
 Lab Storage Container Market | 2026-2036
Lab Storage Container Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Storage Container Market Foresight
Asset-light leasing models for cold-chain storage infrastructure is rewriting competitive entry barriers for mid-tier suppliers. Thermo Fisher Scientific leverages its captive financing arm to bundle equipment leases with consumable contracts across pharmaceutical clients. Corning Incorporated anchors its position through backward integration into borosilicate glass formulation, insulating margin pools from raw material volatility. Sartorius AG competes by specializing in single-use bag assemblies that displace traditional stainless-steel vessels in bioprocessing applications.
Lab storage containers are engineered vessels designed to preserve sample integrity across temperature extremes, pressure differentials, and chemical exposure, typically fabricated from borosilicate glass, fluoropolymer plastics, or austenitic stainless steel with validated seal geometries. Their primary purpose is to prevent contamination, evaporation, and degradation of biological, chemical, or pharmaceutical specimens during handling, transport, and long-term archiving. Plastic vials lead the product type landscape due to disposability trends in clinical diagnostics, while glass bottles sustain premium positioning in analytical reference standard storage where extractables and leachables protocols demand inert surfaces. High-capacity containers represent the fastest-growing capacity tier, driven by bioreactor scale-up and centralized biobanking operations that consolidate specimen volumes.
The FDA enforces container closure integrity testing under sterile drug product guidelines, compelling manufacturers to invest in validated seal technologies and material qualification dossiers. ISO 15378 extends quality management requirements to primary packaging materials for medicinal products, creating a compliance moat that filters out uncertified suppliers. EPA regulations on per- and polyfluoroalkyl substances are forcing material transitions away from certain fluoropolymer liners toward silicone and polypropylene alternatives. Stakeholders must monitor evolving PFAS restrictions and biocompatibility standards to preempt supply disruptions and secure formulary approvals.
Market Dynamics
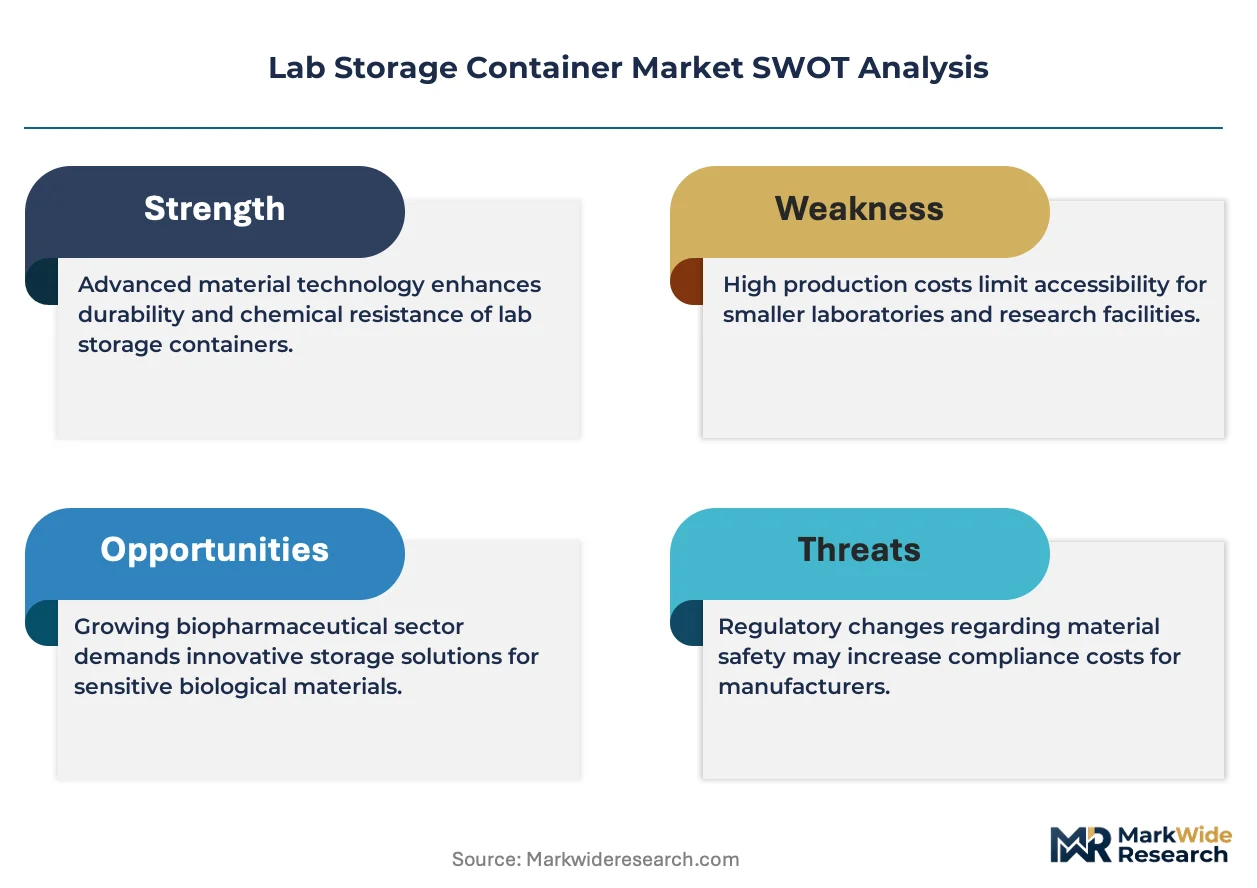
Container closure integrity validation under FDA sterile drug product guidance is forcing material qualification investments that bifurcate supplier tiers between certified and uncertified players.
Growth Catalysts
- Cell therapy bioprocessing:Biotech firms in Boston and San Diego clusters are scaling cryogenic storage infrastructure for autologous cell therapy workflows, pulling demand for high-capacity vessels.
- ISO 15378 certification expansion:Quality management mandates for primary medicinal packaging materials are filtering out uncertified suppliers and consolidating procurement toward qualified vendors.
- Biobank centralization:Consolidated specimen archiving operations are displacing distributed storage models and driving single-site capacity expansion.
Market Restraints
- Borosilicate glass supply concentration:Backward integration by dominant glass formers limits margin flexibility for downstream container fabricators.
- PFAS material transitions:EPA restrictions on per- and polyfluoroalkyl substances are forcing costly reformulation of fluoropolymer liners toward silicone and polypropylene alternatives.
- Stainless steel vessel displacement:Single-use bag assemblies are compressing demand for traditional reusable metal containers in bioprocessing applications.
Strategic Opportunities
- Asset-light leasing penetration:Equipment lease bundling with consumable contracts is opening mid-tier supplier access to pharmaceutical clients previously blocked by capital barriers.
- Extractables and leachables protocols:Analytical reference standard storage is sustaining premium glass bottle positioning against plastic alternatives.
- Biocompatibility standard evolution:Anticipatory compliance with emerging material safety dossiers is creating first-mover advantage in formulary approvals.
Industry Challenges
- Validated seal technology integration:Container closure integrity testing protocols require cross-functional coordination between materials science and quality assurance teams that remains scarce.
- Multi-regulatory dossier harmonization:Divergent FDA, EMA, and NMPA material qualification timelines are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Storage Container Market |
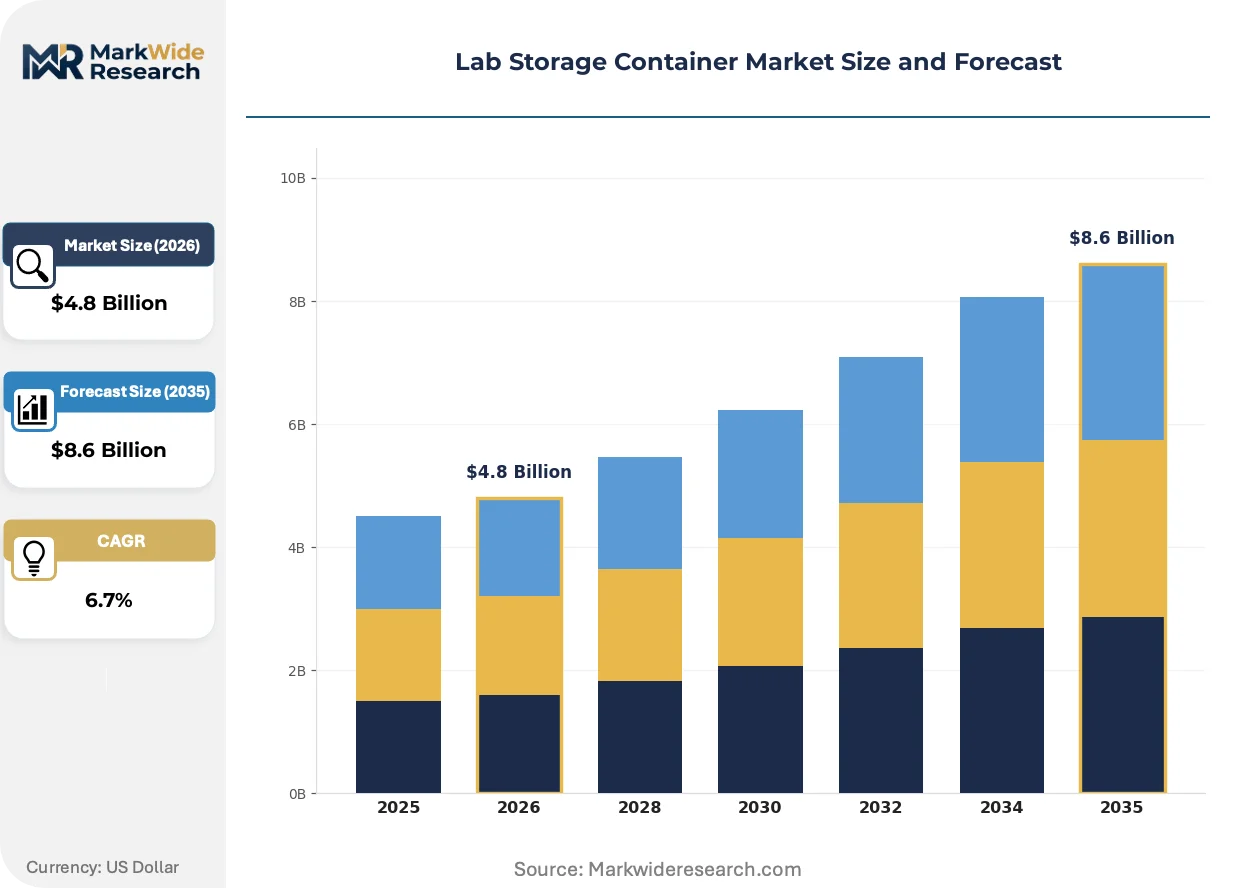
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Bottles, Bags, Containers Material: Plastic, Glass, Metal, Silicone End User: Laboratories, Pharmaceutical Companies, Research Institutes, Biotech Firms Capacity: Low Volume, Medium Volume, High Volume, Custom Size |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, Sartorius AG, Merck KGaA, Eppendorf AG, VWR International, Danaher, Greiner Bio-One International GmbH, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Storage Container Market Shifts & Advancements
Active material science convergence with digital traceability systems is redefining performance benchmarks for specimen integrity assurance across temperature and pressure extremes.
Smart sensor-embedded cryogenic vessels is hybridizing passive thermal protection with real-time condition monitoring. Cell therapy logistics providers are piloting these systems for chain-of-custody verification. The technology is compressing insurance and liability costs while enabling outcome-based service pricing.
EPA PFAS restrictions are accelerating silicone and polypropylene liner substitution in fluoropolymer-dependent applications. Container manufacturers are rebuilding material qualification dossiers from substrate chemistry through seal geometry validation. Glass bottle suppliers serving analytical reference markets face compressed reformulation timelines compared to plastic vial producers.
Pharmaceutical procurement teams are consolidating vendor panels around full-service providers offering equipment leases bundled with consumable contracts. This behavior is displacing discrete equipment and consumable sourcing through separate channels. The pattern concentrates in United States biotech clusters where capital efficiency pressures are most acute.
Lab Storage Container Market Segmentation
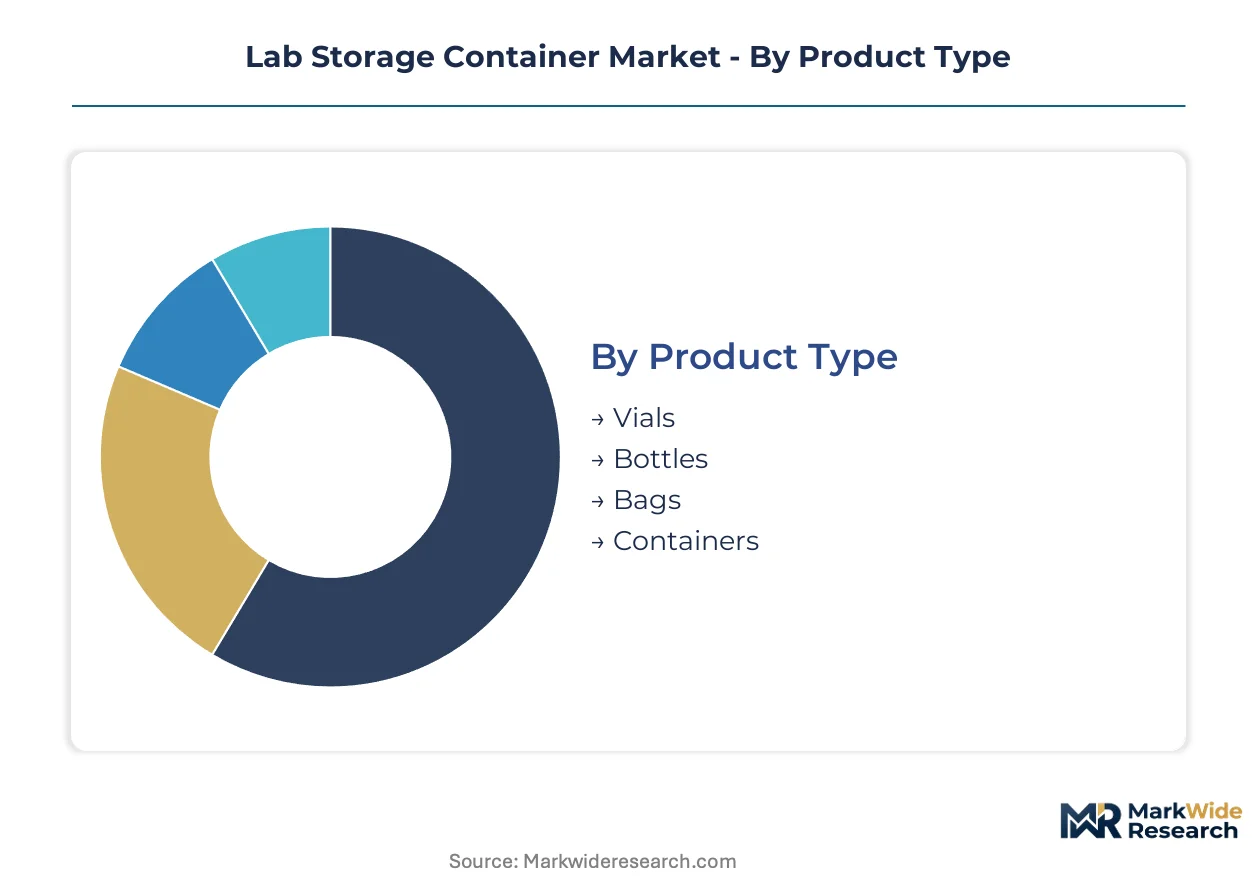
Segmentation in lab storage containers reveals how material science, regulatory compliance, and end-use workflows fragment procurement patterns across the value chain. Container selection hinges on extractables protocols, temperature requirements, and closure integrity standards that vary sharply by application.
Product Type:
Application-specific functional requirements determine which vessel geometries dominate procurement decisions across diagnostic, therapeutic, and research workflows.
- Vials:Small cylindrical vessels with crimp or screw closures, typically 2-20mL capacity, engineered for chromatography autosamplers and clinical diagnostic analyzers. Demand clusters in high-throughput pathology labs across Boston and San Diego where disposability eliminates cross-contamination risks in PCR and immunoassay workflows.
- Bottles:Wide-mouth or narrow-neck vessels from 50mL to 4L, fabricated in amber or clear borosilicate glass for light-sensitive analytical standards. Pharmaceutical quality control labs in Basel and Research Triangle Park specify these for reference material storage where USP <661> extractables testing mandates inert surfaces.
- Bags:Flexible single-use assemblies with welded ports and tubing interfaces, replacing rigid vessels in bioreactor harvest and buffer preparation. Bioprocessing facilities in Singapore and Shanghai deploy these for cell therapy media holds to reduce cleaning validation burdens.
- Containers:Large-format vessels and drums for bulk chemical storage, often with UN-certified closures for hazardous material transport. Chemical synthesis operations in Ludwigshafen and Houston specify these for solvent and reagent warehousing.
Vials command the established base. The steepest expansion runs through bags as single-use bioprocessing displaces stainless steel infrastructure.
Material:
Surface chemistry and thermal stability requirements stratify material selection across temperature extremes and chemical exposure profiles.
- Plastic:Polypropylene and cyclic olefin polymer formulations dominate clinical diagnostics for cost efficiency and disposability. High-throughput screening facilities in Cambridge, Massachusetts specify these for compound library storage where extractables profiles under ISO 10993-18 guide material qualification.
- Glass:Borosilicate and soda-lime compositions sustain premium positioning in analytical reference storage. European pharmacopeia compliance labs in Frankfurt and Milan require Type I borosilicate for parenteral drug product containers where hydrolytic resistance testing under USP <660> applies.
- Metal:Austenitic stainless steel 316L vessels persist in cryogenic dewars and pressure-rated containment. Cell therapy cryopreservation workflows in Gaithersburg and South San Francisco specify these for vapor-phase liquid nitrogen storage of CAR-T starting material.
- Silicone:Platinum-cured elastomer liners and gaskets are displacing fluoropolymer alternatives under EPA PFAS restrictions. Container closure manufacturers in Minnesota and Ohio are rebuilding qualification dossiers for silicone formulations in sterile drug product packaging.
Plastic commands the established base. The steepest expansion runs through silicone as regulatory pressure accelerates material transitions.
End User:
Customer type determines volume scale, certification requirements, and procurement integration depth across the value chain.
- Laboratories:Academic and hospital-based research facilities with fragmented purchasing and instrument-specific consumable needs. Core facilities at Johns Hopkins and Stanford specify vendor-agnostic vial formats to maintain chromatography system interoperability.
- Pharmaceutical Companies:Integrated drug developers with consolidated vendor panels and validated supply agreements. Quality assurance teams at Merck KGaA and Roche enforce ISO 15378 certification for all primary packaging materials in sterile injectable products.
- Research Institutes:Government and nonprofit facilities with grant-funded procurement cycles and biobanking mandates. The UK Biobank and All of Us Research Program specify high-capacity cryogenic containers for longitudinal specimen archiving.
- Biotech Firms:Venture-backed developers with asset-light infrastructure preferences and rapid scale-up timelines. Autologous cell therapy developers in Cambridge and La Jolla lease cryogenic storage systems through bundled equipment-consumable contracts.
Pharmaceutical companies command the established base. The steepest expansion runs through biotech firms as cell therapy commercialization accelerates infrastructure deployment.
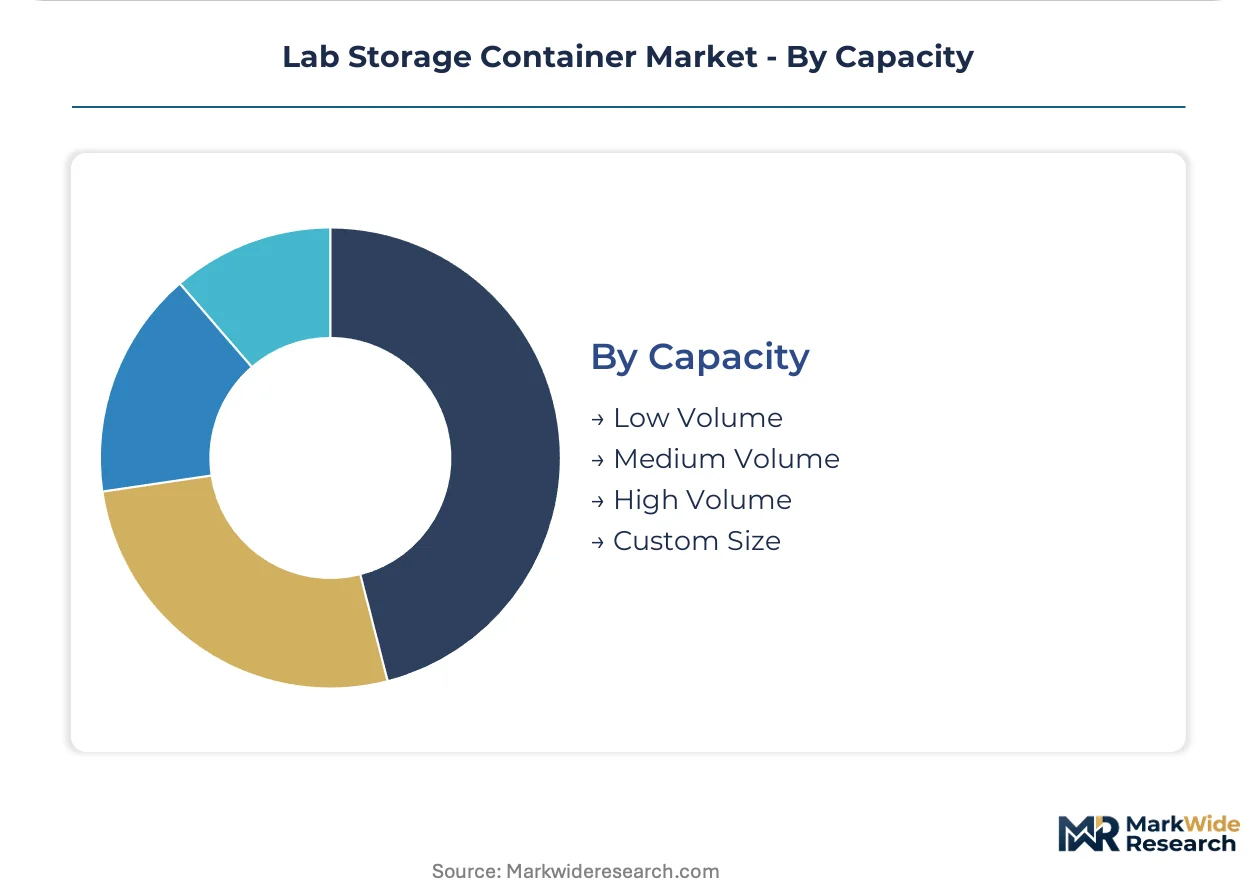
Capacity:
Volume tier selection reflects consolidation trends in biobanking and scale-up dynamics in bioprocessing workflows.
- Low Volume:Sub-5mL vessels for analytical samples, diagnostic specimens, and compound screening libraries. Clinical labs in Indianapolis and Copenhagen specify these for automated liquid handling compatibility in high-throughput screening.
- Medium Volume:5-500mL range for buffer preparation, cell culture media, and intermediate product holds. Contract manufacturing organizations in North Carolina and Switzerland standardize on these for batch flexibility in multi-product facilities.
- High Volume:Above 500mL to 50L+ for bioreactor harvest, bulk drug substance, and centralized biobank consolidation. Cell therapy manufacturers in Massachusetts and California deploy these for autologous product cryopreservation at commercial scale.
- Custom Size:Engineered-to-order vessels for specialized geometries, port configurations, or integration with proprietary equipment. Gene therapy developers in Philadelphia and Amsterdam specify these for viral vector production systems with non-standard vessel interfaces.
Medium volume commands the established base. The steepest expansion runs through high volume as bioreactor scale-up and biobank centralization concentrate specimen storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States biotech clusters while European suppliers absorb margin compression from REACH compliance costs. German glass formers command raw material premiums that downstream fabricators in Southern Europe cannot pass through. Asian manufacturers leverage polypropylene scale to undercut Western producers in clinical diagnostics procurement.
United States
Cell therapy commercialization in Massachusetts and California drives cryogenic vessel procurement at commercial scale. FDA container closure integrity guidance tightens material qualification timelines for sterile drug product packaging. The Boston-Cambridge corridor hosts over 1,000 biotech firms consolidating vendor panels around ISO 15378-certified suppliers.
Germany
Pharmaceutical quality control labs in Frankfurt and Basel-border facilities sustain premium glass bottle demand for analytical reference storage. ECHA REACH regulations on borosilicate glass extractables extend qualification dossier requirements. Baden-Württemberg specialty chemical producers specify UN-certified bulk containers for solvent warehousing and hazardous material transport.
China
Bioprocessing scale-up in Shanghai and Suzhou pulls single-use bag assembly demand for cell therapy media holds. NMPA alignment with ICH Q3D guidelines on elemental impurities tightens material safety dossiers. The Yangtze River Delta concentrates domestic polypropylene vial manufacturing for clinical diagnostics export markets.
Switzerland
Pharmaceutical packaging material suppliers serving Roche and Novartis procurement networks face Swissmedic quality system audits. The country's national pharmaceutical regulator enforces ISO 15378 certification parity with FDA and EMA standards. Basel-region quality control labs specify Type I borosilicate for parenteral drug product containers under USP hydrolytic resistance protocols.
Japan
PMDA biocompatibility standards for primary packaging materials accelerate silicone liner substitution away from fluoropolymer alternatives. METI industrial policy supports domestic cryogenic equipment manufacturing for cell therapy logistics. Osaka-based pharmaceutical quality labs drive amber glass bottle procurement for light-sensitive analytical standards storage.
Lab Storage Container Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and closure technology. The supplier base stratifies into three tiers: full-service providers bundling equipment leases with consumable contracts, material-centric fabricators with backward integration into substrate production, and specialized single-use assembly producers displacing traditional stainless-steel vessels. Consolidation pressure runs through ISO 15378 certification requirements that filter uncertified players. Dominant competitive moves include captive financing arms for lease bundling and in-house production of borosilicate glass to insulate margin pools from raw material volatility.
Among the named players, Thermo Fisher Scientific exemplifies the platform integrator archetype through its captive financing capabilities. Corning Incorporated anchors the material-centric tier with upstream control over borosilicate glass formulation. Sartorius AG occupies a position within the single-use specialization vector, representing the assembly producers displacing reusable metal infrastructure in bioprocessing workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| Sartorius AG |
| Merck KGaA |
| Eppendorf AG |
| VWR International |
| Danaher |
| Greiner Bio-One International GmbH |
| Hamilton Company |
| Others |
Supply & Pricing Matrix
Single-source dependency on German borosilicate glass formers determines both pricing tier spreads and supply chain shape, compressing margin flexibility for downstream container fabricators while amplifying premiums for backward-integrated suppliers. FDA container closure integrity mandates and EPA PFAS restrictions are forcing parallel investments in material qualification dossiers and silicone liner reformulation, widening the cost gap between certified and uncertified supplier tiers.
Pricing Analysis
Pharmaceutical quality assurance buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 15378 certification and USP extractables compliance as primary differentiation drivers. Pricing pressure stems from biotech procurement teams consolidating vendor panels around bundled equipment-consumable contracts that compress discrete component margins. Contract manufacturing organizations exhibit highest price sensitivity due to multi-product facility economics, while cell therapy developers prioritize validated supply agreements over unit cost.
Supply Chain Analysis
Extended payment terms from captive financing arms at platform integrators are reshaping working capital requirements for mid-tier suppliers competing against lease-bundled offerings. Raw material supply concentrates in Germany for borosilicate glass, China for polypropylene resin, and the United States for platinum-cured silicone formulations. Distribution runs through pharmaceutical procurement consortiums in Boston and San Diego that enforce ISO 15378 qualification as a gating requirement, creating structural vulnerability for uncertified fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy commercialization represents a high-growth disruption vector, with autologous therapy workflows forcing infrastructure buildouts that favor qualified suppliers with cryogenic vessel portfolios and validated seal technologies.
For Market Incumbents: Insulate margin pools through captive supply of borosilicate glass substrate and accelerated ISO 15378 certification expansion to filter emerging competitors. Defensive consolidation should prioritize single-use bag assembly capabilities to offset stainless steel vessel displacement in bioprocessing applications, while financing arm leverage locks in pharmaceutical client relationships against lease-bundled entrants.
For New Entrants and Emerging Players: Establish a beachhead in silicone liner manufacturing for sterile drug product packaging, where EPA PFAS restrictions are forcing urgent material transitions and incumbent qualification timelines create temporary supply gaps. Target mid-tier contract manufacturing organizations in North Carolina and Switzerland with vendor-agnostic medium-volume vessel offerings that bypass consolidated pharmaceutical procurement panels.
For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors platform integrators with captive financing and backward-integrated material control over pure-play component suppliers. Long-term viability centers on full-service providers bundling equipment leases with consumable contracts; monitor NMPA alignment with ICH Q3D guidelines as a signal for Chinese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Expansion | Filters uncertified competitors and consolidates procurement toward qualified vendors in pharmaceutical quality assurance. |
| Silicone Liner Reformulation | Rebuilds material qualification dossiers under EPA PFAS restrictions for sterile drug product container closure systems. |
| Asset-Light Leasing Penetration | Opens mid-tier supplier access to biotech clients through bundled equipment-consumable contracts. |
| Backward Integration into Borosilicate Glass | Insulates margin pools from raw material volatility and German supply concentration. |
| Smart Sensor-Embedded Cryogenic Vessels | Enables real-time chain-of-custody verification for cell therapy logistics providers. |
Research Methodology
Initial hypotheses were tested against primary input from bioprocessing facility directors, pharmaceutical quality assurance managers, regulatory affairs specialists, and laboratory procurement officers, then refined through secondary validation against FDA guidance documents, EMA submissions, ISO certification registries, and SEC filings from disclosed market participants. Bottom-up vessel demand modeling triangulated against top-down market sizing across material, product type, and end-user segments.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning plastic-glass-metal-silicone materials, vial-bottle-bag-container geometries, and laboratory-pharmaceutical-biotech end-user archetypes. CAGRs derived from shipment volume trajectories and average selling price evolution incorporated cell therapy infrastructure deployment timelines and biobank centralization patterns as industry-specific forecast inputs.
Sensitivities concentrate around EPA PFAS restriction implementation pace, NMPA-ICH Q3D alignment timelines, and biotech venture funding availability for infrastructure buildouts. Forecasts reflect assumptions regarding regulatory harmonization and material substitution economics; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stackable Container Market
Containers
Hinged Lid Tins Market
Containers
Foldable Large Containers Market
Containers
Bulk Containers Market
Containers
Car Lube Container Market
Containers
Jars Market
Containers
Oblong Jar Market
Containers
Slip Lid Can Market
Containers
Metal Cans and Glass Jars Market
Containers
Intermediate Bulk Container Liner Market
Containers
Water Resistant Packing Cubes Market
Containers
Jerry Cans Market
Containers
Canning Jars Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Concentrate Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market