
 Cans Market | 2026-2036
Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Cans Market Outlook
Capital-intensity divergence between integrated smelter-to-can plants and toll-coating dependent operators is collapsing as energy hedging costs erode the historic advantage of backward-linked producers. Ball Corporation leverages captive aluminum supply to sustain margin stability across North American beverage contracts. Crown Holdings Inc. anchors its position through geographic dominance in European food canning, while Ardagh Group S.A. differentiates via specialized two-piece aluminum designs for carbonated drinks.
Cans are cylindrical metal containers formed from aluminum or steel sheet, typically featuring a drawn-and-ironed body with a separate seamed end, designed to preserve contents through hermetic sealing against oxygen and light ingress. The manufacturing process involves cupping, redrawing, ironing, and necking to achieve wall thickness below 0.1mm for material efficiency. Aluminum cans lead beverage applications due to infinite recyclability and lightweight logistics, while steel cans retain structural primacy in retorted food segments where thermal processing demands higher wall strength. Compostable cans represent an emerging niche as bio-polymer barriers advance, though current capacity constraints limit penetration beyond premium positioning.
EPA guidelines on volatile organic compound emissions from can coating operations constrain solvent-based interior lining formulations, while FDA food-contact substance notifications govern epoxy-phenolic and polyester coatings for acidic beverages. BIS certification requirements in India and GB standards in China add compliance layers for exporters targeting Asia-Pacific procurement contracts. Stakeholders must monitor evolving extended producer responsibility frameworks as deposit-return schemes expand across jurisdictions, reshaping collection infrastructure economics and brand packaging commitments.
Market Dynamics
Aluminum sheet supply concentration in Gulf Coast smelter clusters is forcing beverage can makers to renegotiate toll-coating contracts and absorb energy-linked price volatility previously borne by upstream suppliers.
Growth Catalysts
- EU REACH compliance:Tightened chemical disclosure requirements for interior can coatings are accelerating migration from epoxy-phenolic to polyester-based formulations, expanding specialty coating capacity.
- Beverage brand plastic exit:Coca-Cola, PepsiCo, and AB InBev procurement mandates are redirecting volume toward aluminum two-piece designs across North American and European filling operations.
- German canning infrastructure:Central European distribution networks anchored in Bavaria and North Rhine-Westphalia concentrate demand for high-speed aluminum lines serving carbonated and still drinks.
Market Restraints
- Aluminum ingot cost volatility:LME price swings and Midwest premiums compress margin stability for toll-dependent can manufacturers without captive smelter supply.
- Coating formulation constraints:EPA volatile organic compound emission limits restrict solvent-based interior lining chemistries, extending R&D timelines for compliant alternatives.
- Steel can substitution ceiling:Retorted food segments requiring thermal wall strength above 0.15mm resist aluminum conversion, preserving steel's structural primacy in vegetable and protein canning.
Strategic Opportunities
- India BIS certification pathway:Exporters establishing GB-standard-compliant production for China can leverage overlapping technical specifications to penetrate Indian beverage procurement contracts.
- Compostable barrier convergence:Bio-polymer lining advances combined with fiber body forming create premium positioning for single-serve beverage cans in Nordic deposit-return markets.
- Deposit-return scheme expansion:Extended producer responsibility frameworks in Germany, Sweden, and the Netherlands reshape collection infrastructure economics, favoring aluminum's infinite recyclability narrative.
Industry Challenges
- Thin-wall drawing expertise:Achieving sub-0.1mm body thickness for material efficiency requires precision redrawing and ironing skills concentrated among German and Japanese equipment specialists.
- Coating cure line capex:Converting solvent-based to water-based or UV-cured interior lining systems demands furnace and spray-booth replacement running into nine-figure investments per plant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cans Market |
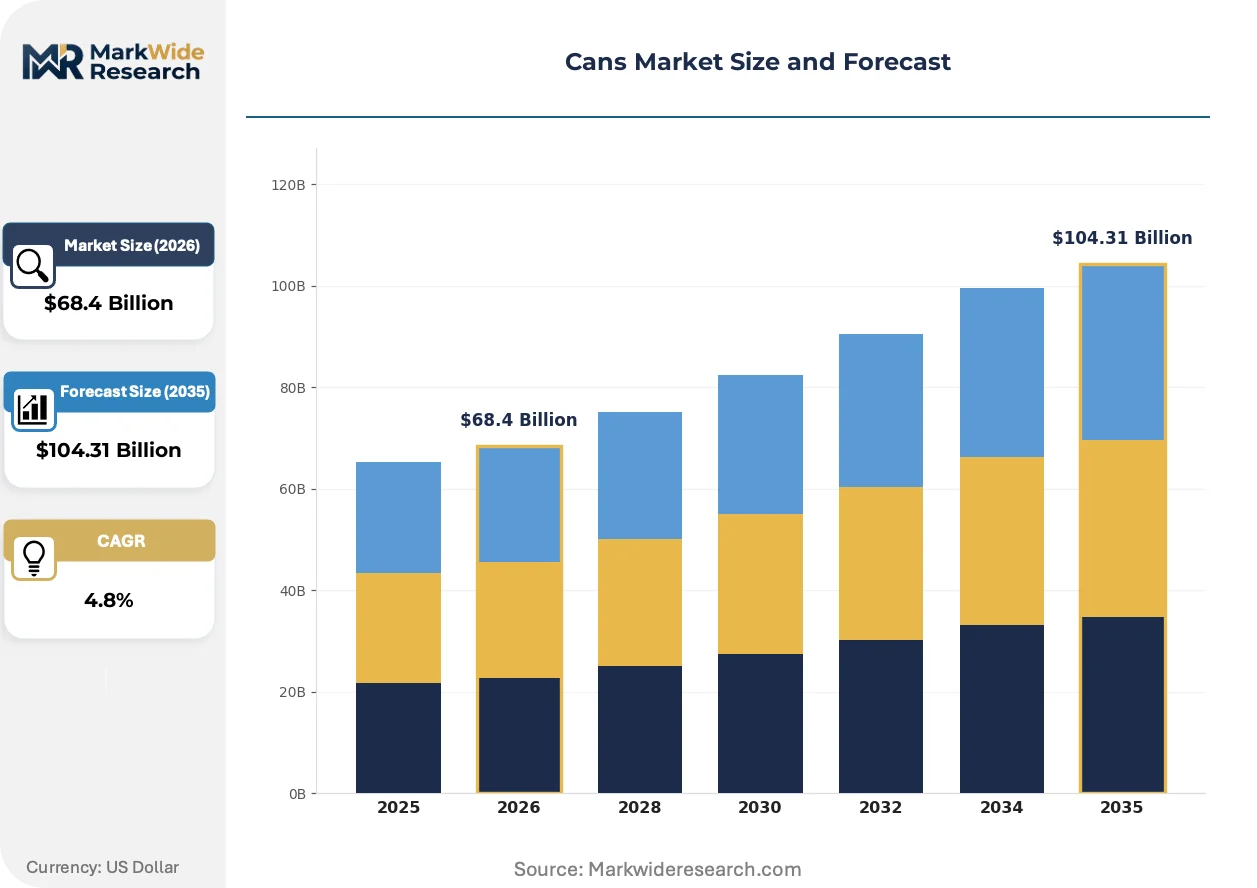
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Compostable Cans, Glass-Lined Cans End User: Food Industry, Beverage Manufacturers, Chemical Companies, Household Products Capacity: 250ml, 500ml, 1L, 2L Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Convenience Stores |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Ardagh Group S.A., Silgan Holdings Inc., CAN-PACK S.A., Toyo Seikan Group Holdings Ltd., CPMC Holdings Limited, Kian Joo Can Factory Berhad, Universal Can Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cans Market Strategic Shifts
Digital printing and smart packaging integration are collapsing minimum order quantities and enabling batch-level traceability, rewiring how beverage brands manage seasonal SKU proliferation and supply chain transparency.
Digital direct-to-can printing is bifurcating the decoration supply chain. Craft breweries and energy drink startups adopt inkjet and electrophotographic systems for 5,000-unit runs with variable graphics. This technology compresses lead times from six weeks to 72 hours, enabling market testing without cylinder engraving costs and fragmenting volume away from traditional offset-litho decorators.
EU F-Gas Regulation phase-down schedules are tightening specifications for can manufacturing equipment refrigerants and compressed gas systems. Industrial consequence includes accelerated retrofit of pneumatic forming presses and cold-end spray systems. German and Austrian canning line OEMs are most affected, responding with CO2-based cooling alternatives and hydrocarbon-blown coating cure processes.
Brand procurement committees now mandate aluminum provenance documentation and recycled-content certificates as standard RFQ line items. This specification shift disrupts spot-market aluminum purchasing and replaces it with multi-year tolling agreements tied to specific smelter pools. The practice is most visible in Nordic markets where deposit-return transparency requirements and consumer-facing sustainability reporting create audit-trail pressure.
Cans Market Segmentation
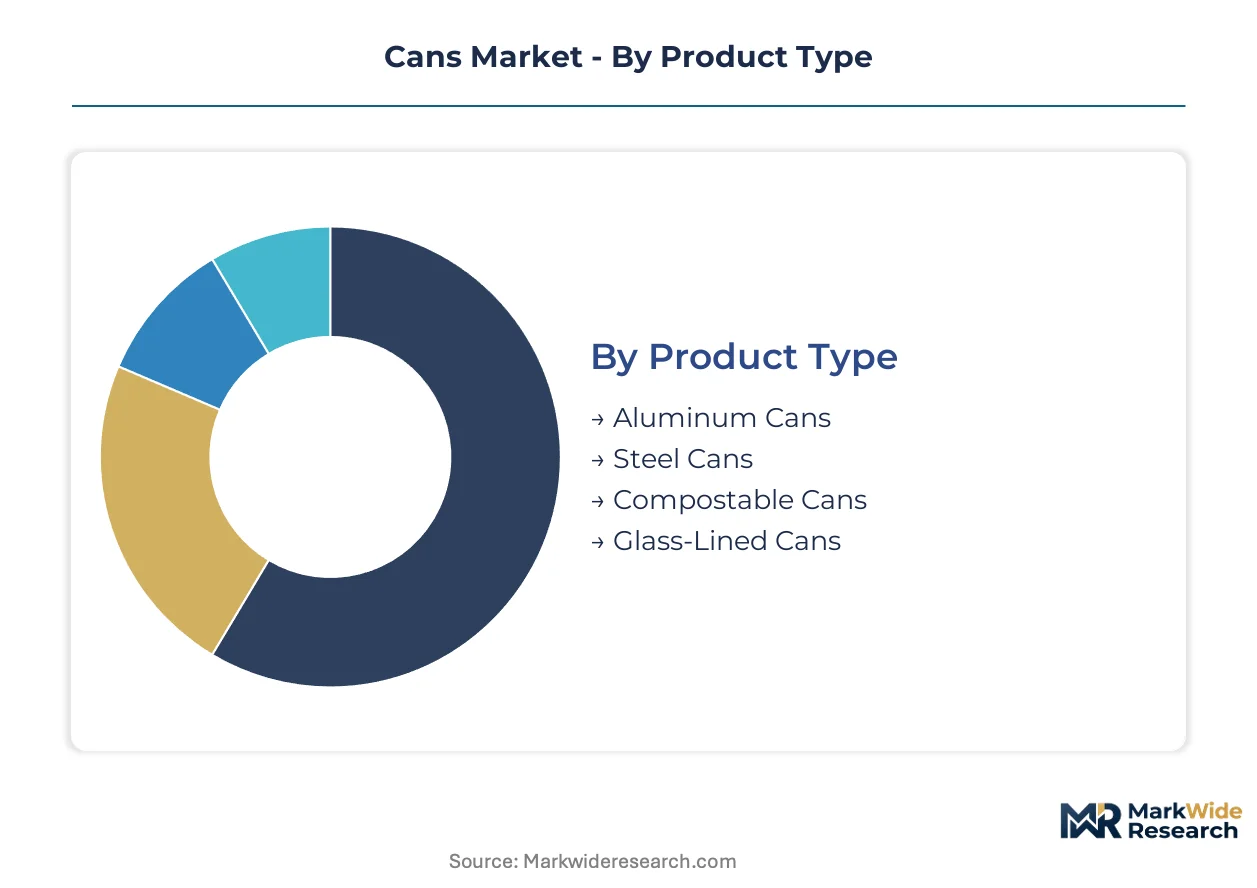
Segmentation in the Cans Market reveals divergent growth trajectories across material technologies and procurement channels. Aluminum and steel formats serve fundamentally different thermal and logistics requirements, while capacity and distribution choices reflect beverage brand SKU proliferation versus food processor bulk contracting patterns.
Product Type:
Domestic production concentrates aluminum and steel canning lines in Germany, the US, and China, while compostable and glass-lined formats remain export-dependent specialty niches from Nordic and Japanese suppliers.
- Aluminum Cans:Drawn-and-ironed two-piece construction achieves sub-0.1mm wall thickness for carbonated beverages. Demand concentrates with Coca-Cola, PepsiCo, and AB InBev procurement mandates shifting volume from plastic across North American and European filling operations.
- Steel Cans:Three-piece welded construction with tinplate or TFS substrate withstands retort thermal processing above 121°C. Food canning in Germany, France, and Italy preserves steel's structural primacy where wall strength requirements exceed 0.15mm.
- Compostable Cans:Bio-polymer barriers on fiber bodies from Nordic suppliers serve premium single-serve positioning in Swedish and German deposit-return markets.
- Glass-Lined Cans:Interior silica-based coating prevents metal-ion migration for acidic chemical and specialty beverage applications from Japanese producers.
Aluminum Cans holds the largest share; momentum sits with Compostable Cans in premium Nordic positioning.
End User:
Cost tier differentiation separates high-volume beverage contracts with multi-year tolling agreements from food processor spot purchasing and chemical company specification-driven procurement.
- Food Industry:Vegetable, protein, and ready-meal canning demands retort-compatible steel formats with epoxy-phenolic or polyester interior linings compliant with FDA and EFSA food-contact notifications.
- Beverage Manufacturers:Carbonated soft drinks, beer, and energy drinks drive aluminum two-piece volume with infinite recyclability credentials for EU Green Deal alignment.
- Chemical Companies:Paints, coatings, and aerosol formulations require UN-certified pressure-rated steel or aluminum monobloc construction with corrosion-resistant interior treatments.
- Household Products:Cleaning and personal care aerosols utilize aluminum monobloc or steel three-piece formats with hydrocarbon or compressed gas propellant compatibility.
Beverage Manufacturers commands volume leadership; Food Industry maintains the steadiest contract visibility.
Capacity:
Volume concentration patterns show 500ml standardization in European retail, 250ml premium single-serve expansion in Asian markets, and 2L bulk formats for food service and institutional procurement.
- 250ml:Slim-profile aluminum designs serve energy drinks and premium spirits in Japanese and South Korean convenience retail with higher per-unit margin extraction.
- 500ml:Standard beverage can format dominates German, US, and Brazilian filling lines with optimized palletization and logistics efficiency.
- 1L:Large-format aluminum and steel designs address family-size beverage and cooking sauce segments in Mexican and Indonesian retail channels.
- 2L:Bulk food service and institutional formats for vegetable oils, fruit juices, and industrial chemicals concentrate in Chinese and Indian manufacturing.
500ml holds the largest share; 250ml is climbing the fastest on premium single-serve positioning.
Distribution Channel:
Customer type fragmentation separates direct procurement by multinational beverage brands from wholesale distributor intermediation serving regional food processors and convenience store chain consolidation.
- Online Retail:Direct-to-consumer craft beverage and specialty food sales enable 5,000-unit digital direct-to-can printing runs with 72-hour lead times.
- Supermarkets:Hypermarket and grocery chain private-label contracting drives standardized 500ml aluminum volume with recycled-content certification requirements.
- Wholesale Distributors:Industrial and food service bulk procurement concentrates 1L and 2L formats with pallet-level traceability mandates.
- Convenience Stores:Impulse-oriented 250ml and 500ml single-serve placement in German, Japanese, and US urban retail with chilled supply chain requirements.
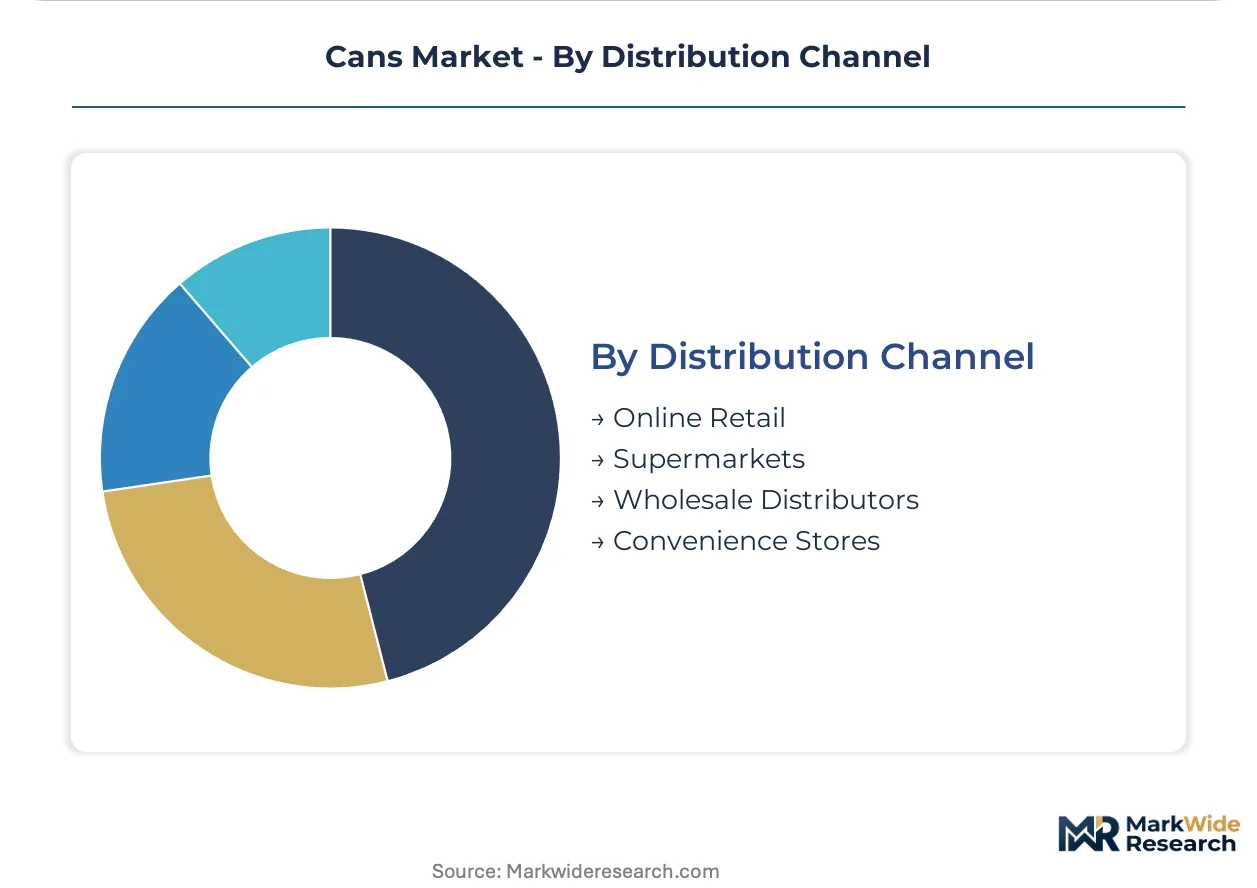
Supermarkets holds the largest share; Online Retail is gaining share fastest on digital printing enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage procurement committees in Germany demonstrate the lowest price elasticity as sustainability premiums override commodity swings, while Indian food processors exhibit acute sensitivity to aluminum ingot volatility.
United States
Midwest beverage can demand concentrates around Chicago and Milwaukee filling corridors serving Coca-Cola and PepsiCo distribution networks. EPA volatile organic compound emission limits from coating operations constrain solvent-based interior lining formulations at Ohio and Colorado plants. Gulf Coast aluminum smelter clusters in Texas and Louisiana force toll-dependent manufacturers to absorb energy-linked price swings previously borne by upstream suppliers.
Germany
Bavarian and North Rhine-Westphalian canning lines anchor Central European beverage distribution with high-speed aluminum output for carbonated and still drinks. EU F-Gas Regulation phase-down schedules accelerate retrofit of pneumatic forming presses at Stuttgart and Munich equipment OEMs. Deposit-return scheme expansion across federal states reshapes collection infrastructure economics, favoring aluminum's infinite recyclability credentials in Berlin and Hamburg retail channels.
China
Yangtze River Delta and Pearl River Delta manufacturing bases supply 2L bulk formats for food service and institutional procurement across domestic and Southeast Asian markets. GB standards and MIIT dual carbon goals add compliance layers for exporters targeting beverage procurement contracts. Shandong Peninsula steel canning capacity serves retorted food segments where thermal wall strength requirements preserve structural primacy.
India
Maharashtra and Gujarat beverage filling operations drive aluminum two-piece demand amid AB InBev and domestic brand procurement mandates shifting from plastic. BIS certification requirements and FSSAI food-contact substance notifications constrain epoxy-phenolic coating imports. Haryana and Delhi-NCR distribution networks concentrate 500ml standardized volume for modern retail and convenience store chains.
Brazil
São Paulo and Minas Gerais aluminum canning corridors serve carbonated soft drink and beer volume with recycled-content certification requirements from multinational brand procurement committees. ANVISA pharmaceutical and food-contact regulations govern interior lining formulations for acidic beverage applications. Rio Grande do Sul steel food canning maintains retort-compatible formats for vegetable and protein segments where wall strength exceeds 0.15mm.
Cans Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Cans Market. Ball Corporation and Crown Holdings Inc. anchor the upper tier through captive aluminum supply and geographic dominance respectively, while toll-coating dependent operators compete on digital printing agility and specialty coating capacity. Three archetypes define competitive positioning: integrated smelter-to-can producers, toll-coating specialists with thin-wall drawing expertise, and regional fabricators serving food canning niches. Capacity expansion and backward integration into aluminum sheet supply represent the dominant competitive moves as energy hedging costs erode historic advantages.
Among North American integrated producers, Ball Corporation exemplifies the captive supply archetype through its smelter-linked tolling agreements, while Crown Holdings Inc. occupies a position within the geographic dominance tier through its European food canning concentration. Ardagh Group S.A. sits within the specialty design tier, representing differentiated two-piece aluminum positioning for carbonated beverage applications. These three entities collectively illustrate how procurement committee mandates for provenance documentation and recycled-content certificates are replacing spot-market purchasing with multi-year supply agreements.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Ardagh Group S.A. |
| Silgan Holdings Inc. |
| CAN-PACK S.A. |
| Toyo Seikan Group Holdings Ltd. |
| CPMC Holdings Limited |
| Kian Joo Can Factory Berhad |
| Universal Can Corporation |
| Others |
Value Chain & Pricing Dynamics
Six-week cylinder engraving lead times for traditional offset-litho decoration anchor pricing power with integrated decorators, while 72-hour digital direct-to-can turnaround collapses minimum order quantities and fragments volume toward agile toll-coating specialists. This lead-time compression concentrates buyer leverage with beverage brands managing seasonal SKU proliferation, reshaping how procurement committees negotiate multi-year tolling agreements versus spot aluminum sheet purchases.
Pricing Analysis
After-sales coating cure line service contracts and extended maintenance agreements drive lifetime value for can manufacturing equipment OEMs. Three-tier pricing structure across premium, standard, and economy levels separates German thin-wall drawing specialists from toll-coating dependent operators and regional fabricators. Cost compression in standard aluminum two-piece beverage cans intensifies because Gulf Coast smelter energy hedging costs erode backward-linked producer advantages. Food processors exhibit acute price sensitivity to aluminum ingot volatility, while German beverage procurement committees demonstrate the lowest elasticity as sustainability premiums override commodity swings.
Supply Chain Analysis
Gulf Coast aluminum smelter clusters in Texas and Louisiana create a chokepoint that forces toll-dependent can manufacturers to absorb energy-linked price swings previously borne by upstream suppliers. Primary aluminum supply concentrates in Canada, Russia, and Australia, while can sheet rolling capacity clusters in Germany, China, and the United States. Raw material procurement draws from bauxite mining, alumina refining, and primary smelting operations tethered to LME pricing mechanisms. Single-source vulnerability runs through Midwest premium negotiations between beverage can makers and smelter-linked tolling agreements. Distribution runs through direct procurement by multinational beverage brands, wholesale distributor intermediation serving regional food processors, and online retail channels enabling craft brewery fragment orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cans Market represents an early-cycle expansion story as beverage brand plastic exit mandates accelerate aluminum two-piece procurement across North American and European filling operations. This adoption tailwind concentrates demand with deposit-return scheme expansion reshaping collection infrastructure economics in favor of infinite recyclability credentials.
For Market Incumbents: Consolidate coating formulation capacity by converting solvent-based interior lining systems to EPA-compliant water-based or UV-cured alternatives at Ohio and Colorado plants. Add thin-wall drawing expertise through equipment partnerships with German and Japanese specialists to defend against toll-coating specialists fragmenting volume on digital printing agility. Backward integration into aluminum sheet supply via captive smelter tolling agreements mitigates LME price swing exposure. For New Entrants and Emerging Players: Differentiate on compostable barrier convergence for premium single-serve positioning in Swedish and German deposit-return markets where bio-polymer lining advances create white-space above commodity aluminum. Target India's BIS certification pathway by establishing GB-standard-compliant production for China and leveraging overlapping technical specifications to penetrate Maharashtra and Gujarat beverage procurement contracts. Lead with 5,000-unit digital direct-to-can printing runs for craft breweries and energy drink startups seeking 72-hour lead times. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-infrastructure play because extended producer responsibility frameworks and deposit-return scheme expansion create structural demand for aluminum's infinite recyclability narrative. Acquisition targets should prioritize toll-coating specialists with thin-wall drawing expertise and digital printing capability in Nordic or German geographies. Watch for inflection when EU F-Gas Regulation phase-down schedules accelerate retrofit demand at Stuttgart and Munich equipment OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sheet Supply | Captive smelter tolling agreements with Gulf Coast clusters insulate margin stability from LME volatility. |
| Coating Formulation Conversion | EPA-compliant water-based interior lining systems at Ohio plants satisfy volatile organic compound emission limits. |
| Digital Direct-to-Can Printing Deployment | Inkjet and electrophotographic systems compress craft brewery lead times from six weeks to 72 hours. |
| Thin-Wall Drawing Expertise Acquisition | Precision redrawing and ironing skills from German equipment specialists enable sub-0.1mm body thickness. |
| Deposit-Return Scheme Infrastructure Alignment | Collection economics in Berlin and Hamburg retail channels favor aluminum's infinite recyclability credentials. |
Study Parameters
Operator-level perspectives from can manufacturing plant managers, beverage brand procurement committees, coating formulation R&D directors, and aluminum smelter tolling agreement specialists anchored the qualitative base for this study. Primary interview findings combined with secondary validation from SEC 10-K filings, customs and trade data, EPA emission disclosure records, and EU REACH compliance documentation. Bottom-up volume modeling across material technologies and procurement channels triangulated with top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness across aluminum ingot price volatility scenarios, EU F-Gas Regulation implementation timelines, and deposit-return scheme expansion rates over the projection horizon. Segmentation dimensions modeled include material format, end-user industry, capacity tier, and distribution channel, with additional granularity on coating formulation chemistry and recycled-content certification status. CAGRs derived from historical volume trajectories, procurement committee mandate timing, and smelter capacity expansion announcements.
Decision-makers should treat outputs as directional under sustained beverage brand plastic exit commitments and stable EU regulatory enforcement; material deviation in aluminum price volatility or coating compliance timelines would warrant model refresh. Practitioners should keep alternative scenarios live as BIS certification requirements in India and GB standard evolution in China reshape export pathway economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Latin America Food Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Metal Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
South Africa Metal Packaging Market