
 In-Mold Labelled Containers Market | 2026-2036
In-Mold Labelled Containers Market Size, Share, and Industry Trends Forecast 2026-2036
In-Mold Labelled Containers Market Analytics
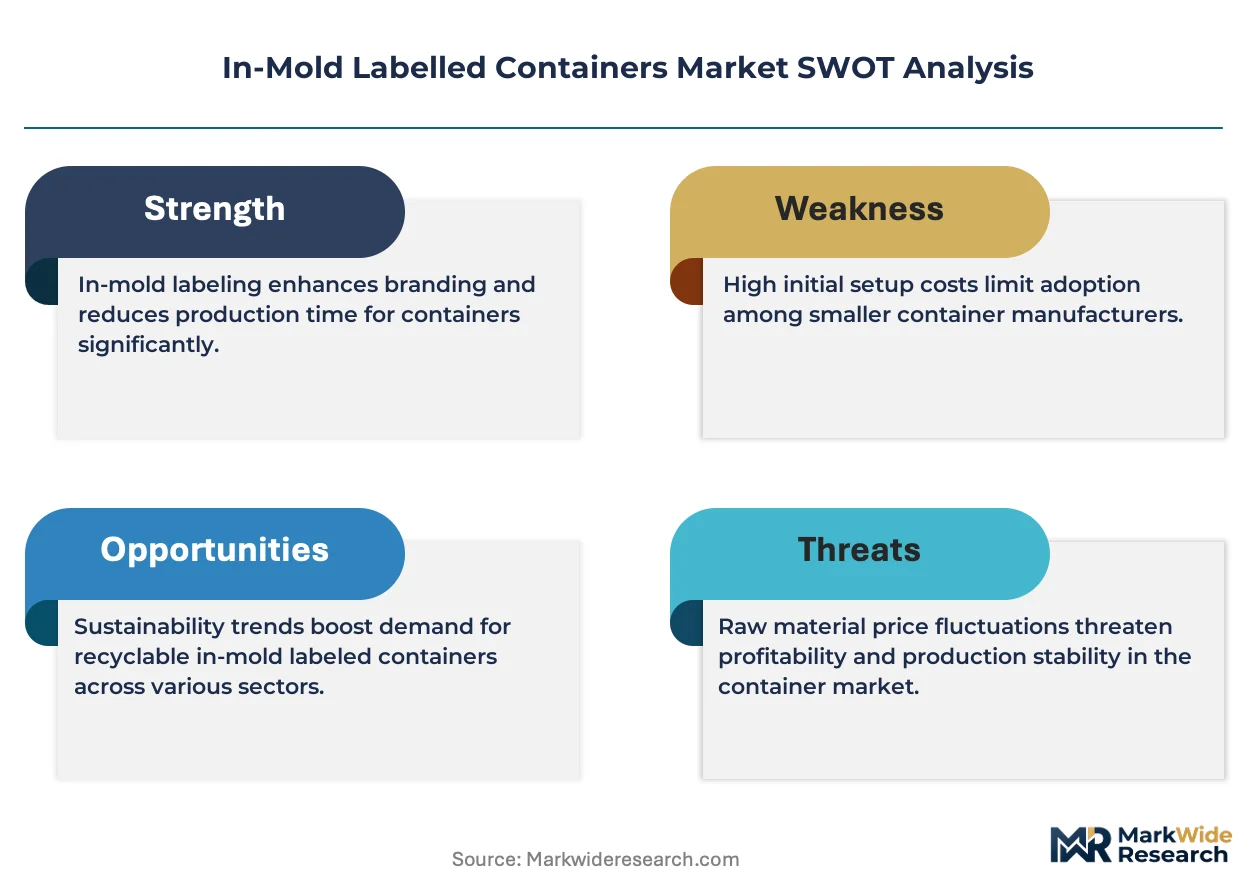
Asset-light leasing models for high-performance printing presses is narrowing the capital barrier for mid-tier decorators entering in-mold label supply. Multi-Color Corporation leverages its North American plant network to sustain regional fulfillment density. CCL Industries anchors European demand through dedicated blow-moulded container lines. Constantia Flexibles competes via backward integration into film substrates, controlling cost volatility.
In-mold labelled containers are polymer vessels where pre-printed polypropylene or polystyrene labels fuse with molten resin during blow moulding or injection moulding, creating permanent, scratch-resistant graphics without post-mould adhesives. This integration delivers chemical resistance and 360-degree branding for products requiring repeated handling or refrigeration exposure. Blow moulded containers dominate beverage applications due to process compatibility with HDPE and PET stretch ratios. Injection moulded formats command premium positioning in personal care where wall-thickness precision and thread-definition tolerances matter. Polypropylene material grades are capturing share from polystyrene as recyclability protocols harden across European sorting infrastructure.
The US FDA maintains indirect food-contact clearance pathways for in-mold label adhesives and substrates under 21 CFR 177, while the EU's REACH framework governs SVHC disclosure for label inks migrating into food simulants. Germany's national packaging ordinance, enforced by the Central Agency Packaging Register, mandates minimum recycled content thresholds that reshape material procurement for export-bound suppliers. Stakeholders must monitor how California's SB 54 implementation timeline interacts with federal preemption debates to determine whether dual compliance systems or unified standards emerge.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing material choices across the value chain, forcing converters to requalify polypropylene grades and triggering migration from polystyrene in blow-moulded beverage formats.
Growth Catalysts
- Quick-service restaurant chains:Food packaging standardization at scale drives demand for 360-degree branding on disposable containers with refrigeration durability.
- REACH SVHC disclosure protocols:Chemical transparency mandates accelerate adoption of pre-qualified in-mold label substrates that preempt regulatory scrutiny.
- Digital printing integration:High-definition inkjet systems reduce minimum order quantities, enabling shorter runs for regional beverage launches.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings compress converter margins and complicate long-term contract pricing with brand owners.
- German precision manufacturing concentration:Stuttgart and Munich corridor dominance creates geographic supply risk for export-dependent decorators.
- California SB 54 uncertainty:Extended producer responsibility implementation timeline clashes with federal preemption debates, generating compliance ambiguity.
Strategic Opportunities
- Asset-light press leasing:Mid-tier decorators bypass capital barriers through performance-based equipment financing models.
- Personal care injection moulding:Premium wall-thickness precision requirements open margin-rich positioning for thread-definition specialists.
- EU Green Deal packaging targets:Recycled content mandates create pull for backward-integrated film substrate suppliers with certified circular streams.
Industry Challenges
- Multi-material sorting infrastructure gaps:European recycling facilities struggle to separate fused label-resin combinations, threatening circularity claims.
- Food-contact adhesive requalification:FDA 21 CFR 177 pathway updates demand extensive migration testing timelines for new substrate-adhesive pairings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Mold Labelled Containers Market |
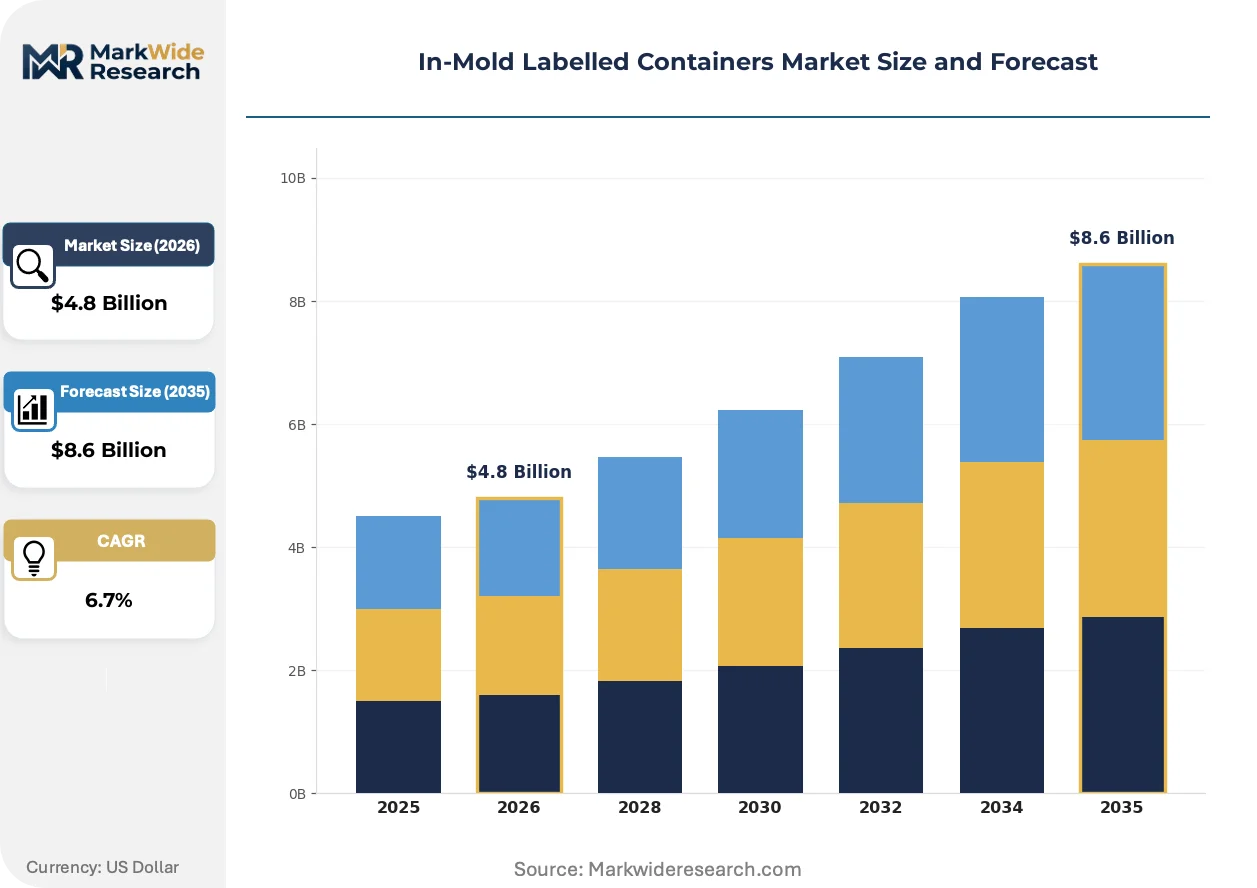
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Moulded, Injection Moulded, Thermoformed, Extruded Material: Polyethylene, Polypropylene, Polystyrene, PET Application: Food Packaging, Beverage Containers, Personal Care, Household Products End User: Retail, E-Commerce, Manufacturing, Distribution |
| Companies Covered | Multi-Color Corporation, CCL Industries, Huhtamaki Group, Coveris Holdings, Fort Dearborn Company, Constantia Flexibles, Inland Packaging, Fuji Seal International, EVCO Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Mold Labelled Containers Market Evolving Landscape
Label-to-container fusion technology is advancing on three fronts simultaneously: material science breakthroughs, compliance automation, and procurement model restructuring. These shifts are compressing traditional supply hierarchies.
Polyolefin film substrates are hybridizing with bio-based content streams to meet minimum recycled thresholds without sacrificing stretch ratios in blow moulding. Personal care brands in Germany are piloting these grades for premium injection-moulded formats. The structural consequence is hybridizing cost structures across virgin, recycled, and bio-attributed material tiers.
REACH SVHC candidate list expansion is forcing ink reformulation cycles that compress supplier qualification timelines. ECHA disclosure requirements now cover label-to-food simulant migration pathways previously exempt from scrutiny. Blow-moulded beverage applications face the steepest requalification burden as brand owners pre-empt supply disruption.
Brand owners are consolidating decorator relationships around regional fulfillment density rather than national sourcing spreads. Quick-service restaurant procurement teams now mandate single-source accountability for container-label combinations across multi-state footprints. California's SB 54 implementation uncertainty is accelerating this consolidation as risk mitigation.
In-Mold Labelled Containers Market Segmentation
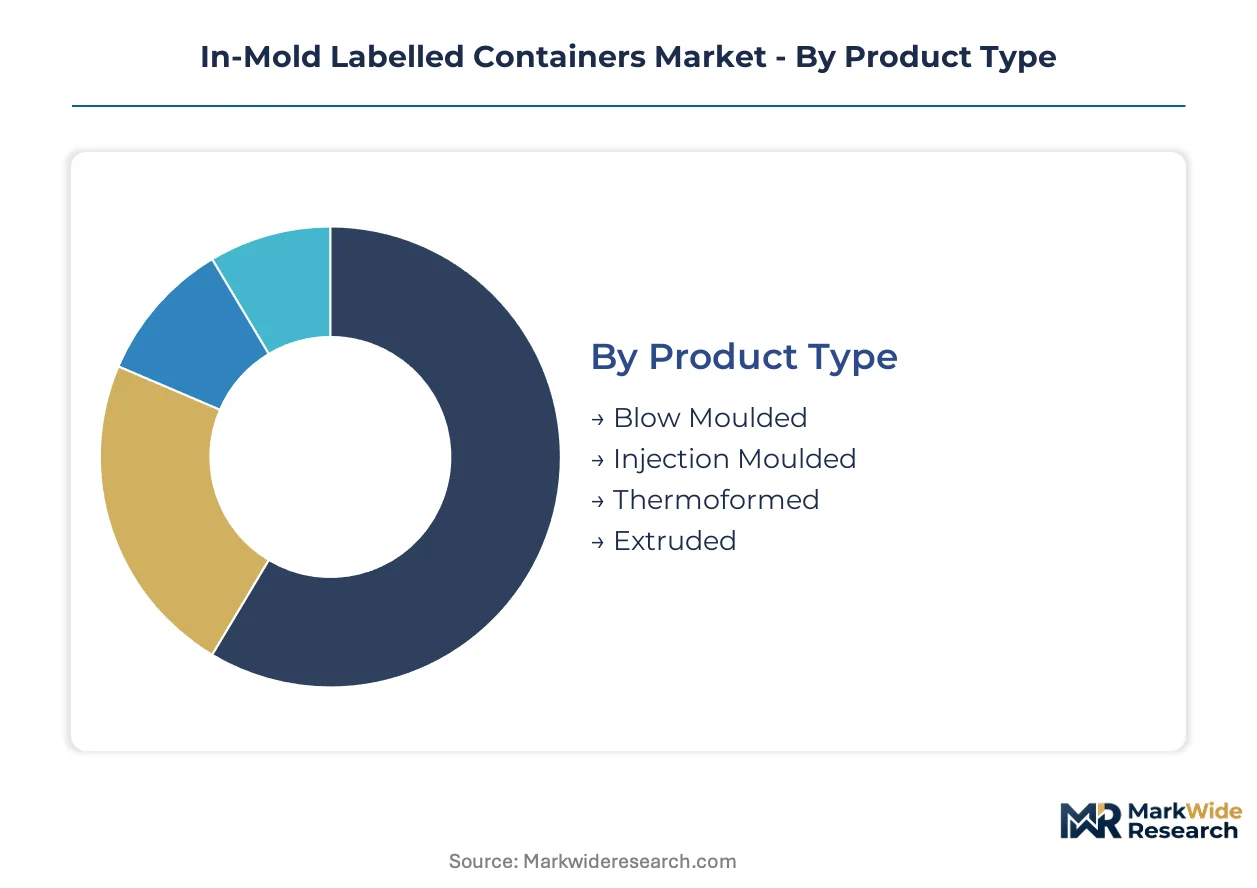
In-mold labelled containers demand fractures across four dimensions: manufacturing process, resin chemistry, end-use durability requirements, and channel fulfillment velocity. Each axis carries distinct margin profiles and requalification burdens that reshape supplier positioning.
Product Type:
Blow moulded formats turn inventory fastest due to beverage industry batch cycles, while thermoformed lines serve slower-moving industrial applications with longer tooling lead times.
- Blow Moulded:HDPE and PET stretch ratios accommodate high-speed rotary equipment. Quick-service restaurant chains in Germany's Stuttgart corridor standardize on this format for 360-degree branding with refrigeration durability.
- Injection Moulded:Wall-thickness precision down to 0.1mm tolerances enables thread-definition critical for personal care closures. Premium positioning in German personal care manufacturing commands margin premiums over commodity beverage formats.
- Thermoformed:Lower capital intensity suits short-run promotional packaging with thinner gauge requirements.
- Extruded:Continuous profile output serves industrial bulk containers with lower graphic complexity demands.
Blow moulded anchors the volume base while injection moulded gains share at the steepest rate.
Material:
Resin selection stratifies by compliance burden and recycling infrastructure compatibility rather than raw material cost alone.
- Polypropylene:Recyclability protocols across European sorting infrastructure are displacing polystyrene in blow-moulded beverage lines. ECHA SVHC disclosure requirements favor pre-qualified PP grades that preempt regulatory scrutiny.
- Polyethylene:HDPE dominates dairy and juice applications where moisture barrier properties outweigh clarity requirements. California's SB 54 recycled content mandates are accelerating procurement shifts toward certified circular PE streams.
- Polystyrene:Legacy presence in thermoformed trays faces structural decline as EU Single-Use Plastics Directive compliance costs mount.
- PET:Clarity and barrier performance sustain premium beverage positioning despite higher processing temperatures complicating label fusion.
Polyethylene retains the largest installed base though polypropylene expands most quickly.
Application:
Application cycles diverge sharply: food service rotates packaging quarterly for menu refreshes while personal care formats persist for years.
- Food Packaging:Disposable container standardization at quick-service restaurant chains demands 360-degree branding with chemical resistance for condiment exposure. REACH food simulant migration testing creates qualification barriers for new substrate entrants.
- Beverage Containers:Refrigeration durability and repeated handling requirements favor fused labels over adhesive alternatives. Germany's Central Agency Packaging Register enforcement tightens recycled content thresholds for export-bound suppliers.
- Personal Care:Premium wall-thickness precision opens margin-rich positioning for thread-definition specialists serving injection-moulded formats.
- Household Products:Chemical resistance requirements for cleaning agents sustain demand despite lower graphic complexity.
Food packaging generates the highest shipment velocity while personal care commands the steepest margin expansion.
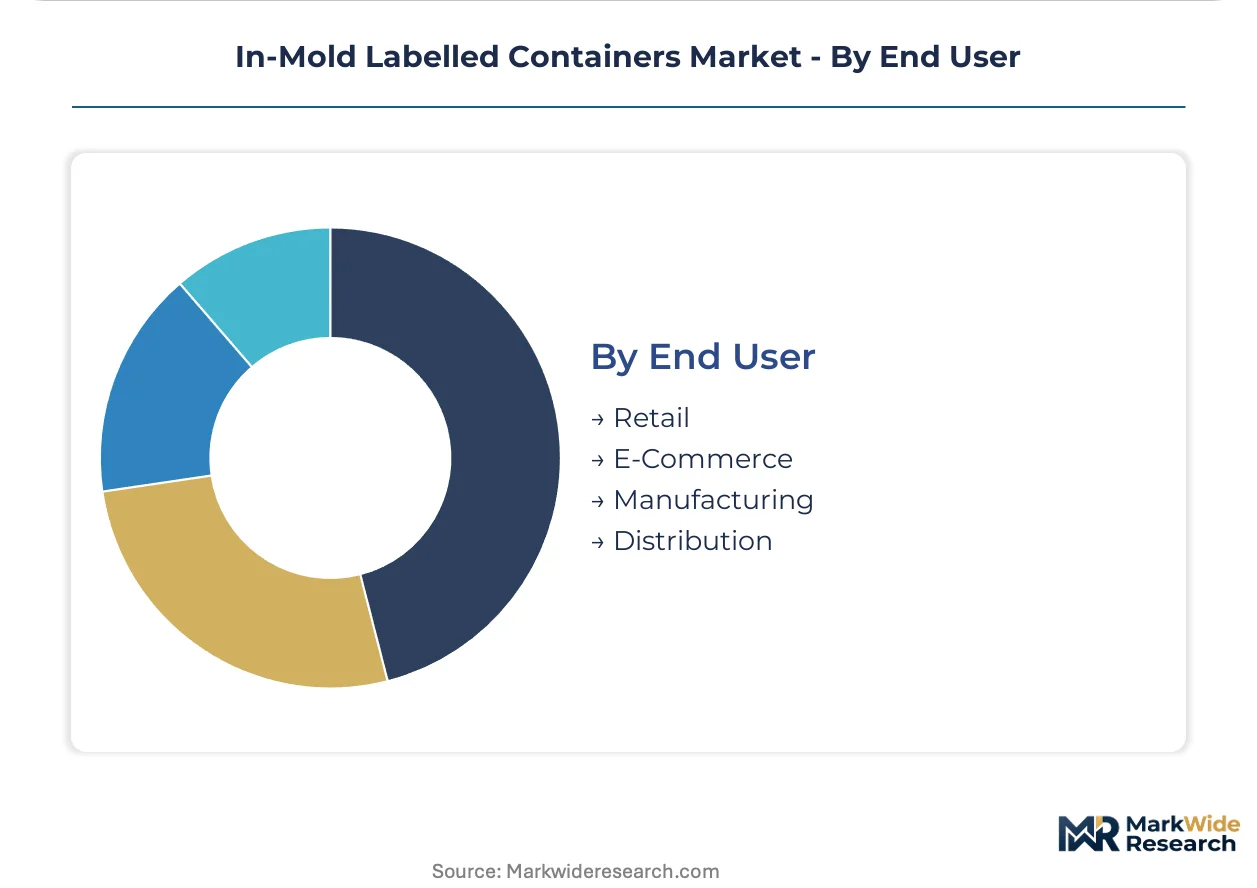
End User:
Channel concentration determines order fragmentation: retail demands predictable replenishment while e-commerce tolerates longer lead times for batch customization.
- Retail:Shelf-ready packaging mandates drive standardization across national footprints. Multi-state quick-service restaurant procurement teams now require single-source accountability for container-label combinations.
- E-Commerce:Shorter runs enabled by digital printing integration support regional beverage launches with reduced minimum order quantities.
- Manufacturing:Captive container production for integrated personal care brands favors backward-integrated film substrate suppliers.
- Distribution:Bulk intermediate packaging serves industrial chemical handling with lower decoration requirements.
Retail channels dominate current volume while e-commerce climbs the fastest among procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-bound suppliers face diverging compliance timelines across major destination markets, forcing dual-track qualification strategies for in-mold label substrates and container specifications.
United States
Quick-service restaurant chains standardizing disposable packaging across multi-state footprints drive demand for 360-degree branded containers with refrigeration durability. California's SB 54 extended producer responsibility framework generates compliance uncertainty as federal preemption debates continue. Chicago and Dallas manufacturing corridors host blow-moulding operations serving national beverage distribution networks.
Germany
Precision manufacturing requirements for personal care injection-moulded formats command margin premiums over commodity beverage applications. The Central Agency Packaging Register enforces minimum recycled content thresholds under the national packaging ordinance, reshaping material procurement for export suppliers. Stuttgart and Munich anchor converter concentration, with blow-moulded beverage standardization dominating the corridor's output mix.
China
Domestic beverage brands accelerating premium positioning favor fused-label clarity and barrier performance despite higher processing temperatures. The Ministry of Ecology and Environment tightens plastic pollution action plan implementation, pressuring substrate selection toward recyclable polypropylene grades. Yangtze River Delta manufacturing clusters integrate digital printing systems for shorter regional launch runs.
Japan
Personal care brands demanding wall-thickness precision down to 0.1mm tolerances sustain injection-moulded format premiums. METI's resource circulation policy framework accelerates sorting infrastructure investment, enabling circularity claims for polypropylene label-resin combinations. Osaka-Kobe industrial zones concentrate captive container production for integrated beauty brands.
India
Quick-service restaurant expansion into tier-2 cities creates pull for standardized food packaging with condiment resistance. FSSAI food-contact clearance pathways for imported label substrates impose testing timelines that favor pre-qualified suppliers. Maharashtra and Gujarat host emerging converter capacity serving domestic beverage and dairy applications.
In-Mold Labelled Containers Market Competitive Landscape
On the supply side, the industry is consolidating around decorators with backward integration into film substrates and regional fulfillment density. Three archetypes dominate: multi-plant North American networks, European blow-moulding specialists with dedicated container lines, and Asian integrated packaging conglomerates. Competitive moves center on asset-light press leasing partnerships and strategic site consolidation to serve quick-service restaurant single-source procurement mandates.
Among North American headquartered decorators, Multi-Color Corporation and Fort Dearborn Company exemplify the multi-plant regional fulfillment archetype. CCL Industries occupies a position within the European specialist tier alongside Constantia Flexibles, which represents backward-integrated substrate control. These named entities anchor industry-level patterns without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Multi-Color Corporation |
| CCL Industries |
| Huhtamaki Group |
| Coveris Holdings |
| Fort Dearborn Company |
| Constantia Flexibles |
| Inland Packaging |
| Fuji Seal International |
| EVCO Plastics |
| Others |
Value Network & Pricing Analysis
Overcapacity in Germany's Stuttgart blow-moulding corridor is compressing converter margins and forcing asset-light leasing models that reshape both supplier consolidation patterns and pricing postures across European export markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate procurement relationships. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under FDA 21 CFR 177 and REACH SVHC compliance tiers. Cost compression in standard-grade polypropylene is intensifying because resin volatility complicates fixed-price commitments. Quick-service restaurant chains exhibit highest price sensitivity due to volume scale mandates, while personal care brands tolerate premium positioning for thread-definition precision.
Supply Chain Analysis
Multi-Color Corporation, CCL Industries, and Constantia Flexibles hold the majority of dedicated blow-moulding and injection-moulding capacity across North America and Europe. Supply concentrates in Germany, the United States, and China, with raw material dependencies on polypropylene resin, polystyrene substrates, and food-contact adhesive formulations. Single-source vulnerability threatens export-bound decorators as California's SB 54 implementation timeline generates compliance ambiguity. Distribution runs through regional fulfillment networks serving quick-service restaurant single-source mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Single-Use Plastics Directive and REACH SVHC expansion are disrupting material qualification timelines, creating winner-take-most dynamics for pre-certified substrate suppliers.
For Market Incumbents: Pre-empt regulatory fragmentation by securing backward integration into film substrates with certified circular streams. Lock in quick-service restaurant single-source contracts before California SB 54 clarity emerges. Anchor capacity in Germany's precision manufacturing corridor to capture personal care premium positioning. For New Entrants and Emerging Players: Build out digital printing capabilities for shorter-run regional beverage launches where minimum order quantity barriers exclude incumbents. Target India's tier-2 city quick-service restaurant expansion where FSSAI clearance timelines favor pre-qualified importers. Pursue asset-light press leasing partnerships to bypass capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward decorators with backward-integrated substrate control and regional fulfillment density across multi-state footprints. The 5-10 year viability window favors suppliers with pre-qualified REACH and FDA pathways. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for requalification burden intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Substrates | Constantia Flexibles controls cost volatility through captive supply of certified circular polypropylene grades. |
| Asset-Light Press Leasing Partnerships | Mid-tier decorators bypass capital barriers via performance-based equipment financing with rotary equipment suppliers. |
| REACH SVHC Pre-Qualification Investment | Pre-qualified substrates preempt regulatory scrutiny as ECHA expands disclosure requirements to food simulant migration pathways. |
| Single-Source Contract Consolidation | Quick-service restaurant procurement teams mandate container-label accountability across multi-state footprints. |
| Digital Printing System Integration | High-definition inkjet systems enable shorter runs for regional beverage launches with reduced minimum order quantities. |
Research Methodology
Operator-level perspectives from blow-moulding plant managers, quick-service restaurant procurement directors, personal care brand packaging engineers, and food-contact regulatory affairs leads anchored the qualitative base. Secondary validation drew from ECHA SVHC candidate list publications, FDA 21 CFR 177 indirect food-contact guidance, German Central Agency Packaging Register enforcement data, and customs records tracking polypropylene resin trade flows. Bottom-up capacity assessments triangulated against top-down demand modeling across manufacturing process, resin chemistry, and end-use application dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across manufacturing process type, material grade tier, application durability requirements, and channel fulfillment velocity. CAGRs were derived from installed base erosion rates and replacement demand curves. Forecast inputs incorporated EU Green Deal packaging target implementation timelines and California SB 54 extended producer responsibility rulemaking progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian integrated packaging conglomerates or sudden REACH SVHC list acceleration would shift outcomes. Quarterly review of ECHA candidate list expansion, German packaging ordinance enforcement actions, and quick-service restaurant procurement consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Popcorn Containers Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Trays Market
Containers
Laminated Bulk Bins Market
Containers
Corrugated Bin Boxes Market
Containers
Sandwich Containers Market
Containers
Global Food Containers Market
Containers
Single Wall Jars Market
Containers
Screw Top Lids Market
Containers
EPS Shippers Market
Containers
Bulk Containers Market
Containers
Laboratory Sample Container Market
Containers
Hinged Lid Compostable Container Market
Containers
Stackable Plastic Trays Market
Containers
Kuwait Container Glass Market