
 Food Can Market | 2026-2036
Food Can Market Size, Share, and Industry Trends Forecast 2026-2036
Food Can Market Intelligence
A shift away from reliance on a few large food conglomerates is broadening the customer base to include a growing number of private-label and artisanal food producers. Crown Holdings, Inc. leverages its extensive global manufacturing network to supply multinational CPGs. Ball Corporation differentiates through its focus on lightweight aluminum can innovations. Ardagh Group secures its position by offering customized packaging for premium brands.
A food can is a hermetically sealed container, typically constructed from tinplate or aluminum, designed for long-term food preservation. Its primary function is to maintain shelf stability by preventing microbial contamination and oxidation after the sterilization process. Aluminum is gaining share over traditional tinplate, especially in the beverage and premium food segments. Demand for cans for ready-to-eat meals represents the fastest-growing end-use application, outpacing mature categories like canned vegetables.
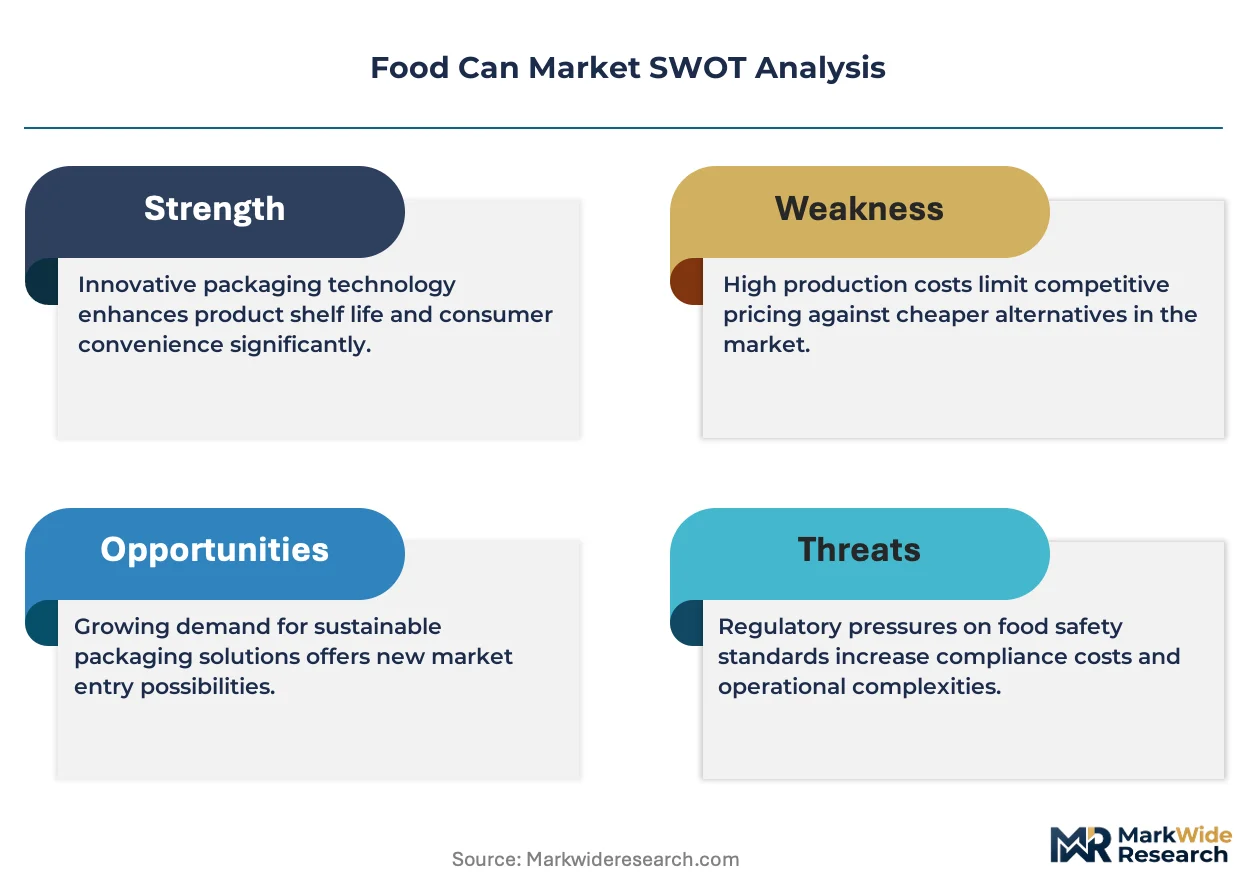
Food contact material standards from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern market access. These regulations, along with China's GB standards administered by the SAMR, set strict limits on chemical migration from can linings, such as bisphenol-A. Future investment decisions will hinge on balancing material sustainability goals against the cost of regulatory compliance for new coating technologies.
Market Dynamics
The market's central dynamic is the tension between material science innovation and the escalating stringency of global food contact regulations. Mandates from the FDA, EFSA, and China's SAMR are forcing a rapid, industry-wide shift to new coating technologies and materials.
Growth Catalysts
- Convenience Food Growth:Rising demand for ready-to-eat meals in economies like India boosts can volume, driven by urbanization and the need for shelf-stable products.
- BPA-Free Regulations:Mandates from the FDA and EFSA restricting bisphenol-A accelerate the adoption of safer internal coatings like polyester and acrylics.
- Aluminum Substitution:The shift to lightweight, recyclable aluminum from tinplate is happening in premium food applications where branding and sustainability are critical.
Market Restraints
- Input Cost Volatility:Price fluctuations for aluminum and tinplate steel create margin pressure for can makers and pricing uncertainty for CPG customers.
- Flexible Packaging Substitution:Stand-up pouches and retortable cartons present a significant threat, offering lighter weight in the single-serve and ready-to-eat meal categories.
- Compliance Hurdles:The high cost and long timelines for validating new coatings against strict FDA and EFSA regulations deter rapid material innovation.
Strategic Opportunities
- Plant-Based Food Packaging:The growing plant-based food sector presents a new application for cans, ensuring product integrity and shelf life for meat alternatives.
- Geographic Expansion:Southeast Asian and Latin American markets offer growth potential as incomes rise and demand for convenient processed foods grows.
- Digital Can Integration:QR codes on cans enable supply chain traceability and direct communication of sustainability credentials to consumers.
Industry Challenges
- Capital-Intensive Line Conversion:Retrofitting or replacing existing manufacturing lines to handle lightweighted aluminum or apply new generations of BPA-free coatings requires significant capital investment.
- Navigating Global Regulatory Fragmentation:Manufacturers face complexity in ensuring a single product complies with diverging food contact material standards, such as the FDA, EFSA, and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Can Market |
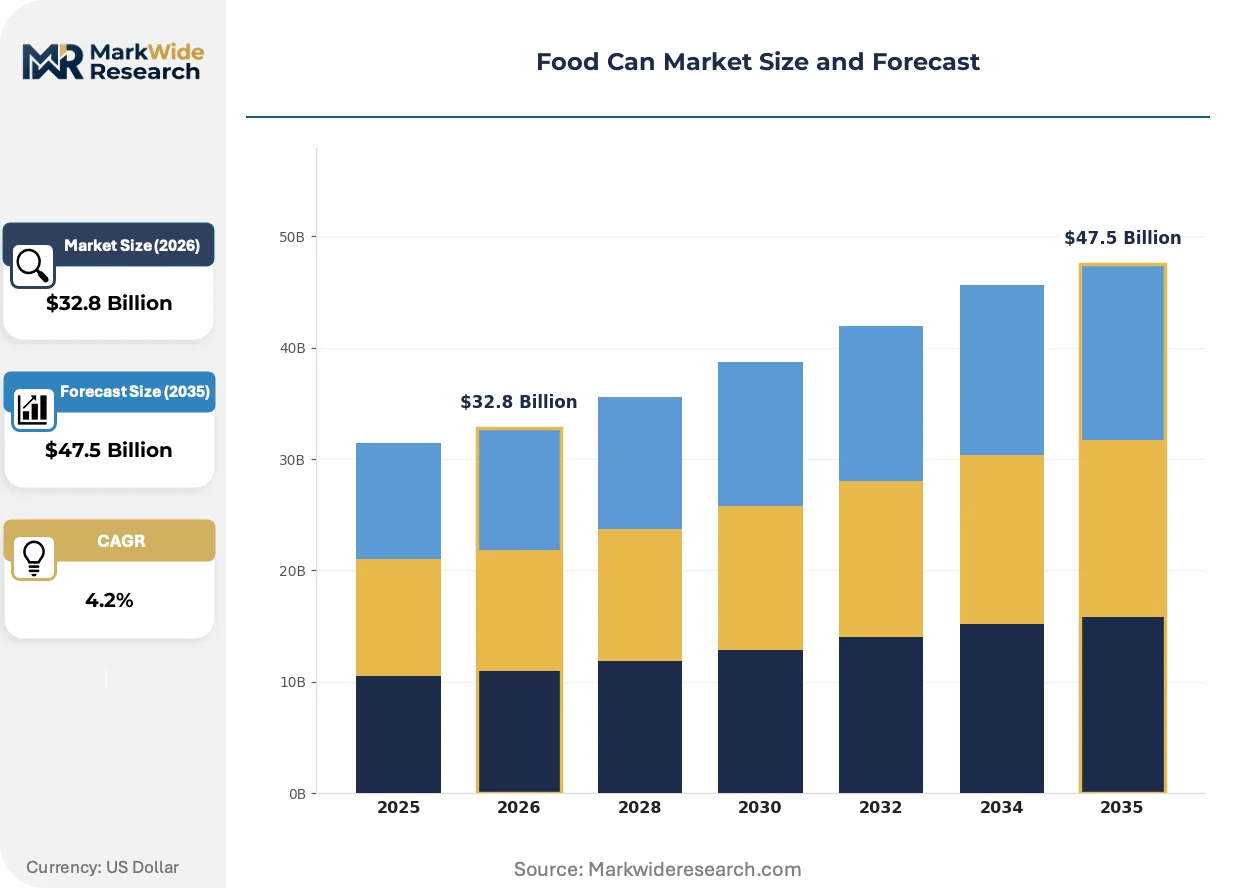
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Tinplate, Aluminum, Steel, Plastic Composite Can Size: 250 ml, 500 ml, 1 Liter, 2 Liters, 5 Liters End Use Application: Canned Vegetables, Ready-to-Eat Meals, Beverage Packaging, Pet Food Closing Mechanism: Easy-Open End, Seamless Lid, Peel-Off, Stay-On Tab |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Ardagh Group, Silgan Holdings Inc., CAN-PACK Group, Kian Joo Group, Toyo Seikan Group Holdings Ltd., CCL Industries, Trivium Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Can Market Strategic Shifts & Innovations
The market's evolution is defined by a dual focus on material sustainability and absolute food safety. This drives innovation in can coatings, material composition, and how packaging communicates its attributes to end-consumers.
Next-generation epoxy-free coatings provide a functional barrier for food products without using materials of concern like bisphenol-A. CPGs in sensitive categories, including infant nutrition and organic foods, are pioneering their adoption. This technology is unifying the high-performance requirements of chemical resistance and flexibility with the stringent food safety mandates from regulators like the FDA and EFSA.
European Union circular economy policies are placing greater emphasis on material-to-material recycling rates for packaging. This shift pressures can manufacturers to optimize designs for maximum metal recovery and minimize non-recyclable components. The aluminum can segment, in particular, is leveraging its high recycling value to gain share over multi-material packaging formats in response to these regulatory drivers.
Consumer demand for transparency in food ingredients is extending to packaging, creating a pull for clean-label cans. This behavioral shift disrupts traditional B2B sales models, requiring can producers to supply detailed material data to brand owners for consumer-facing communication. The trend is most visible in North American and European organic food segments, where brand storytelling includes packaging composition.
Food Can Market Segmentation
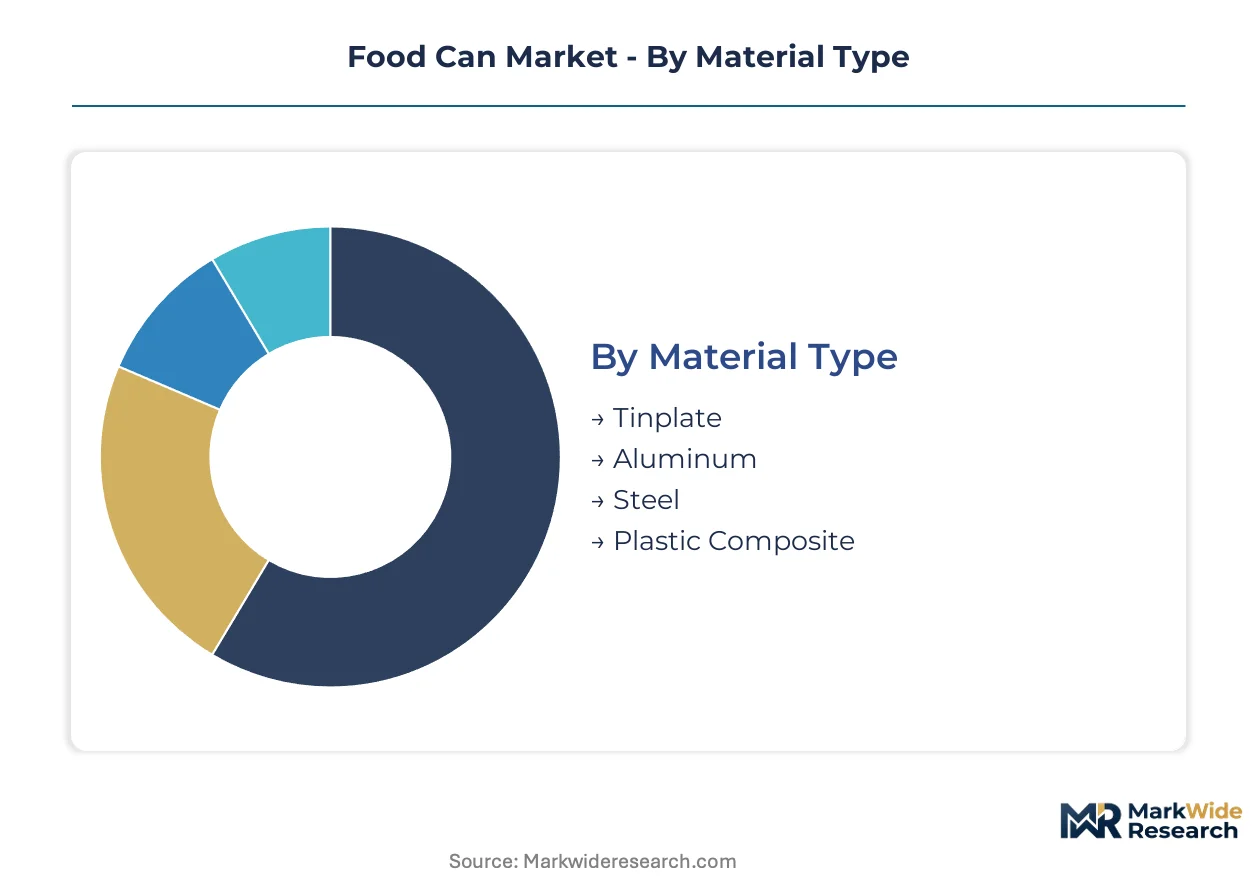
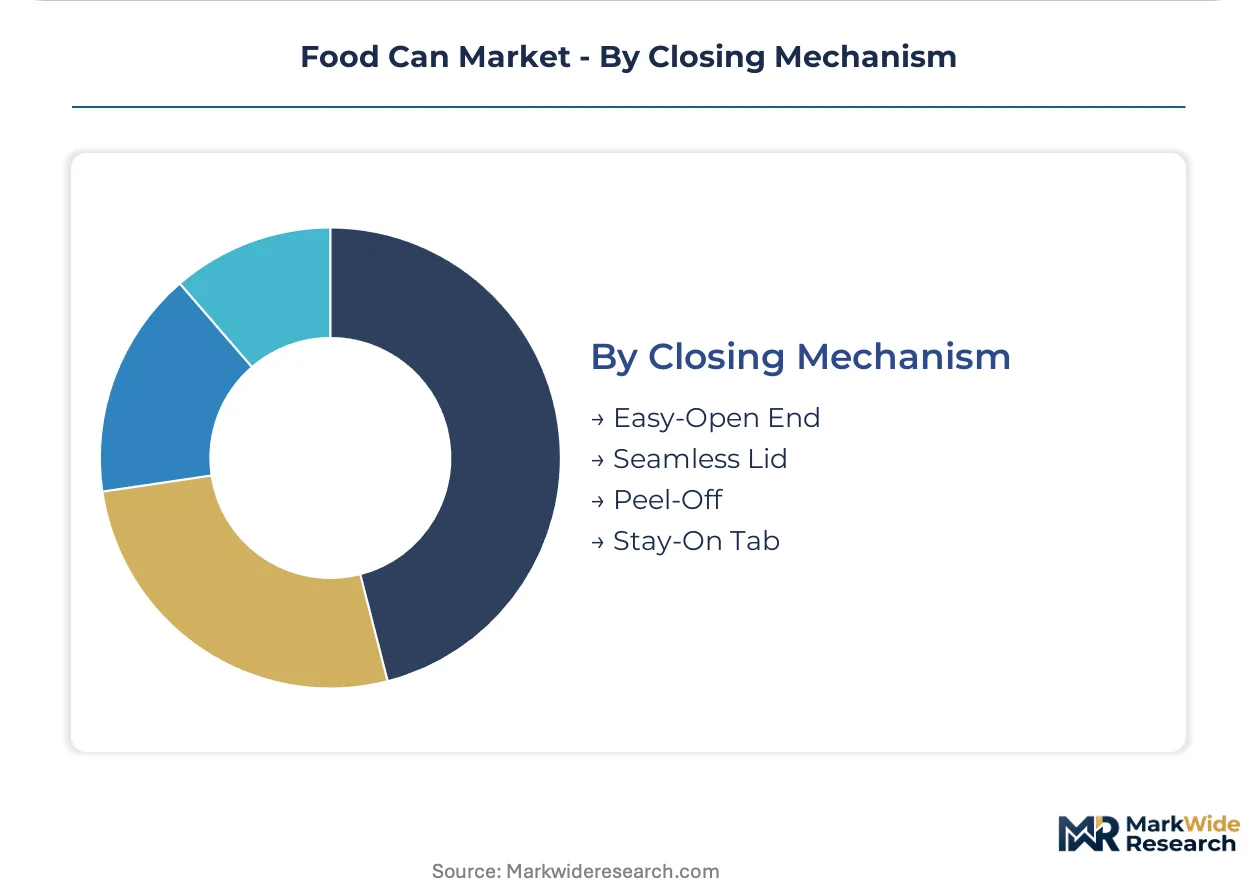
The segmentation analysis provides a structured view of the food can market, dissecting its various components. Understanding these segments helps stakeholders identify specific growth vectors and demand shifts. This detailed breakdown illuminates where innovation and regulatory compliance intersect with consumer preferences.
Material Type:
The material composition of food cans dictates their performance characteristics and environmental footprint.
- Aluminum:This lightweight metal offers superior recyclability and corrosion resistance for various food products. Demand for aluminum cans is accelerating in premium food segments and beverage packaging due to sustainability targets.
- Tinplate:A traditional material, tinplate provides excellent barrier properties and structural integrity for long-term food preservation. Its robust nature makes it suitable for a wide array of canned goods, particularly in mature markets.
- Steel:Steel cans offer high strength and durability, often used for larger volume food applications.
- Plastic Composite:These hybrid solutions combine plastic with other materials, offering flexibility and lighter weight for certain food preservation needs.
Mature deployment sits with Tinplate. Newer deployment is concentrated in Aluminum.
Can Size:
The volumetric capacity of food cans aligns with diverse consumer needs and product applications.
- 500 ml:This medium-sized can is frequently chosen for single-serve ready-to-eat meals and individual beverage portions. Urbanization trends and convenience food consumption drive demand for this practical size, especially in developing economies.
- 1 Liter:Often used for family-sized portions of vegetables, fruits, and processed food items, the 1-liter can serves established household consumption patterns. Its prevalence reflects traditional food preservation practices across many global markets.
- 250 ml:Smaller 250 ml cans cater to single servings or specialty food items, offering portion control.
- 2 Liters:Larger 2-liter cans are typically employed for bulk food items or institutional catering.
- 5 Liters:The largest 5-liter cans find application in industrial food service or bulk ingredient storage.
The smallest volumes are served by 250 ml. The largest volumes are served by 5 Liters.
End Use Application:
Demand patterns for food cans are directly influenced by the specific food products they contain and consumer lifestyles.
- Ready-to-Eat Meals:This segment exhibits the steepest expansion trajectory, driven by busy consumer lifestyles and urbanization in regions like India. Cans for ready-to-eat meals offer convenience and extended shelf life, aligning with modern dietary habits.
- Beverage Packaging:A high-volume application, beverage packaging utilizes cans for soft drinks, juices, and increasingly, functional beverages. The segment benefits from aluminum's recyclability and consumer preference for portable, single-serve options.
- Canned Vegetables:A mature segment, canned vegetables rely on cans for long-term preservation and year-round availability.
- Pet Food:Cans provide a robust and shelf-stable packaging solution for various pet food formulations, ensuring product integrity.
Consumption for Canned Vegetables drives significant volume. Emerging demand patterns are reshaping Ready-to-Eat Meals.
Closing Mechanism:
The functional design of can closures enhances consumer convenience and product security.
- Easy-Open End:This mechanism provides consumer convenience, eliminating the need for separate opening tools. Its widespread adoption across various food categories reflects a strong market preference for user-friendly packaging.
- Stay-On Tab:Predominantly used in beverage packaging, the stay-on tab offers a convenient and integrated opening solution. This design minimizes litter and is a standard feature for many canned drinks.
- Seamless Lid:Seamless lids offer a robust and hermetic seal, crucial for maintaining product sterility over extended periods.
- Peel-Off:Peel-off lids provide an alternative easy-opening solution, often found in smaller or premium food can formats.
Traditional sealing methods are represented by Seamless Lid. Modern convenience features are central to Easy-Open End.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food cans concentrates heavily in developing economies, particularly India, driven by rising convenience food consumption. Urbanization patterns across these regions fuel the need for shelf-stable food solutions. This geographic shift influences global manufacturing and distribution strategies for can makers.
India
India's market for food cans benefits from the expanding ready-to-eat meal segment and rapid urbanization. The FSSAI plays a crucial role in regulating food contact materials for domestic producers. Manufacturing clusters in Maharashtra and Tamil Nadu are investing in advanced can production lines to meet local demand.
China
China's food can demand reflects evolving consumer preferences for convenient processed foods and premium offerings. The SAMR enforces strict GB standards on packaging materials, including bisphenol-A limits for can linings. Major production facilities in the Pearl River Delta are adapting to these stringent regulatory requirements and sustainability goals.
United States
The United States market sees sustained demand for both traditional canned goods and premium aluminum food packaging. FDA regulations directly influence material choices, particularly the shift to BPA-free internal coatings across the industry. Packaging innovation centers in the Midwest are developing next-generation coating technologies for various food applications.
Germany
Germany's food can sector emphasizes sustainability targets and high-quality packaging for premium food brands. EFSA guidelines, alongside EU circular economy policies, drive material-to-material recycling initiatives for metal packaging. The Rhine-Ruhr region, with its strong industrial base, supports advanced can manufacturing and material recovery efforts.
France
France exhibits strong demand from artisanal food producers and for convenient, ready-to-eat meal formats. European Union directives on food safety and material recycling influence packaging design and material composition. The Greater Paris region is a hub for packaging research and development, focusing on new coating applications and sustainable materials.
Food Can Market Key Industry Players
Global producers anchor one tier, leveraging extensive manufacturing networks; regional specialists hold positions through targeted innovation. The market structure exhibits tiered competition, with scale players dominating high-volume segments and niche providers serving premium applications. Strategic archetypes include multinational integrators, innovation-driven specialists, and custom solution providers. Capacity expansion and strategic partnerships are dominant competitive moves.
Multinational integrators like Crown Holdings, Inc. leverage their global footprint to serve large consumer packaged goods companies across various geographies. Ball Corporation exemplifies innovation-driven specialists, focusing on lightweight aluminum can solutions and sustainability attributes for beverage and premium food segments. Ardagh Group occupies a position among custom solution providers, offering specialized packaging for premium brands that require unique designs and advanced material specifications globally. These companies collectively represent the diverse strategic approaches within the food can manufacturing sector.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Ardagh Group |
| Silgan Holdings Inc. |
| CAN-PACK Group |
| Kian Joo Group |
| Toyo Seikan Group Holdings Ltd. |
| CCL Industries |
| Trivium Packaging |
| Others |
Cost & Logistics Intelligence
India's Maharashtra and Tamil Nadu manufacturing clusters, with their concentrated skilled labor, influence pricing tiers by offering cost advantages for high-volume can production. This labor-cost differential shapes competitive pricing strategies.
Pricing Analysis
High-volume food can segments prioritize cost efficiency, while premium applications command higher margins for specialized solutions. Pricing operates on a hybrid model, combining long-term contract-based agreements with value-based pricing for customized designs. Customization level and volume scale drive price differentiation. Margin pressure stems from input cost volatility for aluminum and tinplate, impacting profitability.
Supply Chain Analysis
Food contact material standards from the FDA, EFSA, and China's SAMR gate market access, requiring stringent qualification for can linings. Supply concentrates in manufacturing hubs across China, India, and the United States. Key dependencies include aluminum, tinplate, and next-generation epoxy-free coatings. Regulatory fragmentation across these regions presents a structural supply chain risk. Distribution runs through direct supply relationships with consumer packaged goods companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food can market is poised for consolidation, as capital-intensive line conversions for new coating technologies pressure smaller manufacturers. This creates an environment where scale players can acquire or outcompete.
For Market Incumbents: Hedge against flexible packaging substitution by accelerating investment in next-generation BPA-free coatings and lightweight aluminum solutions. Consolidate market position through strategic acquisitions of smaller players struggling with capital-intensive line conversions. Expand manufacturing footprint in high-demand developing economies like India to secure future volume. This mitigates risks from evolving food contact material standards.
For New Entrants and Emerging Players: Begin with niche segments like plant-based food packaging or premium artisanal brands, where customization and sustainability attributes command higher value. Target underpenetrated geographic markets in Southeast Asia, leveraging localized production. Offer differentiated packaging solutions with advanced digital integration, such as QR codes for supply chain transparency. This approach bypasses direct competition with high-volume incumbents.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term value in an essential, yet evolving, packaging sector. Focus on innovation-driven specialists with proven next-generation coating technologies or strong regional compliance expertise. These targets offer crucial intellectual property and market access. A key signal to watch is the accelerated adoption rate of epoxy-free coatings across major CPGs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Establishes a strong production base in high-demand developing economies like India. |
| R&D Investment | Ensures compliance with evolving FDA and EFSA food contact material standards. |
| Geographic Diversification | Mitigates regulatory fragmentation risks by localizing production in China. |
| Digital Integration | Enhances consumer trust through supply chain traceability and sustainability credentials. |
| Material Innovation | Drives adoption of lightweight aluminum cans, aligning with EU circular economy policies. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with CPG procurement managers, can manufacturing R&D leads, and food safety regulators provided critical market insights. This approach combined qualitative depth with quantitative validation. A rigorous bottom-up and top-down triangulation method ensured data accuracy and forecast robustness.
Data stream reconciliation integrated diverse inputs into a robust analytical framework across the projection horizon. Segmentation dimensions included material type, can size, end-use application, closing mechanism, and regional demand patterns. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included BPA-free coating adoption rates and urbanization trends in developing economies.
Underlying measurement precision varies by segment; mature categories like canned vegetables carry tighter precision than emerging ready-to-eat meals. Forecasts reflect assumptions regarding raw material price stability and regulatory evolution. A model refresh is warranted upon material change in global food contact material standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Seafood Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Fast Food Containers Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Wooden Cutlery Market