
 Pail Lids Market | 2026-2036
Pail Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Pail Lids Market Analytics
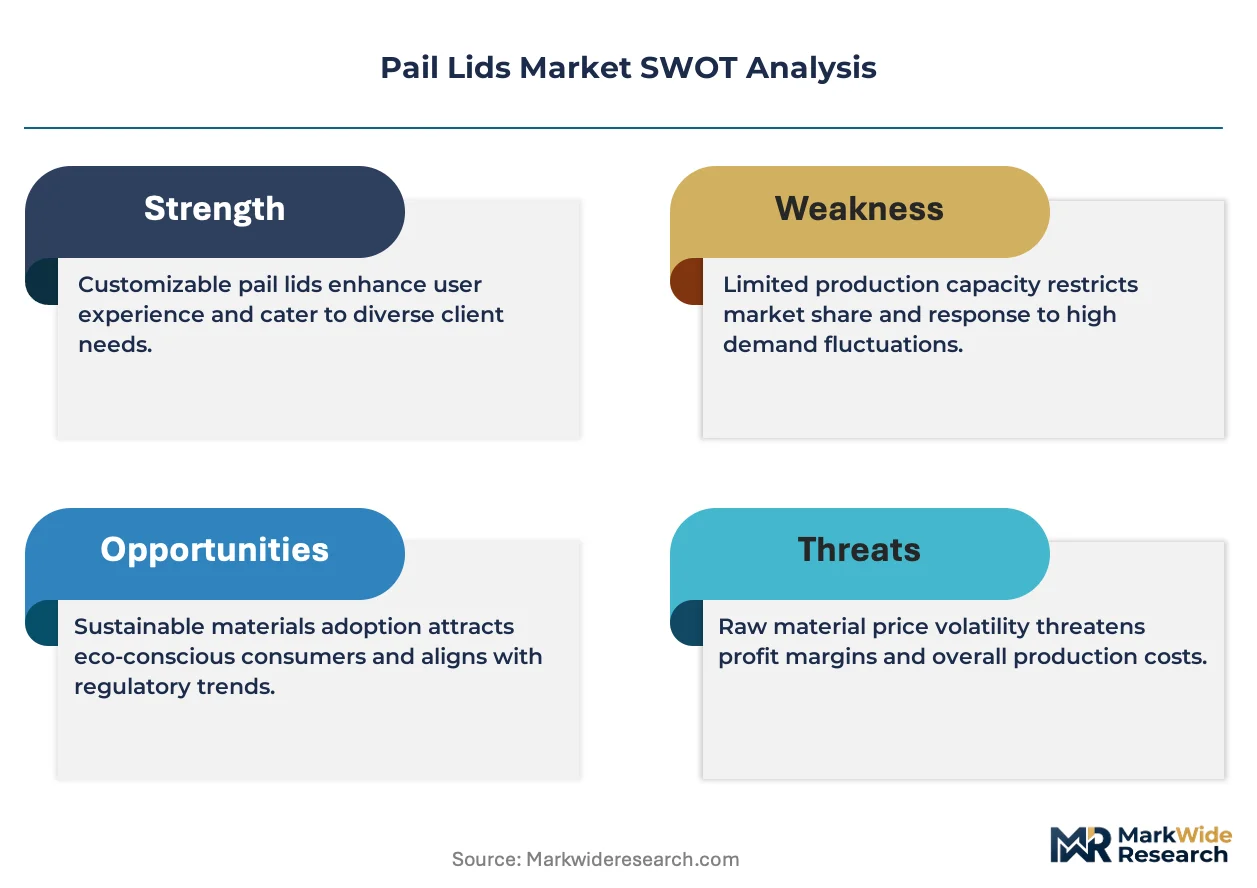
Modular closure bundling with tamper-evident rings and integrated gaskets is repositioning how industrial buyers evaluate total cost of ownership. Mauser Packaging Solutions leverages captive resin-to-lid manufacturing to control specification consistency across chemical storage accounts. Greif Inc. anchors North American volume through its steel and plastic pail platform, while Sonoco Products Company differentiates via fiber-based composite lids targeting sustainability mandates in food packaging.
Pail lids are engineered closures manufactured from injection-molded polypropylene, steel, or fiber-composite substrates, designed to seal cylindrical containers ranging from 1 to 10 gallons against leakage, contamination, and pressure differential. Plastic screw-cap closures dominate chemical storage applications due to chemical resistance and resealability, while snap-fit configurations lead food packaging throughput where line speed governs operational economics. Metal hinged lids retain share in industrial lubricant segments where puncture resistance and stack-load tolerance justify premium positioning over polymer alternatives.
The FDA governs food-contact lid materials under 21 CFR, while OSHA enforces workplace chemical containment through HazCom-aligned closure integrity standards; both frameworks elevate testing documentation burdens for suppliers seeking dual-use certification. The EPA's Spill Prevention, Control, and Countermeasure rules further tighten secondary containment specifications for petroleum-handling facilities, directly influencing gasket and venting design requirements. Buyers must weigh material conversion timelines against evolving UN performance-oriented packaging certifications before committing to multi-year supply agreements.
Market Dynamics
UN-certified closure mandates and petrochemical sector consolidation are compressing supplier qualification timelines while elevating specification rigor for tamper-evident gasket systems across industrial accounts.
Growth Catalysts
- OSHA HazCom alignment:Chemical manufacturers face escalating workplace containment audits, forcing replacement cycles for legacy non-vented closures with pressure-differential-rated alternatives.
- Injection-molded polypropylene substitution:Steel lid displacement accelerates in coatings and adhesives segments where chemical resistance and resealability govern operational uptime.
- United States petrochemical cluster density:Gulf Coast refinery and downstream chemical capacity expansion sustains concentrated demand for 5-gallon pail lid systems with integrated spout designs.
Market Restraints
- Propylene resin price volatility:Feedstock cost swings compress margin stability for injection-molded closure producers locked into annual supply contracts.
- Mid-Atlantic metal stamping concentration:Hinged steel lid fabrication relies on a narrow supplier base around Pittsburgh and Cleveland, creating single-source vulnerability.
- FDA 21 CFR dual-use certification friction:Food-contact material testing documentation burdens extend commercialization timelines for chemical-storage suppliers seeking cross-vertical expansion.
Strategic Opportunities
- Texas and Louisiana chemical corridor expansion:New polyethylene and polypropylene derivative capacity coming online creates captive demand for specification-matched closure systems.
- Spill Prevention Control and Countermeasure (SPCC) secondary containment:EPA enforcement intensification at petroleum-handling facilities drives gasket and venting redesign mandates.
- Fiber-composite and recycled-content convergence:Sustainability procurement scorecards at food packaging accounts favor bio-based lid substrates with performance parity to virgin polypropylene.
Industry Challenges
- UN performance-oriented packaging certification timelines:Six-to-twelve-month test documentation cycles delay contract awards for suppliers lacking pre-certified closure portfolios.
- Legacy steel-to-plastic line conversion capex:Food packagers face retooling costs for snap-fit closure handling equipment that erodes short-term ROI on material substitution.
- Tamper-evident ring integration complexity:Modular bundling requirements strain quality assurance protocols for mid-tier molders lacking automated vision inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pail Lids Market |
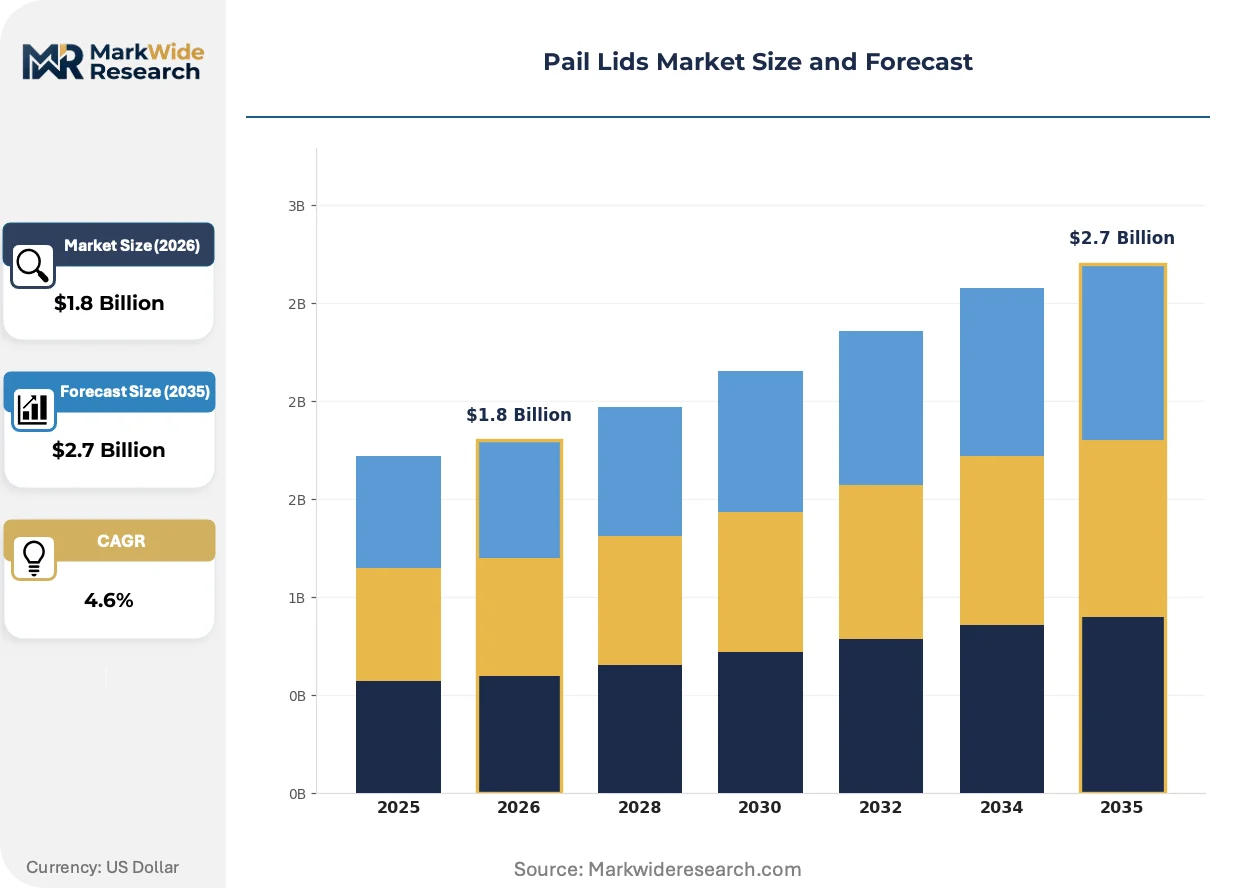
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Composite, Rubber Closure Type: Screw Cap, Snap Fit, Hinged, Push-On Application: Food Packaging, Chemical Storage, Pharmaceutical, Industrial Use Size: 1 Gallon, 2 Gallon, 5 Gallon, 10 Gallon |
| Companies Covered | Berry Global Group, Inc., Mauser Packaging Solutions, Sonoco Products Company, Greif Inc., Bway Corporation, Huhtamaki Oyj, Amcor plc, AptarGroup, Inc., Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pail Lids Market Evolving Landscape
Closure engineering is pivoting toward smart venting and material traceability as industrial buyers consolidate supplier bases around specification consistency and regulatory documentation depth.
Smart venting technology with pressure-relief membranes and RFID-embedded traceability is automating inventory reconciliation and leak-detection protocols for chemical distributors. Bulk petrochemical handlers in Texas and Louisiana are piloting these systems at 10,000-unit scale. The technology is automating compliance documentation workflows that previously required manual batch record retention.
EPA Spill Prevention Control and Countermeasure rules are tightening secondary containment specifications for above-ground storage tank facilities. Petroleum terminals and lubricant blenders must now specify gasket materials with documented chemical compatibility across aromatic and aliphatic hydrocarbon exposure. Gulf Coast refiners are responding by pre-qualifying closure suppliers with pre-submitted SPCC-aligned test data packages.
Consolidated supplier qualification is displacing fragmented multi-source procurement in coatings and adhesives manufacturing. Procurement teams at Ohio and Illinois-based industrial paint producers are reducing approved vendor lists from twelve to three closure suppliers. This concentration is most visible in the Midwest rust belt, where plant rationalization has centralized purchasing authority at regional headquarters.
Pail Lids Market Segmentation
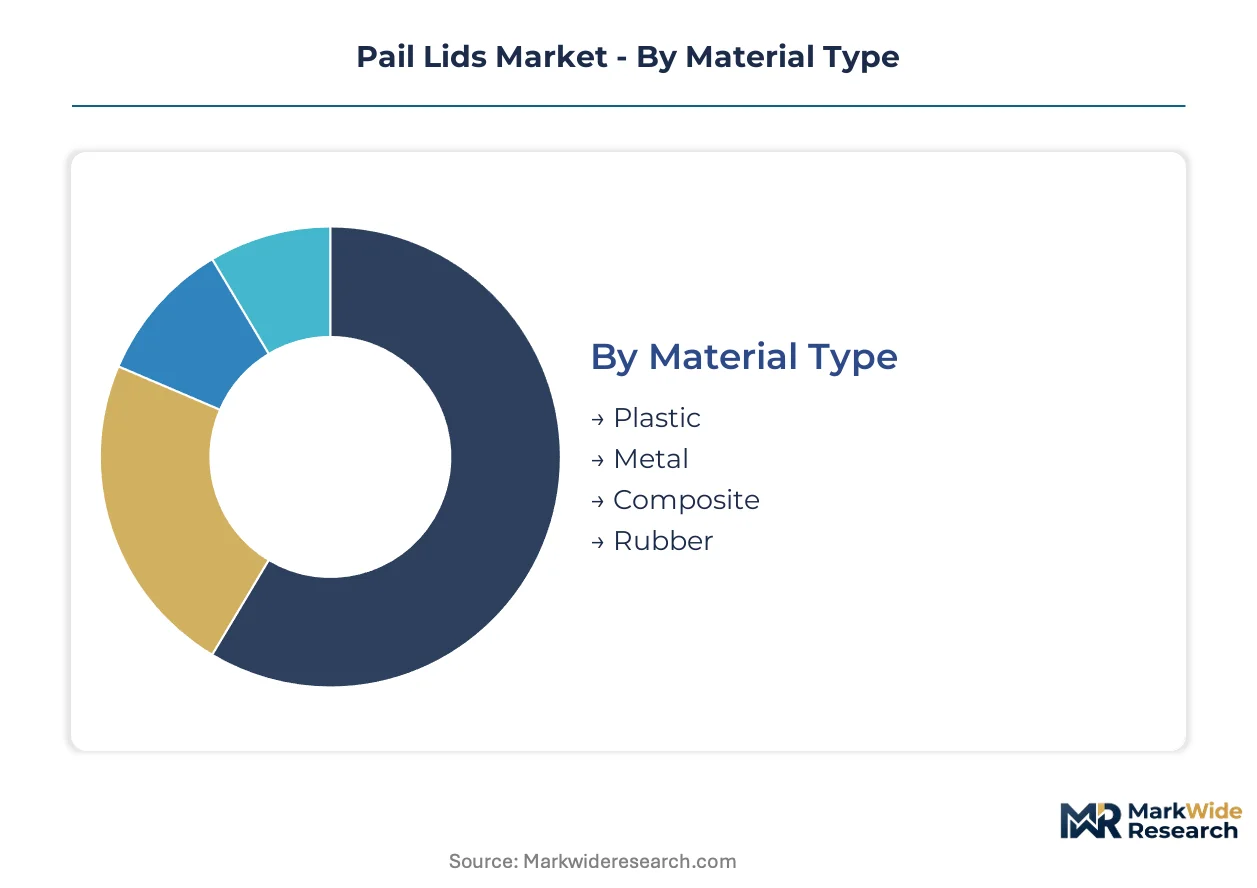
Pail lid procurement decisions hinge on certification alignment across material substrates and closure mechanisms. Buyers map application-specific regulatory burdens—FDA 21 CFR for food contact, OSHA HazCom for chemical containment, UN performance standards for hazardous transport—onto segment selection criteria that govern supplier qualification timelines.
Material Type:
Certification documentation depth varies sharply by substrate, with UN performance-oriented packaging and FDA dual-use approvals creating divergent commercialization barriers.
- Plastic:Injection-molded polypropylene dominates chemical storage applications due to aromatic hydrocarbon resistance and resealability. Gulf Coast petrochemical handlers specify vented screw-cap configurations with integrated gaskets to meet EPA SPCC secondary containment mandates.
- Metal:Steel hinged lids retain industrial lubricant share where puncture resistance and stack-load tolerance justify premium positioning. Pittsburgh and Cleveland metal stamping clusters supply coatings manufacturers requiring OSHA-aligned containment audit documentation.
- Composite:Fiber-based substrates target sustainability procurement scorecards at food packaging accounts seeking bio-based alternatives with virgin polypropylene performance parity.
- Rubber:Specialized gasket-grade compounds seal pressure-differential-rated closures for hazardous material transport certification.
Plastic sits at the top of the volume ranking, with composite climbing the fastest as sustainability mandates harden.
Closure Type:
Operational economics and line speed requirements segment procurement patterns across automated versus manual handling infrastructure.
- Screw Cap:Threaded polypropylene closures enable repeated resealability for chemical distributors managing partial container evacuation. Texas and Louisiana refiners pilot RFID-embedded traceability at 10,000-unit scale.
- Snap Fit:Single-motion engagement maximizes food packaging throughput where line speed governs operational economics. Midwest industrial paint producers consolidate supplier lists around snap-fit standardization.
- Hinged:Metal and polymer variants retain share in lubricant blending where one-handed access and container reclosure frequency matter.
- Push-On:Friction-fit configurations serve cost-sensitive applications with minimal pressure-differential exposure.
Screw cap configurations command the largest installed base, though snap fit systems are expanding most quickly in food sector automation retrofits.
Application:
End-use verticals impose distinct regulatory frameworks that reshape material and design specifications.
- Food Packaging:FDA 21 CFR material testing documentation extends commercialization timelines for suppliers seeking cross-vertical expansion from chemical storage. Fiber-composite lid development accelerates here.
- Chemical Storage:OSHA HazCom alignment and UN-certified closure mandates compress supplier qualification timelines while elevating tamper-evident gasket system requirements. Gulf Coast petrochemical cluster density sustains concentrated demand.
- Pharmaceutical:Tamper-evident ring integration and child-resistant closure specifications add quality assurance protocol layers.
- Industrial Use:Coatings and adhesives manufacturers reduce approved vendor lists from fragmented multi-source bases to three closure suppliers maximum.
Chemical storage generates the steepest volume trajectory, with food packaging gaining share fastest on sustainability procurement shifts.
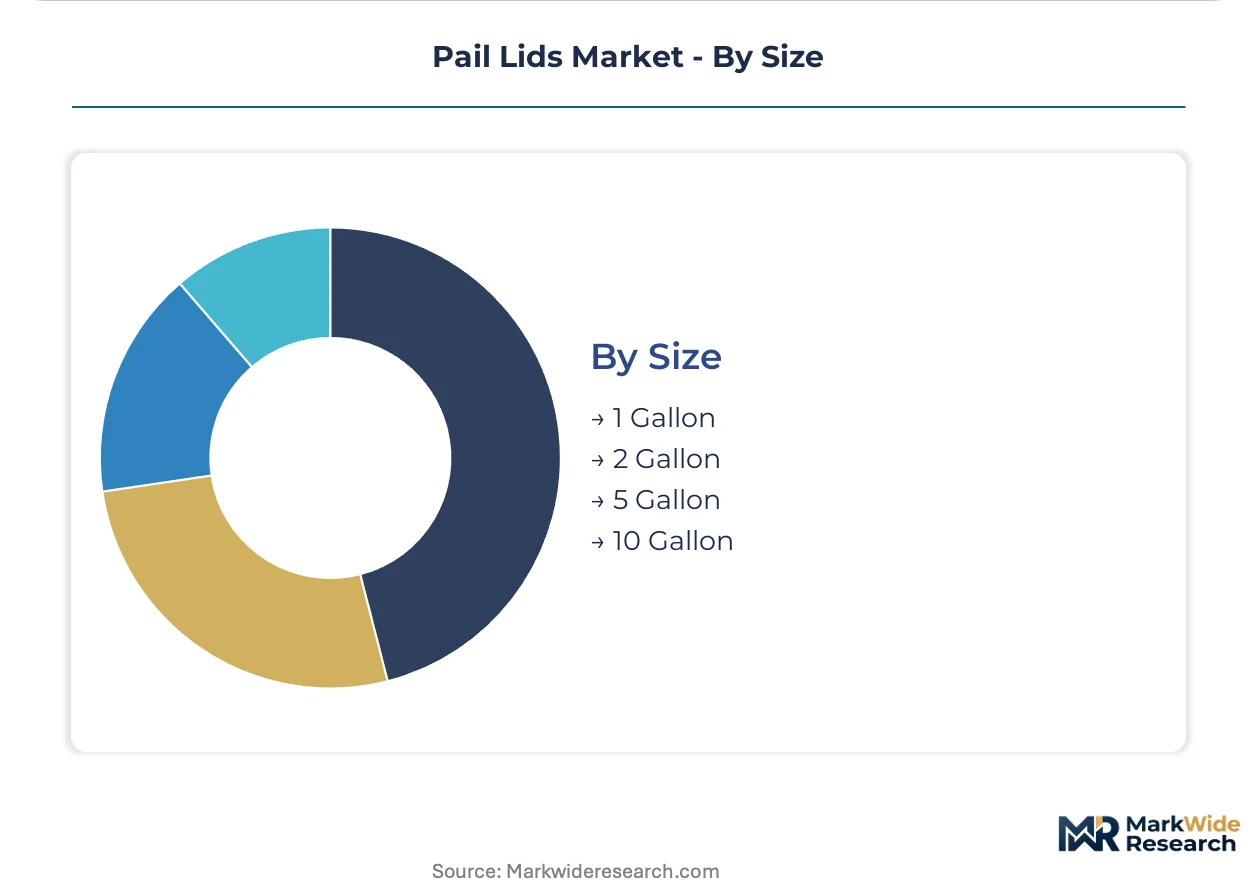
Size:
Container capacity correlates with end-use concentration and secondary containment specification intensity.
- 5 Gallon:The standard industrial workhorse serves petrochemical and coatings producers with integrated spout designs and venting systems. EPA SPCC enforcement at petroleum-handling facilities drives gasket redesign mandates specifically at this capacity.
- 1 Gallon:Compact format dominates retail-facing food and specialty chemical segments where handling ergonomics and shelf footprint constrain design.
- 2 Gallon:Mid-size configuration balances portability with volume efficiency in adhesives and sealants distribution.
- 10 Gallon:Large-format closures require reinforced gasket systems and stack-load engineering for bulk industrial supply chains.
Five-gallon systems anchor procurement volume, with one-gallon formats expanding most quickly in retail channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pail lids industry traces its industrial-scale origins to post-war American chemical manufacturing, where standardized 5-gallon container systems first achieved mass adoption across Gulf Coast petrochemical corridors. This foundation established the technical specifications and regulatory frameworks that subsequently diffused to European and Asian industrial packaging markets.
United States
Gulf Coast petrochemical cluster density sustains concentrated demand for vented screw-cap systems with integrated spout designs. OSHA HazCom workplace containment audits force replacement cycles for legacy non-vented closures across Texas and Louisiana refineries. Houston-area lubricant blenders pre-qualify suppliers with pre-submitted EPA SPCC-aligned test data packages to accelerate procurement timelines.
Germany
REACH chemical registration requirements elevate documentation burdens for closure suppliers seeking industrial coatings accounts in the Rhine-Ruhr manufacturing belt. ECHA enforcement of substance restrictions reshapes gasket material selection for hazardous material transport certification. Bavarian automotive chemical producers consolidate approved vendor lists around specification-matched UN-certified closure systems.
China
Dual carbon goals and GB standards compliance accelerate fiber-composite lid development for domestic food packaging accounts seeking bio-based alternatives. MIIT industrial packaging guidelines tighten secondary containment specifications for petroleum-handling facilities in the Yangtze River Delta. Shanghai-area coatings manufacturers pilot RFID-embedded traceability systems at 10,000-unit scale for inventory reconciliation automation.
Japan
METI industrial safety frameworks drive tamper-evident ring integration for chemical distributors managing partial container evacuation protocols. JIS standards compliance creates divergent commercialization barriers for foreign suppliers seeking cross-vertical expansion from food packaging into chemical storage. Osaka-based adhesives manufacturers reduce approved vendor lists from fragmented multi-source bases to three closure suppliers maximum.
Pail Lids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and captive resin-to-lid manufacturing integration. The vendor base stratifies into three tiers: integrated packaging conglomerates with captive resin operations, specialized industrial closure fabricators with regional stamping or molding concentration, and diversified materials companies leveraging cross-divisional polymer science capabilities. Consolidated supplier qualification and backward integration into resin compounding represent the dominant competitive moves reshaping procurement relationships.
Among North American integrated packaging specialists, Mauser Packaging Solutions and Greif Inc. exemplify the resin-to-lid manufacturing archetype that controls specification consistency across chemical storage accounts. Sonoco Products Company occupies a position within the fiber-based composite tier targeting sustainability procurement scorecards. These three anchors illustrate how geographic clustering around Gulf Coast petrochemical corridors and Midwest metal stamping bases shapes competitive positioning.
| Leading Market Players |
|---|
| Berry Global Group, Inc. |
| Mauser Packaging Solutions |
| Sonoco Products Company |
| Greif Inc. |
| Bway Corporation |
| Huhtamaki Oyj |
| Amcor plc |
| AptarGroup, Inc. |
| Silgan Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Polypropylene resin costs cascade through injection-molded closure pricing tiers, with Gulf Coast petrochemical feedstock proximity separating premium specification-matched suppliers from economy-grade distant competitors serving price-sensitive coatings distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with UN-certified tamper-evident systems commanding spreads over commodity snap-fit alternatives based on documentation depth and automated vision inspection integration. Price differentiation hinges on certification grade alignment and captive resin compounding capability, with backward-integrated molders extracting margin advantage during propylene volatility cycles. Cost compression in economy tiers intensifies as mid-Atlantic metal stamping consolidation eliminates secondary sourcing flexibility. Chemical storage buyers exhibit lowest price sensitivity due to regulatory audit exposure, while retail-facing food packagers prioritize line-speed economics over per-unit cost minimization.
Supply Chain Analysis
Freight cost exposure from Pittsburgh and Cleveland metal stamping clusters to Texas and Louisiana chemical corridors compresses margin structures for steel hinged lid fabricators lacking regional molding alternatives. Geographic supply concentration centers on the United States, China, and Germany, with injection-molded polypropylene capacity clustering around Gulf Coast resin production and Yangtze River Delta compounding infrastructure. Raw material dependencies span propylene monomer, cold-rolled steel coil, and fiber-composite pulp substrates. Single-source vulnerability permeates mid-Atlantic metal stamping concentration. Distribution runs through direct mill-to-plant contracts for volume chemical accounts and distributor networks for fragmented coatings and adhesives manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pail Lids Market functions as a stable compounder anchored by regulatory replacement cycles that mandate closure system upgrades regardless of macroeconomic cyclicality.
For Market Incumbents: Hedge propylene cost exposure through captive resin compounding or long-term supply offtake agreements with Gulf Coast crackers. Defend specification-matched relationships by pre-submitting EPA SPCC-aligned test data packages that accelerate procurement timelines for petroleum-handling facilities. Prioritize automated vision inspection capital deployment to capture tamper-evident ring integration contracts fleeing mid-tier molders with quality assurance gaps. For New Entrants and Emerging Players: Regional distributors serving fragmented Midwest industrial paint producers represent the most penetrable channel anchor, with approved vendor list consolidation from twelve to three suppliers creating displacement opportunity. Fiber-composite lid development for sustainability procurement scorecards offers white-space access before virgin polypropylene performance parity hardens into table stakes. Pursue joint qualification pilots with Ohio and Illinois-based coatings manufacturers seeking second-source redundancy against single-source metal stamping vulnerability. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA 21 CFR dual-use certification friction extends commercialization timelines beyond twelve months, stranding mid-tier chemical-storage suppliers seeking cross-vertical expansion into food packaging. Acquisition target archetypes include specialized industrial closure fabricators with pre-certified UN performance portfolios and regional molding concentration lacking national scale. Monitor EPA SPCC enforcement intensity at petroleum-handling facilities as inflection indicator for gasket and venting redesign mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margin stability against propylene monomer volatility cycles. |
| Automated Vision Inspection Deployment | Tamper-evident ring quality assurance protocols separate specification-matched suppliers from disqualification risk. |
| Pre-Certified UN Portfolio Expansion | Six-to-twelve-month test documentation cycles compress supplier qualification timelines for contract capture. |
| Fiber-Composite Substrate Development | Bio-based alternatives with virgin polypropylene performance parity align with sustainability procurement scorecards. |
| Regional Molding Capacity Addition | Gulf Coast proximity to Texas and Louisiana chemical corridor expansion captures captive derivative demand. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream coatings manufacturers, technical R&D directors at closure fabricators, and distribution channel partners — were reconciled against secondary validation from customs and trade data, American Chemistry Council reports, and SEC 10-K filings. Bottom-up volume modeling across material substrates and closure mechanisms was cross-referenced with top-down industry sizing from petrochemical cluster capacity announcements and EPA SPCC enforcement records.
Historical shipment trajectories were cross-referenced against panel input from procurement officers at lubricant blenders and industrial paint producers to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include material type, closure mechanism, application vertical, and regional production hub concentration. CAGRs were derived from slope analysis of replacement cycle timing and regulatory mandate implementation schedules, with specific inputs from OSHA HazCom audit frequency trends and UN performance-oriented packaging certification pipeline visibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene resin price volatility, mid-Atlantic metal stamping consolidation patterns, and fiber-composite substrate performance parity achievement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Rotomolded Containers Market
Containers
Snap Secure Containers Market
Containers
Container Fixed Fittings Market
Containers
Bulk Container Packaging Market
Containers
Corrugated Open-Head Drums Market
Containers
Roll Containers Market
Containers
Containerboard Market
Containers
Twist Up Stick Container Market
Containers
Intermediate Bulk Container Liner Market
Containers
Foldable Container Market
Containers
Pinch Grip Jars Market
Containers
Packaging Bins Market
Containers
Carboy Market
Containers
Trays Market
Containers
Laminated Bulk Bins Market
Containers
Tottle Containers Market