
 Lever Lid Tinplate Containers Market | 2026-2036
Lever Lid Tinplate Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Lever Lid Tinplate Containers Market Foresight
Specialty food packaging is recalibrating lever lid tinplate demand as artisan producers and premium brands abandon plastic snap-tops for metal closures with tamper-evident seals. Invopak leverages its UK manufacturing footprint to dominate contract supply for condiment and preserve makers. HUBER Packaging Group GmbH anchors continental European demand through specialized printing and coating capabilities on tinplate substrates. Trivium Packaging competes across beverage and industrial lines with integrated metal forming and decoration technology.
Lever lid tinplate containers are cylindrical metal vessels fabricated from electrolytic tinplate steel, typically ranging from 0.16 mm to 0.36 mm thickness, with a mechanically crimped lid that pivots on a wire bail to create a resealable closure; the tin coating provides corrosion resistance for acidic or moist contents while the steel substrate delivers structural rigidity for stacking and transport. Standard containers occupy the volume base in commodity food and chemical applications where price sensitivity limits specification flexibility. Specialty containers capture margin pools in high-value niches requiring custom embossing, internal lacquering, or dimensional deviation from catalog sizes. Extra deep containers are expanding fastest among food service bulk purchasers seeking efficient kitchen storage with stackable geometry.
FDA food-contact substance notifications govern tinplate migration limits for acidic foods in the United States, while REACH and the EU Packaging and Packaging Waste Directive shape material compliance and extended producer obligations across Europe. BIS certification requirements for food-grade metal packaging in India are tightening testing protocols for tin coating uniformity and solder seam integrity. Stakeholders must monitor how divergent national recycling targets and deposit schemes reshape the total cost of metal packaging ownership against competing substrates.
Market Dynamics
Specialty food producers are abandoning plastic closures at scale, forcing tinplate lever lid specifications upward as tamper-evident metal seals become a baseline hygiene signal rather than a premium add-on.
Growth Catalysts
- REACH substance restrictions:European chemical safety rules are accelerating substitution away from polymer-based closures toward tinplate alternatives with documented migration profiles.
- Acidic food packaging:Preserves, condiments, and pickled goods require corrosion-resistant containers that tinplate substrates deliver through controlled tin coating weights.
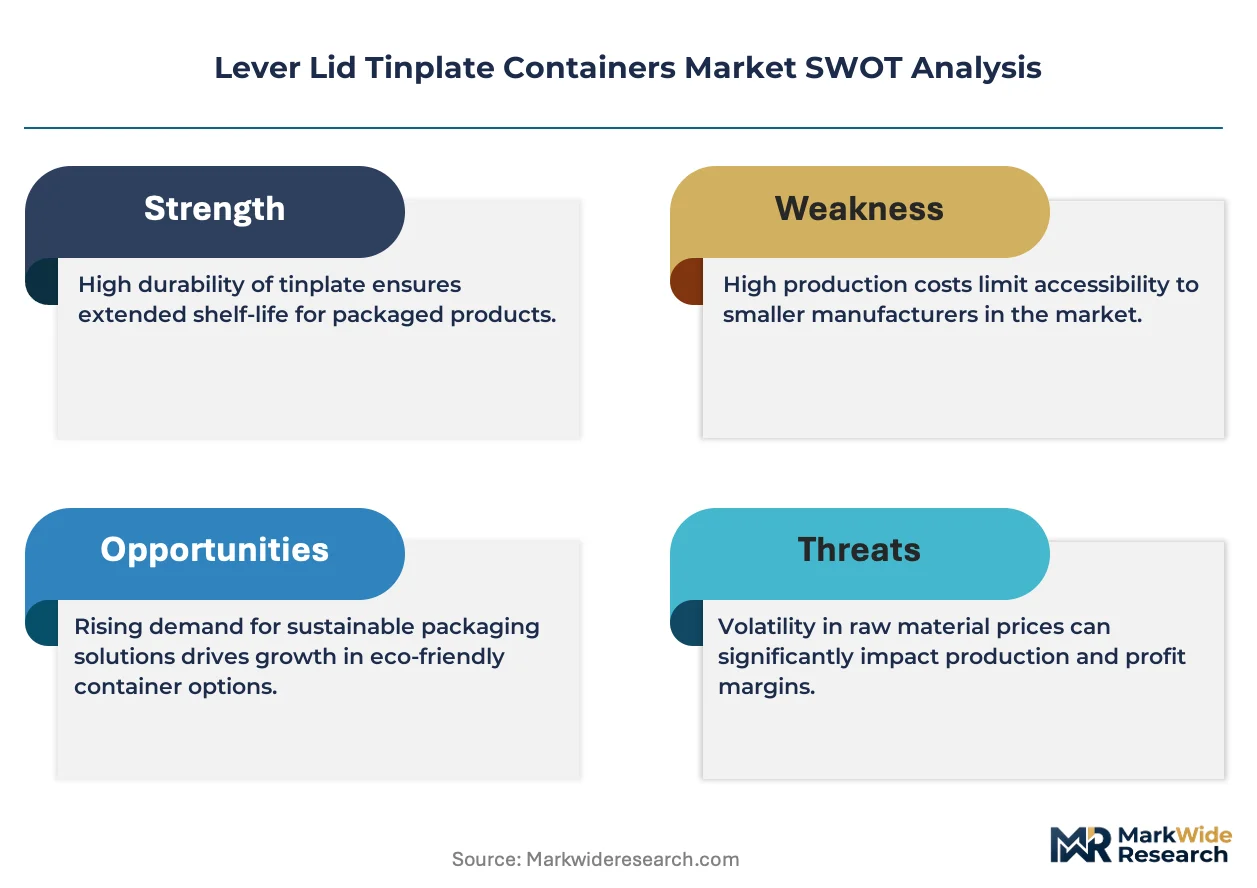
- India's BIS certification tightening:New testing protocols for solder seam integrity are filtering out substandard imports and concentrating demand on certified domestic suppliers.
Market Restraints
- Electrolytic tinplate input volatility:Steel substrate costs and tin metal price swings compress converter margins unpredictably.
- Coating technology concentration:Advanced internal lacquering capabilities cluster in Germany and the United Kingdom, creating supply bottlenecks for specialty orders.
- Aluminum substitution in beverages:Two-piece aluminum cans with integrated easy-open ends capture share in carbonated and still drinks.
Strategic Opportunities
- Food service bulk formats:Extra deep containers for commercial kitchen storage remain underpenetrated relative to retail-sized catalog offerings.
- EU Packaging and Packaging Waste Directive:Extended producer responsibility schemes create preferential economics for infinitely recyclable tinplate against multi-material alternatives.
- Digital printing convergence:Direct-to-metal decoration technologies are collapsing minimum order quantities and enabling mass customization for artisan brands.
Industry Challenges
- Lacquer formulation chemistry expertise:Internal coating specifications for aggressive food chemistries require scarce polymer science talent.
- Multi-jurisdiction compliance timelines:Simultaneous FDA notification, REACH registration, and BIS certification processes delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lever Lid Tinplate Containers Market |
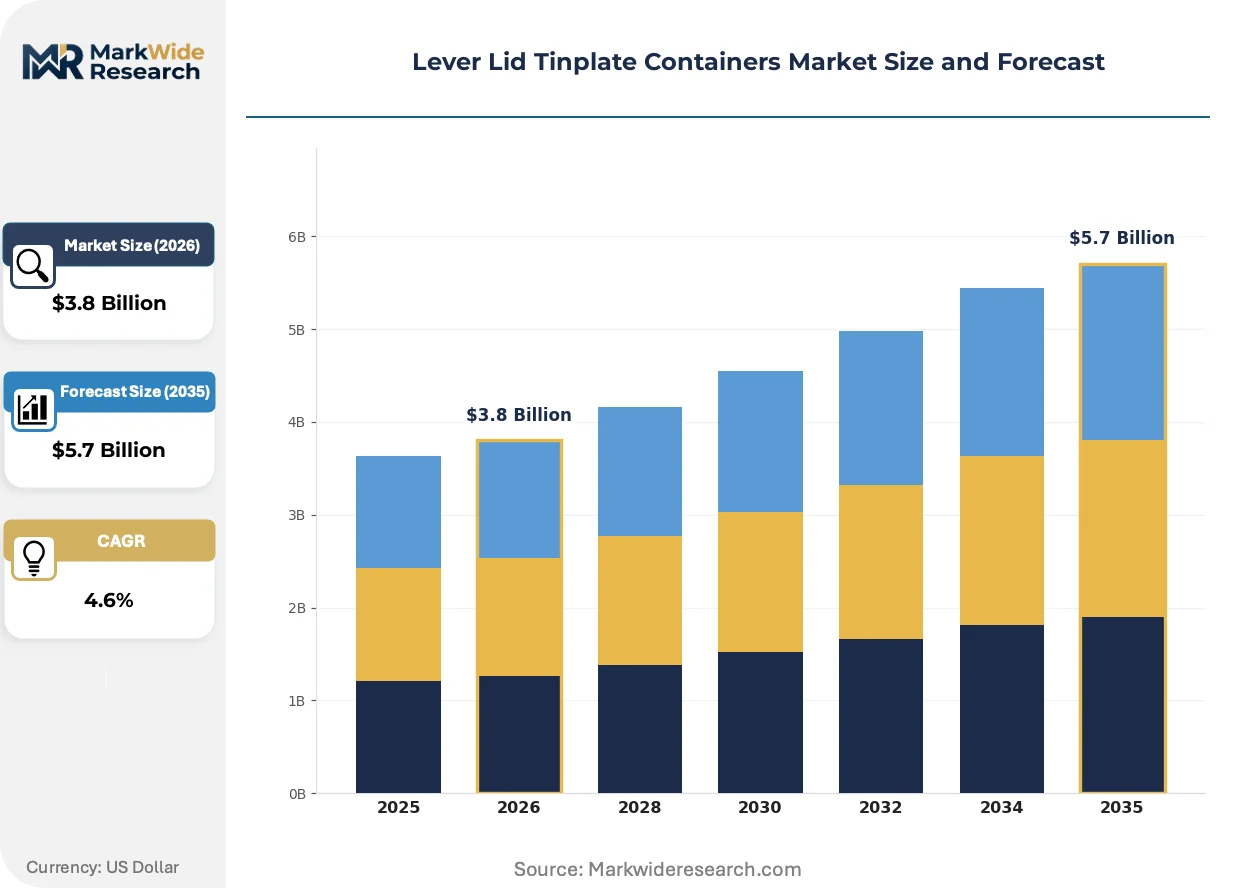
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Containers, Custom Containers, Specialty Containers, Extra Deep Containers Application: Food Packaging, Beverage Packaging, Chemical Storage, Industrial Use Size: Small, Medium, Large, Extra Large End User: Retailers, Manufacturers, Distributors, Food Services |
| Companies Covered | Invopak, RLM Packaging Ltd, HUBER Packaging Group GmbH, Taylor Davis Ltd, Central Tin Containers Ltd, Pirlo Holding GmbH, Quitmann O’Neill Packaging Limited, Mauser Packaging Solutions, Trivium Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lever Lid Tinplate Containers Market Shifts & Advancements
Container specification and decoration technology are converging to collapse lead times and enable batch-size flexibility that legacy tinplate supply chains could not support.
Electrolytic tinplate with differential coating weights is unifying corrosion performance and cost efficiency in a single substrate specification. Specialty condiment producers in Germany and the United States are specifying asymmetric tin coatings—heavier on the interior for acid resistance, lighter on the exterior for decoration adhesion. This technology is unifying what previously required separate material grades into one inventory position, reducing converter working capital requirements.
REACH Annex XVII restrictions on specific phthalates and bisphenols are forcing reformulation of internal lacquers and external coatings across European supply chains. Tinplate converters must validate alternative polymer systems through ECHA notification processes before commercial deployment. Small-batch artisan food producers face the steepest compliance burden, driving consolidation of specification authority toward larger contract packers with in-house regulatory affairs functions.
Direct sourcing relationships between specialty food brands and tinplate decorators are compressing traditional distributor channels. Premium preserve makers in the United Kingdom and craft sauce producers in the United States now specify containers directly with Invopak and comparable converters, bypassing packaging wholesalers. This disintermediation is most visible in segments where brand identity depends on distinctive embossing or custom dimensional formats that catalog distributors cannot supply.
Lever Lid Tinplate Containers Market Segmentation
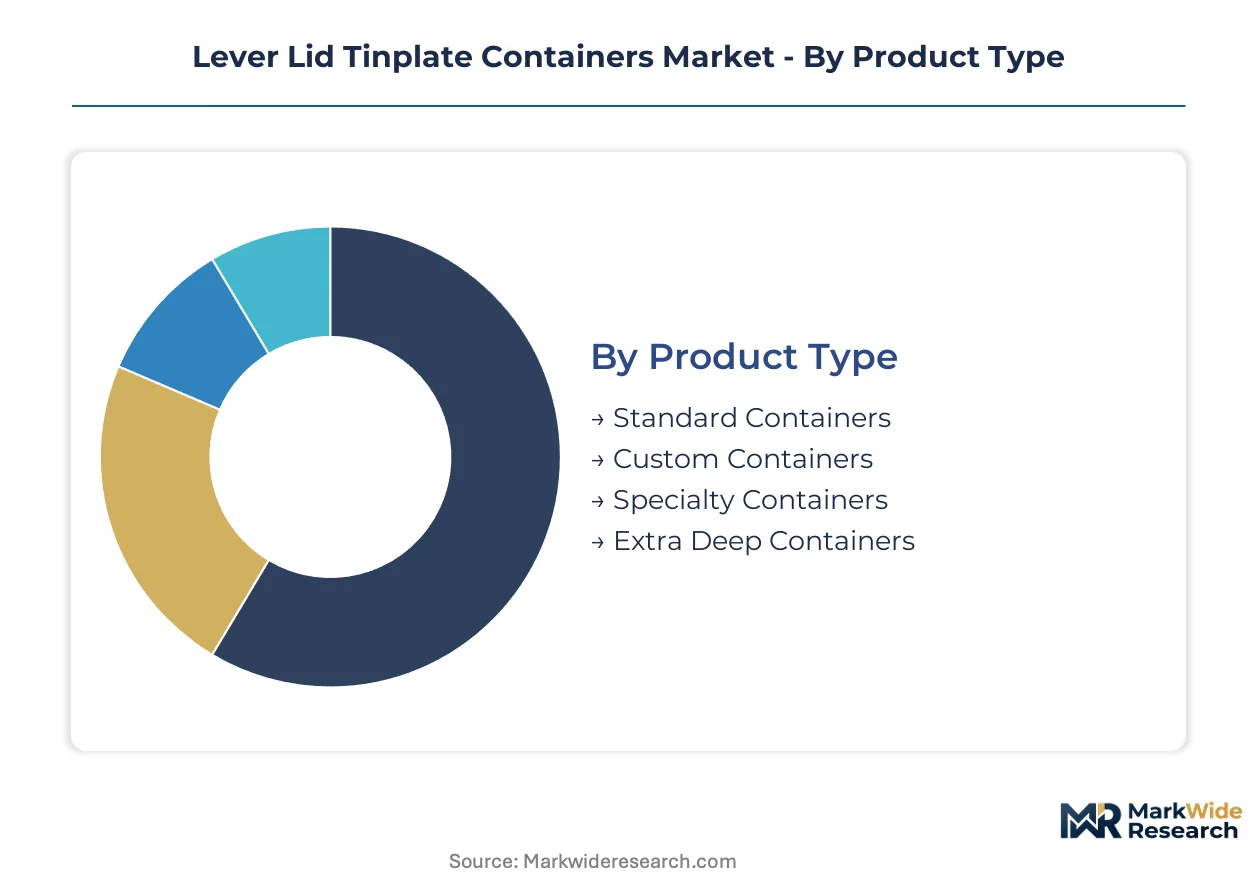
Lever lid tinplate containers serve heterogeneous demand pools that fragment by performance specification, regulatory exposure, and procurement scale. Buyers sort across metal thickness, coating chemistry, and dimensional deviation tolerances based on content acidity, shelf-life requirements, and brand positioning needs.
Product Type:
Cost tier dominates converter quoting behavior as tin coating weights and steel substrate gauges determine unit economics.
- Standard Containers:Fabricated from 0.16 mm to 0.25 mm electrolytic tinplate with uniform coating weights, these cylinders serve commodity condiment and chemical applications where price sensitivity limits specification flexibility. German retail chains and Indian bulk chemical distributors anchor procurement volumes for this tier.
- Specialty Containers:Asymmetric tin coatings—heavier interior deposition for acid resistance, lighter exterior for lithography adhesion—unify corrosion performance and decoration economics in one substrate specification. Artisan preserve makers in the United Kingdom and craft sauce producers in the United States specify these for tamper-evident metal seals that signal hygiene premium.
- Custom Containers:Dimensional deviation from catalog sizes with bespoke embossing or neck profiles.
- Extra Deep Containers:Expanded height-to-diameter ratios for commercial kitchen storage efficiency.
Volume sits with Standard Containers; growth tilts toward Specialty Containers.
Application:
Regulatory exposure intensity separates segments as FDA, REACH, and BIS compliance burdens vary by content chemistry.
- Food Packaging:Preserves, condiments, and pickled goods demand controlled tin coating weights to prevent iron dissolution into acidic matrices. REACH Annex XVII phthalate restrictions and evolving FDA food-contact substance notifications force continuous lacquer reformulation across European and North American supply chains.
- Chemical Storage:Solvent-based contents require specialized internal epoxy phenolic coatings with documented migration profiles for ECHA notification.
- Beverage Packaging:Two-piece aluminum cans displace tinplate in carbonated applications.
- Industrial Use:Lubricants, adhesives, and maintenance compounds with lower aesthetic requirements.
Food Packaging commands procurement scale; Chemical Storage faces steepest compliance filtration.
Size:
Volume scale and handling logistics shape buyer preferences across kitchen, retail shelf, and industrial storage contexts.
- Small:Single-serve condiment portions and sample formats for hospitality and travel retail channels.
- Medium:Household preserve and sauce volumes dominating European supermarket assortments.
- Large:Food service institutional purchasing with palletized distribution economics.
- Extra Large:Bulk ingredient storage for commercial bakeries and manufacturing input buffers.
Medium sizes anchor retail velocity; Extra Large formats are expanding most quickly in food service procurement.
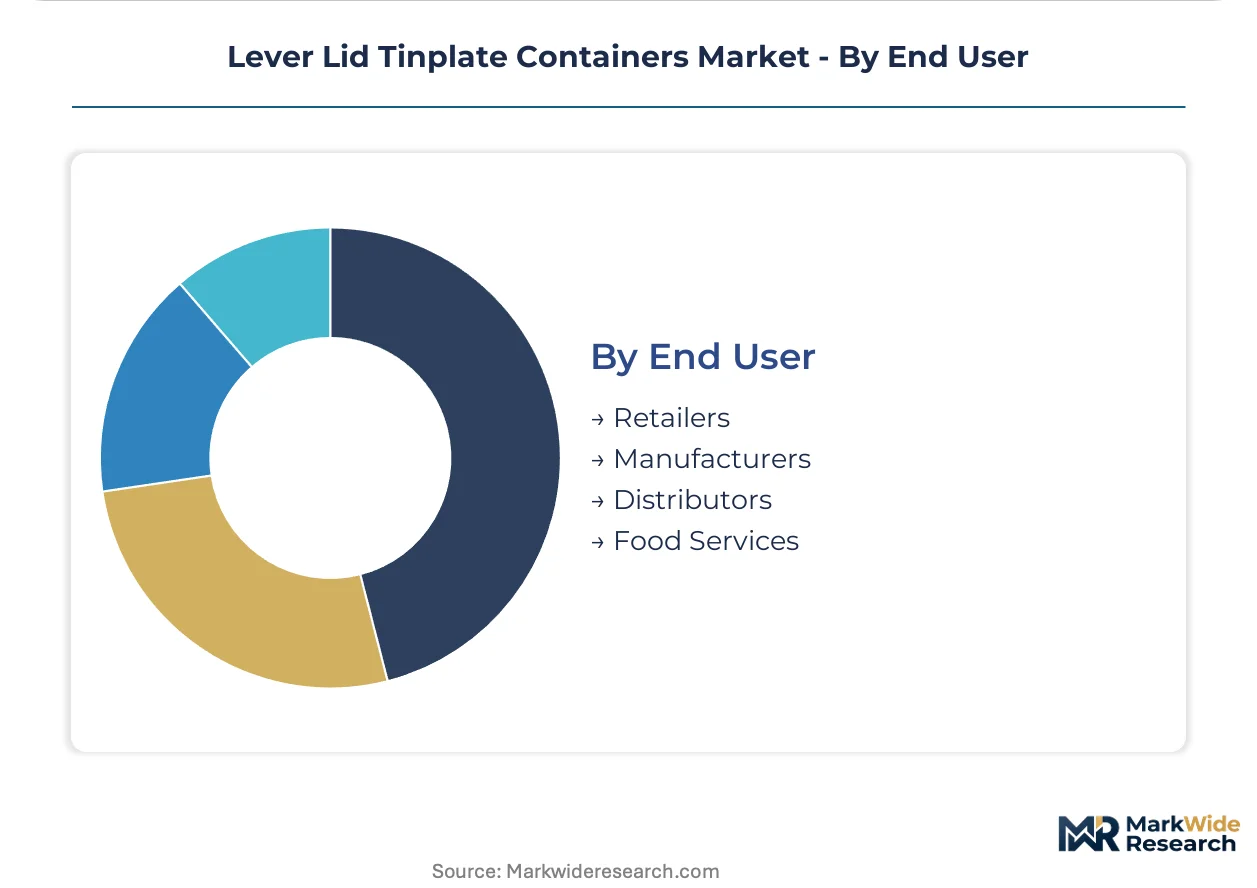
End User:
Specification authority concentration determines channel structure and margin capture.
- Manufacturers:Brand-owning food producers with in-house regulatory affairs functions now specify containers directly with converters, bypassing traditional packaging distributors. Direct relationships with Invopak and comparable decorators enable custom embossing and dimensional formats unavailable through catalog wholesalers.
- Food Services:Commercial kitchen operators seeking stackable geometry and efficient storage density.
- Retailers:Private label programs with standardized specifications and volume commitments.
- Distributors:Traditional packaging wholesalers facing disintermediation pressure from direct sourcing trends.
Manufacturers concentrate specification authority; Food Services represent the steepest expansion trajectory in extra deep formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Regions and Delhi-Mumbai Industrial Corridor tax incentives concentrate tinplate converting capacity near Hazira and Mundra ports. German industrial zones in Bavaria and North Rhine-Westphalia leverage REACH compliance infrastructure to capture premium specification orders.
United States
Artisan sauce producers and craft preserve makers in the Pacific Northwest and Northeast corridor specify direct-to-converter relationships for custom embossing. FDA food-contact substance notifications govern tinplate migration limits for acidic contents, tightening testing protocols annually. Chicago-area metal forming clusters supply food service bulk formats to institutional buyers seeking stackable storage geometry.
Germany
Specialty condiment manufacturers in Bavaria specify asymmetric tin coatings with heavier interior deposition for acid resistance. REACH Annex XVII restrictions on phthalates and bisphenols force continuous lacquer reformulation across converter supply chains. The Stuttgart industrial corridor anchors advanced internal coating capabilities that filter substandard competitors from premium specification tiers.
India
Domestic preserve brands and bulk chemical distributors in Maharashtra and Gujarat expand procurement of certified tinplate closures. BIS certification requirements for food-grade metal packaging tighten testing protocols for tin coating uniformity and solder seam integrity. Hazira port-adjacent converting facilities capture demand from exporters seeking compliance documentation for European and North American destinations.
United Kingdom
Premium preserve makers and specialty food brands in the Midlands and Southeast specify lever lid formats with tamper-evident metal seals. Evolving packaging waste regulations align with extended producer responsibility schemes favoring infinitely recyclable substrates. Manchester-area contract packers consolidate specification authority through in-house regulatory affairs functions that bypass traditional distributor channels.
China
Export-oriented condiment processors in Guangdong and Zhejiang provinces specify tinplate closures for markets with strict migration limit requirements. GB standards for food-contact metal packaging converge with international protocols to reduce technical barriers. Yangtze River Delta fabricators invest in differential coating technology to unify corrosion performance and decoration economics in single substrate specifications.
Lever Lid Tinplate Containers Market Competitive Landscape
Top-tier vendors anchor premium specification tiers, while mid-scale converters compete on batch flexibility and regional logistics. The vendor base stratifies across integrated metal formers with captive coating capabilities, specialized decorators with digital printing convergence, and commodity cylinder producers serving price-sensitive chemical applications. Two competitive moves dominate: direct sourcing relationships that disintermediate traditional packaging distributors, and backward integration into electrolytic tinplate slitting to control substrate cost volatility.
Among UK-based fabricators, Invopak and Taylor Davis Ltd occupy positions within the contract supply tier for condiment and preserve makers. HUBER Packaging Group GmbH represents the continental European archetype with specialized printing capabilities. Trivium Packaging sits within the integrated metal forming segment spanning beverage and industrial applications.
| Leading Market Players |
|---|
| Invopak |
| RLM Packaging Ltd |
| HUBER Packaging Group GmbH |
| Taylor Davis Ltd |
| Central Tin Containers Ltd |
| Pirlo Holding GmbH |
| Quitmann O'Neill Packaging Limited |
| Mauser Packaging Solutions |
| Trivium Packaging |
| Others |
Supply & Pricing Matrix
REACH Annex XVII phthalate restrictions are forcing specialty food producers to abandon polymer closures and specify tinplate alternatives with documented migration profiles, compelling converters to absorb reformulation costs while buyers with in-house regulatory functions capture pricing leverage.
Pricing Analysis
Short-lead-time premiums dominate contract negotiations as artisan preserve makers in the United Kingdom and craft sauce producers in the United States pay markups for batch-size flexibility unavailable through catalog distributors. Pricing stratifies across premium, standard, and economy tiers based on tin coating weight asymmetry and internal lacquer specification complexity. Cost compression in standard containers intensifies as Indian bulk chemical distributors consolidate procurement volumes and squeeze converter margins. Food service institutional buyers exhibit lowest price sensitivity due to palletized distribution economics and stackable geometry requirements.
Supply Chain Analysis
Freight cost differentials favor port-adjacent converting capacity near Hazira and Mundra in India, Bavarian industrial zones in Germany, and Chicago-area metal forming clusters in the United States. Raw material flows draw from electrolytic tinplate steel producers in China, Japan, and South Korea, with tin metal sourcing anchored in Indonesian and Peruvian mining operations. Single-source vulnerability concentrates in advanced internal lacquering capabilities clustering in Germany and the United Kingdom. Distribution runs through direct sourcing relationships that disintermediate traditional packaging wholesalers for premium specification tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance fragmentation is accelerating consolidation as smaller converters lack capital for simultaneous FDA notification, REACH registration, and BIS certification processes.
For Market Incumbents: Deploy backward integration into electrolytic tinplate slitting to control substrate cost volatility from tin metal price swings. Anchor premium positioning through captive coating capabilities in differential tin deposition technology that filters substandard competitors from specification tiers demanding asymmetric corrosion performance. For New Entrants and Emerging Players: BIS certification tightening in India opens a window for domestic converters with testing infrastructure to capture share from filtered import competitors. Target food service extra deep formats where retail-sized catalog offerings remain underpenetrated and stackable geometry commands procurement loyalty. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale decorators possessing digital printing convergence capabilities given direct-to-metal decoration demand from artisan brands collapsing minimum order quantities. Watch differential coating technology adoption rates as the inflection signal separating premium specification capture from commodity margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Tinplate Slitting | Captive substrate supply insulates converter margins from LME tin volatility and steel input swings. |
| Differential Coating Technology Investment | Asymmetric tin deposition unifies corrosion performance and decoration economics in single inventory positions. |
| Digital Printing Convergence Deployment | Direct-to-metal decoration collapses MOQs and enables mass customization for artisan preserve brands. |
| Food Service Extra Deep Format Expansion | Commercial kitchen stackable geometry captures procurement volume absent from retail catalog offerings. |
| Multi-Jurisdiction Regulatory Affairs Buildout | In-house FDA, REACH, and BIS capabilities consolidate specification authority and bypass distributor channels. |
Research Methodology
Multi-period observation of tin coating weight specifications, internal lacquer formulation shifts, and direct sourcing relationship formation anchored the trend analysis, supplemented by interviews with tinplate converter plant managers, specialty food brand procurement leads, packaging distributor channel partners, and regulatory affairs directors at contract packers. Secondary validation drew from ECHA REACH registration databases, FDA food-contact substance notification filings, BIS certification records, and customs trade data for electrolytic tinplate steel flows. Bottom-up volume triangulation across product type and application segments was cross-checked against top-down value estimates from converter revenue disclosures.
Segment-weighting approaches distributed value and volume across standard, specialty, and extra deep container formats by tin coating asymmetry, internal lacquer chemistry tier, and end-use regulatory exposure intensity. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window. Industry-specific forecast inputs included REACH Annex XVII substance restriction implementation timelines and BIS testing protocol enforcement trajectories.
The model assumes a particular technology adoption path for differential coating deposition; alternative pathways for internal lacquer formulation chemistry would alter the outlook if polymer science talent scarcity accelerates or resolves. Forecasts reflect documented assumptions around regulatory compliance burden trajectories and substrate cost volatility parameters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Intermediate Bulk Container (IBC) Market
Containers
Stackable Plastic Trays Market
Containers
Die Cut Display Container Market
Containers
Canisters Market
Containers
Metal Crates Market
Containers
Durable Insulated Containers Market
Containers
Conipack Pails Market
Containers
Single Wall Jars Market
Containers
Acrylic Container Market
Containers
Modular Container Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Metal IBC Market
Containers
Flexible Water Tanks Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Slide Top Tins Market
Containers
Light Resistant Containers Market