
 Compartment Trays Market | 2026-2036
Compartment Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Compartment Trays Market Outlook
Skilled thermoforming technicians is rotating toward biodegradable polymer processing as converters retool for next-generation material specifications. Huhtamaki leverages its European molded fiber infrastructure to capture premium foodservice contracts. Pactiv Evergreen sustains dominant North American channel control through direct distributor relationships. Sonoco Products Company anchors its position with specialized medical-grade cleanroom tray production.
Compartment trays are rigid, multi-cavity containers engineered with precise cell dimensions, wall thickness tolerances, and surface finish specifications to separate, protect, and present discrete items during storage, transport, or display. They are thermoformed, injection-molded, or pressed from substrates including PET, PP, molded pulp, aluminum, or bagasse fiber to meet dimensional stability and barrier requirements across temperature ranges from frozen distribution to autoclave sterilization. Plastic material types still occupy the largest volume share due to cost efficiency and processing versatility, though biodegradable segments are gaining fastest as EU regulatory deadlines approach and brand owners commit to packaging reduction targets. Medical application demand leads in per-unit margin contribution because of validation requirements and cleanroom manufacturing overhead, while foodservice remains the absolute volume anchor across global markets.
FDA food contact substance notifications govern polymer selection and migration limits for U.S. medical and foodservice tray applications, while EU REACH and the Packaging and Packaging Waste Regulation constrain substance restrictions and mandate recyclability targets that reshape material R&D priorities. Stakeholders must monitor evolving extended producer responsibility frameworks and biodegradability certification standards as these compliance layers increasingly determine supplier qualification and market access eligibility.
Market Dynamics
EU REACH substance restrictions and the Packaging and Packaging Waste Regulation are forcing converters to abandon legacy polymers and revalidate entire product lines before 2030 compliance deadlines.
Growth Catalysts
- Healthcare Logistics Standardization:Hospital networks and pharmaceutical distributors are adopting ISO-certified compartment trays to reduce contamination risk and streamline sterile supply chain handling.
- REACH Compliance Deadlines:The EU Packaging and Packaging Waste Regulation mandates recyclability targets that accelerate R&D investment in mono-material and fiber-based tray architectures.
- Molded Fiber Infrastructure:European converters are retooling thermoforming lines to process bagasse and bamboo pulp, capturing premium foodservice contracts from sustainability-focused QSR chains.
Market Restraints
- Petrochemical Feedstock Volatility:Propylene and ethylene price swings compress margins for PP and PET tray producers who lack long-term supply contracts.
- Cleanroom Validation Overhead:Medical-grade tray manufacturing requires ISO 14644-1 Class 7 certification and 18-month FDA 510(k) timelines that deter new entrants.
- Aluminum Substitution Threat:Recyclable aluminum compartment trays are capturing frozen ready-meal applications where barrier performance outweighs cost premiums.
Strategic Opportunities
- Central European Manufacturing Corridor:Germany's industrial packaging cluster offers co-location advantages for converters serving pharmaceutical distribution hubs in Switzerland and the Netherlands.
- Biodegradable Polymer Convergence:PLA-PBAT blends processed on modified PET thermoforming lines enable drop-in replacement for fossil-based medical trays with comparable dimensional stability.
- Direct Hospital Procurement Platforms:Group purchasing organizations are consolidating sterile packaging spend, creating channel access for qualified tray suppliers with validated ERP integration.
Industry Challenges
- Thermoforming Technician Scarcity:Skilled operators capable of calibrating multi-zone heating profiles for bio-based polymers command 40% wage premiums and 6-month recruitment cycles.
- Legacy Tooling Obsolescence:Existing aluminum molds designed for amorphous PET degrade faster when processing crystalline PLA, forcing capital-intensive retooling decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compartment Trays Market |
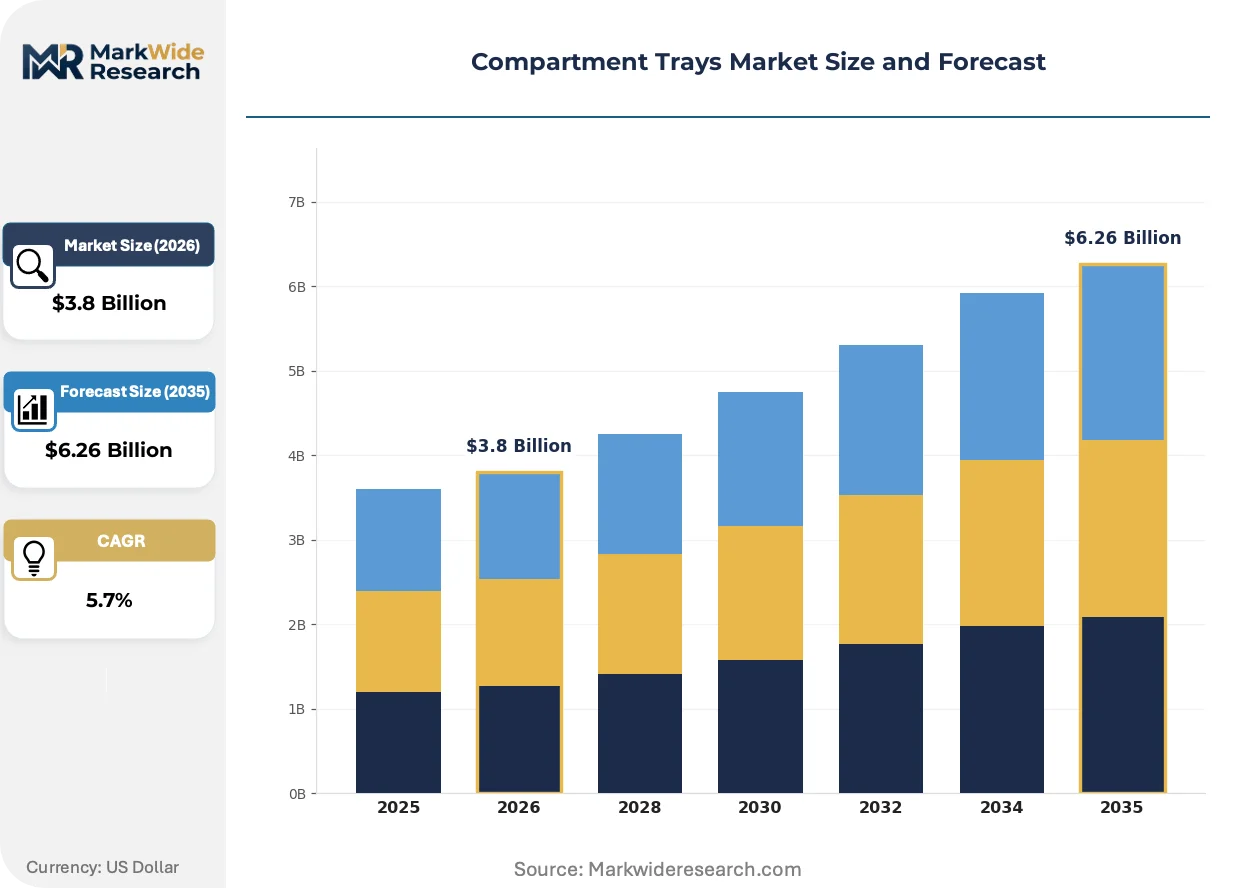
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood, Metal, Biodegradable Application: Foodservice, Retail, Medical, Hospitality Distribution Channel: Online, Offline, Direct Sales, Wholesale Size: Small, Medium, Large, Custom |
| Companies Covered | Huhtamaki, Pactiv Evergreen, Novolex, Amcor, Sonoco Products Company, Genpak, Anchor Packaging, Sealed Air, Cascades, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compartment Trays Market Strategic Shifts
Material science breakthroughs and regulatory compression timelines are converging to reshape competitive positioning across medical, foodservice, and industrial end-uses.
Molded fiber thermoforming is displacing conventional plastic compartment trays in temperature-stable foodservice applications. Major European QSR chains are specifying fiber-based solutions for ambient and chilled distribution. The technology is displacing PS and PP volumes in catering and institutional channels where moisture barrier requirements permit fiber substitution.
REACH Annex XVII substance restrictions are eliminating certain phthalates and heavy metal catalysts from food contact polymers. Tray converters must reformulate masterbatches and resubmit migration test data to EFSA. Medical device manufacturers face the steepest compliance burden, as notified body reviews extend validation timelines by 8-12 months.
Hospital supply chain managers are consolidating sterile packaging vendors through outcome-based contracting models that bundle tray supply with inventory management and waste reduction guarantees. This procurement evolution compresses supplier rosters to 2-3 qualified partners per category. German university hospital networks are pioneering these integrated sourcing arrangements, with Austrian and Swiss facilities adopting similar frameworks.
Compartment Trays Market Segmentation
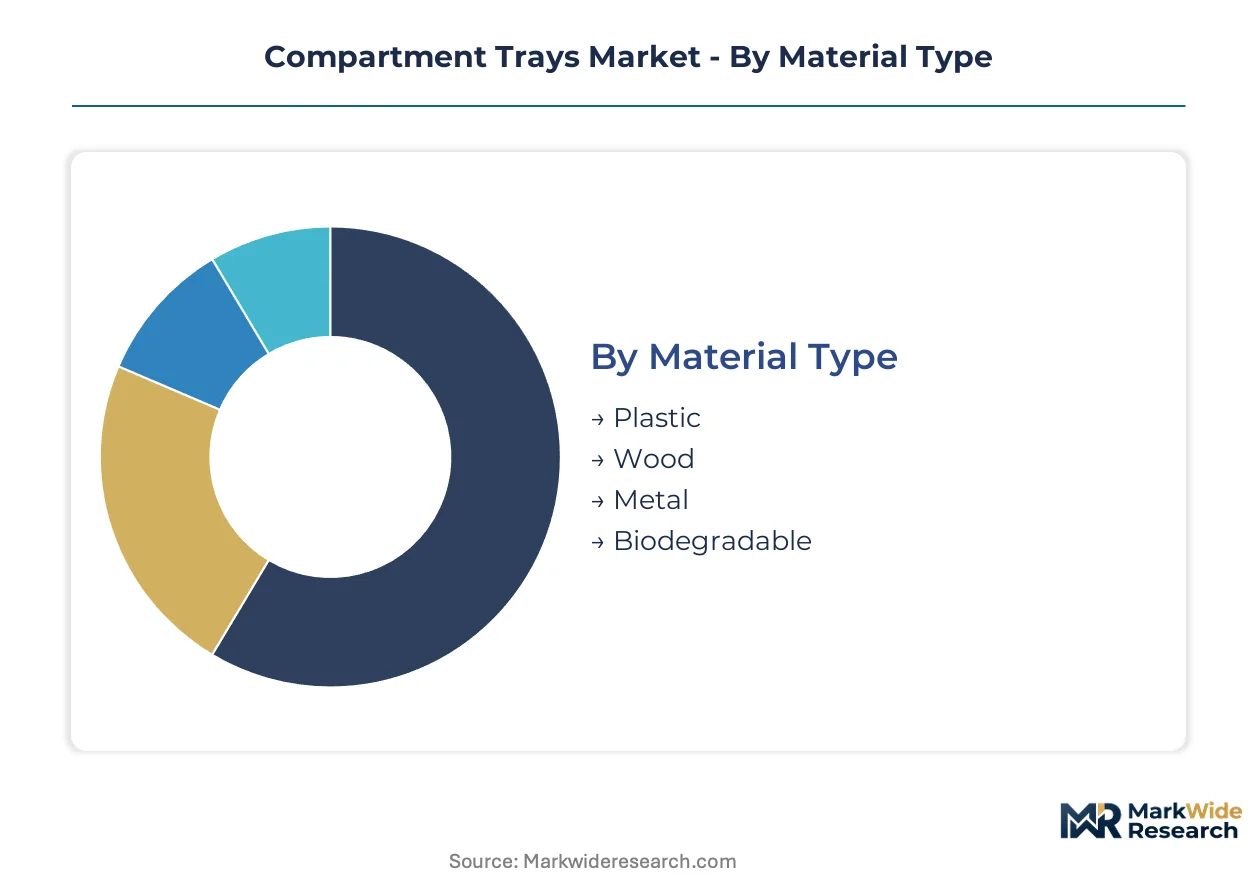
Compartment tray procurement diverges sharply by end-use validation requirements and regulatory exposure. Material selection and distribution channel strategy must align with specific compliance frameworks governing food contact, medical device sterility, or retail display durability.
Material Type:
FDA food contact substance notifications and EU REACH Annex XVII substance restrictions create divergent qualification pathways for polymer families, while biodegradable segments face evolving compostability certification demands.
- Plastic:PET and PP thermoformed trays dominate absolute volume through cost efficiency and processing versatility. Hospital networks in Germany and pharmaceutical distributors in Switzerland specify medical-grade PP for autoclave sterilization cycles.
- Biodegradable:PLA-PBAT blends and bagasse fiber formulations are capturing premium foodservice contracts as EU Packaging and Packaging Waste Regulation deadlines approach. QSR chains across Central Europe now mandate fiber-based solutions for ambient distribution.
- Metal:Aluminum compartment trays serve frozen ready-meal applications where barrier performance and recyclability outweigh cost premiums.
- Wood:Pressed fiber and bamboo composites address specialty catering and institutional channels with moderate moisture exposure.
Established volume favors Plastic; emerging adoption favors Biodegradable.
Application:
Per-unit margin structure varies by validation intensity, with medical applications commanding premium pricing for cleanroom manufacturing overhead.
- Medical:ISO 14644-1 Class 7 cleanroom production and FDA 510(k) validation timelines create steep entry barriers. German university hospital networks consolidate sterile packaging spend through outcome-based contracting.
- Foodservice:Absolute volume anchor across global markets, spanning QSR chains, institutional catering, and airline meal service. Temperature stability requirements drive material selection from frozen distribution to hot-hold applications.
- Retail:Display-ready trays for electronics, cosmetics, and consumer goods emphasize visual presentation and theft deterrence.
- Hospitality:In-room dining and banquet service applications prioritize stackability and microwave compatibility.
Medical commands the steepest margin premium; Foodservice anchors absolute volume scale.
Distribution Channel:
Channel control patterns reflect customer scale and integration requirements, with large healthcare systems bypassing intermediaries.
- Direct Sales:Group purchasing organizations and hospital networks consolidate sterile packaging procurement through validated ERP integration.
- Wholesale:Foodservice distributors maintain broad SKU availability for regional restaurant chains and institutional buyers.
- Offline:Traditional packaging distributors serve mid-market manufacturers with technical specification support.
- Online:E-procurement platforms gain traction for standardized SKUs with predictable replenishment cycles.
Direct Sales captures the highest-margin medical contracts; Wholesale retains foodservice volume leadership.
Size:
Dimensional standardization versus customization trade-offs determine tooling amortization and production economics.
- Custom:Medical device manufacturers specify precise cell dimensions and wall thickness tolerances for surgical instrument sets.
- Large:Industrial component packaging and catering platters require reinforced structures for heavy-load distribution.
- Medium:Standard meal tray formats balance material efficiency with functional compartment separation.
- Small:Single-serve condiment and pharmaceutical dose packaging emphasize portion control and tamper evidence.
Custom specifications dominate medical validation requirements; Medium formats anchor foodservice standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial packaging corridor processes compartment trays for pharmaceutical distribution at specifications exceeding foodservice norms elsewhere. Swiss hospital networks demand ISO 14644-1 Class 7 cleanroom validation that Central European converters struggle to replicate. France's QSR chains specify molded fiber solutions under EU Packaging and Packaging Waste Regulation timelines that outpace North American sustainability commitments.
United States
FDA food contact substance notifications govern polymer selection for medical and foodservice tray applications across hospital networks and QSR chains. The agency's migration limits and 510(k) validation timelines create compliance overhead that domestic converters absorb through scale. Chicago-area distributors maintain direct relationships with Pactiv Evergreen for foodservice volume, while Minnesota-based medical packaging clusters serve sterile supply chains.
Germany
Hospital networks in Baden-Württemberg and Bavaria consolidate sterile packaging procurement through outcome-based contracting with validated ERP integration. ECHA REACH Annex XVII substance restrictions eliminate legacy phthalates from food contact polymers, forcing masterbatch reformulation. The Stuttgart industrial corridor hosts thermoforming specialists retooling for PLA-PBAT blend processing to meet 2030 regulatory deadlines.
Switzerland
Swissmedic medical device regulations mandate cleanroom manufacturing standards that exceed EU MDR baseline requirements for surgical instrument trays. University hospital networks in Zurich and Geneva pioneer integrated sourcing arrangements bundling tray supply with inventory management. Basel's pharmaceutical distribution hubs require dimensional stability specifications that filter supplier qualification to three qualified partners per category.
Netherlands
Rotterdam's port logistics cluster drives demand for temperature-stable compartment trays in pharmaceutical cold chain distribution. The Dutch national packaging covenant accelerates mono-material and fiber-based tray R&D ahead of EU-wide mandates. Eindhoven's high-tech manufacturing zone sources anti-static trays for electronics assembly with surface finish specifications distinct from medical or foodservice applications.
France
ANSM pharmaceutical packaging guidelines constrain material selection for hospital sterile supply chains in Île-de-France and Auvergne-Rhône-Alpes. QSR chains across the country mandate bagasse fiber solutions for ambient distribution under corporate sustainability commitments. Lyon-based catering distributors specify microwave-compatible compartment formats that diverge from German autoclave-sterilization preferences.
Compartment Trays Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in compartment tray manufacturing. The upper tier commands direct distributor relationships and validated cleanroom infrastructure. The specialist tier competes on material innovation and regional logistics proximity. Three archetypes dominate: diversified packaging conglomerates with thermoforming scale, fiber-based sustainability specialists, and medical-grade cleanroom operators. Competitive moves concentrate on capacity expansion in Central European corridors and strategic partnerships with group purchasing organizations.
Among diversified packaging conglomerates, Huhtamaki and Pactiv Evergreen occupy positions reflecting distinct geographic emphases. Huhtamaki leverages its European molded fiber infrastructure to capture premium foodservice contracts under tightening EU regulatory deadlines. Pactiv Evergreen sustains dominant North American channel control through direct distributor relationships with QSR chains and institutional buyers. Sonoco Products Company anchors the medical-grade tier with specialized cleanroom tray production capabilities that hospital networks specify for sterile supply chain validation.
| Leading Market Players |
|---|
| Huhtamaki |
| Pactiv Evergreen |
| Novolex |
| Amcor |
| Sonoco Products Company |
| Genpak |
| Anchor Packaging |
| Sealed Air |
| Cascades |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) validation timelines and EU MDR cleanroom certification requirements gate both supplier qualification and price differentiation simultaneously. Medical-grade tray producers command substantial premiums for ISO 14644-1 Class 7 infrastructure that foodservice converters cannot replicate. Buyers face tiered access where validation intensity directly determines available supply base and contract terms.
Pricing Analysis
Long-term offtake agreements dominate medical tray procurement through group purchasing organizations, while spot purchasing persists in foodservice channels. Three-tier pricing structure across premium, standard, and economy levels reflects cleanroom certification grade, volume scale, and geographic delivery cost. Cost compression in standard-grade foodservice tiers is intensifying because of petrochemical feedstock volatility. Institutional catering buyers exhibit highest price sensitivity; Swiss hospital networks show lowest sensitivity due to sterility validation requirements.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp corridors elevates inbound logistics costs for German thermoforming converters sourcing PLA resin from North American suppliers. Supply concentrates in Germany, Switzerland, and the Netherlands for medical-grade production; China and Thailand dominate molded fiber raw material extraction. Raw material dependencies include propylene for PP trays, bagasse pulp for fiber solutions, and aluminum coil stock for barrier applications. Single-source vulnerability in biopolymer resin supply creates structural risk. Distribution runs through direct hospital procurement platforms for medical applications and wholesale foodservice distributors for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified thermoforming technicians capable of calibrating multi-zone heating profiles for bio-based polymers represent a binding constraint across European manufacturing corridors. This capability scarcity limits capacity expansion regardless of capital availability.
For Market Incumbents: Secure long-term resin supply contracts to hedge propylene and ethylene price volatility threatening PP and PET tray margins. Expand molded fiber capacity in Germany's industrial corridor before EU Packaging and Packaging Waste Regulation deadlines eliminate qualified competitor supply. Vertical integration into bagasse pulp processing reduces raw material exposure. For New Entrants and Emerging Players: Differentiate on biodegradable polymer processing expertise to capture premium foodservice contracts from sustainability-focused QSR chains in France and Central Europe. Target Austrian and Swiss hospital networks adopting integrated sourcing arrangements with fewer qualified suppliers per category. Pursue direct ERP integration with group purchasing organizations as primary go-to-market channel. For Investors and Strategic Acquirers: EU REACH Annex XVII substance restrictions and 2030 packaging recyclability mandates reshape the acquisition landscape toward converters with validated mono-material and fiber-based tray architectures. Five-to-ten-year viability favors specialists with backward integration into pulp processing or captive biopolymer compounding. Watch for EFSA migration test data resubmission timelines as inflection indicator for medical tray producer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644-1 Class 7 certification enables Swissmedic-compliant surgical tray production for Basel pharmaceutical hubs. |
| Biopolymer Compounding Integration | In-house PLA-PBAT blend production reduces ECHA REACH compliance risk and raw material cost exposure. |
| Hospital GPO Partnership | Validated ERP integration with German university hospital networks locks out competitor access through outcome-based contracting. |
| Molded Fiber Line Retooling | Bagasse and bamboo pulp processing capability captures ANSM-mandated sustainable packaging contracts in French QSR channels. |
| Aluminum Barrier Tray Development | Recyclable frozen ready-meal formats defend against substitution threat in Netherlands retail distribution. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with thermoforming plant managers, hospital procurement directors, pharmaceutical distribution logistics heads, and ECHA regulatory affairs specialists; and secondary validation through FDA 510(k) filings, EU MDR notified body records, customs trade data for polymer resin movements, and GPO contract disclosure databases. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures across material type and application segments.
Across the analysis window, forecasts incorporate segmentation by material substrate, end-use validation intensity, distribution channel integration depth, and regional regulatory cluster. CAGRs derive from weighted capacity expansion announcements, substitution elasticity estimates for biodegradable alternatives, and hospital network procurement consolidation patterns. Industry-specific inputs include thermoforming line retooling timelines and EFSA migration test resubmission backlogs.
The analysis sits within stated boundaries; outcomes outside maintained EU regulatory deadlines, stable petrochemical feedstock availability, and continued hospital network consolidation would require recalibration. Forecasts reflect documented assumptions regarding cleanroom certification capacity expansion and biopolymer resin supply scalability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Belgium Container Glass Market
Containers
Collapsible Sleeve Containers Market
Containers
Conipack Pails Market
Containers
Europe Plastic Bottles and Containers Market
Containers
EMEA Container Technology Market
Containers
Reconditioned IBC Market
Containers
Popcorn Containers Market
Containers
PS Containers Market
Containers
Screw Top Jar Market
Containers
Stack and Nest Containers Market
Containers
North America Plastic Bottles and Containers Market
Containers
Corrugated Bin Boxes Market
Containers
HDPE Crates Market
Containers
Rotomolded Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Laminated Bulk Bins Market