
 Collapsible Food Packaging Containers Market | 2026-2036
Collapsible Food Packaging Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Food Packaging Containers Market Analysis
Packaging engineering talent scarcity is bifurcating the competitive landscape into firms that can design for circularity and those trapped in linear models. SKI Plastoware Private Limited leverages its South Asian manufacturing base to compete on cost for foldable polyethylene designs. WestRock Company anchors North American supply through integrated paperboard and corrugated collapsible formats. DS Smith plc specializes in retail-ready nestable containers that reduce last-mile cube utilization.
Collapsible food packaging containers are engineered storage and transport vessels designed to fold, nest, or compress when empty, typically constructed from polypropylene, polyethylene, or corrugated fiberboard with wall thicknesses calibrated for 50–100 reuse cycles in closed-loop distribution. Their primary function is to cut reverse logistics costs and warehouse cube requirements for perishable and dry food movements. Plastic containers dominate current volume due to durability and washability in commercial food service, while paper containers capture fastest growth in e-commerce grocery where single-use presentation and lightweight returnability converge. Nestable designs command premium positioning in catering and institutional feeding, whereas foldable formats penetrate retail back-of-house replenishment where space constraints are acute.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications jointly shape material selection and migration testing protocols, with REACH compliance adding substance restriction layers for colorants and stabilizers in European circulation. The EU Green Deal's packaging minimization targets are forcing reformulation of multi-material laminates toward recyclable mono-structures. Stakeholders must decide whether to prioritize asset-pooling network density or material certification breadth as the decisive capability gap.
Market Dynamics
Meal-kit delivery services are forcing a wholesale redesign of returnable packaging economics, collapsing the payback period thresholds that previously favored single-use formats and triggering capital redeployment toward pooling infrastructure.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory material recovery targets are accelerating mono-material polypropylene adoption across centralized European distribution networks.
- Reverse logistics cost compression:Foldable polyethylene designs cut empty-haul cube utilization by over sixty percent for perishable food distributors operating tight-margin routes.
- Germany's pooling standardization:Centralized food distribution networks in this market favor standardized collapsible systems that enable inter-operator compatibility and asset sharing.
Market Restraints
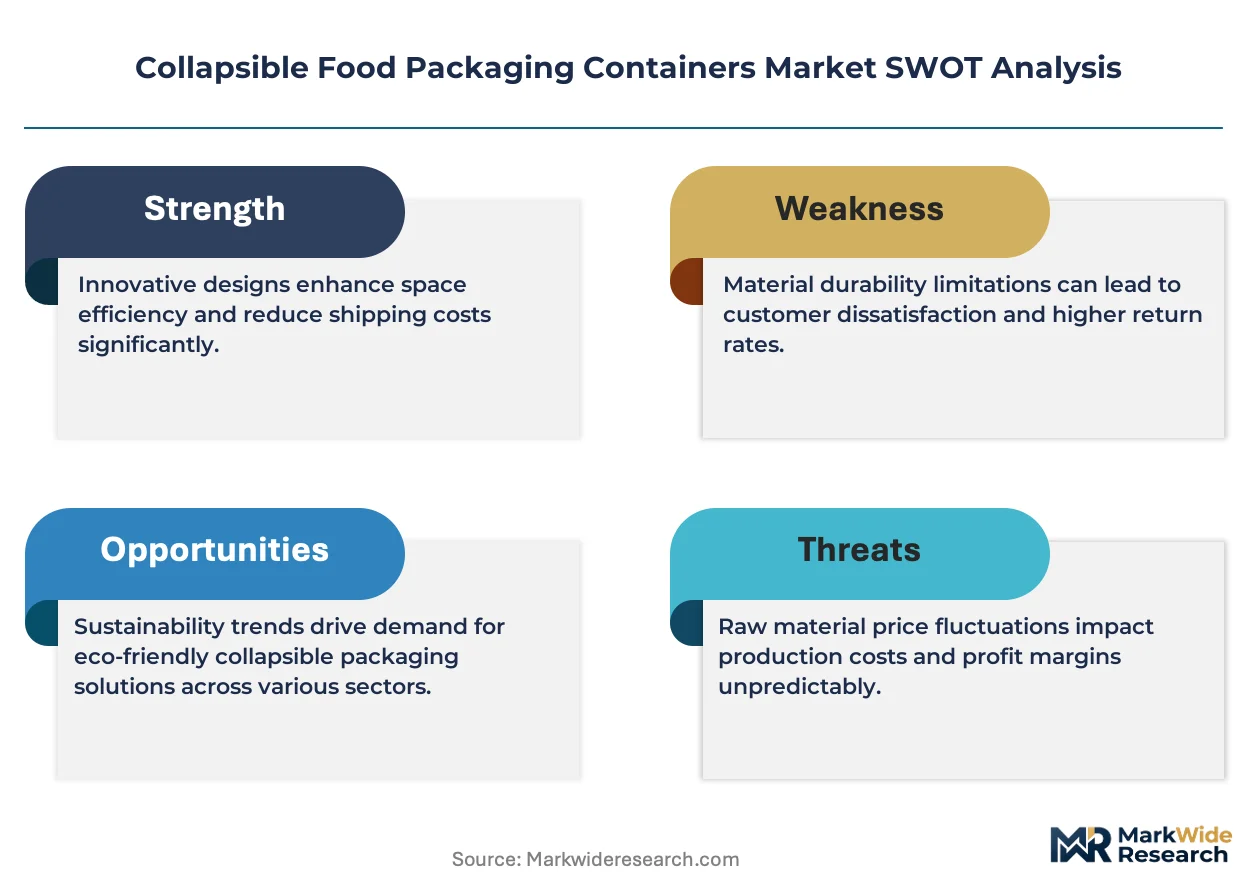
- Polypropylene price volatility:Feedstock cost swings tied to naphtha cracking margins compress converter margins and deter long-term pooling contracts.
- REACH substance restrictions:Colorant and stabilizer compliance layers add testing burden and timeline risk for European circulation assets.
- Corrugated fiberboard substitution:Single-use paper formats capture e-commerce grocery volume where washability requirements are absent and presentation value dominates.
Strategic Opportunities
- India's cold chain expansion:Underdeveloped returnable infrastructure in this market creates first-mover positioning for foldable container operators targeting horticultural export consolidation.
- FDA food contact notification harmonization:Streamlined migration testing protocols could unlock cross-border asset pooling between North American and select Asia-Pacific jurisdictions.
- RFID-embedded traceability:Convergence of polymer molding with IoT tagging enables cycle-count automation and damage-liability attribution in multi-user pooling networks.
Industry Challenges
- Circularity engineering talent scarcity:Packaging design-for-recovery expertise concentrates in Western European and North American technical institutes, constraining converter capability in emerging manufacturing hubs.
- Multi-jurisdiction certification timelines:Parallel FDA notification and EU compliance pathways extend product launch windows by twelve to eighteen months for global format launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Food Packaging Containers Market |
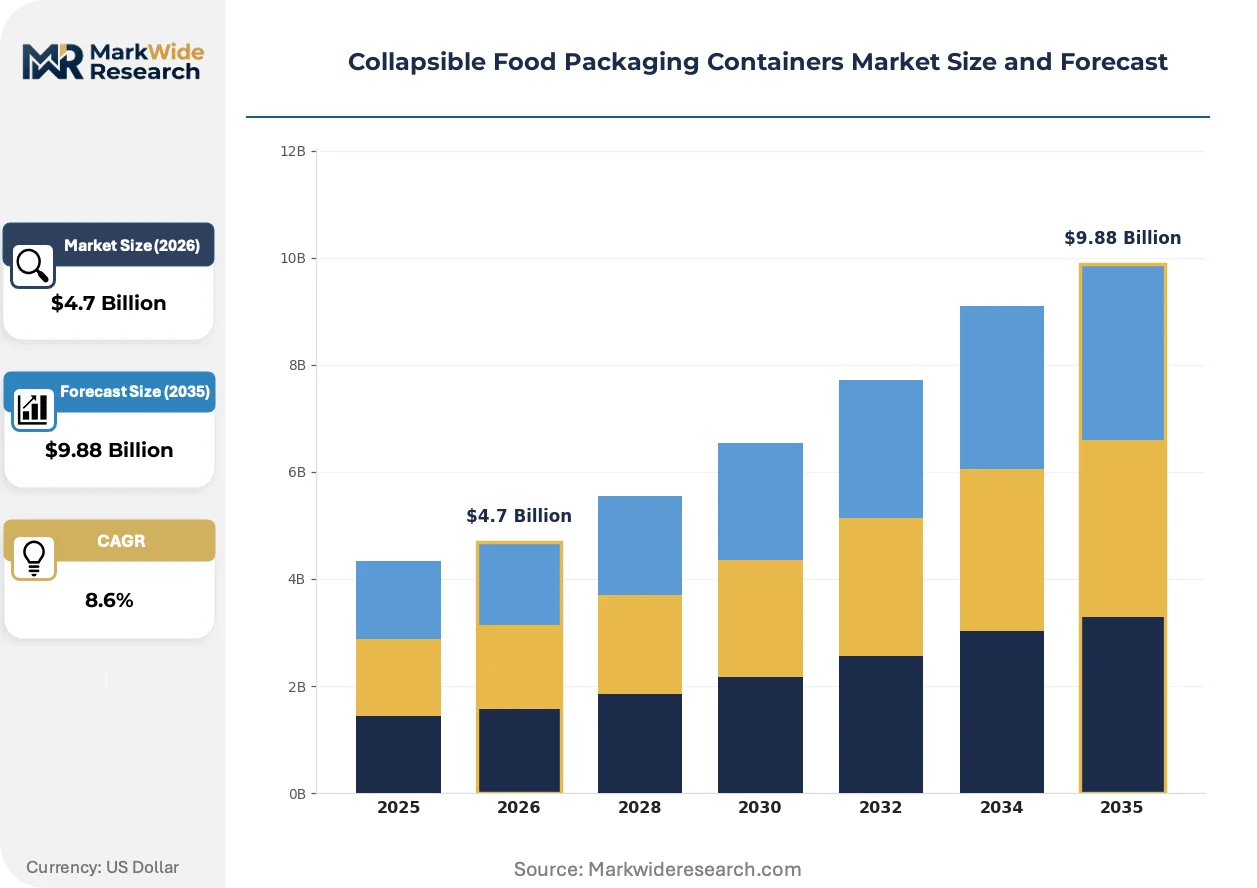
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Paper Containers, Metal Containers, Glass Containers End User: Food Service, Retail, E-commerce, Catering Material: Polyethylene, Polypropylene, Cardboard, Aluminum Design Style: Stackable, Nestable, Foldable, Reusable |
| Companies Covered | SKI Plastoware Private Limited, Jaycoplastic, WestRock Company, Schoeller Allibert, ORBIS Corporation, Brambles Limited, DS Smith plc, Plastor Ltd, Rehrig Pacific Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Food Packaging Containers Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing the viable design space for collapsible food packaging, favoring formats that satisfy multiple compliance regimes simultaneously.
Mono-material polypropylene constructions are decomposing the legacy multi-layer barrier formats that previously dominated hot-fill and extended-shelf-life applications. Institutional foodservice operators in Germany and the Netherlands are adopting these designs at accelerated pace to preempt EU Green Deal packaging minimization enforcement. The structural consequence is decomposing the historical trade-off between barrier performance and mechanical durability that trapped converters in non-recyclable laminates.
REACH substance restriction expansions are forcing reformulation of colorants and UV stabilizers across European circulation assets. Industrial consequence includes migration toward in-mold labeling and laser-etched identification to eliminate adhesive layers and printed ink systems. Nestable container segments serving catering and institutional feeding are responding fastest, with several operators eliminating external decoration entirely to secure compliance certainty.
Buyer concentration among meal-kit delivery platforms is compressing supplier negotiation cycles and unbundling after-sales service expectations. These platforms now demand real-time asset tracking and damage liability transfer protocols that legacy pooling operators cannot satisfy. The shift is most visible in North American urban corridors where platform density justifies dedicated container fleets with embedded telemetry.
Collapsible Food Packaging Containers Market Segmentation
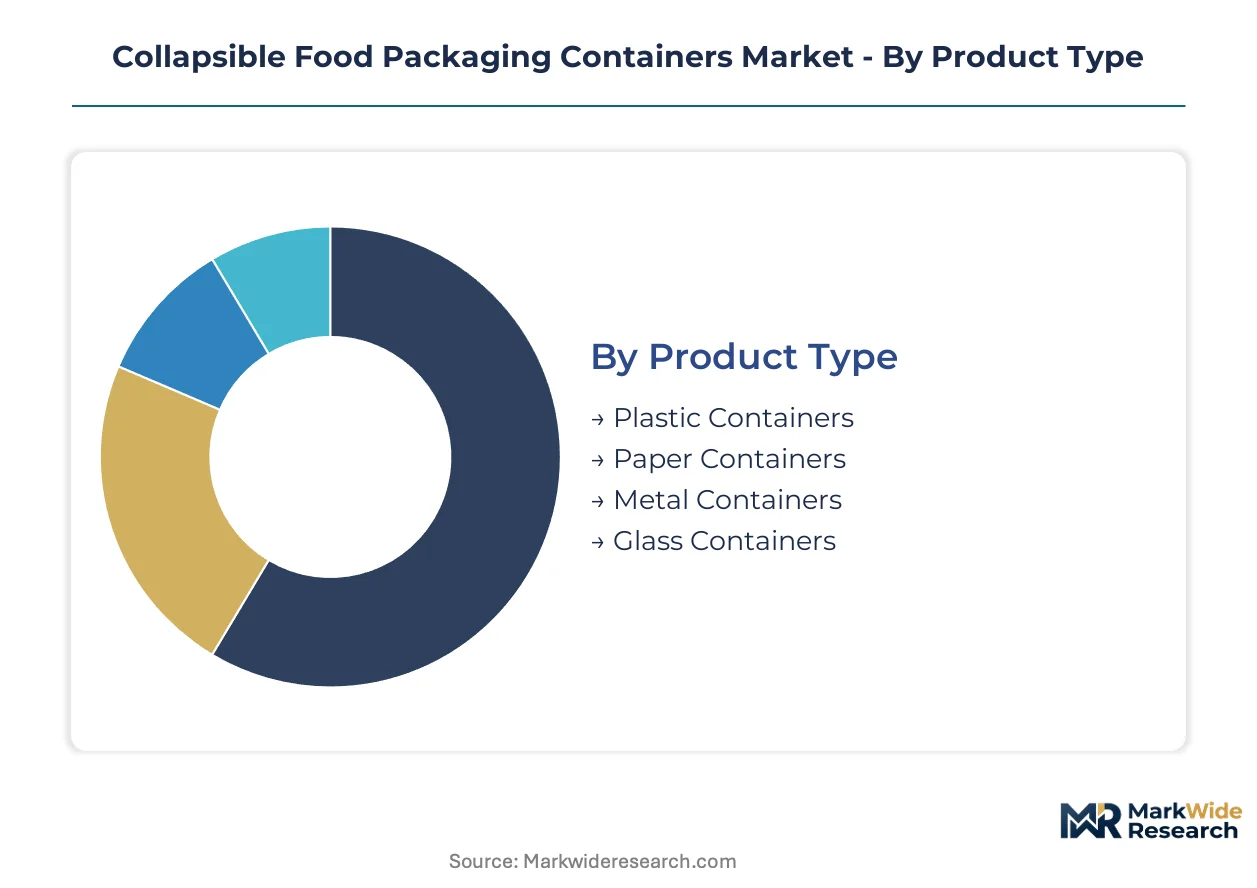
Segmentation in collapsible food packaging containers reveals how material science, logistics economics, and regulatory compliance intersect. Each dimension exposes different competitive moats and capital deployment priorities for converters and pooling operators.
Product Type:
Plastic containers dominate domestic circulation across Germany and the Netherlands where washing infrastructure supports reuse economics. Paper formats concentrate in export-oriented e-commerce corridors serving UK and French grocery platforms.
- Plastic Containers:Polypropylene and polyethylene constructions withstand 50–100 commercial wash cycles. German institutional foodservice operators deploy these in standardized pooling systems to preempt EU Green Deal enforcement.
- Paper Containers:Corrugated fiberboard and molded pulp designs collapse flat for lightweight returnability. UK e-commerce grocery platforms favor these where single-use presentation outweighs durability requirements.
- Metal Containers:Aluminum and stainless-steel formats serve premium catering segments requiring thermal retention.
- Glass Containers:Borosilicate and tempered glass variants occupy niche artisan food preservation markets.
Plastic containers hold the largest share; momentum sits with paper formats.
End User:
Food service operators prioritize washability and cycle life. Retail and e-commerce platforms trade durability for cube efficiency in reverse logistics.
- Food Service:Commercial kitchens and institutional cafeterias demand polypropylene nestable designs that survive industrial dishwashing. Netherlands hospital feeding systems represent concentrated demand for RFID-tagged pooling assets.
- Retail:Supermarket back-of-house replenishment favors foldable polyethylene totes that compress empty-haul volume by sixty percent.
- E-commerce:Meal-kit delivery platforms in North American urban corridors drive specifications for real-time traceability and damage liability protocols.
- Catering:Event and mobile food service operators value lightweight nestable formats for rapid deployment and breakdown.
Food service commands volume concentration; e-commerce climbs fastest on platform density.
Material:
Polymer selection determines regulatory pathway complexity. Mono-material constructions accelerate EU compliance; multi-layer barriers face Green Deal obsolescence.
- Polyethylene:Low-density and linear-low-density grades dominate foldable tote production for perishable distribution. French logistics operators specify these for cold-chain horticultural consolidation.
- Polypropylene:Homopolymer and copolymer formulations deliver heat resistance for hot-fill applications. German converters are shifting capacity to mono-material designs to satisfy REACH substance restrictions.
- Cardboard:Recycled corrugated and solid board structures capture grocery e-commerce where moisture barriers are secondary to presentation.
- Aluminum:Lightweight alloy sheets form rigid collapsible frames for premium thermal containers.
Polypropylene leads installed base; polyethylene gains on cold-chain expansion.
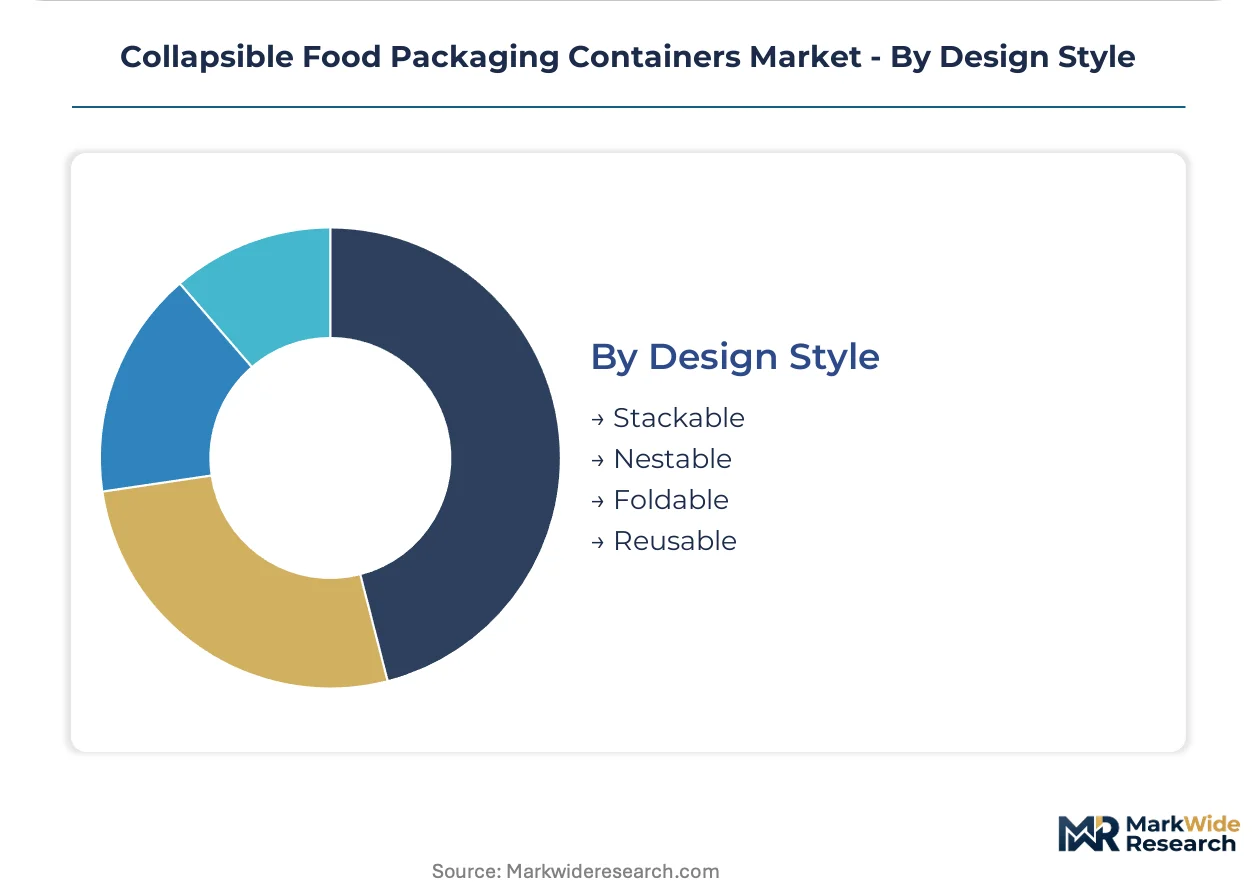
Design Style:
Structural geometry dictates space recovery ratio and automation compatibility. European pooling networks standardize on nestable formats; North American retail favors foldable adaptability.
- Stackable:Vertical interlocking features enable stable palletization without nesting depth. Italian pasta and sauce distributors use these for warehouse density in multi-temperature facilities.
- Nestable:Tapered wall designs allow empty containers to telescope inside one another. Benelux catering operators have adopted these for inter-operator asset sharing compatibility.
- Foldable:Hinged or creased panels collapse flat for maximum cube reduction. US grocery replenishment networks deploy polyethylene foldables in high-frequency store delivery loops.
- Reusable:Reinforced construction for extended cycle life in closed-loop systems. German automotive supplier cafeterias specify these under long-term pooling contracts.
Nestable designs anchor European standardization; foldable formats expand most quickly in North American retail back-of-house.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions anchor European demand patterns, while meal-kit platform density and cold-chain infrastructure gaps shape adoption trajectories across North America and Asia-Pacific. The report maps concentration across five national markets where regulatory alignment and logistics economics intersect.
Germany
Centralized food distribution networks drive standardized pooling system deployment, with automotive supplier cafeterias and hospital feeding systems commanding concentrated volume. The EU Green Deal packaging minimization targets accelerate mono-material polypropylene conversion ahead of enforcement deadlines. Bavaria and North Rhine-Westphalia host converter clusters serving Benelux inter-operator asset sharing networks.
United States
Meal-kit delivery platforms in urban corridors compress supplier negotiation cycles and unbundle legacy after-sales service expectations. FDA food contact substance notifications shape migration testing protocols for cross-border circulation assets. Chicago and Dallas-Fort Worth logistics hubs deploy foldable polyethylene totes in high-frequency grocery replenishment loops.
Netherlands
Institutional foodservice operators adopt RFID-tagged nestable designs for cycle-count automation in multi-user pooling networks. REACH compliance layers for colorants and stabilizers force reformulation toward in-mold labeling and laser-etched identification. Rotterdam and Amsterdam distribution clusters serve as standardization testbeds for EU-wide asset compatibility.
India
Underdeveloped returnable infrastructure creates first-mover positioning for foldable container operators targeting horticultural export consolidation. FSSAI food safety standards and DGFT export protocols shape material certification requirements. Maharashtra and Gujarat cold-chain expansion projects drive procurement of polyethylene designs for perishable distribution.
France
Logistics operators specify low-density polyethylene grades for cold-chain horticultural consolidation and perishable distribution. EU Packaging and Packaging Waste Regulation material recovery targets accelerate shifts away from multi-layer barrier formats. Lyon and Marseille distribution corridors anchor foldable tote deployment for agricultural export networks.
Collapsible Food Packaging Containers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with converter capability bifurcating between circularity-engineering competence and linear-model entrapment. The market structure rewards firms that control pooling network density alongside material certification breadth. Three archetypes dominate: integrated packaging-converters with captive logistics assets, pure-play pooling operators with telemetry-enabled fleet management, and regional fabricators competing on cost for standardized foldable designs. Competitive moves concentrate on strategic partnerships for RFID-embedded traceability and capacity redeployment toward mono-material production lines.
Within the integrated-converter tier, WestRock Company and DS Smith plc exemplify firms anchoring supply through paperboard and corrugated format integration. SKI Plastoware Private Limited occupies a position among South Asian fabricators leveraging manufacturing base cost structures for polyethylene designs. These three entities represent distinct strategic postures: North American supply integration, retail-ready nestable specialization, and cost-driven foldable production respectively.
| Leading Market Players |
|---|
| SKI Plastoware Private Limited |
| Jaycoplastic |
| WestRock Company |
| Schoeller Allibert |
| ORBIS Corporation |
| Brambles Limited |
| DS Smith plc |
| Plastor Ltd |
| Rehrig Pacific Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Dutch polypropylene converter facilities sits above regional benchmarks, compressing per-unit fixed costs and establishing price floors that marginal South Asian fabricators cannot undercut without sacrificing REACH compliance layers. This scale concentration enables pooling operators to enforce long-term offtake terms while spot-market buyers absorb feedstock volatility premiums.
Pricing Analysis
Long-term offtake contracts dominate procurement between institutional foodservice operators and European pooling networks, insulating converters from naphtha price swings while locking buyers into standardized nestable formats. Price differentiation rests on certification breadth—REACH-compliant mono-material designs command premiums over multi-layer alternatives facing Green Deal obsolescence—and cycle-life guarantees. Cost compression in foldable polyethylene segments is intensifying because meal-kit platforms negotiate real-time traceability bundles that legacy operators cannot unbundle. Quick-service restaurant chains exhibit highest price sensitivity due to thin operating margins, whereas hospital feeding systems prioritize compliance certainty over unit economics.
Supply Chain Analysis
Just-in-time resin procurement prevails among European converters, though strategic stockpiles of FDA-notified grades accumulate at North American transshipment hubs to circumvent cross-border notification delays. Manufacturing concentrates in Germany, the Netherlands, and India—German facilities anchor REACH-compliant mono-material capacity, Dutch plants serve RFID-embedded traceability demand, and Indian fabricators supply foldable polyethylene for cold-chain expansion. Raw material flows draw from Saudi and Qatari naphtha crackers, Belgian compounding specialists, and South Korean additive suppliers. Single-source vulnerability concentrates in EU-approved colorant systems subject to ECHA restriction expansions. Distribution runs through Rotterdam and Hamburg port clusters for European pooling networks, with Mumbai and Chennai anchoring South Asian horticultural export consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensible positioning in collapsible food packaging rests on pooling network density effects—asset interoperability across operators creates switching costs that isolate incumbents from price-only competition. Regulatory entrenchment compounds this moat as REACH compliance timelines and FDA notification pathways extend product launch windows for challengers.
For Market Incumbents: Compound pooling network density through RFID-embedded traceability standardization that locks meal-kit platforms into proprietary cycle-count protocols. Add captive washing infrastructure in Benelux corridor nodes to preempt third-party logistics encroachment. Corrugated fiberboard substitution in e-commerce grocery represents the most acute substitute threat requiring format diversification response.
For New Entrants and Emerging Players: Differentiate on cold-chain horticultural consolidation in Maharashtra and Gujarat, where FSSAI certification requirements remain less stringent than REACH layers and returnable infrastructure is underdeveloped. India's export-oriented perishable distribution offers the most penetrable geography for foldable polyethylene operators. Go-to-market execution should anchor on DGFT export protocol navigation bundled with local washing partnership structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pooling operators with telemetry-enabled fleet management and multi-user network density, as these assets generate per-cycle fees rather than transactional container sales. Five-to-ten year viability favors firms with backward integration into polymer compounding and captive certification expertise. Acquisition targets should display REACH-compliant mono-material production lines and established automotive supplier cafeteria contracts. The signal to watch is EU Green Deal enforcement acceleration triggering obsolescence of multi-layer barrier inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Production Line Conversion | REACH compliance de-risks European circulation assets against Green Deal enforcement timelines. |
| RFID-Embedded Traceability Integration | Meal-kit platforms demand real-time cycle-count automation that legacy pooling operators cannot satisfy. |
| Backward Integration into Polymer Compounding | Captive resin formulation secures colorant and stabilizer compliance certainty under ECHA expansion. |
| Cold-Chain Infrastructure Partnership | Indian horticultural export consolidation requires foldable container deployment with FSSAI-aligned washing protocols. |
| Multi-User Pooling Network Expansion | Inter-operator asset sharing in Benelux generates network effects that compress challenger entry economics. |
Methodological Framework
Desk research of EU regulatory filings, FDA food contact substance notifications, and customs trade data preceded structured interviews with pooling network operators, polymer converter plant managers, and meal-kit platform supply chain directors. Secondary validation drew from ECHA restriction proposals, SEC 10-K disclosures of integrated packaging firms, and automotive supplier cafeteria procurement records. Bottom-up container shipment estimates triangulated against top-down foodservice distribution spending allocations.
Variance decomposition across material, design style, and end-user dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated polymer grade tier, logistics automation compatibility, and regional regulatory cluster intensity. CAGRs derived from logistic curve fitting to observed pooling network penetration rates, with cross-validation against perishable distribution volume growth and cold-chain infrastructure investment flows.
Material uncertainties—polypropylene feedstock cost swings, REACH substance restriction timeline acceleration, and meal-kit platform consolidation failures—sit outside the modeled envelope. Forecasts reflect assumptions about EU Green Deal enforcement pacing and FDA notification harmonization progress. Revision becomes warranted when naphtha cracking margin volatility exceeds historical bands or when ECHA restriction expansions capture additional colorant categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Acrylic Container Market
Containers
Containerboard Market
Containers
Edible Oil Cans Market
Containers
Cups and Lids Market
Containers
Cylindrical Cans Market
Containers
Multi Cavity Tray Market
Containers
Thermoformed Containers Market
Containers
Foldable Container Market
Containers
Thin Wall Plastic Containers Market
Containers
Intermediate Bulk Container Liner Market
Containers
Pocket Containers Market
Containers
Stackable Plastic Trays Market
Containers
Compartment Take-Out Container Market
Containers
EMEA Container Technology Market
Containers
Belgium Container Glass Market
Containers
Metal Crates Market