
 Thin Wall Plastic Containers Market | 2026-2036
Thin Wall Plastic Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Wall Plastic Containers Market Outlook
Foodservice distribution channels are reconfiguring around direct-to-retail supply models that bypass traditional wholesaling tiers. Amcor plc leverages its global converting footprint to sustain shelf-ready tray programs for major European grocery banners. Berry Global Inc. anchors North American dairy tub supply through captive thermoforming capacity and retailer-specific tooling investments.
Thin wall plastic containers are injection-molded or thermoformed vessels with wall thickness below 0.8 millimeters, engineered from polypropylene, polyethylene, or PET to minimize resin content while preserving stack strength and barrier performance for perishable goods. Polypropylene dominates dairy and margarine tub applications due to its thermal stability and living-hinge compatibility, while PET trays capture premium deli and produce segments where clarity drives shelf appeal. The food industry end-use segment commands the deepest volume pools, though pharmaceutical-grade polystyrene vials and pails retain higher unit margins amid sterility validation requirements.
The European Chemicals Agency enforces REACH compliance for food-contact substances, while the FDA regulates indirect food additive migration limits through 21 CFR standards in the United States. These frameworks compel resin suppliers and converters to maintain exhaustive extraction testing protocols that lengthen qualification cycles but raise barriers to unvalidated imports. Stakeholders must monitor accelerating mechanical recycling content mandates across multiple jurisdictions, as certifiable post-consumer feedstock access becomes the decisive supply constraint.
Market Dynamics
Europe's Single-Use Plastics Directive is compressing virgin polymer demand while mechanical recycling mandates force converters to requalify entire product portfolios around certifiable rPET feedstock access.
Growth Catalysts
- rPET Mandates:Germany's Packaging Act amendments require minimum recycled content thresholds in food-contact applications, pulling converters toward validated post-consumer supply chains.
- Dairy Segment Expansion:Margarine and spreadable cheese producers in France and the Netherlands are converting from glass and metal to injection-molded polypropylene tubs with living-hinge lids.
- Thermoforming Efficiency Gains:Servo-driven trim-in-place systems cut cycle times by compressing forming and cutting stations into single-tooling configurations.
Market Restraints
- Feedstock Scarcity:Certifiable food-grade rPET supply concentrates among three European reclaimers, creating allocation bottlenecks for mid-volume converters.
- Propylene Price Volatility:Naphtha-cracking margins in the ARA hub transmit directly to polypropylene pellet costs, squeezing thin-wall converters with limited pass-through power.
- Barrier Performance Ceilings:Polyethylene terephthalate trays below 0.6 millimeter walls cannot achieve oxygen transmission rates required for modified-atmosphere meat packaging without secondary films.
Strategic Opportunities
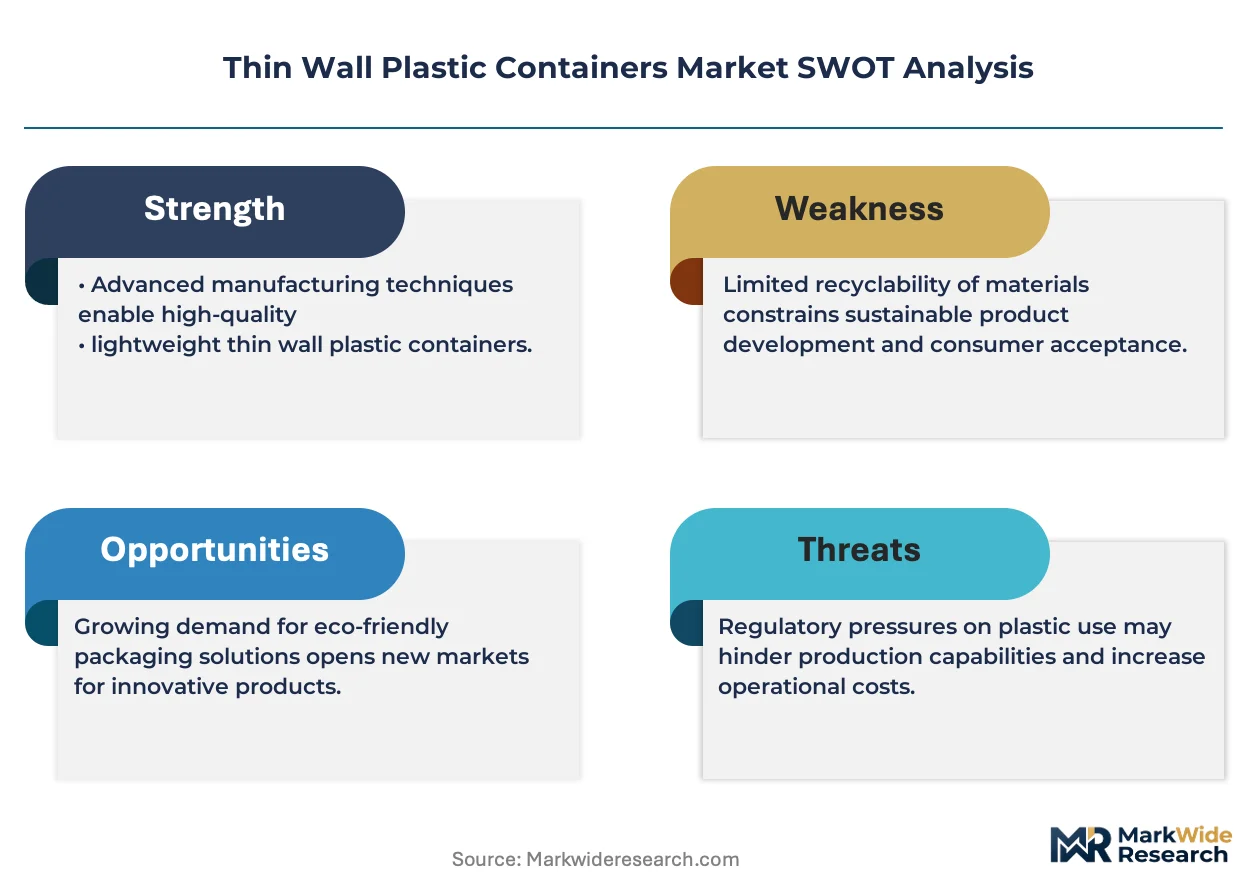
- Pharmaceutical-Grade Polystyrene:Sterility-validated vials and pails for diagnostic reagents command unit margins three to four times above food-contact equivalents.
- Direct-to-Retail Supply Models:Foodservice distributors are bypassing wholesale tiers to deliver shelf-ready trays straight to grocery backrooms, compressing lead times.
- Chemical Recycling Scale-Up:Pyrolysis-derived feedstocks promise to expand food-contact eligible resin pools beyond mechanical recycling contamination limits.
Industry Challenges
- Extraction Testing Backlogs:ECHA's REACH compliance protocols for food-contact substances extend qualification cycles to eighteen months, freezing product development pipelines.
- Tooling Amortization Pressure:Retailer-specific cavity configurations require dedicated molds that strain capital allocation for sub-$50 million revenue converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Wall Plastic Containers Market |
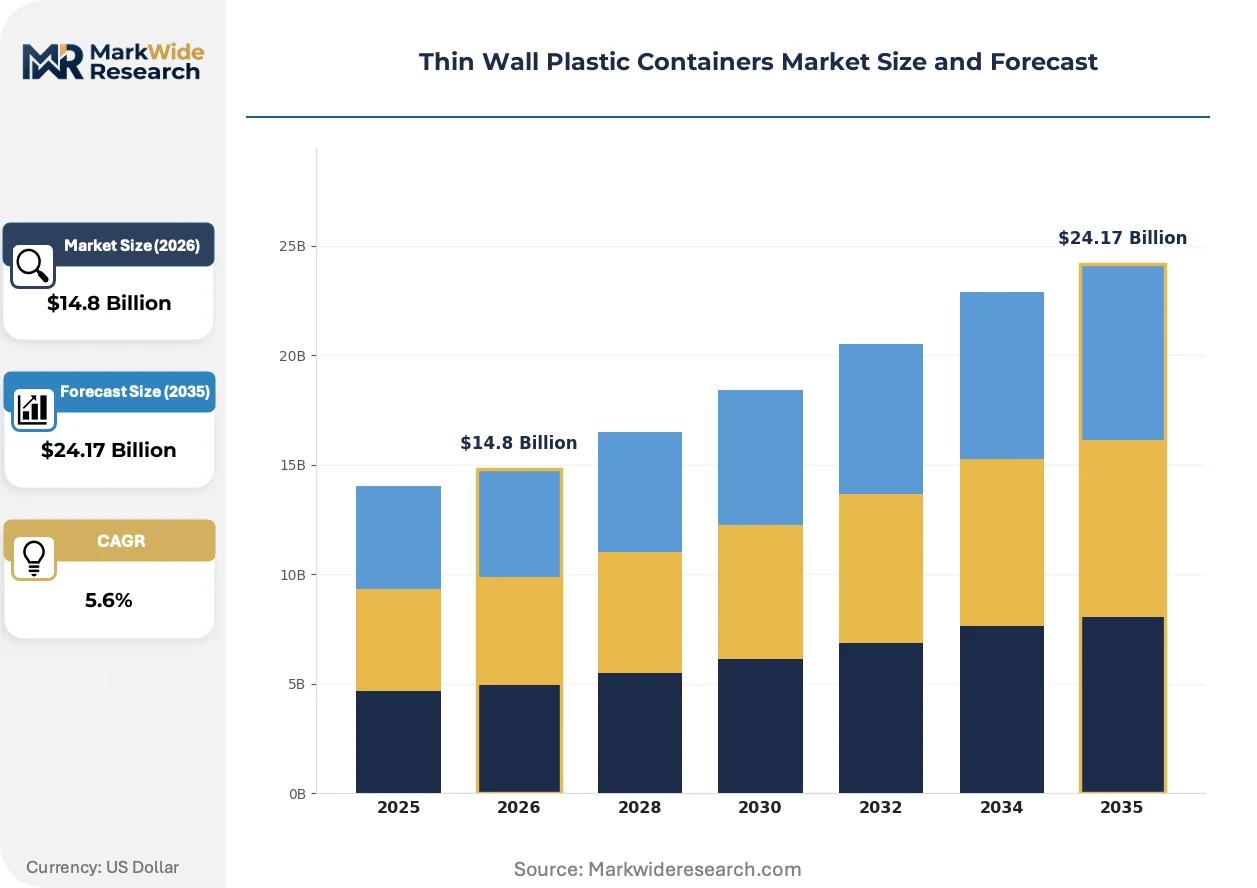
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Pails, Tubs, Trays Material: Polypropylene, Polyethylene, Polystyrene, PET End User: Food Industry, Pharmaceutical Sector, Personal Care, Household Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | EVCO Plastics, RPC Letica Corporation, Borouge Pte Ltd., Sunrise Plastics, Sem Plastik San. Tic. A.S., Berry Global Inc., Amcor plc, Greiner Packaging International, Double H Plastics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Wall Plastic Containers Market Strategic Shifts
Material science and processing control systems are converging to enable thinner walls without sacrificing stack strength, while regulatory pressure accelerates the shift from virgin to circular feedstocks.
Digital cavity pressure monitoring is digitizing quality assurance in thin-wall injection molding. Dairy tub producers in Denmark and Sweden are retrofitting sensors to existing presses to capture real-time viscosity variations. This data stream is digitizing defect prediction, allowing operators to adjust temperatures before short shots or flash occur rather than relying on post-mold inspection.
REACH enforcement through ECHA is tightening migration testing protocols for polypropylene nucleating agents. The industrial consequence is a forced reformulation cycle among European compounders seeking food-contact approval. Dairy and margarine segments are most affected, with several German converters already switching to alternative clarifying agents to avoid registration delays.
Retailer consolidation is compressing supplier rosters across European grocery banners. Major chains in Germany and France are mandating shelf-ready packaging specifications that only large thermoformers can meet at scale. This concentration is visible most acutely in the ready-to-eat meal segment, where single-source contracts now cover entire national store networks.
Thin Wall Plastic Containers Market Segmentation
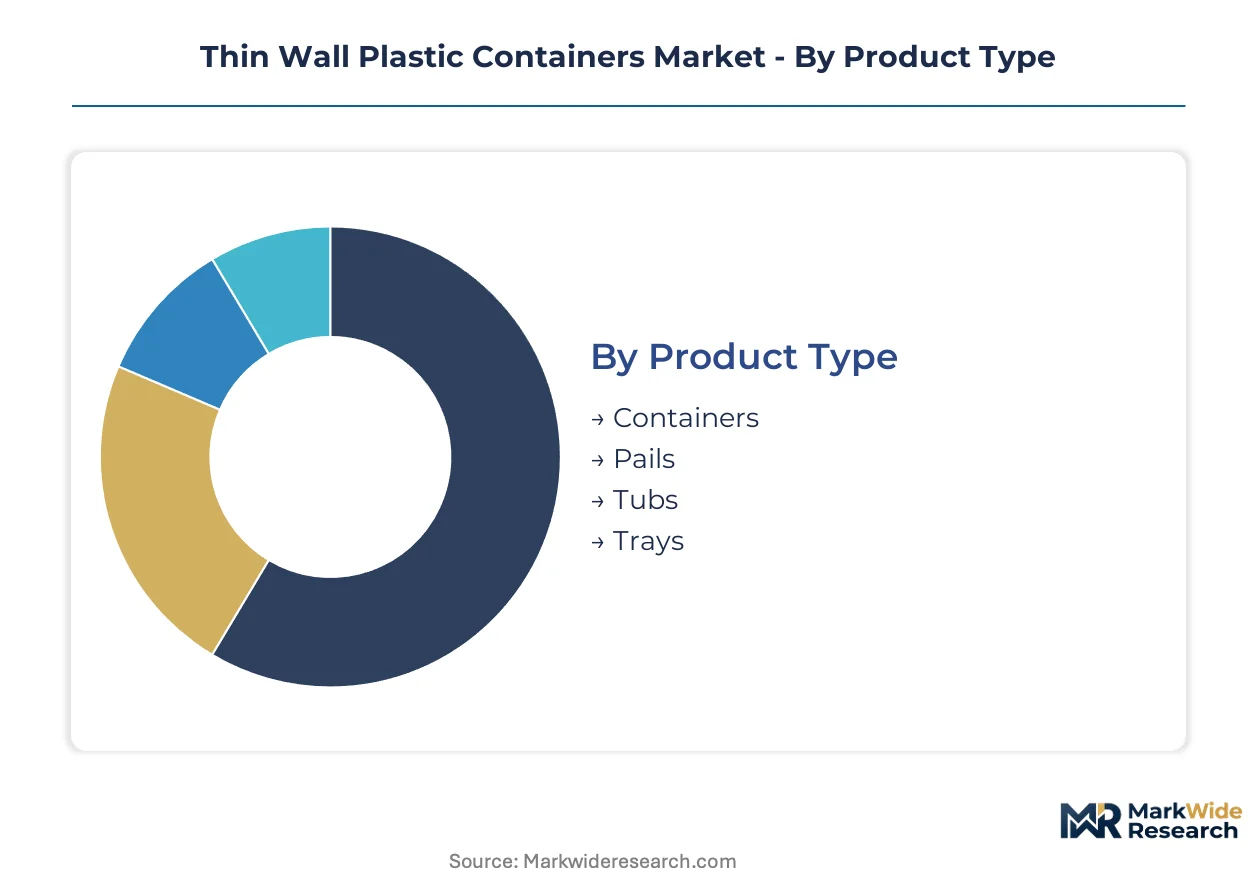
Thin wall plastic containers fragment across four structural dimensions that determine resin selection, barrier engineering, and channel economics. Each segmentation axis carries distinct margin profiles and qualification burdens that reshape supplier positioning.
Product Type:
Mature formats dominate volume throughput while emerging configurations capture premium shelf positioning.
- Containers:Injection-molded vessels with sub-0.8 millimeter walls serve condiment and sauce segments where stack strength must survive automated palletizing. German retail consolidation has compressed supplier rosters for standardized round formats, favoring thermoformers with multi-cavity tooling investments.
- Tubs:Living-hinge polypropylene designs anchor dairy and margarine applications across France and the Netherlands. ECHA's REACH compliance protocols for nucleating agents have forced reformulation cycles among compounders supplying this segment, extending qualification timelines.
- Pails:Handle-integrated formats for industrial and foodservice bulk applications.
- Trays:Thermoformed PET and PP structures for ready-to-eat meals and produce.
Tubs handle the majority of throughput; trays are expanding most quickly on share.
Material:
Cost tiers separate commodity resins from performance grades with specialized barrier or clarity properties.
- Polypropylene:Homopolymer and random copolymer grades command dairy tub applications through thermal stability and living-hinge fatigue resistance. Naphtha-cracking margin volatility in the ARA hub transmits directly to pellet costs, squeezing converters with limited pricing power.
- PET:Amorphous and crystallized grades capture premium deli and produce segments where optical clarity drives shelf appeal. Germany's Packaging Act amendments mandate minimum recycled content thresholds, pulling converters toward validated rPET supply chains concentrated among three European reclaimers.
- Polyethylene:HDPE and LDPE formulations for chemical resistance and flexibility.
- Polystyrene:Crystal and high-impact grades for pharmaceutical vials and diagnostic pails.
Polypropylene anchors volume economics; PET climbs the fastest on regulatory-driven substitution.
End User:
Application requirements dictate sterilization protocols, migration testing burdens, and margin structures.
- Food Industry:Ready-to-eat meals, dairy, and deli segments demand shelf-ready packaging with modified-atmosphere compatibility. Direct-to-retail supply models are bypassing wholesale tiers, compressing lead times for thermoformed tray programs.
- Pharmaceutical Sector:Sterility-validated polystyrene vials and pails for diagnostic reagents command unit margins three to four times above food-contact equivalents. FDA 21 CFR and ECHA REACH protocols impose exhaustive extraction testing that freezes product development pipelines.
- Personal Care:Cosmetic and hygiene product packaging with aesthetic surface requirements.
- Household Products:Cleaning and maintenance chemical containers with chemical resistance specifications.
Food Industry carries the deepest volume pools; Pharmaceutical Sector shows the steepest margin expansion trajectory.
Distribution Channel:
Customer type determines order fragmentation, tooling amortization schedules, and specification control.
- Supermarkets:Consolidated grocery banners in Germany and France mandate retailer-specific cavity configurations requiring dedicated molds. Single-source contracts now cover entire national store networks for ready-to-eat meal trays.
- Distributors:Traditional foodservice wholesaling tiers face disintermediation as direct-to-retail models compress margins. Mid-volume converters struggle with allocation bottlenecks for certifiable food-grade rPET feedstock.
- Online Retail:E-commerce fulfillment packaging with damage resistance specifications.
- Convenience Stores:Small-format retail with high-velocity, single-serve packaging requirements.
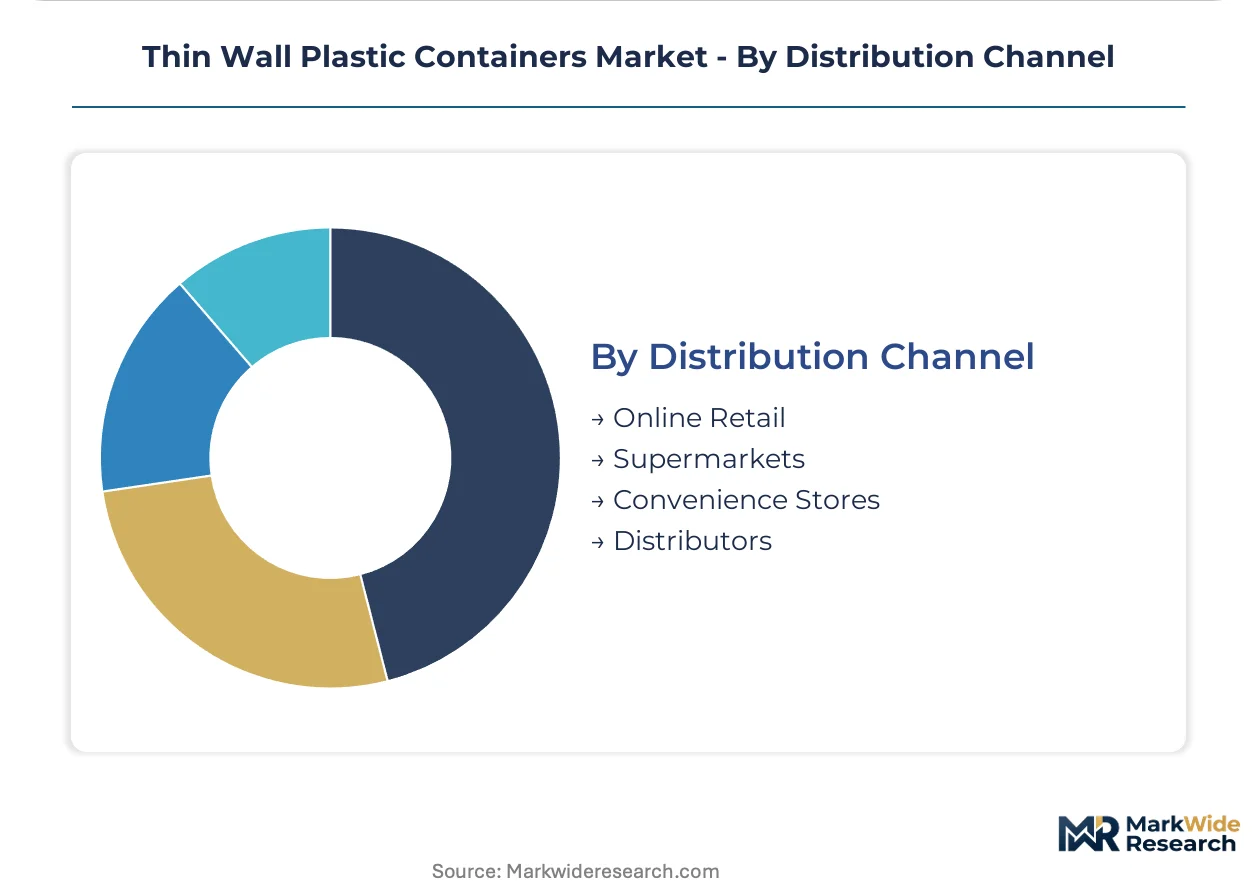
Supermarkets concentrate specification control; distributors are losing share fastest to direct supply restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement is compressing qualification cycles across European converting operations while FDA 21 CFR migration limits govern North American food-contact approvals. Germany's Packaging Act amendments and rPET mandates are forcing material transitions faster than supply chains can adapt.
Germany
Retail consolidation at Edeka, Rewe, and Aldi Süd is mandating shelf-ready tray specifications that only large thermoformers can fulfill. The country's Packaging Act requires minimum recycled content thresholds in food-contact applications, pulling converters toward validated rPET supply chains. Industrial concentration is visible in the Baden-Württemberg and North Rhine-Westphalia clusters, where multi-cavity tooling investments now dominate dairy tub supply.
United States
Foodservice distributors are bypassing wholesale tiers to deliver shelf-ready packaging directly to grocery backrooms, compressing lead times for thermoformed programs. FDA regulates indirect food additive migration limits through 21 CFR standards, compelling exhaustive extraction testing protocols. The Midwest industrial corridor around Chicago anchors injection-molded polypropylene capacity for condiment and sauce segments.
France
Margarine and spreadable cheese producers are converting from glass and metal to injection-molded polypropylene tubs with living-hinge lids. ANSM enforces food-contact substance compliance parallel to REACH frameworks, extending qualification timelines for nucleating agent reformulations. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate dairy packaging demand near major retail distribution hubs.
Netherlands
Dairy segment expansion is driving polypropylene tub demand across FrieslandCampina and private-label supply chains. The country's alignment with EU Single-Use Plastics Directive implementation is accelerating mechanical recycling infrastructure investment. The Randstad logistics cluster enables just-in-time delivery of shelf-ready formats to consolidated grocery banners.
China
Domestic demand for lightweight food packaging is expanding across ready-to-eat and dairy segments as cold-chain infrastructure matures. SAMR and GB standards govern food-contact plastics with migration testing protocols that lengthen import qualification cycles. The Yangtze River Delta and Pearl River Delta manufacturing basins concentrate thermoforming and injection molding capacity for export and domestic markets.
Thin Wall Plastic Containers Market Competitive Environment
Global converters and regional specialists split the market along capability tiers that separate multi-cavity tooling investments from flexible job-shop operations. Consolidation pressure from retailer single-source contracts is squeezing mid-volume players without dedicated mold amortization capacity. Three archetypes dominate: multinational integrated packaging groups with captive resin access; regional thermoformers with retailer-specific tooling commitments; and specialized pharmaceutical-grade polystyrene molders with sterility validation capabilities. Competitive moves center on backward integration into rPET feedstock sourcing and geographic expansion through toll manufacturing partnerships.
Among multinational integrated groups, Amcor plc and Berry Global Inc. occupy positions that exemplify scale-driven shelf-ready program supply. Amcor leverages its global converting footprint to sustain tray programs for European grocery banners, while Berry anchors North American dairy tub supply through captive thermoforming capacity. Greiner Packaging International represents the European regional specialist archetype with retailer-specific tooling investments concentrated in German-speaking markets.
| Leading Market Players |
|---|
| EVCO Plastics |
| RPC Letica Corporation |
| Borouge Pte Ltd. |
| Sunrise Plastics |
| Sem Plastik San. Tic. A.S. |
| Berry Global Inc. |
| Amcor plc |
| Greiner Packaging International |
| Double H Plastics, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European thermoforming operations is compressing contract margins while simultaneously accelerating rPET feedstock competition among converters seeking regulatory compliance. German retail consolidation has concentrated buyer power among three major grocery banners, forcing mid-volume suppliers to absorb resin volatility or exit shelf-ready programs entirely.
Pricing Analysis
Price spreads between virgin polypropylene and certifiable food-grade rPET have widened across the ARA hub as reclaimers capture scarcity premiums. Three-tier pricing structure across premium pharmaceutical-grade polystyrene, standard food-contact polypropylene, and economy polyethylene pails separates margins by certification burden and sterilization validation. Cost compression in standard dairy tub segments is intensifying because naphtha-cracking margin volatility transmits directly to converters with limited pass-through power. Small-format convenience store buyers exhibit the highest price sensitivity, while pharmaceutical diagnostic reagent suppliers accept premium positioning for sterility-validated vials.
Supply Chain Analysis
Export-control restrictions on advanced nucleating agent technologies under REACH registration requirements are limiting formulation knowledge transfers to non-European compounders. Supply concentrates among Germany, France, and the Netherlands for injection-molded dairy tubs, while China and the United States anchor thermoformed tray capacity. Raw material flows draw from ARA hub naphtha crackers, Middle Eastern propylene export terminals, and three European rPET reclaimers with food-contact certification. Single-source vulnerability concentrates in certifiable post-consumer feedstock access, where allocation bottlenecks freeze mid-volume converter expansion plans. Distribution runs through direct-to-retail supply models that bypass traditional foodservice wholesaling tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where ECHA REACH compliance protocols and eighteen-month qualification cycles erect barriers that favor incumbents with established extraction testing capabilities.
For Market Incumbents: Build switching-cost moats by embedding multi-cavity tooling investments into retailer-specific cavity configurations that strain capital allocation for sub-fifty-million-revenue competitors. Backward integration into rPET feedstock sourcing anchors supply security against allocation bottlenecks from the three European reclaimers. Threat displacement from chemical recycling scale-up demands monitoring of pyrolysis-derived resin qualification timelines. For New Entrants and Emerging Players: Pursue pharmaceutical-grade polystyrene vials and diagnostic pails where sterility validation requirements command unit margins three to four times above food-contact equivalents. White-space concentrates in sterility-validated formats for diagnostic reagent supply chains, where exhaustive FDA 21 CFR and ECHA REACH protocols have frozen incumbent product development pipelines. Go-to-market positioning should emphasize toll manufacturing partnerships with established molders to bypass capital-intensive tooling amortization. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because retailer single-source contracts covering entire national store networks are squeezing mid-volume players without dedicated mold amortization capacity. Acquisition targets center on regional thermoformers with retailer-specific tooling commitments in German-speaking markets. The signal to watch is mechanical recycling infrastructure investment velocity, as certifiable post-consumer feedstock access becomes the decisive supply constraint.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Feedstock Backward Integration | Captures scarce certifiable post-consumer supply chains ahead of Germany's Packaging Act threshold mandates. |
| Pharmaceutical-Grade Sterility Validation | Opens diagnostic reagent vial segments with margins three to four times above food-contact equivalents. |
| Servo-Driven Trim-in-Place Retrofit | Compresses cycle times for dairy tub producers competing on European retail consolidation timelines. |
| Direct-to-Retail Supply Model Expansion | Bypasses disintermediated foodservice wholesale tiers to capture grocery backroom delivery contracts. |
| Chemical Recycling Partnership Structure | Positions for pyrolysis-derived resin pools beyond mechanical recycling contamination limits. |
Study Parameters
Desk research of ECHA REACH registration databases, FDA 21 CFR indirect food additive filings, and European thermoforming capacity registries preceded structured interviews with dairy packaging procurement managers, pharmaceutical diagnostic reagent supply chain directors, and rPET reclaimer technical sales leads. Secondary validation drew from customs trade data, SEC 10-K disclosures of integrated packaging groups, and EU Single-Use Plastics Directive implementation reports. Bottom-up volume modeling triangulated against top-down resin consumption forecasts.
Assumptions held fixed include ECHA enforcement intensity on nucleating agent migration protocols and Germany's Packaging Act recycled content thresholds, while propylene price volatility and chemical recycling commercialization timelines were varied across sensitivity scenarios. Segmentation dimensions spanned product type, material grade, end-use sterilization protocol, and distribution channel control structure. CAGRs were derived from installed thermoforming and injection molding capacity utilization trends cross-referenced with retail shelf-ready packaging specification adoption curves.
Sensitivities concentrate around rPET reclaimer capacity expansion announcements and pyrolysis-derived resin food-contact approval timelines. Forecasts embed assumptions regarding REACH qualification cycle durations and retailer consolidation velocity. Material shifts in ECHA nucleating agent enforcement or German Packaging Act threshold acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Tin Containers Market
Containers
Oblong Jar Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Carboy Market
Containers
Stock Clamshell Packaging Market
Containers
Americas Container Technology Market
Containers
Club Store Packaging Tray Market
Containers
Canning Jars Market
Containers
Popcorn Containers Market
Containers
Dispensing Jug Market
Containers
Takeaway Containers Market
Containers
Bulk Containers Market
Containers
Wet Wipes Canister Market
Containers
EPS Shippers Market
Containers
Kuwait Container Glass Market
Containers
Gable Top Container Market