
 Slip Lid Can Market | 2026-2036
Slip Lid Can Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Lid Can Market Analytics
Food-grade specification upgrades across premium ready-to-drink segments is collapsing the cost gap between standard three-piece cans and higher-specification slip lid alternatives. Crown Holdings leverages its European beverage can footprint to sustain aluminum slip lid output for specialty coffee brands. Silgan Holdings anchors North American supply through its decorated metal packaging network, while Toyo Seikan Group dominates Asian production with precision-drawn steel formats for seafood and dairy applications.
A slip lid can is a cylindrical metal container featuring a separate cover that slides or presses onto a beaded rim, typically manufactured from drawn-and-ironed aluminum or tinplate steel with internal linings of epoxy phenolic or organosol coatings to prevent corrosion and flavor transfer. Its primary commercial purpose is to provide resealable, shelf-stable packaging for moisture-sensitive or multi-serve contents where full aperture access and repeated closure extend product usability. Steel slip lid cans occupy the mature volume base in processed fish and pet food segments where cost efficiency and established filling infrastructure preserve incumbent demand. Aluminum variants are capturing faster expansion in beverage and personal care applications where lightweighting and decoration flexibility command premium positioning. Biodegradable substrates remain nascent but attract development capital as brand sustainability commitments intensify scrutiny of conventional metal recycling loops.
EU REACH restrictions on bisphenol-A coatings and FDA food-contact substance notifications are reshaping internal lining specifications, compelling suppliers to qualify polyester and acrylic alternatives that maintain barrier performance without regulated constituents. The EU Green Deal's packaging reuse targets and extended producer responsibility schemes are accelerating demand for formats that support refill and return logistics. China's GB standards for food-contact metals and Japan's JIS specifications for tinplate quality create parallel compliance pathways that segment export-oriented production. Stakeholders must monitor how divergent coating approval timelines across FDA, EFSA, and China's NMPA channels constrain new product introductions and inform regional capacity allocation decisions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is collapsing the cost gap between standard three-piece cans and higher-specification slip lid formats by mandating material recovery targets that favor aluminum and steel with established recycling infrastructure.
Growth Catalysts
- EU Green Deal packaging reuse targets:Extended producer responsibility schemes accelerate demand for formats supporting refill and return logistics across beverage and personal care segments.
- Ready-to-drink coffee premiumization:Food and beverage brands in North America and Europe expand resealable metal packaging for multi-serve consumption occasions.
- Germany's food canning tradition:Sustainability mandates align with slip lid formats over peel-seal alternatives in processed fish and dairy applications.
Market Restraints
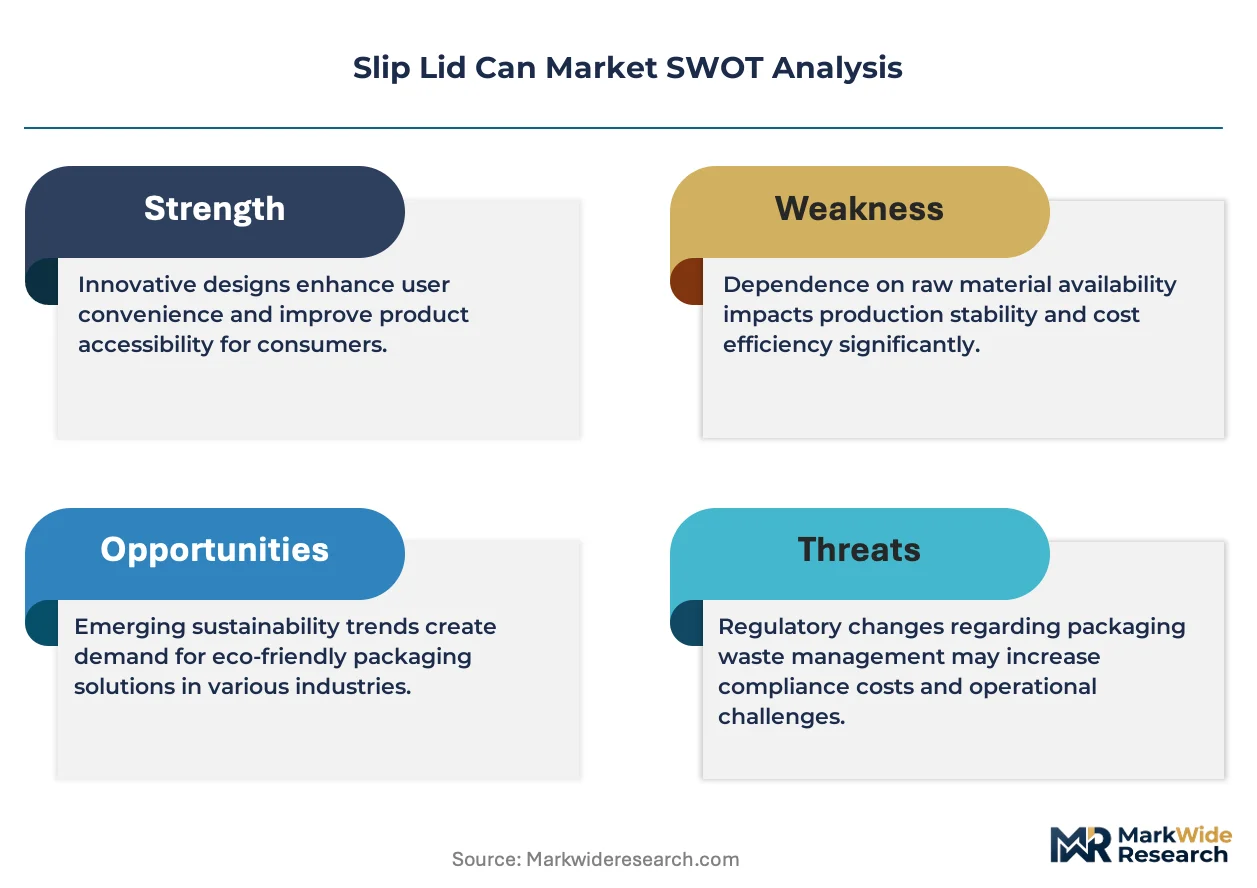
- Aluminum input cost volatility:LME price swings compress converter margins and destabilize contract pricing for lightweight beverage formats.
- Coating qualification timelines:FDA food-contact substance notifications and EU REACH bisphenol-A restrictions delay new product introductions by 18-24 months.
- Flexible pouch substitution:Stand-up pouches with zip closures capture single-serve snack and pet food volume at lower unit cost.
Strategic Opportunities
- Biodegradable substrate development:Brand sustainability commitments intensify scrutiny of conventional metal recycling loops and attract capital to next-generation barrier materials.
- Precision-drawn steel for seafood:Asian export markets favor tinplate formats with organosol linings for extended shelf stability in ambient distribution.
- Refill infrastructure alignment:EU packaging reuse targets create white space for slip lid formats in bulk retail and zero-waste store channels.
Industry Challenges
- Coating chemist talent scarcity:Migration from epoxy phenolic to polyester and acrylic alternatives requires specialized formulation expertise that outpaces graduate pipeline output.
- Multi-regulatory compliance synchronization:Divergent approval timelines across FDA, EFSA, and China's NMPA channels fragment new product launch sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Lid Can Market |
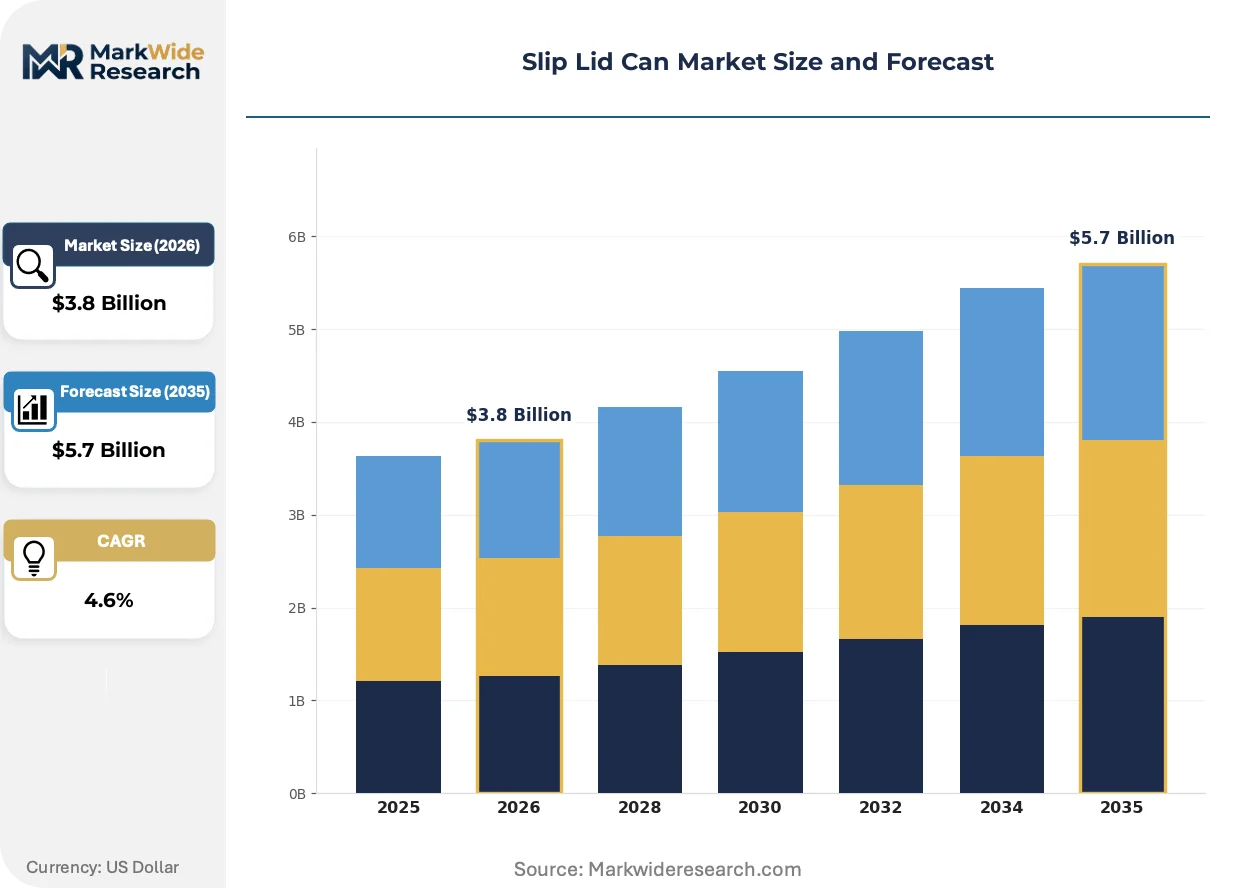
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Biodegradable End User: Food & Beverage, Personal Care, Household, Industrial Capacity: 200ml, 330ml, 500ml, 1000ml Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Crown Holdings, Inc., Silgan Holdings Inc., Ball Corporation, Ardagh Group, Independent Can Company, Sonoco Products Company, Berry Global, Toyo Seikan Group Holdings Ltd., Allstate Can Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Lid Can Market Evolving Landscape
Internal lining chemistry and lightweight substrate engineering are reshaping competitive positioning in metal packaging, with regulatory pressure on legacy coatings forcing accelerated qualification of alternative barrier systems.
Polyester-based internal coatings are fragmenting the incumbent epoxy phenolic standard by eliminating bisphenol-A constituents while maintaining corrosion resistance for acidic contents. Premium ready-to-drink coffee brands in Germany and the United States are qualifying these alternatives at pilot scale. The technology is fragmenting supplier R&D roadmaps and extending qualification timelines for converters serving multiple regulatory jurisdictions.
REACH restrictions on bisphenol-A coatings are compelling European converters to revalidate entire product portfolios. Industrial consequence includes accelerated investment in acrylic and polyester alternative qualification programs. Seafood and dairy applications in EU member states face the tightest compliance deadlines and are consolidating supplier relationships to secure coating allocation priority.
Brand sustainability commitments are compressing procurement cycles for packaging with verifiable recycling credentials. Ready-to-drink beverage manufacturers are unbundling decoration specifications from structural performance requirements. Germany and adjacent EU markets exhibit the strongest preference for aluminum formats with post-consumer recycled content thresholds above 50 percent.
Slip Lid Can Market Segmentation
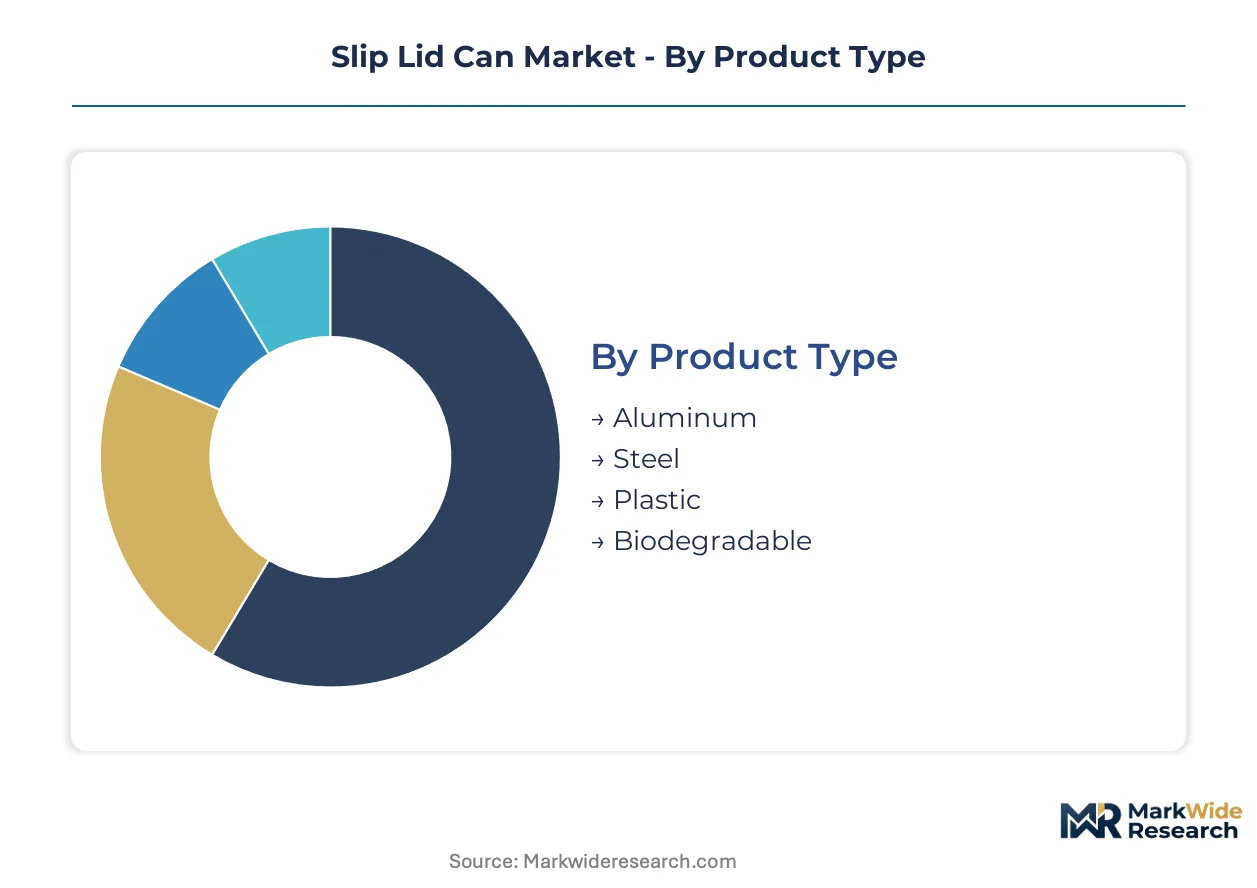
Slip lid can demand fragments across material substrates, end-use applications, and capacity tiers that each face distinct substitution pressures from flexible pouches and rigid plastic alternatives. Understanding these fault lines reveals where converters can defend volume and where retreat to premium niches becomes necessary.
Product Type:
Flexible pouch substitution threatens steel and aluminum most acutely in single-serve formats, while biodegradable alternatives compete for sustainability-driven brand commitments.
- Aluminum:Drawn-and-ironed construction with epoxy phenolic or polyester internal linings delivers lightweight barrier performance for acidic beverages. Demand concentrates in German ready-to-drink coffee brands qualifying post-consumer recycled content thresholds above 50 percent under EU Green Deal procurement mandates.
- Steel:Tinplate substrates with organosol coatings provide cost-efficient shelf stability for processed fish and pet food segments. Established filling infrastructure in North American canneries preserves incumbent volume despite aluminum lightweighting advances in adjacent categories.
- Plastic:Polypropylene and polyethylene terephthalate formats serve budget household and industrial segments where metal barrier properties exceed requirements.
- Biodegradable:Cellulose-based and polylactic acid substrates attract development capital from brands intensifying scrutiny of conventional metal recycling loop verifiability.
Steel anchors the volume base while biodegradable formats gain share at the steepest rate.
End User:
Margin structures diverge sharply across customer categories, with food and beverage converters capturing scale economies unavailable to personal care specialists.
- Food & Beverage:Multi-serve ready-to-drink coffee and craft beverage applications in Germany and the United States command premium positioning through resealable metal formats. EU REACH bisphenol-A restrictions force coating revalidation timelines that consolidate supplier relationships toward qualified converters.
- Personal Care:Precision-drawn aluminum serves cosmetic and grooming products where decoration flexibility supports brand differentiation. Lower volume per SKU fragments procurement scale and extends qualification cycles.
- Household:Cleaning and maintenance products utilize standard steel specifications with cost-minimized internal linings.
- Industrial:Chemical and lubricant applications prioritize corrosion resistance over decoration, accepting heavier-gauge tinplate with basic epoxy phenolic barriers.
Food and beverage commands the revenue concentration while personal care expands most quickly through premiumization.
Capacity:
Filling line compatibility and retail shelf-space economics determine which capacity tiers sustain investment versus face displacement by alternative formats.
- 200ml:Single-serve beverage and sampler formats face intense flexible pouch competition in snack and pet food adjacencies.
- 330ml:Standard beverage can footprint adapted to slip lid mechanics for premium coffee and tea applications in German retail.
- 500ml:Multi-serve dairy and seafood formats align with established European canning traditions and reuse-target retail channels.
- 1000ml:Bulk household and industrial applications where resealability extends product usability across extended consumption cycles.
The 330ml tier concentrates production investment while 500ml climbs fastest on refill infrastructure alignment.
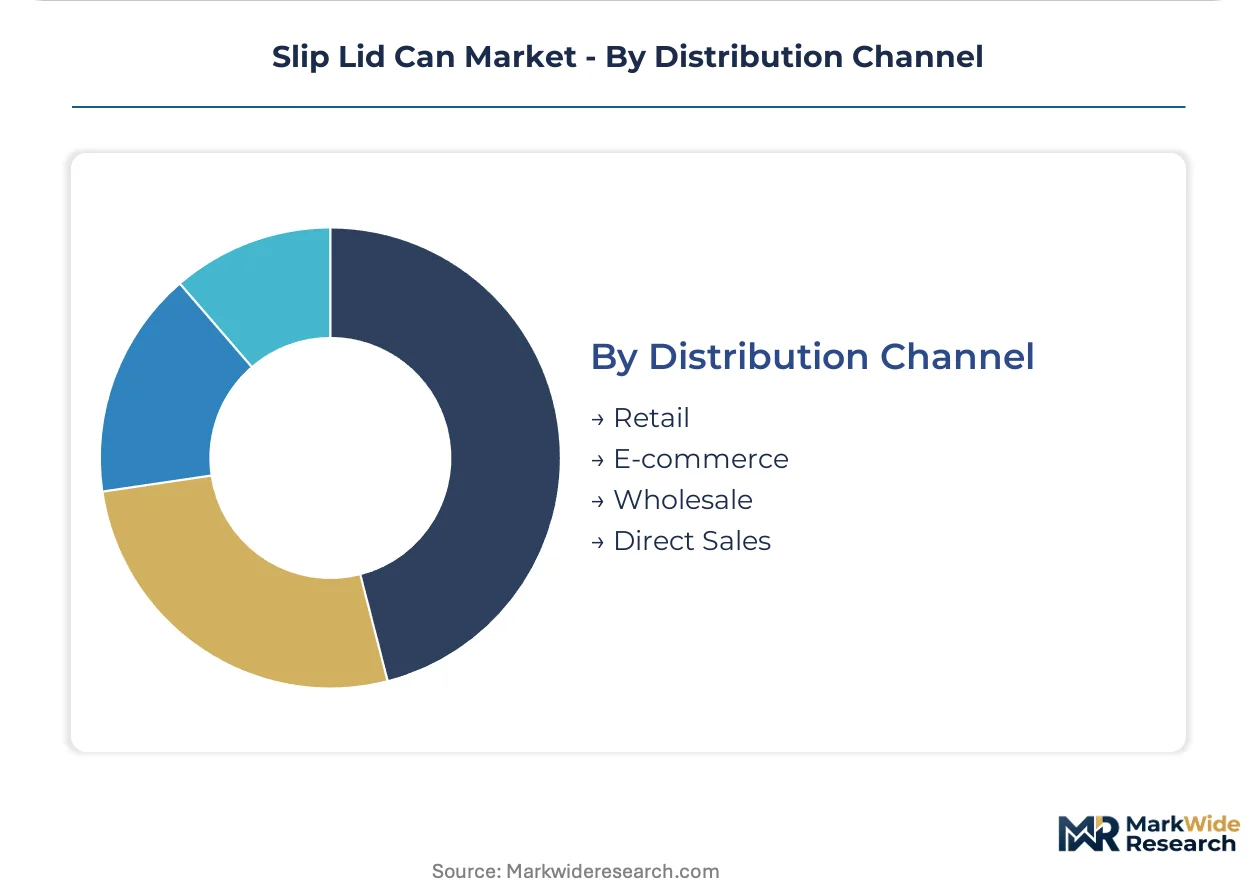
Distribution Channel:
Channel selection directly shapes format specification, with zero-waste retail imposing reuse-logic requirements absent in conventional wholesale.
- Retail:Supermarket and specialty store placement demands shelf-ready decoration and standardized pallet configurations.
- E-commerce:Direct-to-consumer shipment requires enhanced seam integrity and damage-resistant packaging specifications.
- Wholesale:Foodservice and institutional volume runs through established distributor networks with legacy steel can preferences.
- Direct Sales:Bulk and refill store channels in Germany and adjacent EU markets prioritize aluminum formats with verified recycling credentials.
Retail maintains the volume foundation while direct sales channels accelerate fastest on EU packaging reuse targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity concentrates in Germany, the United States, and Japan, where established metal packaging infrastructure serves distinct end-use specializations. Regulatory divergence across FDA, EFSA, and Japan's Ministry of Health, Labour and Welfare creates parallel compliance pathways that segment export-oriented production.
Germany
Ready-to-drink coffee brands and processed fish canneries drive specification upgrades toward resealable aluminum formats. The EU Packaging and Packaging Waste Regulation mandates material recovery targets that favor slip lid constructions over peel-seal alternatives. Bavaria's precision metalworking cluster around Nuremberg hosts converter facilities qualifying polyester-based internal coatings to meet REACH bisphenol-A restrictions.
United States
Premium craft beverage and pet food applications sustain demand for both aluminum lightweighting and tinplate cost efficiency. FDA food-contact substance notification requirements delay new coating introductions by 18-24 months. The Midwest canning belt spanning Ohio, Indiana, and Illinois preserves legacy steel filling infrastructure while coastal facilities pilot recycled-content aluminum for direct-to-consumer channels.
Japan
Seafood and dairy applications favor precision-drawn steel with organosol linings under JIS tinplate quality specifications. METI packaging sustainability guidelines encourage refill-and-return logistics that align with slip lid reusability. The Kansai industrial corridor around Osaka maintains dedicated capacity for export-oriented shelf-stable formats.
China
Domestic food brands and export processors split demand between cost-optimized steel and specification-grade aluminum. GB standards for food-contact metals create compliance complexity for converters serving multiple destination markets. The Yangtze River Delta packaging cluster near Shanghai concentrates coating qualification capacity for brands targeting EU and US regulatory pathways.
United Kingdom
Specialty coffee importers and zero-waste retail channels generate niche demand for verified-recycling-credential aluminum. Extended producer responsibility schemes under the UK Packaging Waste Regulations accelerate format trials in London and Southeast England bulk retail locations. Midlands-based converters leverage legacy beverage can expertise to serve emerging resealable formats.
Slip Lid Can Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated multinationals commanding coating qualification expertise while regional specialists defend margin in legacy tinplate segments. The market structure reflects tiered consolidation: three global converters control premium aluminum beverage specifications, mid-cap independents anchor processed food volume, and Asian specialists dominate precision-drawn steel for seafood. Dominant competitive moves include backward integration into coating chemistry and geographic expansion through distributor partnerships rather than greenfield capacity.
Among North American fabricators, Crown Holdings, Inc. and Silgan Holdings Inc. occupy positions exemplifying scale-driven coating qualification capability, while Toyo Seikan Group Holdings Ltd. represents the Asian precision-steel archetype. These three named entities anchor the competitive landscape without exhausting its structure, as independent regional converters and private-label specialists fill volume tiers where specification requirements permit standardized sourcing.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Silgan Holdings Inc. |
| Ball Corporation |
| Ardagh Group |
| Independent Can Company |
| Sonoco Products Company |
| Berry Global |
| Toyo Seikan Group Holdings Ltd. |
| Allstate Can Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German ready-to-drink coffee brands and aluminum converters lock in both coating allocation priority and eighteen-month price visibility against LME volatility. These agreements tether volume commitments to REACH-compliant polyester lining qualifications, embedding regulatory compliance costs directly into contract structures.
Pricing Analysis
EU REACH bisphenol-A restrictions dictate the pricing tier structure by forcing coating revalidation investments that stratify converters into qualified premium suppliers versus legacy standard-tier competitors. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified aluminum formats from tinplate steel and flexible pouch alternatives. Cost compression in standard steel tiers intensifies because flexible pouch substitution erodes volume scale. Private-label food brands exhibit the highest price sensitivity, while premium beverage marketers absorb specification premiums for verified recycling credentials.
Supply Chain Analysis
Strait of Malacca transit routes for tinplate coil shipments from Japanese mills to Southeast Asian seafood processors represent a logistics chokepoint that amplifies lead time variance. Converter capacity concentrates in Germany, the United States, and Japan, with raw material feeds drawing from LME aluminum warehouses, Brazilian tinplate ore, and Korean epoxy resin suppliers. Single-source vulnerability in polyester coating chemistry creates supply chain risk as REACH deadlines consolidate qualified supplier relationships. Distribution runs through bulk retail and zero-waste store channels in EU member states, with e-commerce direct-to-consumer volume expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating revalidation services and refill logistics infrastructure represent recurring-revenue layers expanding faster than base metal packaging hardware. The EU Green Deal's packaging reuse targets transform one-time can sales into ongoing service relationships.
For Market Incumbents: Consolidate coating qualification expertise through captive R&D investment in polyester and acrylic alternatives, locking out mid-cap competitors facing eighteen-month FDA notification delays. Secure priority allocation agreements with German seafood processors facing the tightest REACH compliance deadlines. Backward integration into epoxy resin supply buffers raw material volatility while preserving margin in premium aluminum tiers.
For New Entrants and Emerging Players: FDA food-contact substance notification fast-tracks offer entry pathways into US craft beverage segments where incumbent coating portfolios face revalidation bottlenecks. Target zero-waste retail channels in London and Southeast England where verified recycling credentials command specification premiums unavailable in conventional wholesale. Partner with independent can decorators to bypass integrated converter capacity constraints.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with qualified polyester coating portfolios and established German food canning relationships. Long-term viability hinges on refill infrastructure alignment rather than single-use volume scale. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal separating service-attach winners from commodity metal losers.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Qualification | REACH-compliant polyester alternatives secure priority allocation from German dairy processors facing 2025 deadlines. |
| Refill Infrastructure Partnership | Zero-waste store alliances in Bavaria convert single-use sales into recurring logistics revenue under EU reuse targets. |
| Backward Integration into Resin Supply | Captive epoxy production shields margin from Korean supplier concentration and LME-tethered input volatility. |
| Precision-Drawn Steel Capacity Expansion | JIS-certified tinplate formats capture Asian seafood export volume with organosol barrier advantages over aluminum. |
| Direct-to-Consumer Channel Development | E-commerce specifications demand enhanced seam integrity that differentiates premium converters from wholesale-standard competitors. |
Research Methodology
Desk research of EU regulatory filings, FDA food-contact substance notifications, and customs trade data preceded structured interviews with coating R&D directors, beverage brand procurement leads, and zero-waste retail channel operators. Primary fieldwork with German cannery engineers and Japanese tinplate quality inspectors anchored volume assumptions. Secondary validation drew from SEC 10-K disclosures of listed packaging converters, ECHA REACH registration databases, and trade association production statistics. Bottom-up capacity modeling triangulated against top-down consumption estimates across material substrate and end-use segments.
Variance decomposition across the projection horizon isolates volume drivers by material tier, regulatory compliance cluster, and channel mix. Segmentation dimensions modeled include aluminum versus steel substrate, food and beverage versus personal care end-use, and retail versus direct sales channel. CAGRs were derived from historical production trends adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated REACH coating approval timelines and EU Green Deal procurement mandate phase-ins.
Underlying assumptions cover sustained LME price bands, REACH enforcement consistency, and refill infrastructure investment rates, with deviation risk concentrated in coating chemist talent scarcity and flexible pouch substitution acceleration. Revision becomes warranted when bisphenol-A restriction deadlines shift or aluminum input volatility crosses margin compression thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Coating Market
Containers
Lever Lid Cans Market
Containers
Foam Containers Market
Containers
Packaging Bins Market
Containers
Global Food Storage Container Market
Containers
Asia and Africa Food Cans Market
Containers
Conipack Pails Market
Containers
Half Height Containers Market
Containers
Foldable Container Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Global Container Monitoring Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Containerboard Market
Containers
Disposable Lids Market
Containers
Spout Containers Market
Containers
Container Stacking Machine Market