
 Sandwich Containers Market | 2026-2036
Sandwich Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Containers Market Analytics
Food-grade polymer engineering talent is reorganizing how manufacturers approach barrier performance and seal integrity in sandwich container production. Tupperware Brands Corporation leverages decades of direct-selling infrastructure to sustain consumer loyalty in home-use segments. Rubbermaid Commercial Products LLC anchors its position through institutional channel control, supplying food service operators with standardized, stackable systems. Lock & Lock Co., Ltd. differentiates via patented four-side locking mechanisms that dominate airtight closure expectations across Asian and European retail.
Sandwich containers are rigid or semi-rigid receptacles designed to protect prepared sandwiches from moisture loss, contamination, and compression during storage or transport, typically manufactured through injection molding or thermoforming with wall thicknesses ranging from 0.5 to 2.0 millimeters depending on material and reuse cycles. Plastic remains the volume leader due to cost scalability, though biodegradable alternatives are gaining fastest as European Union Single-Use Plastics Directive enforcement tightens material specifications. The food service end-user segment commands the highest per-unit procurement volumes, while meal prep applications concentrate margin pools through subscription-box partnerships and portion-control specifications.
The U.S. Food and Drug Administration governs indirect food additive migration limits under 21 CFR, while the European Chemicals Agency enforces REACH substance restrictions on phthalates and bisphenol derivatives in food-contact articles. These frameworks compel manufacturers to reformulate base resins and validate substitute chemistries through migration testing protocols. Stakeholders must monitor evolving extended producer responsibility legislation in multiple jurisdictions, as compliance cost allocation between resin suppliers, molders, and brand owners remains unresolved and will determine competitive cost structures.
Market Dynamics
Extended producer responsibility legislation is compressing margin structures across sandwich container supply chains as manufacturers absorb compliance costs previously externalized to municipal waste systems.
Growth Catalysts
- EU Single-Use Plastics Directive:Enforcement mandates are pulling food service operators toward durable, multi-use container programs to avoid material restrictions on disposable alternatives.
- Deposit-return infrastructure:Germany's national packaging law operationalizes reusable container circulation through standardized return logistics at retail points.
- Barrier polymer engineering:Advances in co-extrusion technology enable thinner wall constructions without compromising seal integrity or moisture protection.
Market Restraints
- Food-grade resin cost volatility:Polypropylene and polyethylene terephthalate feedstock prices fluctuate with crude oil indices, squeezing converter margins on fixed-price institutional contracts.
- Multi-use certification timelines:Migration testing protocols under FDA 21 CFR and EFSA food contact guidelines extend product development cycles by 8-14 months.
- Silicone gasket substitution:Thermoplastic elastomer alternatives threaten traditional silicone seal components in premium container segments.
Strategic Opportunities
- Subscription meal kit channels:Portion-control specifications in prepared food delivery create demand for standardized, stackable container formats with integrated labeling zones.
- Reverse logistics partnerships:Collaboration with urban food delivery platforms enables container pooling systems that reduce per-use costs below disposable equivalents.
- Biodegradable resin formulations:Polylactic acid and polyhydroxyalkanoate blends respond to municipal composting infrastructure expansion in France and the Netherlands.
Industry Challenges
- Migration testing capacity constraints:Third-party laboratory bottlenecks delay regulatory approval for reformulated base resins, compressing product launch windows.
- Mold tooling capex intensity:Multi-cavity injection molds for airtight closure mechanisms require capital deployment exceeding mid-tier converter balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Containers Market |
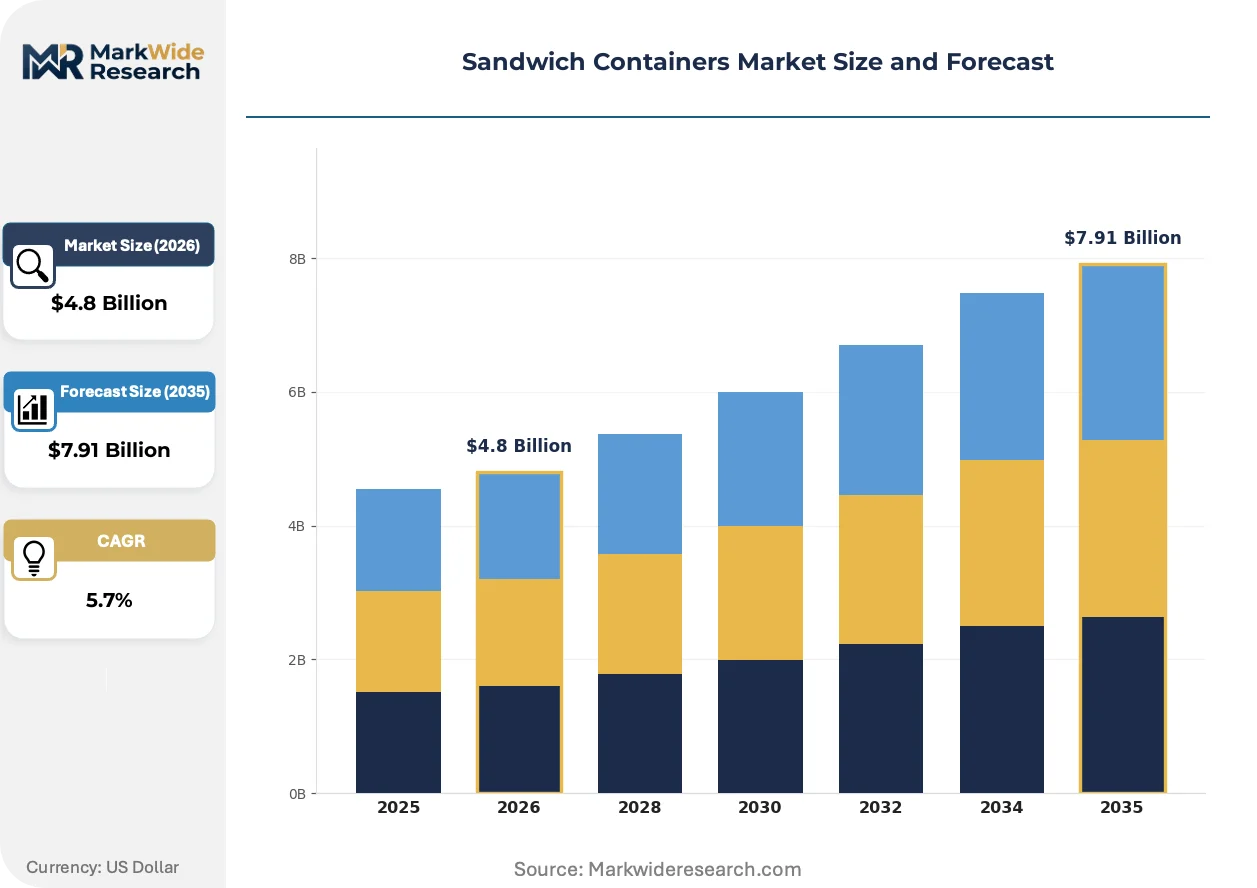
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Glass, Stainless Steel, Biodegradable Size: Small, Medium, Large, Extra Large Closure Type: Snap-On, Twist-Off, Airtight, Latch End User: Retail, Food Service, Meal Prep, Home Use |
| Companies Covered | Tupperware Brands Corporation, Rubbermaid Commercial Products LLC, Lock & Lock Co., Ltd., Newell Brands Inc., Snapware Corporation, OXO International Ltd., Thermos L.L.C., Schur Flexibles Holding GesmbH, Eco-Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Containers Market Evolving Landscape
Active barrier technologies and circular material flows are restructuring how sandwich containers deliver functional performance while satisfying tightening regulatory specifications on end-of-life pathways.
Thin-film oxygen scavenger integration is miniaturizing active packaging components into container sidewalls rather than discrete sachets. Meal prep subscription services are specifying these embedded barriers for protein-heavy sandwich contents requiring extended refrigerated shelf life. The technology is compressing differentiation potential among converters lacking in-house polymer compounding capabilities.
REACH substance restrictions on phthalates and bisphenol derivatives are forcing base resin reformulations across European supply chains. Manufacturers are validating substitute chemistries through migration testing protocols before commercial deployment. Food service procurement in Germany and France now requires third-party certification of bisphenol-free status, shifting competitive advantage to vertically integrated compounders.
Direct-to-operator distribution platforms are disintermediating traditional food service supply houses for reusable container procurement. Institutional buyers are consolidating purchasing through digital marketplaces that standardize specifications across multi-location operators. This channel compression is most advanced in North American urban food service clusters where municipal single-use bans create urgent compliance deadlines.
Sandwich Containers Market Segmentation
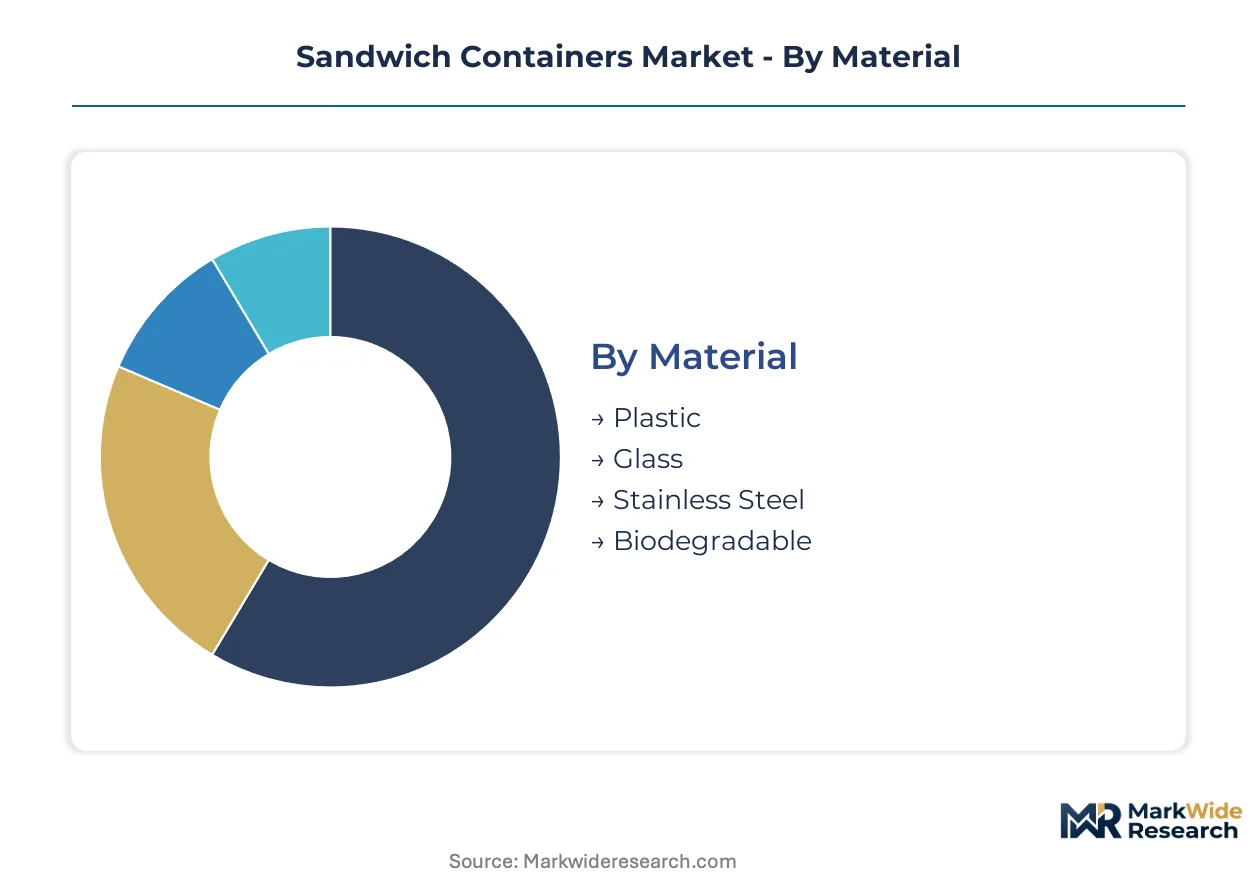
Segmentation in sandwich containers determines compliance pathways, procurement economics, and end-of-life handling obligations. Material specifications trigger distinct regulatory regimes across jurisdictions, while closure mechanisms define reuse-cycle durability and food safety validation requirements.
Material:
FDA 21 CFR governs plastic migration limits in the United States, while ECHA REACH restrictions on phthalates and bisphenol derivatives reshape European resin formulations. These divergent frameworks fragment supplier qualification requirements and compound certification costs for multi-region manufacturers.
- Plastic:Polypropylene and polyethylene terephthalate dominate through injection-molded and thermoformed constructions with wall thicknesses of 0.5 to 2.0 millimeters. Food service operators in Germany source plastic containers through deposit-return schemes mandated by national packaging law, though EFSA migration testing protocols extend development cycles.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate blends respond to municipal composting infrastructure in France and the Netherlands. These formulations face the steepest expansion trajectory as EU Single-Use Plastics Directive enforcement tightens specifications on disposable alternatives.
- Glass:Borosilicate and soda-lime compositions deliver inert barrier properties for premium home-use segments in Japan and Switzerland. Weight penalties constrain food service adoption despite superior microwave compatibility.
- Stainless Steel:18/8 and 304-grade alloys serve institutional meal prep applications requiring thermal retention and mechanical durability. Higher unit costs limit penetration beyond subscription-box partnerships specifying portion-control formats.
Established volume favors plastic; emerging adoption favors biodegradable.
Size:
Dimensional specifications correlate directly with portion-control economics in prepared food delivery and institutional procurement contracts. Standardization pressures from meal kit operators compress SKU proliferation among converters serving subscription channels.
- Medium:450-650 milliliter capacities capture the majority of single-sandwich retail and home-use demand. German food service operators specify medium formats for standardized return logistics under deposit-return infrastructure.
- Large:750-1000 milliliter volumes concentrate in meal prep subscriptions requiring multi-component sandwich assembly with segregated compartments. North American urban food delivery platforms specify large containers for reverse logistics pooling systems.
- Small:Sub-400 milliliter formats serve snack-sized portions and children's lunch segments. Limited barrier surface area reduces material costs for biodegradable resin formulations.
- Extra Large:Exceeding 1000 milliliter capacities address catering and family-size portions. Stackability constraints and storage footprint penalties restrict adoption beyond institutional channels.
Procurement scale concentrates in medium; margin expansion concentrates in large.
Closure Type:
Seal integrity specifications determine moisture retention performance and regulatory validation requirements for extended shelf-life applications. Patent-protected locking mechanisms differentiate premium positioning in Asian and European retail channels.
- Airtight:Silicone gasket or thermoplastic elastomer seals with four-side locking mechanisms dominate freshness-sensitive segments. EFSA food contact guidelines govern elastomer migration limits, compelling reformulation of traditional silicone components.
- Snap-On:Single-motion engagement suits high-throughput food service environments where speed of access outweighs extended barrier performance. Lower tooling costs attract mid-tier converters with constrained capital deployment capacity.
- Latch:Mechanical hinge systems provide audible closure confirmation for institutional quality assurance protocols. Metal hinge components face REACH substance restrictions on nickel release in European markets.
- Twist-Off:Threaded engagement mechanisms concentrate in glass container formats for home-use microwave applications. Torque specifications require calibrated capping equipment that elevates per-unit production costs.
Food service procurement gravitates toward snap-on; subscription meal kit specifications favor airtight.
End User:
Channel-specific requirements fragment demand across regulatory compliance, volume scale, and customization intensity. Direct-to-operator digital marketplaces are compressing traditional food service supply house margins in North American urban clusters.
- Food Service:Institutional operators command highest per-unit procurement volumes with standardized, stackable specifications. Municipal single-use bans in U.S. coastal cities and Canadian provinces accelerate reusable container program adoption.
- Meal Prep:Subscription-box partnerships concentrate margin pools through portion-control specifications and integrated labeling zones. Active barrier technology integration for protein-heavy contents drives premium pricing in this segment.
- Retail:Branded and private-label shelf placement requires compliance with FDA indirect food additive migration limits and state-level disclosure requirements. Competition from direct-selling infrastructure constrains margin capture.
- Home Use:Consumer loyalty programs and direct-selling networks sustain repeat purchase economics. Airtight closure expectations in Asian and European markets elevate performance thresholds for market entry.
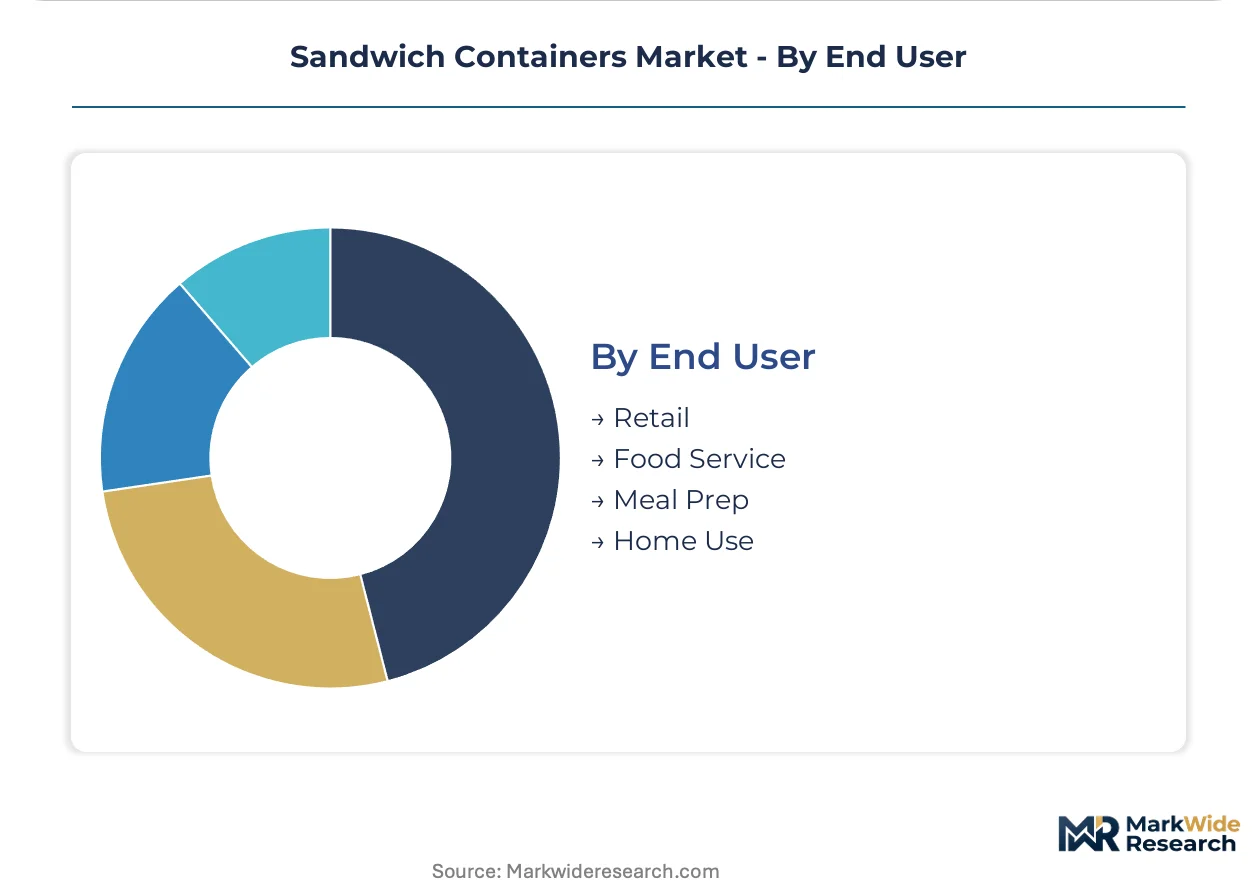
Volume concentration sits with food service; margin rate concentration sits with meal prep.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA migration testing protocols and Germany's national packaging law anchor European regulatory leadership in sandwich container compliance pathways. Food service operators across multiple jurisdictions navigate divergent substance restrictions while municipal single-use bans accelerate reusable program adoption.
United States
Coastal municipal single-use bans in California and New York Metro drive food service operator procurement shifts toward durable container programs. FDA 21 CFR indirect food additive migration limits govern base resin formulations for domestic manufacturers. Chicago and Los Angeles urban food delivery platforms pilot reverse logistics pooling systems that reduce per-use costs below disposable equivalents.
Germany
National packaging law operationalizes reusable container circulation through standardized deposit-return logistics at retail points. ECHA REACH substance restrictions on phthalates compel base resin reformulations across converter supply chains. Bavaria's industrial molding clusters concentrate multi-cavity injection tooling capacity for airtight closure mechanisms serving institutional buyers.
France
Municipal composting infrastructure expansion in Paris and Lyon accelerates polylactic acid formulation adoption for biodegradable alternatives. ANSM enforces food contact material safety standards that exceed baseline EU requirements. Auvergne-Rhône-Alpes chemical compounding facilities validate substitute chemistries ahead of commercial deployment.
Japan
PMDA pharmaceutical-grade manufacturing standards migrate into premium home-use container specifications for borosilicate glass formats. METI circular economy roadmaps incentivize durable product design across consumer goods sectors. Osaka-Kobe industrial corridors anchor precision molding capabilities for four-side locking mechanism production.
Netherlands
Randstad logistics hubs enable container pooling system pilots with urban food delivery platforms across Amsterdam and Rotterdam. National extended producer responsibility frameworks allocate compliance costs between resin suppliers and brand owners. Eindhoven polymer research institutes advance co-extrusion technology for thinner wall constructions without seal integrity compromise.
Sandwich Containers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in sandwich container manufacturing, with compounders controlling resin formulation advantages and molders competing on closure mechanism precision. The market structure rewards backward integration into food-grade polymer engineering while penalizing converters dependent on external resin supply. Three archetypes dominate: vertically integrated compounder-molders, precision closure specialists, and direct-selling infrastructure operators. Capacity expansion in multi-cavity injection tooling and strategic partnerships with urban food delivery platforms represent the dominant competitive moves reshaping procurement channels.
Within the direct-selling infrastructure tier, Tupperware Brands Corporation exemplifies consumer loyalty sustainment through decades-honed distribution networks. Among precision closure specialists, Lock & Lock Co., Ltd. occupies a position defined by patented four-side locking mechanism differentiation across Asian and European retail channels. At the institutional supply vector, Rubbermaid Commercial Products LLC anchors food service operator relationships through standardized, stackable system specifications. These three entities represent distinct strategic postures rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Tupperware Brands Corporation |
| Rubbermaid Commercial Products LLC |
| Lock & Lock Co., Ltd. |
| Newell Brands Inc. |
| Snapware Corporation |
| OXO International Ltd. |
| Thermos L.L.C. |
| Schur Flexibles Holding GesmbH |
| Eco-Products Inc. |
| Others |
Value Network & Pricing Analysis
Multi-cavity injection tooling scale economies in Bavaria and Osaka-Kobe industrial corridors concentrate mold fabrication capacity among converters with balance-sheet depth, compressing price floors for airtight closure mechanisms while elevating entry barriers for mid-tier competitors lacking captive production assets.
Pricing Analysis
German deposit-return infrastructure commands premium pricing for standardized reusable formats versus North American transactional spot markets. Three-tier pricing structure across premium airtight, standard snap-on, and economy single-use levels differentiates by certification grade and closure mechanism complexity. Cost compression in food-grade resin formulations is intensifying because ECHA REACH compliance extends development timelines. Food service operators exhibit highest price sensitivity due to institutional procurement scale, while meal prep subscription channels absorb premium positioning for active barrier integration.
Supply Chain Analysis
Inventory lead times for silicone gasket and thermoplastic elastomer components stretch 14-20 weeks due to polymer compounding bottlenecks in Germany and Japan. Raw material sourcing draws from Saudi Arabian polypropylene feedstock, South Korean PET resin, and Belgian co-extrusion equipment. Single-source vulnerability concentrates in precision mold tooling fabricated by Bavarian and Osaka-Kobe specialists. Distribution runs through direct-to-operator digital marketplaces disintermediating traditional food service supply houses in North American urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sandwich container demand acceleration reflects a high-growth disruption anchored in EU Single-Use Plastics Directive enforcement pulling food service operators toward durable multi-use programs.
For Market Incumbents: Shield market position through backward integration into food-grade polymer compounding to capture REACH compliance cost allocation. Prioritize capacity addition in Germany to service deposit-return logistics standardization. Defensive patent filings around four-side locking mechanism miniaturization counter thermoplastic elastomer substitution threats in premium segments. For New Entrants and Emerging Players: Differentiate on biodegradable resin formulations for French and Dutch municipal composting infrastructure. Target meal prep subscription channels specifying active barrier integration as the most penetrable white-space. Pursue direct-to-operator digital marketplace partnerships as primary go-to-market angle bypassing incumbent supply house relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated compounder-molders with in-house migration testing capabilities. Five-to-ten year viability hinges on regulatory compliance cost absorption rather than commodity volume scale. Acquisition target archetype: precision closure specialists with patented locking mechanisms. Signal to watch: third-party laboratory capacity expansion rates as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cavity Injection Tooling Investment | Bavarian and Osaka-Kobe mold fabrication clusters enable airtight closure precision at scale. |
| Biodegradable Resin Formulation Partnership | Polylactic acid and polyhydroxyalkanoate blends respond to French municipal composting infrastructure expansion. |
| Reverse Logistics Platform Integration | Urban food delivery pooling systems in Chicago and Los Angeles reduce per-use costs below disposable equivalents. |
| Migration Testing Laboratory Acquisition | In-house EFSA and FDA 21 CFR validation compresses 8-14 month certification timelines. |
| Direct-to-Operator Digital Marketplace Launch | Disintermediation of traditional food service supply houses captures procurement consolidation in coastal U.S. cities. |
Research Methodology
Initial hypotheses were tested against primary input from food service procurement directors, polymer compounding engineers, regulatory affairs specialists at converters, and meal kit supply chain managers and refined through secondary validation against EFSA migration testing protocols, FDA 21 CFR indirect food additive filings, German national packaging law implementation reports, and EU Single-Use Plastics Directive enforcement guidance. Bottom-up volume modeling across material-grade and closure-type segments triangulated with top-down value aggregation.
Variance-decomposition across the projection horizon isolates regulatory compliance cost absorption, resin feedstock price volatility, and channel structure shifts as primary forecast drivers. Segmentation dimensions include material specification, closure mechanism type, end-user channel, and geographic regulatory cluster. CAGRs derive from installed base replacement cycles and reusable program adoption curves. Industry-specific inputs encompass deposit-return logistics penetration rates and municipal single-use ban implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained ECHA enforcement or accelerated biodegradable resin scale-up would require recalibration. Forecasts reflect documented assumptions on regulatory trajectory and substitution elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Lift-Off Lid Box Market
Containers
Sanitary Cans Market
Containers
Global Multi Pack Carriers Market
Containers
Composite Ibcs System Market
Containers
Reconditioned IBC Market
Containers
ISO Ocean Containers Market
Containers
Tottle Containers Market
Containers
Water Resistant Packing Cubes Market
Containers
Disposable Cups and Lids Market
Containers
Mini Spray Bottles Market
Containers
PET Hinged Containers Market
Containers
Stainless Steel Cask Market
Containers
Canning Jars Market
Containers
Essential Oil Containers Market
Containers
EPS Container Market
Containers
Compartment Take-Out Container Market