
 Foam Containers Market | 2026-2036
Foam Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Containers Market Foresight
Biodegradable foam chemistry is fragmenting traditional petroleum-based supply chains as converters reformulate around starch and mycelium alternatives. Dart Container Corporation leverages its captive resin compounding network to stabilize input costs across North American thermoforming operations. Huhtamaki Group anchors European demand through molded fiber integration at its flagship manufacturing campus in the Netherlands. Sealed Air Corporation differentiates via performance-engineered polyethylene foam grades targeting temperature-sensitive pharmaceutical distribution.
Foam containers are engineered cellular structures manufactured through expansion, molding, or thermoforming of synthetic or natural polymers, typically achieving densities between 16 and 96 kilograms per cubic meter depending on end-use cushioning or insulation requirements. Polystyrene retains dominance in cost-driven food service applications despite municipal restrictions, while molded pulp captures premium positioning among beauty brands pursuing plastic elimination commitments. Polyurethane foam leads electronics protection segments where anti-static formulations and precise compression set characteristics justify higher unit economics against commodity alternatives.
The US FDA regulates food-contact substances under 21 CFR 177, while the EU REACH framework restricts certain styrene monomer residuals, and California's DTSC lists polystyrene in priority product evaluations under Safer Consumer Products regulations. These overlapping compliance obligations compel manufacturers to maintain parallel certification streams for cross-border distribution. Stakeholders must monitor emerging extended producer responsibility frameworks in multiple jurisdictions that will reshape collection infrastructure and material recovery economics.
Market Dynamics
Biodegradable foam chemistry is fragmenting petroleum-based supply chains as converters reformulate around starch and mycelium alternatives, forcing raw material procurement restructuring across thermoforming operations.
Growth Catalysts
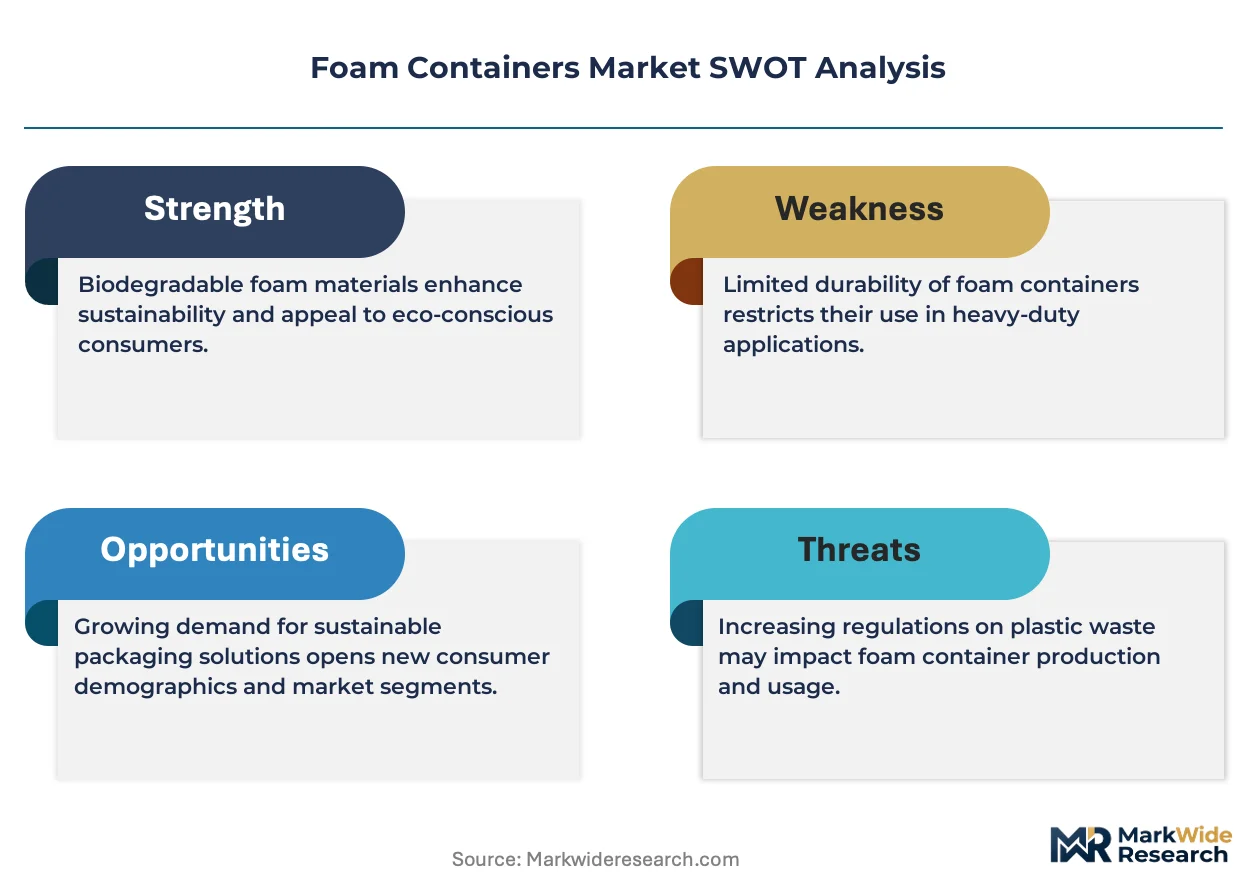
- EU REACH framework restrictions on styrene monomer residuals:These compliance obligations accelerate investment in alternative polymer platforms by multinational suppliers seeking cross-border distribution continuity.
- Electronics export manufacturing clusters:Southeast Asian production hubs drive protective packaging consumption as semiconductor and consumer device assembly expands insulated container requirements.
- Quick-service restaurant plastic replacement mandates:Municipal single-use plastic prohibitions in multiple jurisdictions redirect food service procurement toward insulated foam alternatives for hot and cold chain applications.
Market Restraints
- Petrochemical feedstock volatility:Styrene monomer and polyurethane precursor costs fluctuate with crude oil indices, compressing converter margins on fixed-price food service contracts.
- California DTSC Safer Consumer Products evaluations:State-level priority product listings for polystyrene create parallel compliance streams that duplicate certification costs for US-focused manufacturers.
- Molded pulp substitution in premium beauty packaging:Plastic elimination commitments by cosmetics brands displace foam containers in gift set and fragrance applications where aesthetics justify higher unit costs.
Strategic Opportunities
- Temperature-sensitive pharmaceutical distribution:Cold chain biologics and vaccine logistics create demand for performance-engineered polyethylene foam grades with validated thermal protection profiles.
- Extended producer responsibility framework expansion:Emerging collection infrastructure mandates in multiple jurisdictions reshape material recovery economics for foam container producers with reverse logistics capabilities.
- Mycelium-starch composite integration:Convergence of agricultural waste processing and fungal cultivation biotechnology enables home-compostable foam alternatives at commercial scale.
Industry Challenges
- Parallel FDA-EFSA certification maintenance:Divergent food-contact substance approvals under 21 CFR 177 and EU safety assessments require duplicate toxicology documentation and testing protocols.
- Thermoforming equipment reconfiguration:Legacy polystyrene production lines demand capital-intensive retrofitting to process biodegradable alternatives with different melt flow and cooling characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Containers Market |
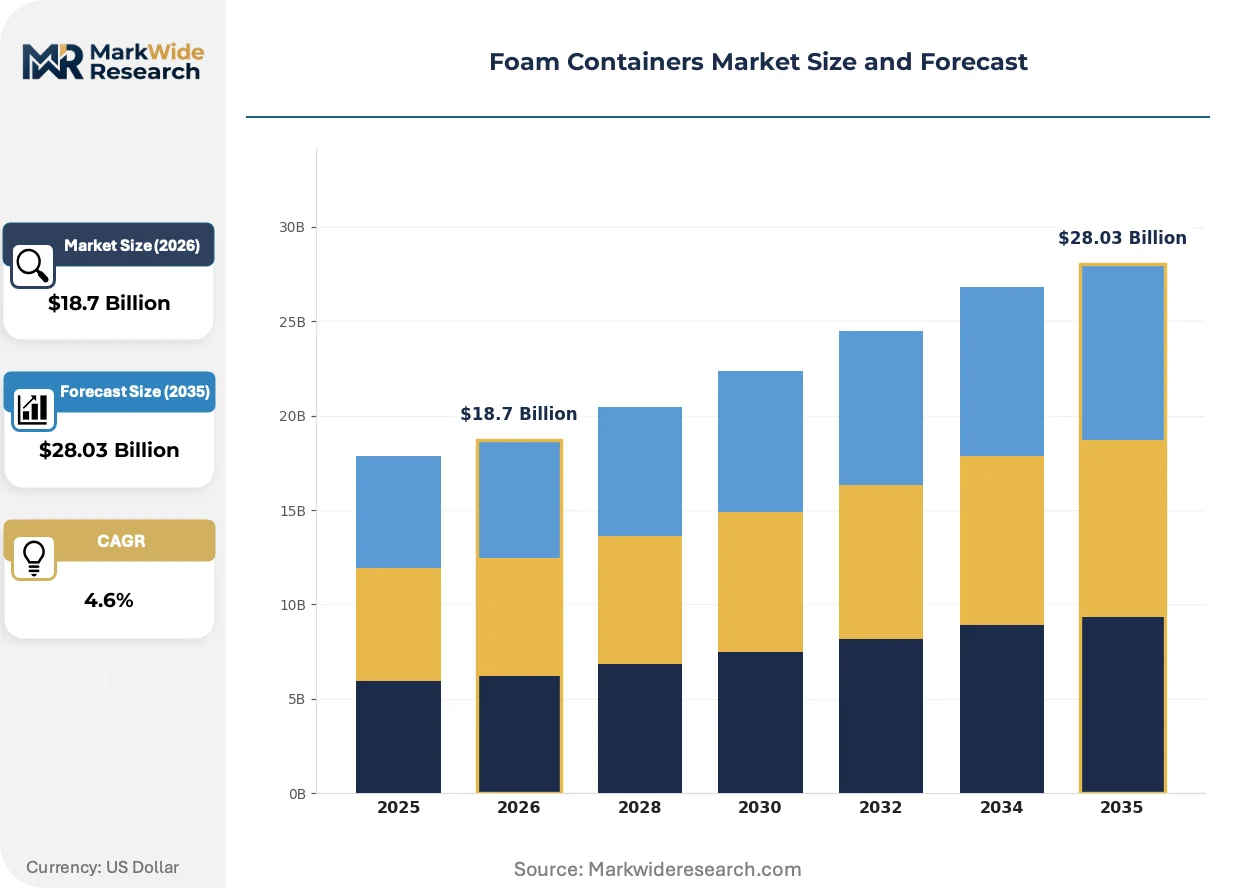
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polystyrene, Polyethylene, Polyurethane, Polypropylene, Molded Pulp Application: Food Packaging, Pharmaceutical Packaging, Electronics Protection, Cosmetic Packaging, Industrial Packaging End User Industry: Fast Food Chains, Pharmaceutical Manufacturers, Electronic Assemblers, Beauty Brands, Manufacturing Units Packaging Style: Clamshell, Tray, Cup, Box, Sleeve |
| Companies Covered | Drew Foam Co, Inc., Atlas Foam Products, Dart Container Corporation, Huhtamaki Group, Sealed Air Corporation, Pactiv Evergreen Inc., Premier Protective Packaging, UFP Technologies, Genpak LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Containers Market Shifts & Advancements
Active reformulation across the value chain is compressing traditional material hierarchies as converters, brand owners, and waste managers simultaneously pursue divergent performance and sustainability targets.
Expanded polystyrene bead molding is migrating from commodity food service trays toward specialized pharmaceutical cold chain shippers where thermal performance validation commands premium positioning. Biologics distributors in North America and Europe now specify foam containers with documented phase-change material compatibility. This technology shift compresses unit volumes in traditional quick-service applications while expanding margin capture in healthcare logistics.
California's Department of Toxic Substances Control maintains active priority product evaluations for polystyrene under Safer Consumer Products regulations, compelling manufacturers to submit alternative assessment analyses. Industrial consequence includes accelerated reformulation timelines and pre-emptive substitution in brand owner supply chains. Food packaging segments serving California-operating quick-service chains are responding with pilot programs for molded fiber and bio-based foam alternatives ahead of potential listing finalization.
Certification-driven procurement now dominates buyer evaluation criteria as extended producer responsibility frameworks emerge across multiple jurisdictions. Direct supplier relationships are displacing distributor-mediated purchasing for large quick-service and pharmaceutical accounts seeking chain-of-custody documentation. This pattern is most visible in European Union member states where packaging waste directive implementation varies by national transposition timeline.
Foam Containers Market Segmentation
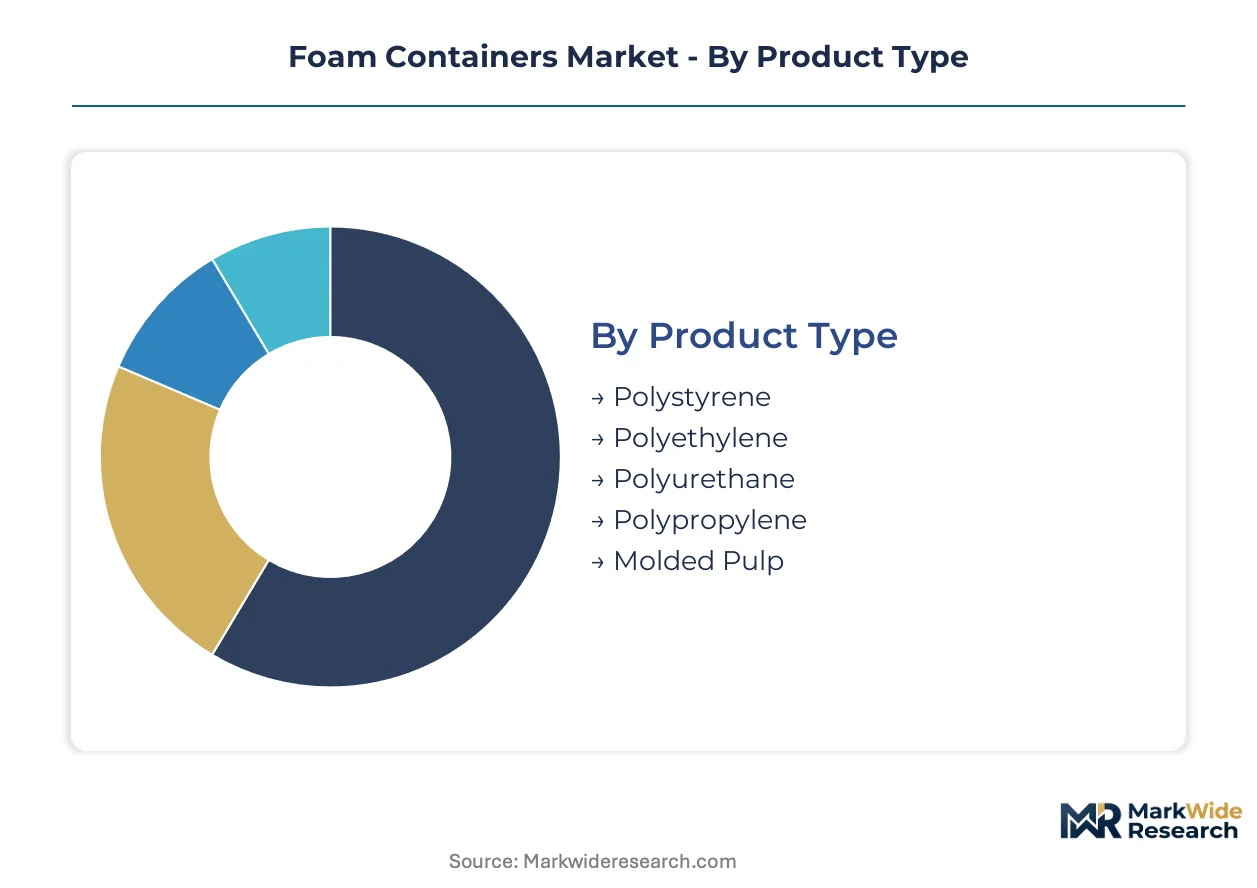
Material chemistry and end-use thermal requirements fragment procurement patterns across foam container categories. Each segmentation dimension reveals distinct margin structures and compliance obligations that reshape supplier positioning.
Product Type:
After-sales technical support intensity varies sharply by polymer chemistry, with polyurethane and polyethylene formulations demanding specialized equipment calibration services that polystyrene converters rarely provide.
- Polystyrene:Expanded bead structures achieve densities between 16 and 32 kilograms per cubic meter through steam molding of pre-expanded resin particles. Quick-service restaurant procurement in the United States concentrates here despite municipal restrictions in California and New York City driving substitution trials.
- Polyethylene:Cross-linked and non-cross-linked grades offer closed-cell moisture resistance with compression set recovery critical for pharmaceutical cold chain validation. Temperature-sensitive biologics distribution in Germany and the United Kingdom specifies these grades for validated thermal protection profiles.
- Polyurethane:Reaction-injection molded systems deliver precise cushioning for electronics protection with anti-static additive compatibility.
- Polypropylene:Higher service temperatures suit microwaveable food applications with expanded bead processing similar to polystyrene.
- Molded Pulp:Cellulosic fiber compression molding serves beauty brands pursuing plastic elimination commitments with home-compostable end-of-life credentials.
Polystyrene holds the largest share; momentum sits with molded pulp.
Application:
Cost tier stratification separates commodity food service from premium pharmaceutical validation requirements that command five-to-ten-fold unit price multiples.
- Food Packaging:Thermoformed trays and hinged containers dominate quick-service restaurant procurement with insulation performance driving hot and cold chain specifications. Municipal single-use plastic prohibitions across multiple jurisdictions redirect demand toward foam alternatives.
- Pharmaceutical Packaging:Validated cold chain shippers with documented phase-change material compatibility serve biologics and vaccine distribution. North American and European distributors now require thermal performance documentation that commodity converters cannot supply.
- Electronics Protection:Anti-static and conductive formulations protect semiconductor and consumer device assemblies during Southeast Asian export manufacturing.
- Cosmetic Packaging:Gift set and fragrance applications increasingly specify molded fiber alternatives as beauty brands execute plastic elimination commitments.
- Industrial Packaging:Heavy-duty cushioning for machinery and automotive components utilizes higher-density polyurethane and polyethylene grades.
Food packaging commands volume concentration; pharmaceutical packaging captures margin expansion.
End User Industry:
Customer procurement sophistication spans distributor-mediated purchasing for fragmented fast food operators to direct supplier relationships with pharmaceutical manufacturers requiring chain-of-custody documentation.
- Fast Food Chains:Consolidated procurement by multinational operators drives volume concentration with sustainability mandates accelerating material substitution pilots. California-operating chains face DTSC priority product evaluation pressures.
- Pharmaceutical Manufacturers:Cold chain biologics producers specify performance-engineered grades with validated thermal profiles and regulatory documentation.
- Electronic Assemblers:Semiconductor and consumer device manufacturing clusters in Vietnam and Malaysia drive protective packaging consumption.
- Beauty Brands:Premium positioning justifies higher unit costs for molded fiber and bio-based alternatives.
- Manufacturing Units:Industrial machinery and automotive component protection utilizes standard-density polyethylene and polyurethane grades.
Fast food chains represent the largest addressable base; pharmaceutical manufacturers offer the steepest expansion trajectory.
Packaging Style:
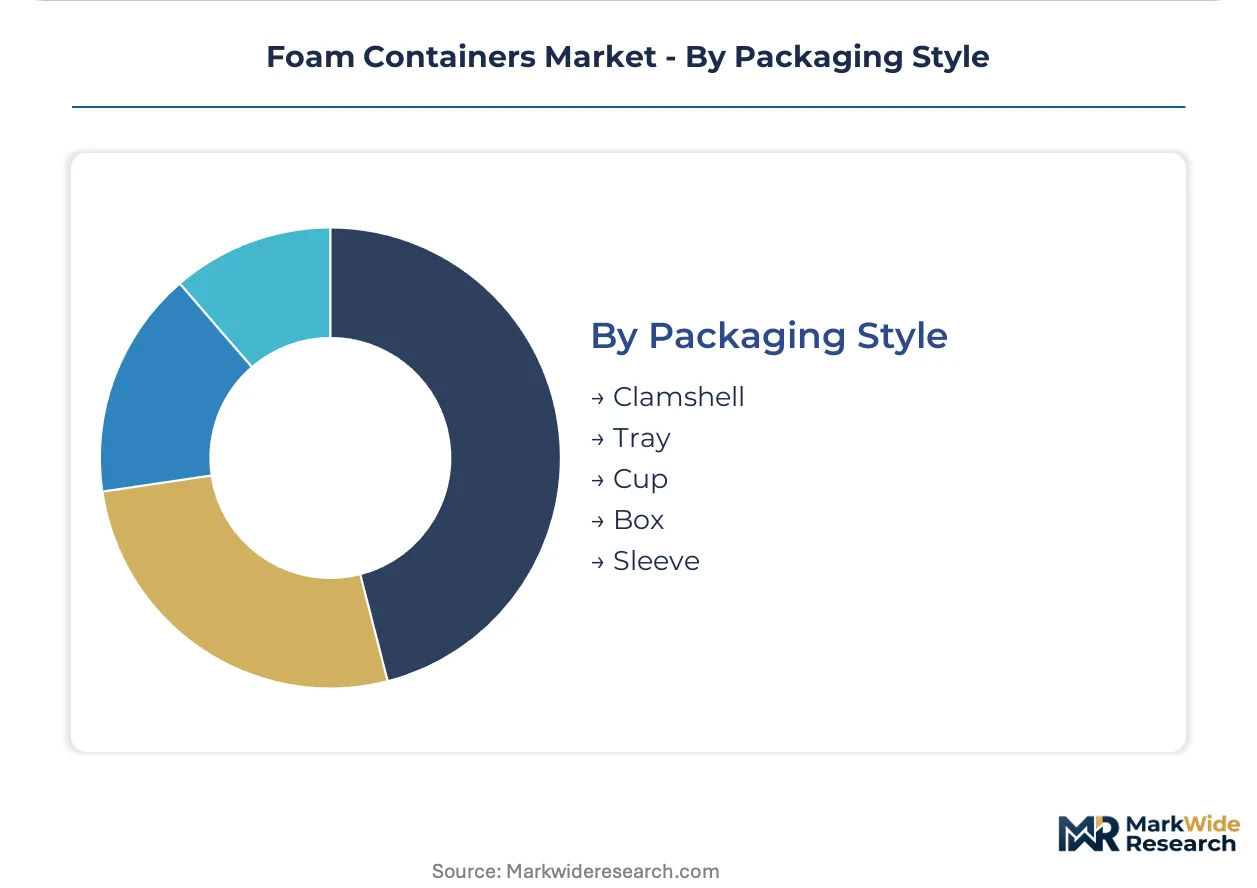
Volume scale concentrates in tray and cup formats while margin capture favors specialized clamshell and box configurations with customization requirements.
- Clamshell:Hinged single-piece construction serves ready-to-eat meals and electronics with tamper-evident closure requirements. Quick-service salad and sandwich applications in the United States specify these formats.
- Tray:Open-top thermoformed structures dominate meat and produce retail packaging with overwrap film compatibility. Commodity food service procurement concentrates here.
- Cup:Tapered sidewall designs for beverage and soup applications compete with paper alternatives on insulation performance.
- Box:Rigid six-sided containers serve pharmaceutical cold chain and premium electronics with assembly-required designs.
- Sleeve:Wrap-around cushioning for cylindrical and irregular shapes provides corner protection with minimal material usage.
Tray formats hold the largest share; box configurations gain share fastest on pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports protective foam containers to semiconductor assembly operations in South Korea and Japan, while Germany ships pharmaceutical-grade cold chain solutions to distributors across the European Union and North American biologics networks.
United States
Quick-service restaurant procurement drives expanded polystyrene consumption despite municipal restrictions in California and New York City. The FDA regulates food-contact substances under 21 CFR 177, creating compliance documentation burdens for cross-border suppliers. Chicago and Dallas manufacturing clusters process thermoformed trays for national fast-food distribution networks.
Germany
Temperature-sensitive biologics distribution commands premium polyethylene foam specifications with validated thermal protection profiles. ECHA REACH framework restrictions on styrene monomer residuals accelerate alternative polymer platform investment. The Rhine-Ruhr industrial corridor hosts compounding operations serving pharmaceutical cold chain logistics across the European Union.
China
Electronics export manufacturing clusters in Guangdong and Jiangsu provinces drive protective polyurethane foam consumption for semiconductor and consumer device assembly. The Ministry of Ecology and Environment enforces dual carbon goals that reshape polymer feedstock sourcing for domestic converters. Shenzhen and Suzhou thermoforming operations supply molded pulp alternatives for beauty brand plastic elimination commitments.
Vietnam
Semiconductor and consumer device assembly expansion in Bac Ninh and Hai Phong provinces generates insulated container demand for export logistics. The country's national environmental regulator maintains evolving extended producer responsibility frameworks for packaging waste collection infrastructure. Ho Chi Minh City manufacturing campuses process starch-based foam alternatives for European beauty brand procurement.
Netherlands
Molded fiber integration at flagship manufacturing campuses serves premium positioning among cosmetics brands pursuing plastic elimination. EFSA maintains divergent stances on food-contact polystyrene compared to FDA assessments, complicating multinational supplier certification streams. The Rotterdam port logistics cluster handles reverse logistics capabilities for emerging material recovery economics.
Foam Containers Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated resin compounders and specialized thermoforming operators with distinct regional footprints. Three strategic archetypes dominate: captive resin producers with backward integration into compounding networks, diversified packaging conglomerates with molded fiber integration capabilities, and performance-engineered foam specialists serving validated cold chain applications. Competitive moves center on thermoforming equipment reconfiguration for biodegradable alternatives and pre-emptive substitution pilots ahead of regulatory listing finalization.
Among North American integrated operators, Dart Container Corporation and Pactiv Evergreen Inc. exemplify the scale-driven archetype with captive supply chain control over resin inputs and national distribution reach. Sealed Air Corporation occupies the performance-specialist position, while Huhtamaki Group anchors European molded fiber integration capabilities. Drew Foam Co, Inc. and Atlas Foam Products represent regional thermoforming specialists with concentrated geographic footprints.
| Leading Market Players |
|---|
| Drew Foam Co, Inc. |
| Atlas Foam Products |
| Dart Container Corporation |
| Huhtamaki Group |
| Sealed Air Corporation |
| Pactiv Evergreen Inc. |
| Premier Protective Packaging |
| UFP Technologies |
| Genpak LLC |
| Others |
Supply & Pricing Matrix
Overcapacity in Southeast Asian polystyrene bead molding operations compresses converter margins while simultaneously intensifying price competition for commodity food service contracts across North American quick-service networks. This utilization dynamic forces suppliers to choose between volume retention at depressed unit economics or selective capacity rationalization that risks permanent customer defection to biodegradable alternatives.
Pricing Analysis
Petroleum-based polystyrene versus next-generation mycelium-starch composites versus emerging molded pulp alternatives stratifies pricing across three performance tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical cold chain specifications from commodity food service trays and experimental bio-based pilots. Price differentiation stems from certification grade—FDA 21 CFR 177 compliance versus EU REACH styrene residual thresholds—and from volume scale with multinational quick-service chains extracting steep contractual discounts. Cost compression in standard-density polystyrene is intensifying because styrene monomer feedstock volatility tracks crude oil indices without corresponding contract renegotiation flexibility. Fast food chains demonstrate highest price sensitivity while pharmaceutical manufacturers accept premium positioning for thermal validation documentation.
Supply Chain Analysis
Tariff exposure between Vietnam and the European Union dominates supply chain risk calculations for electronics protective packaging flows serving German and Dutch distribution hubs. Geographic supply concentration centers on China, Vietnam, and the United States for thermoforming operations and resin compounding capacity. Raw material dependencies draw from petrochemical feedstocks—styrene monomer, polyurethane precursors, polyethylene resins—and from agricultural inputs including corn starch and fungal cultivation substrates for biodegradable alternatives. Single-source vulnerability characterizes specialized pharmaceutical-grade polyethylene foam grades where validated thermal performance documentation limits qualified supplier pools. Distribution runs through direct supplier relationships with large quick-service and pharmaceutical accounts displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable foam chemistry sits at early-cycle penetration with municipal single-use plastic prohibitions accelerating procurement redirection toward insulated alternatives ahead of regulatory finalization timelines.
For Market Incumbents: Entrench position through backward integration into captive resin compounding networks that stabilize input cost volatility across North American thermoforming operations. Accelerate thermoforming equipment reconfiguration for mycelium-starch processing ahead of California DTSC priority product listing finalization. Certification investment in parallel FDA-EFSA documentation streams defends cross-border distribution continuity against emerging compliance fragmentation.
For New Entrants and Emerging Players: Mid-market pharmaceutical cold chain distributors in Germany and the United Kingdom represent the most penetrable entry point where validated thermal protection documentation commands premium positioning absent entrenched supplier relationships. European beauty brand plastic elimination commitments create white-space demand for molded pulp gift set packaging where aesthetics justify higher unit costs than commodity food service alternatives. Direct supplier relationship cultivation with biologics distributors offers go-to-market traction through chain-of-custody documentation capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable foam manufacturing as thermoforming equipment reconfiguration demands retrofit investment incompatible with legacy polystyrene depreciation schedules. Long-term viability favors acquisition targets with molded fiber integration capabilities and established pharmaceutical validation documentation rather than pure-play petroleum-based converters. Watch for California DTSC listing finalization as inflection indicator that would accelerate substitution timelines and stranded asset risk in conventional polystyrene capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoforming Equipment Reconfiguration | Legacy polystyrene lines require capital-intensive retrofitting to process biodegradable alternatives with different melt flow characteristics. |
| Parallel Certification Investment | Duplicate FDA 21 CFR 177 and EU REACH documentation streams defend cross-border distribution continuity for multinational suppliers. |
| Molded Fiber Integration | Cellulosic fiber compression molding captures premium positioning among cosmetics brands executing plastic elimination commitments. |
| Direct Supplier Relationship Cultivation | Chain-of-custody documentation requirements displace distributor-mediated purchasing for large pharmaceutical and quick-service accounts. |
| Reverse Logistics Capability Buildout | Extended producer responsibility frameworks reshape material recovery economics for producers with collection infrastructure investment. |
Research Methodology
Operator-level perspectives from thermoforming plant managers, quick-service restaurant procurement directors, pharmaceutical cold chain logistics coordinators, and resin compounding technical directors anchored the qualitative base for this study. Primary interview findings combined with secondary validation from customs and trade data, SEC 10-K filings of listed packaging conglomerates, and ECHA REACH substance restriction notifications. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic drivers to establish volume and value parameters.
Scenario-bracketing around regulatory finalization timelines and feedstock price volatility bands bounded the projection horizon across the analysis window. Segmentation dimensions modeled include material chemistry tier, end-use thermal requirement specification, packaging format complexity, and regional regulatory cluster. CAGRs derived from historical growth pattern analysis adjusted for structural shift inflection points including municipal plastic prohibition adoption curves and pharmaceutical cold chain expansion trajectories. Styrene monomer price indices and electronics export manufacturing cluster utilization rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil price indices and currency exchange rate volatility would shift the trajectory of converter margin compression and cross-border trade flows. Forecasts reflect assumptions regarding regulatory implementation timelines and substitution elasticity parameters. Material shifts in California DTSC listing finalization or EU REACH styrene residual threshold tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Containerboard Market
Containers
Mini Spray Bottles Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Thermoformed Shallow Trays Market
Containers
Compartment Trays Market
Containers
Compartment Take-Out Container Market
Containers
Water Resistant Packing Cubes Market
Containers
Americas Container Technology Market
Containers
Two Compartment Bottles Market
Containers
Light Resistant Containers Market
Containers
EPS Shippers Market
Containers
Edible Oil Cans Market
Containers
2 Piece Cans Market
Containers
Carboy Market
Containers
Jerry Cans Market
Containers
Durable Insulated Containers Market