
 HDPE Blow Molding and Injection Molding Containers Market | 2026-2036
HDPE Blow Molding and Injection Molding Containers Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Blow Molding and Injection Molding Containers Market Outlook
ISO 15378 certification for pharmaceutical primary packaging materials is collapsing the supplier base to firms with validated clean-room operations and traceable resin chains. Greif leverages its integrated steel and plastic container network to sustain industrial bulk packaging dominance across North American manufacturing corridors. Berry Global Group anchors North American supply through multi-site blow molding capacity serving food and chemical end users. ALPLA Group differentiates via in-house preform and bottle production systems that extend its cost position in European retail packaging.
HDPE blow molding and injection molding containers are hollow or solid thermoplastic articles formed from high-density polyethylene resin with melt flow indices typically between 0.2 and 1.5 g/10 min, processed through extrusion blow, injection blow, or injection stretch techniques to achieve barrier properties, stack strength, and chemical resistance for liquid and solid containment. Bottles and jugs occupy the largest volume share in beverage and household product distribution, while pharmaceutical packaging commands premium positioning due to USP and EP compliance requirements. Trays compete in food service and retail display applications where thin-wall injection molding yields unit cost advantages over thermoformed alternatives.
FDA 21 CFR 177.1520 food-contact notifications and EU REACH Annex XVII substance restrictions shape resin formulation choices and recycling content claims across export-oriented production. The EU Packaging and Packaging Waste Regulation, implemented through national agencies such as Germany's ZSVR, mandates extended producer responsibility fees that alter total cost of ownership calculations for brand owners selecting container formats. Stakeholders must monitor evolving state-level recycled content mandates in California and Washington, as these precede federal rulemaking and create fragmented compliance obligations for multi-regional suppliers.
Market Dynamics
Extended producer responsibility frameworks are restructuring cost allocation between resin suppliers, converters, and brand owners across the HDPE container value chain. Germany's ZSVR fee schedules and California's SB 54 mandates force integrated compliance planning that favors scale operators with traceable recycling streams.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content floors for beverage bottles create guaranteed offtake for post-consumer HDPE flake, locking in demand for rHDPE-compliant blow molding capacity.
- Pharmaceutical serialization:USP Chapter <661> and EP 3.1.3 compliance requirements for HDPE primary packaging drive validated clean-room investments that filter out commodity converters.
- Gulf Coast petrochemical expansion:ExxonMobil and Chevron Phillips Chemical ethane cracker additions near Corpus Christi and Baytown secure virgin resin feedstock proximity for regional blow molders.
Market Restraints
- Ethylene feedstock volatility:Naphtha-to-ethane price spreads swing HDPE resin costs, compressing converter margins when crackers prioritize derivative exports over domestic supply.
- Mono-material substitution ceiling:Multi-layer barrier structures with EVOH or nylon interlayers complicate mechanical recycling streams, limiting closed-loop claims for sensitive food and pharmaceutical applications.
- REACH Annex XVII substance restrictions:ECHA scrutiny of additives including certain phthalates and heavy metal pigments forces reformulation cycles that delay new product qualifications.
Strategic Opportunities
- India FSSAI packaging rules:Mandatory food-grade certification for recycled plastics in contact applications opens technical partnership opportunities for converters with EFSA-validated recycling processes.
- Digital watermark integration:AIM Digimarc and HolyGrail 2.0 marker technologies enable automated sortation of HDPE containers at materials recovery facilities, unlocking premium rHDPE pricing.
- Aseptic blow-fill-seal:Pharmaceutical and nutraceutical brands adopt BFS HDPE vials for biologics stability, displacing glass in parenteral applications where break resistance matters.
Industry Challenges
- ISO 15378 audit timelines:Pharmaceutical packaging converters face 12-18 month validation cycles for clean-room installations, freezing capacity decisions until customer commitments firm.
- Legacy injection mold retrofits:Thin-wall food tray producers must rebuild tool stacks for faster cycle times, straining capex budgets against thermoformed PP competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Blow Molding and Injection Molding Containers Market |
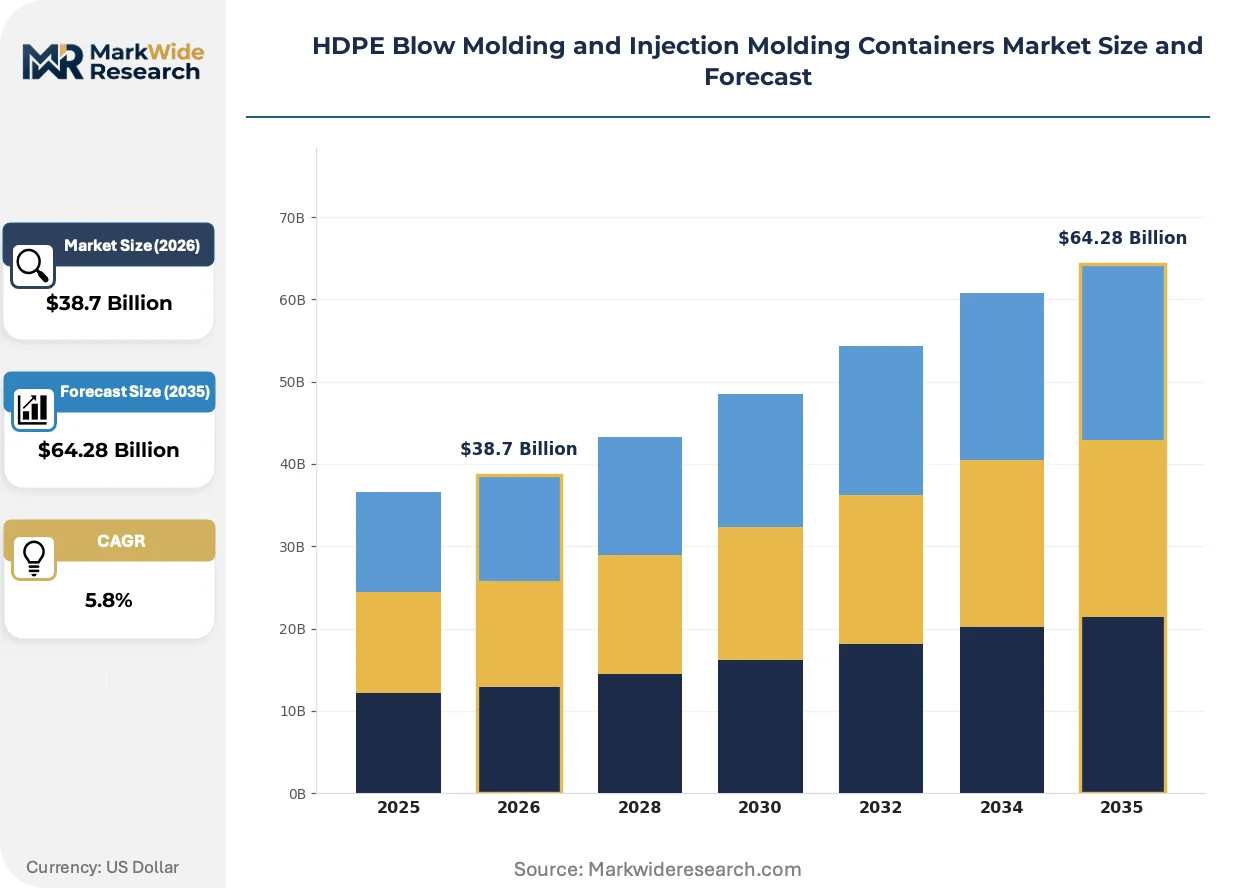
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jugs, Buckets, Trays Application: Food Packaging, Chemical Containers, Pharmaceutical Packaging, Household Products End User: Food & Beverage, Personal Care, Healthcare, Automotive Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Greif, LyondellBasell Industries Holdings B.V., Berry Global Group, WERIT Kunststoffwerke, Greiner Packaging, Plastipak Packaging, Mauser Group, Amcor PLC, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Blow Molding and Injection Molding Containers Market Strategic Shifts
Active and intelligent packaging integration is redefining HDPE container functionality beyond passive containment, embedding sensors and traceability directly into blow molded structures. Material science advances and regulatory precision are converging to enable next-generation performance specifications.
All-PE barrier films with metallized or SiOx coatings are supplanting multi-layer structures with aluminum foil in retortable food pouches and pharmaceutical sachets. Nestlé and Unilever procurement teams specify these mono-material alternatives to satisfy 2025 recyclability pledges. The shift collapses converter qualification timelines by eliminating adhesive lamination steps and enabling single-stream recycling claims.
EU Packaging and Packaging Waste Regulation implementation through 2025 national transpositions mandates deposit-return schemes for HDPE beverage containers above 200ml capacity. France's Citeo and Germany's DSD systems expand reverse logistics infrastructure, forcing brand owners to redesign bottle geometries for automated sortation compatibility. Small-format personal care bottles below 100ml face exclusion from mainstream recycling streams, driving concentration in larger family-size SKUs.
Retail pharmacy chains consolidate generic drug procurement through central fill facilities, compressing primary packaging specification diversity. CVS Health and Walgreens distribution centers demand HDPE vial standardization across multiple API suppliers to maximize automated dispensing line throughput. The concentration pushes contract manufacturers toward single-source HDPE resin qualifications with validated extractables profiles, privileging converters with dedicated pharmaceutical compound libraries.
HDPE Blow Molding and Injection Molding Containers Market Segmentation
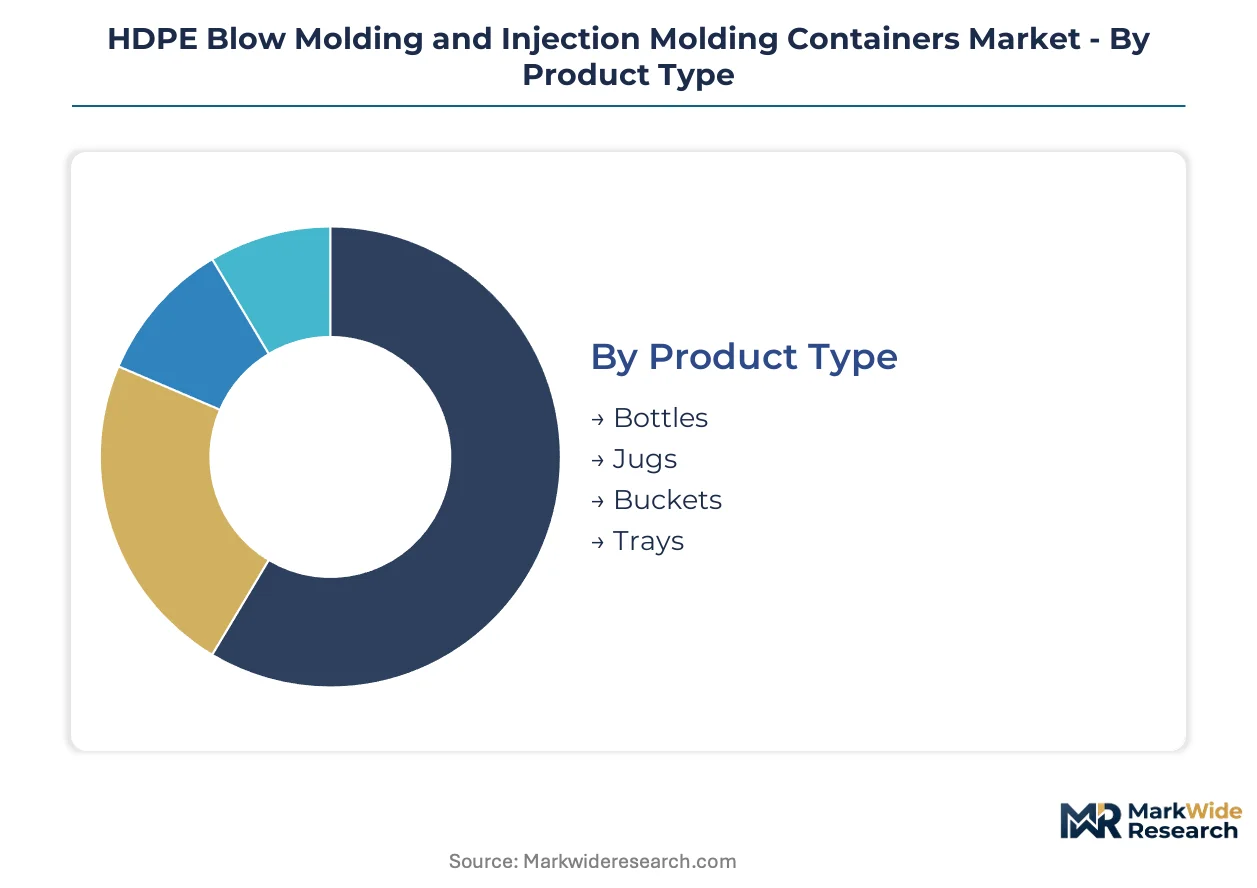
Container specification diversity across HDPE blow molding and injection molding reflects divergent compliance burdens. FDA 21 CFR 177.1520 food-contact notifications and EU REACH Annex XVII substance restrictions force resin formulation choices that segment the supplier base by validated compound libraries.
Product Type:
FDA 21 CFR 177.1520 and EU 10/2011 food-contact regulations impose distinct migration testing protocols on each container geometry, filtering converters by analytical capabilities.
- Bottles:Extrusion blow-molded HDPE structures with 0.3-1.0mm wall thickness and 24-38mm neck finishes dominate beverage and pharmaceutical liquid containment. CVS Health and Walgreens central fill facilities standardize 30-60ml HDPE vial specifications across generic API suppliers to maximize automated dispensing throughput.
- Jugs:High-capacity blow-molded containers with integrated handles and 38-63mm wide-mouth openings serve institutional chemical and food service distribution. Gulf Coast petrochemical corridor converters leverage proximity to ExxonMobil Baytown and Chevron Phillips Chemical Sweeny crackers for virgin resin cost positioning in industrial chemical containment.
- Buckets:Injection-molded or extrusion blow-molded pails with tamper-evident lids and metal or plastic handles target paint, coatings, and food ingredient bulk packaging.
- Trays:Thin-wall injection-molded structures with 0.5-1.5mm walls compete against thermoformed PP in food service display applications.
Bottles handle the majority of throughput; trays are gaining share fastest on thin-wall cycle time improvements.
Application:
Margin structures diverge sharply based on validation depth, with pharmaceutical and food applications commanding premium pricing over commodity chemical containment.
- Food Packaging:Multi-layer blow-molded HDPE with EVOH or nylon barrier layers extends shelf life for sauces, dressings, and dairy. California SB 54 recycled content mandates and EU Single-Use Plastics Directive floors force brand owners to secure rHDPE-qualified converters with traceable post-consumer flake chains.
- Chemical Containers:UN-certified HDPE drums and jugs for hazardous material transport require drop testing and stack load validation under DOT 49 CFR regulations. Industrial packaging corridors in Germany's Rhine-Ruhr region concentrate demand from BASF and Covestro chemical manufacturing clusters.
- Pharmaceutical Packaging:USP Chapter <661> and EP 3.1.3 compliance for HDPE primary packaging demands extractables testing and validated clean-room operations. ISO 15378 certification collapses the supplier base to firms with dedicated pharmaceutical compound libraries.
- Household Products:Standard blow-molded bottles for detergents and cleaners face intense price competition from PET and PP substitutes.
Food packaging handles the majority of throughput; pharmaceutical packaging is climbing the fastest on serialization and biologics stability requirements.
End User:
Procurement centralization across retail pharmacy and food retail chains concentrates volume with converters offering multi-site qualification and standardized resin libraries.
- Food & Beverage:Nestlé and Unilever procurement teams specify mono-material all-PE barrier structures to satisfy 2025 recyclability pledges, collapsing converter qualification timelines.
- Personal Care:Small-format bottles below 100ml face EU Packaging and Packaging Waste Regulation exclusion from mainstream recycling streams, driving SKU consolidation toward family-size containers.
- Healthcare:Hospital and clinic distribution networks demand aseptic blow-fill-seal HDPE vials for parenteral biologics where glass break resistance matters.
- Automotive:Chemical-resistant HDPE containers for lubricants, antifreeze, and AdBlue DEF storage compete with metal and hybrid packaging on unit cost.
Food and beverage handles the majority of throughput; healthcare is expanding most quickly on biologics packaging conversion.
Distribution Channel:
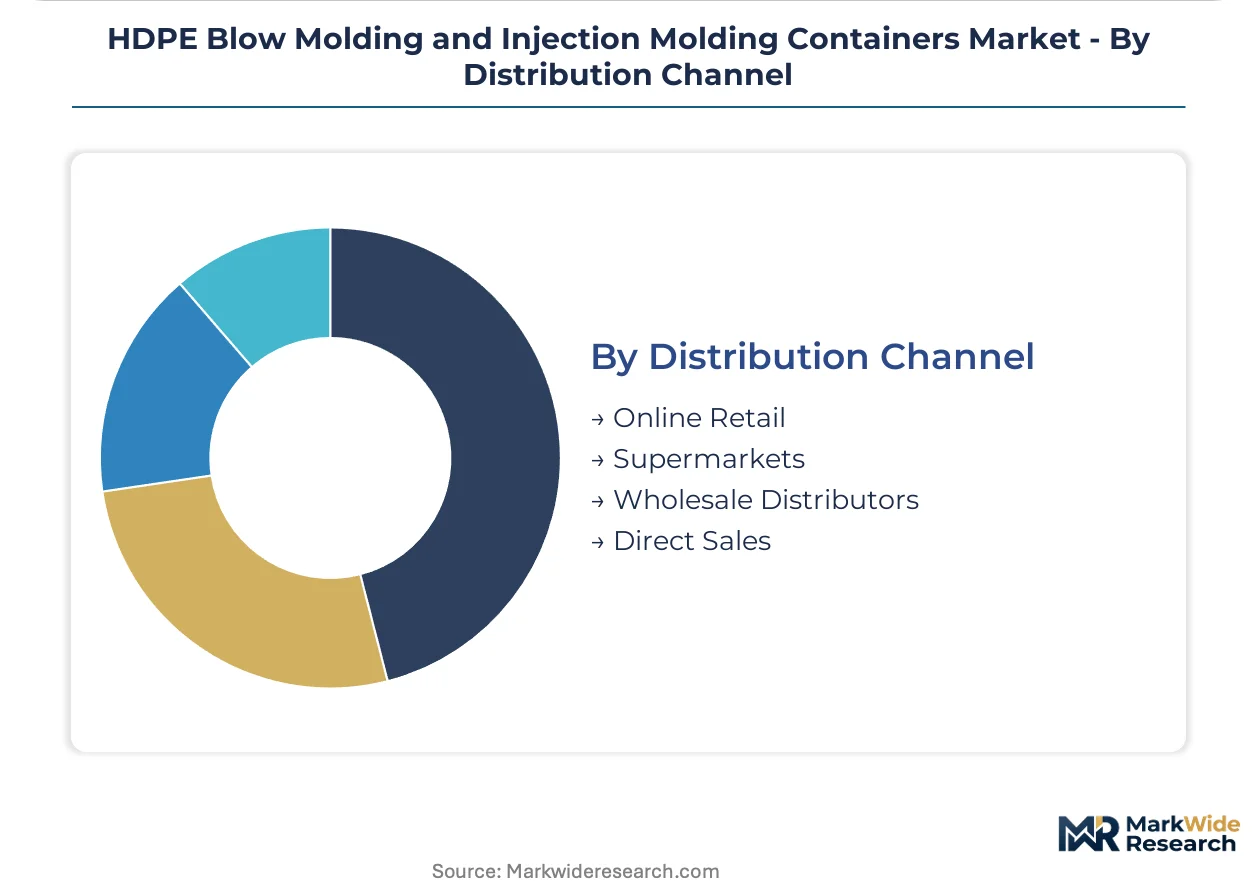
Channel selection determines lot size flexibility and customization depth, with direct sales capturing complex pharmaceutical specifications and wholesale distributors handling commodity chemical volume.
- Online Retail:E-commerce fulfillment demands optimized cube utilization and damage-resistant HDPE designs for parcel shipping.
- Supermarkets:Retail display requirements drive thin-wall injection-molded tray and container specifications for food service and produce.
- Wholesale Distributors:Industrial chemical and food ingredient bulk packaging moves through regional distribution networks serving manufacturing clusters.
- Direct Sales:Pharmaceutical and specialized chemical brand owners contract directly with ISO 15378-validated converters for dedicated capacity and resin qualification.
Wholesale distributors handle the majority of throughput; direct sales is climbing the fastest on pharmaceutical serialization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial packaging buyers cluster near major petrochemical and manufacturing corridors, with procurement patterns tracking ethane cracker proximity and regulatory enforcement intensity across four demand centers.
United States
Gulf Coast petrochemical expansion near Corpus Christi and Baytown secures virgin HDPE feedstock for regional blow molders serving chemical and food packaging demand. FDA 21 CFR 177.1520 compliance requirements filter converters by food-contact notification capabilities. California's SB 54 recycled content mandates are forcing brand owners to secure rHDPE-qualified supply chains ahead of federal rulemaking.
Germany
Rhine-Ruhr industrial packaging corridor concentrates demand from BASF and Covestro chemical manufacturing clusters requiring UN-certified HDPE containment. Germany's ZSVR fee schedules under extended producer responsibility frameworks alter total cost of ownership calculations for brand owners. The country's national packaging regulator enforces strict traceability requirements for post-consumer recycled content claims.
China
Yangtze River Delta manufacturing clusters drive HDPE container demand for automotive lubricants and industrial chemicals, with local converters competing on thin-wall injection molding cycle times. The country's national standards body implements GB standards for food-contact plastics that increasingly reference EFSA safety assessments. Guangdong Province petrochemical complexes near Zhanjiang supply regional blow molding capacity for export-oriented consumer goods packaging.
India
Maharashtra and Gujarat industrial corridors generate HDPE container demand from pharmaceutical contract manufacturing organizations expanding serialization capabilities. FSSAI packaging rules mandating food-grade certification for recycled plastics create technical partnership opportunities for converters with validated recycling processes. The country's central drug regulator enforces USP Chapter <661> alignment for primary packaging materials used in generic drug exports.
Brazil
São Paulo state manufacturing clusters consume HDPE containers for agrochemical and food ingredient distribution, with converters facing price pressure from thermoformed PP alternatives. ANVISA pharmaceutical packaging regulations drive clean-room investments among suppliers serving the country's generics export sector. The national environmental regulator implements extended producer responsibility frameworks modeled on EU Packaging and Packaging Waste Regulation principles.
HDPE Blow Molding and Injection Molding Containers Market Competitive Environment
Player mix skews toward integrated multinational resin-to-container operators and specialized pharmaceutical packaging converters with validated clean-room capabilities. Tiered competitive positioning separates scale-driven industrial bulk suppliers from premium-tier pharmaceutical specialists. Two strategic archetypes dominate: integrated petrochemical-container networks leveraging feedstock proximity, and certification-heavy pharmaceutical compound libraries. Capacity expansion and M&A consolidation represent the dominant competitive moves, with converters acquiring regional players to secure multi-site qualification capabilities.
Among integrated packaging networks, Greif and Berry Global Group exemplify scale-driven archetypes with multi-site blow molding capacity spanning industrial and food end uses. ALPLA Group occupies a position within the in-house production specialist tier, representing converters with captive preform and bottle manufacturing systems. These three companies anchor the competitive structure, with their geographic footprints and certification depth setting qualification benchmarks that filter out commodity competitors in regulated applications.
| Leading Market Players |
|---|
| Greif |
| LyondellBasell Industries Holdings B.V. |
| Berry Global Group |
| WERIT Kunststoffwerke |
| Greiner Packaging |
| Plastipak Packaging |
| Mauser Group |
| Amcor PLC |
| ALPLA Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85 percent at Gulf Coast ethane crackers compress resin spreads and anchor price floors for regional blow molders serving institutional chemical buyers. This scale concentration simultaneously elevates bargaining power for integrated petrochemical-container networks while squeezing standalone converters dependent on spot resin purchases.
Pricing Analysis
Cost-plus contracts indexed to ICIS-LOR ethylene assessments dominate virgin HDPE resin procurement, with converters layering conversion fees that stratify across ISO 15378 certification tiers. Three-tier pricing structure across premium pharmaceutical, standard food-grade, and economy industrial levels reflects validation depth and clean-room capital intensity. Cost compression in standard food-grade tiers is intensifying because California SB 54 mandates force brand owners to absorb rHDPE qualification premiums. Industrial chemical buyers exhibit highest price sensitivity due to substitutability with steel drums and IBC totes.
Supply Chain Analysis
Container freight rates from Rotterdam to Houston and backhaul availability from Asia-Pacific petrochemical hubs dictate inbound logistics costs for European converters sourcing specialty additives. HDPE container manufacturing concentrates in the United States, Germany, and China, with regional supply clusters tethered to ethane cracker proximity and downstream chemical manufacturing corridors. Raw material dependencies center on ethylene feedstock, color masterbatches, and barrier additive packages. Single-source vulnerability to ethane price volatility at Corpus Christi and Baytown crackers represents the dominant structural risk. Distribution runs through wholesale distributors for commodity chemical volume and direct sales channels for pharmaceutical serialization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU Single-Use Plastics Directive implementation, California SB 54 mandates, and India's FSSAI packaging rules creates white-space opportunities for converters with multi-jurisdiction compliance capabilities. This demand-side shift toward traceable recycling chains fragments volume away from undifferentiated commodity suppliers.
For Market Incumbents: Consolidate regional blow molding assets to secure multi-site qualification capabilities demanded by Nestlé and Unilever procurement teams. Acquire ISO 15378-validated pharmaceutical packaging specialists before FDA serialization deadlines filter out commodity competitors. Backward integration into post-consumer HDPE flake processing secures rHDPE supply chains against California and Washington state recycled content mandates.
For New Entrants and Emerging Players: Anchor in India's pharmaceutical contract manufacturing corridor where USP Chapter <661> alignment requirements outpace local clean-room capacity. Target Maharashtra and Gujarat industrial clusters with technical partnerships for EFSA-validated recycling processes under FSSAI rules. Pursue toll manufacturing arrangements with established resin suppliers to bypass virgin HDPE feedstock capital barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with validated pharmaceutical compound libraries over commodity industrial packaging assets. The five-to-ten year viability window privileges firms with traceable post-consumer flake chains and digital watermark integration capabilities. Acquisition focus should center on regional blow molders with ISO 15378 certification and multi-site geographic footprints. The inflection signal to monitor is EU Packaging and Packaging Waste Regulation national transposition timelines accelerating EPR fee schedule implementation.
| Strategic Initiative | Industry Significance |
|---|---|
| rHDPE Qualification Investment | California SB 54 mandates lock in premium pricing for traceable recycled content supply chains. |
| ISO 15378 Certification Acquisition | CVS Health and Walgreens central fill standardization collapses supplier base to validated clean-room operators. |
| Digital Watermark Integration | HolyGrail 2.0 marker adoption enables automated sortation premium capture at materials recovery facilities. |
| Gulf Coast Capacity Expansion | ExxonMobil Baytown ethane cracker proximity secures virgin resin cost positioning for industrial chemical containment. |
| Aseptic Blow-Fill-Seal Adoption | Biologics stability requirements displace glass vials in parenteral applications where break resistance matters. |
Study Parameters
Desk research of customs trade data, SEC 10-K filings from packaging converters, and EU regulatory implementation notices preceded structured interviews with blow molding plant managers, pharmaceutical procurement leads, and brand owner sustainability directors. Primary fieldwork across the United States, Germany, China, and India validated secondary estimates of capacity utilization and rHDPE qualification timelines. Bottom-up volume triangulation from converter site assessments was cross-checked against top-down resin consumption data from petrochemical disclosures.
Variance decomposition across product type, application grade, end-use industry, and regional regulatory cluster shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate blending weighted by baseline volume shares. Industry-specific forecast inputs included ethane cracker expansion timelines, EU Packaging and Packaging Waste Regulation national transposition schedules, and pharmaceutical serialization compliance deadlines.
Material uncertainties — ethylene feedstock price volatility, recycled content mandate enforcement intensity, and barrier technology substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and resin technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Corrugated Open-Head Drums Market
Containers
Sanitary Cans Market
Containers
USA and Canada Packer Bottle Market
Containers
Snap Secure Containers Market
Containers
Stock Clamshell Packaging Market
Containers
Packer Bottle Market
Containers
Flexible Water Tanks Market
Containers
Pinch Grip Jars Market
Containers
Slotted Containers Market
Containers
Sample Containers Market
Containers
Stainless Steel Cask Market
Containers
Slide Top Tins Market
Containers
EPS Shippers Market
Containers
Hinged Lid Tins Market
Containers
Container Mouth Inner Seal Market
Containers
Global Multi Pack Carriers Market