
 Aluminum Cans Market | 2026-2036
Aluminum Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Cans Market Intelligence
The ISO 14001 certification cycle for environmental management is redrawing the supplier landscape for aluminum cans. Ball Corporation leverages its global manufacturing footprint to meet sustainability targets set by multinational beverage clients. Crown Holdings differentiates through specialized can shaping and printing technologies for premium brands. Ardagh Group sustains its market position through long-term supply contracts with major food and beverage conglomerates in both North America and Europe.
Aluminum cans are rigid containers primarily manufactured from specific aluminum alloys, often from the 3xxx or 5xxx series. Their primary function is to provide a lightweight, impermeable, and highly recyclable packaging solution for a variety of products, protecting contents from light and oxygen. Beverage Cans constitute the largest product type, driven by high-volume consumption in the beer and soft drinks application segments. Within the end user industry, Food & Beverage Manufacturers command the majority of volume, while aerosol cans for personal care represent a high-margin niche.
Regulations from the U.S. Environmental Protection Agency (EPA) and adherence to the European Union's REACH directives govern material composition and recycling mandates. In China, national GB standards for food contact materials and the Ministry of Ecology and Environment's (MEE) circular economy policies influence production and waste management. Future profitability for manufacturers will hinge on securing access to recycled aluminum feedstock and investing in energy-efficient production technologies.
Market Dynamics
The central dynamic governing the aluminum cans market is the structural tension between rising sustainability mandates, such as the European Union's Green Deal, and the operational challenge of securing sufficient, high-quality recycled aluminum feedstock to meet circularity targets.
Growth Catalysts
- EU Green Deal:Mandates for material circularity and higher recycling rates create a regulatory pull for aluminum cans over less recyclable alternatives in Europe.
- Craft Beverage Sector:Growth in craft beer and hard seltzers drives demand, as these segments prefer cans for branding and product protection.
- Southeast Asian Production:New beverage production facilities in countries like Vietnam are increasing regional consumption of aluminum cans for domestic and export markets.
Market Restraints
- Input Cost Volatility:Manufacturer margins are exposed to price fluctuations of primary aluminum on the London Metal Exchange (LME), creating cost uncertainty.
- Substitution from PET:In segments like still water, polyethylene terephthalate (PET) bottles remain a threat due to lower initial production costs.
- Energy Intensity:Primary aluminum production via smelting is extremely energy-intensive, posing a significant cost and carbon footprint challenge for manufacturers.
Strategic Opportunities
- New Product Categories:Growth potential exists in packaging for wine, functional waters, and RTD coffee, categories traditionally dominated by glass or plastic.
- Deposit Return Schemes (DRS):New DRS policies provide a financial incentive for consumers to return cans, increasing the supply of high-quality recycled material.
- Alloy Innovation:New, lighter aluminum alloys allow for can-wall thinning, reducing material usage per can and lowering production costs.
Industry Challenges
- Recycled Feedstock Scarcity:A primary hurdle is securing a consistent stream of post-consumer scrap, as contamination compromises the quality of recycled aluminum sheet.
- Capital Investment Cycles:Upgrading or building new can manufacturing lines requires substantial, long-term capital expenditure with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Cans Market |
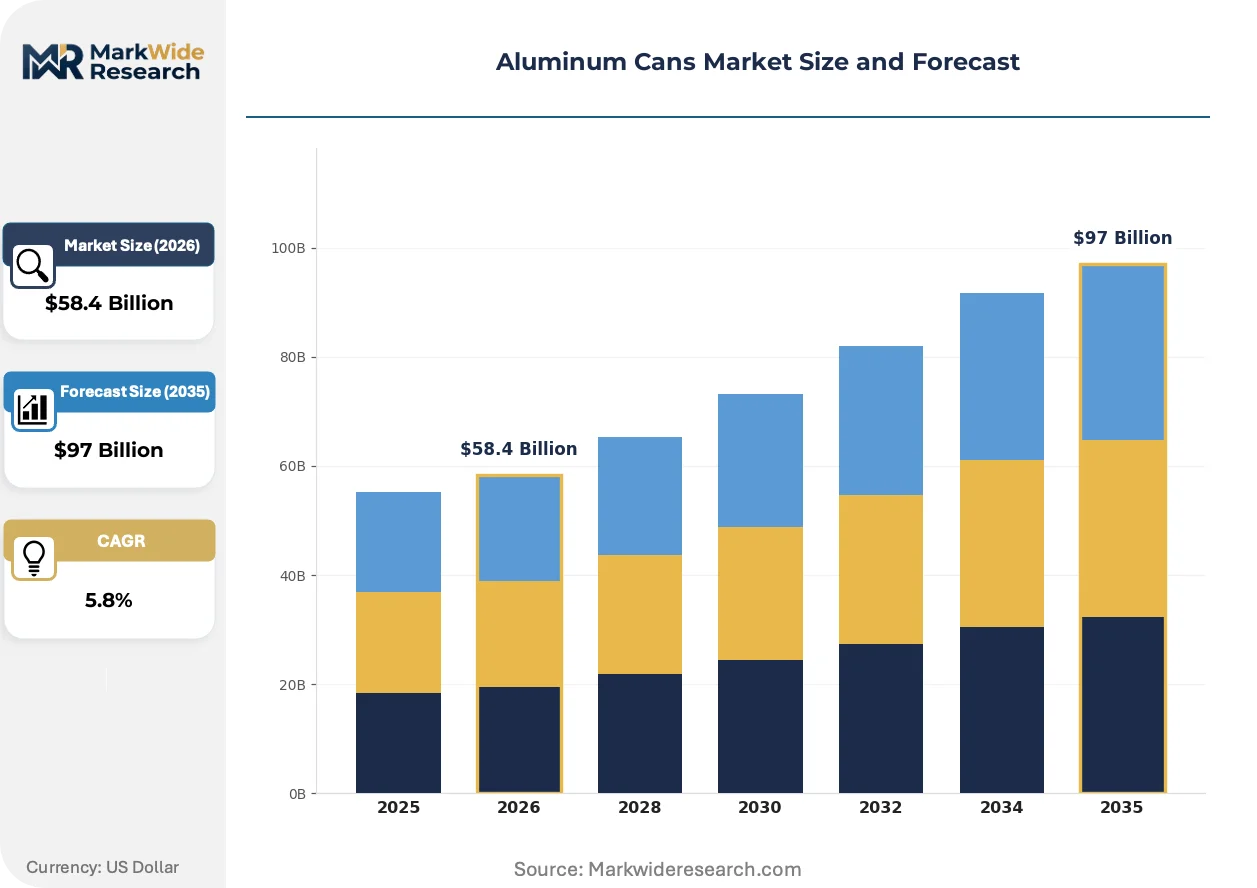
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverage Cans, Food Cans, Personal Care Cans, Aerosol Cans Application: Soft Drinks, Beer, Energy Drinks, Food Packaging, Cosmetics End User Industry: Food & Beverage Manufacturers, Cosmetic Producers, Pharmaceutical Firms, Chemical Suppliers Sales Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Exporters |
| Companies Covered | Ball Corporation, Crown Holdings, Ardagh Group, Silgan Holdings, CAN-PACK, Toyo Seikan Group Holdings, CPMC Holdings, Kian Joo Can Factory Berhad, Nampak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Cans Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of material science advancements, stringent circular economy regulations, and a definitive consumer shift towards sustainable packaging. These forces are collectively reshaping product design, manufacturing processes, and brand-level procurement strategies.
Advanced digital printing on cans allows for high-resolution graphics without the need for plates or labels. Craft beverage producers and marketers of special-edition products are rapidly adopting this for short-run, customized packaging. This direct-to-can printing technology is supplanting traditional offset lithography for applications demanding speed and design flexibility, enabling hyper-segmentation.
Extended Producer Responsibility (EPR) schemes are gaining legislative traction globally, altering the cost structure of packaging. These policies make producers financially responsible for the post-consumer lifecycle of their products, including can collection and recycling. The beverage industry in Europe is most affected, responding with increased investment in collection systems and design-for-recycling initiatives.
Consumer preference is visibly shifting towards packaging formats perceived as more sustainable, directly benefiting aluminum. This behavioral change is disrupting the market for single-use plastic bottles, particularly in the bottled water and soft drink categories. The trend is most prominent among younger consumer demographics in North America and Western Europe, where recyclability is a key factor in purchasing decisions.
Aluminum Cans Market Segmentation
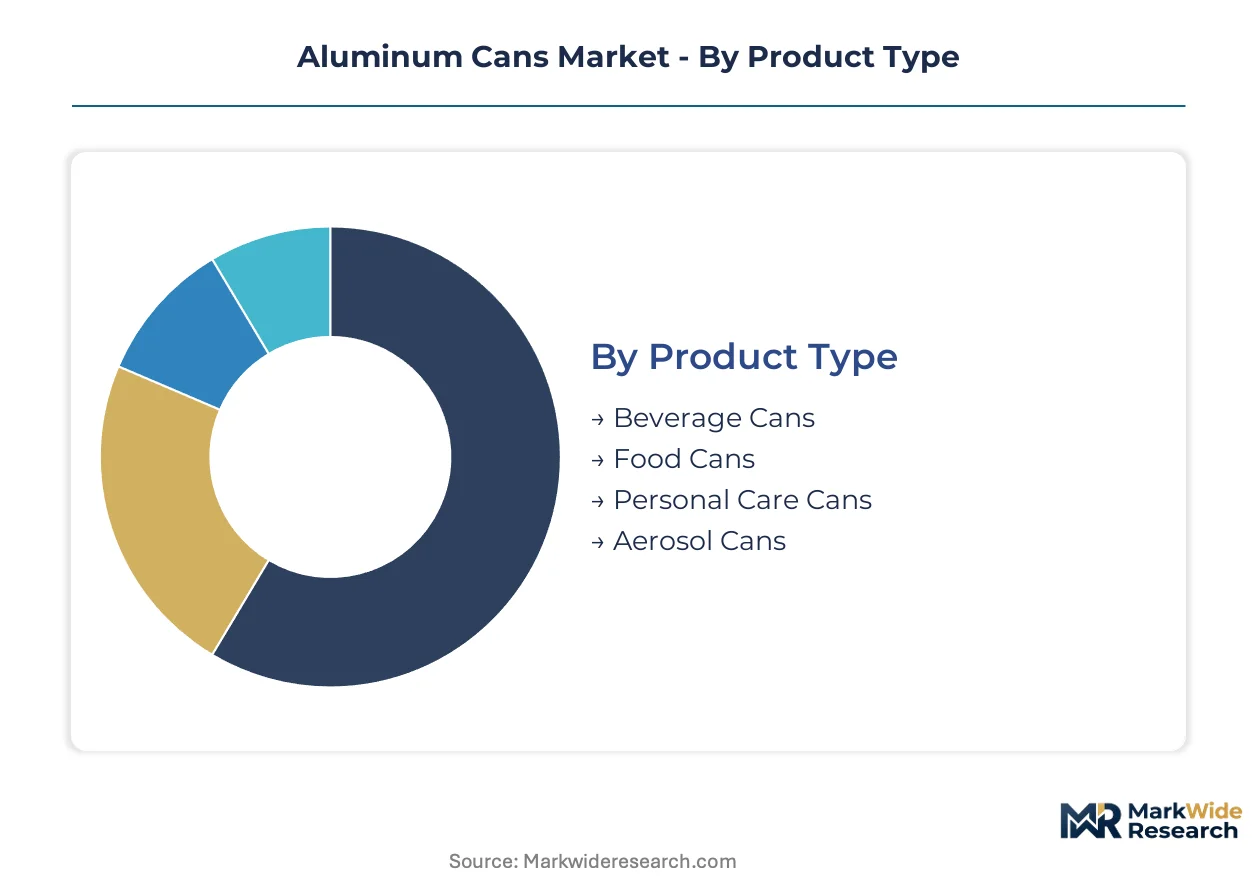
The aluminum cans market segmentation reveals distinct value propositions and operational complexities across product types and end-use applications. Manufacturers strategically align production capabilities to address specific demand patterns within each segment. This granular view informs investment decisions and market penetration strategies for key industry players.
Product Type:
Margin pools within the product type category are significantly influenced by specialization and volume requirements.
- Beverage Cans:These containers are typically made from 3xxx or 5xxx series aluminum alloys, designed for high-speed filling lines. Demand concentrates in the soft drinks and beer sectors, driven by consumer preference for recyclability and brand differentiation in North America and Western Europe.
- Aerosol Cans:These specialized containers use high-pressure aluminum alloys to safely dispense products under pressure. They represent a high-margin niche within personal care and pharmaceutical applications, valued for their precise delivery and product protection.
- Food Cans:Aluminum food cans offer an impermeable barrier for various food products, valued for their light weight and recyclability in the prepared foods sector.
- Personal Care Cans:These cans serve the beauty and personal hygiene markets, providing protective packaging for products like deodorants and hairsprays.
Beverage Cans holds installed capacity. Aerosol Cans is rotating up the share rankings.
Application:
Volume dynamics are a primary differentiator across various application segments for aluminum cans.
- Soft Drinks:This application segment utilizes aluminum cans for carbonated soft drinks and functional beverages, benefiting from the material's ability to preserve carbonation and prevent light degradation. High-volume consumption in North America and Asia drives consistent demand.
- Beer:Aluminum cans for beer offer excellent oxygen barrier properties and protection from UV light, crucial for maintaining product quality and extending shelf life. The craft beverage sector in Europe and the US particularly favors cans for branding and portability.
- Energy Drinks:Energy drink manufacturers increasingly adopt aluminum cans for their branding potential and ability to withstand internal pressure from carbonation.
- Food Packaging:Aluminum cans provide a lightweight and protective solution for various food items, including soups, vegetables, and pet food, ensuring extended shelf life.
- Cosmetics:The cosmetics industry uses aluminum cans for aerosol products like hairsprays and body mists, appreciating their aesthetic appeal and product integrity.
Soft Drinks applications currently dominate volume. Energy Drinks demonstrate the steepest expansion trajectory.
End User Industry:
Customer type dictates the specific packaging requirements and supply chain logistics within the end user industry.
- Food & Beverage Manufacturers:These manufacturers represent the largest end-user segment, requiring vast quantities of aluminum cans for high-speed filling operations across diverse product lines. Their demand is consolidating in Southeast Asian countries like Vietnam, driven by new production facilities.
- Cosmetic Producers:Cosmetic producers leverage aluminum cans for personal care aerosols and specialty packaging, valuing the material's premium aesthetic and protective qualities. This segment often demands specialized printing and shaping technologies for brand differentiation.
- Pharmaceutical Firms:Pharmaceutical firms use aluminum cans for specific medical aerosols and sterile packaging, prioritizing material purity and barrier properties.
- Chemical Suppliers:Chemical suppliers utilize aluminum cans for industrial aerosols and small-volume specialty chemicals, benefiting from the cans' durability and containment capabilities.
Food & Beverage Manufacturers drive the majority of demand. Cosmetic Producers are gaining share fastest.
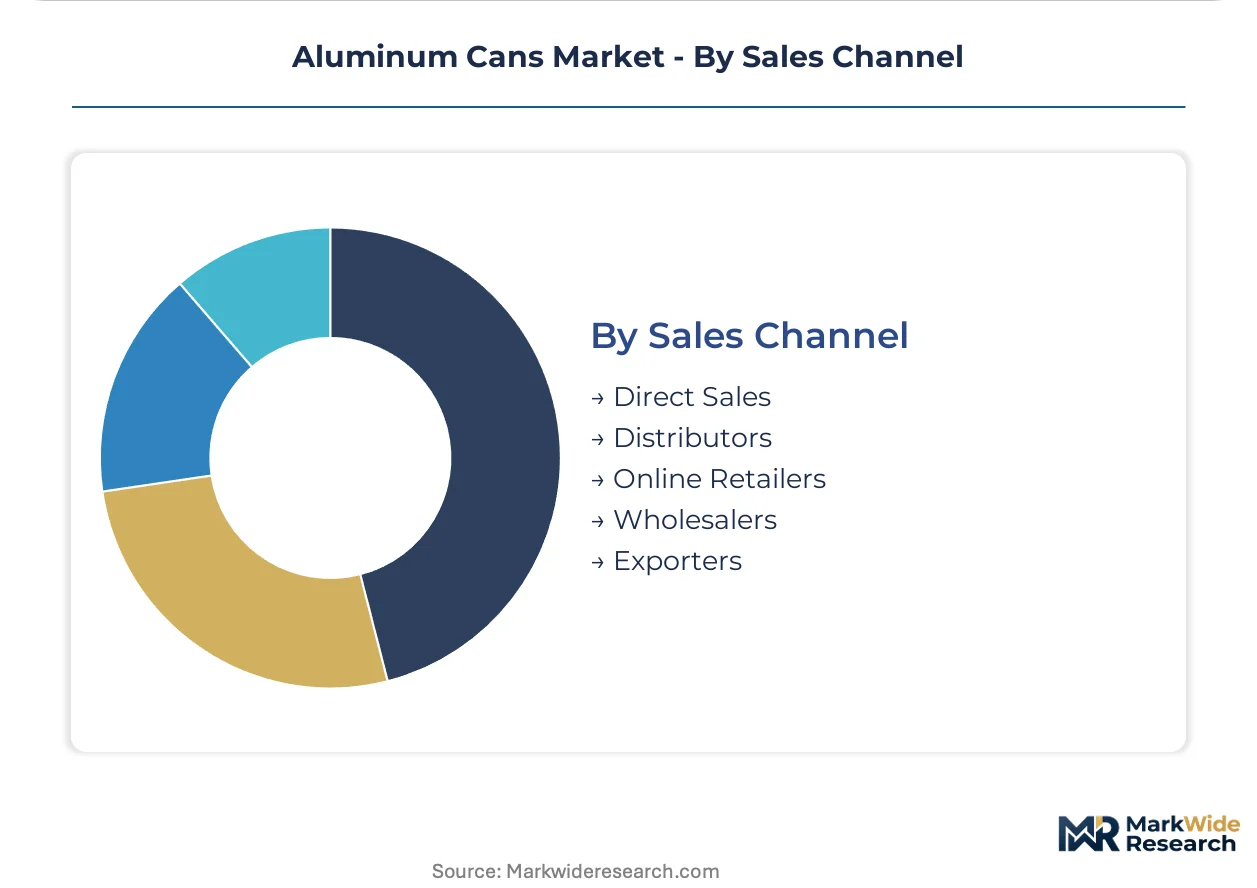
Sales Channel:
Supply concentration varies significantly across the sales channel landscape, influencing distribution efficiencies and direct customer relationships.
- Direct Sales:This channel involves direct transactions between can manufacturers and large-volume end-users, primarily multinational beverage corporations. It enables customized supply agreements and close collaboration on design and sustainability initiatives.
- Distributors:Distributors serve as intermediaries, providing aluminum cans to smaller and medium-sized enterprises that lack direct purchasing power from large manufacturers. This channel offers flexibility and localized inventory management, particularly in fragmented markets.
- Online Retailers:Online retailers are an emerging channel for specialized or smaller-batch aluminum can purchases, catering to craft producers and niche markets.
- Wholesalers:Wholesalers manage bulk procurement and distribution of aluminum cans, often serving regional markets and various end-user industries.
- Exporters:Exporters facilitate the international movement of aluminum cans, addressing demand in regions with limited local manufacturing capacity or specific import requirements.
Direct Sales remain the dominant channel for high-volume transactions. Online Retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Green Deal, emphasizing material circularity, significantly influences regional demand for aluminum cans. This regulatory push, combined with consumer preference for sustainable packaging, shapes manufacturing and procurement decisions across key markets. New beverage production facilities in emerging economies also drive localized consumption.
United States
Demand for aluminum cans in the United States is driven by the craft beverage sector, including beer and hard seltzers, and a shift towards sustainable packaging for functional waters. U.S. Environmental Protection Agency (EPA) regulations govern material composition and recycling mandates. Major beverage producers in the Midwest and California actively invest in can manufacturing and recycling infrastructure.
Germany
Germany's aluminum can market benefits from strong consumer demand for beer and soft drinks, coupled with stringent environmental policies. The EU Green Deal and REACH directives accelerate the adoption of highly recyclable packaging formats. Packaging innovation and high-speed filling lines are concentrated around industrial centers like Bavaria and North Rhine-Westphalia.
China
China's market for aluminum cans expands due to high-volume consumption in the soft drinks and energy drinks segments. National GB standards for food contact materials and the Ministry of Ecology and Environment's (MEE) circular economy policies influence production. Significant manufacturing and beverage filling facilities operate across the Yangtze River Delta and Guangdong province.
Vietnam
New beverage production facilities in Vietnam are increasing regional consumption of aluminum cans for both domestic and export markets. Government incentives for foreign investment in manufacturing support this growth. Industrial parks near Ho Chi Minh City and Hanoi are becoming key hubs for can production and beverage packaging operations.
Brazil
Brazil's aluminum can market experiences consistent demand from high-volume soft drink and beer consumption, alongside a growing focus on packaging sustainability. National recycling programs and environmental standards set by IBAMA encourage material circularity. Beverage production and can manufacturing are prominent in the industrial belt of São Paulo and Minas Gerais.
Aluminum Cans Market Key Industry Players
Player mix skews toward established global manufacturers with extensive production capabilities and specialized product offerings. The market structure exhibits consolidation among top-tier players, while smaller, regional suppliers cater to niche demands. Strategic archetypes include global scale operators, technology innovators, and regional specialists. Dominant competitive moves involve significant capital expenditure in new production lines and strategic investments in recycled feedstock procurement.
Global scale operators like Ball Corporation and Ardagh Group exemplify broad geographic reach and high-volume production capabilities, serving multinational beverage clients. Crown Holdings represents a technology innovator archetype, differentiating through specialized can shaping and advanced printing technologies for premium brands. These firms collectively anchor the market through long-term supply contracts and continuous investment in sustainable manufacturing processes.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Silgan Holdings |
| CAN-PACK |
| Toyo Seikan Group Holdings |
| CPMC Holdings |
| Kian Joo Can Factory Berhad |
| Nampak |
| Others |
Cost & Logistics Intelligence
The ISO 14001 certification cycle gates both supplier qualification and price differentiation across the aluminum cans market. This environmental management standard influences procurement decisions for multinational beverage clients seeking sustainable packaging solutions.
Pricing Analysis
Certification level, particularly ISO 14001 adherence, creates the primary spread in aluminum can pricing. Long-term supply contracts, often hybridizing commodity spot rates with fixed premiums, dominate transactions for large volume buyers. Quality grade and volume scale further differentiate pricing. Pricing pressure stems from the volatility of primary aluminum on the London Metal Exchange. Smaller craft beverage producers exhibit higher price sensitivity than multinational food and beverage manufacturers.
Supply Chain Analysis
Inbound logistics costs, particularly related to container availability and specific trade lanes from Asia, impact aluminum can supply chains. Geographic concentration of manufacturing centers on China, Vietnam, and key European industrial hubs like Germany. The supply chain draws heavily from primary aluminum and, increasingly, recycled aluminum feedstock. Recycled feedstock scarcity and contamination represent a structural risk. Distribution runs through direct sales to large end-users and via distributors for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum cans market presents a defensive moat story, underpinned by significant capital investment cycles that create high barriers to entry. This structural advantage ensures long-term stability for established players.
For Market Incumbents:Compound existing advantages by securing long-term recycled aluminum feedstock contracts to mitigate input cost volatility. Invest in energy-efficient production technologies to address the high energy intensity of primary aluminum manufacturing. This defends against margin erosion from LME price fluctuations and strengthens sustainability credentials. Expand manufacturing capacity in Southeast Asian markets to serve growing regional beverage production.
For New Entrants and Emerging Players:Anchor in niche segments by leveraging advanced digital printing for customized, short-run packaging for craft beverage producers. Target online retail channels to reach smaller enterprises seeking specialized can purchases. The most penetrable segment is new product categories like functional waters and RTD coffee. Offer design flexibility and faster time-to-market as a key go-to-market angle.
For Investors and Strategic Acquirers:The EU Green Deal and global EPR schemes reshape the acquisition landscape, favoring companies with robust circular economy infrastructure. Long-term viability for aluminum cans is strong, spanning beyond a decade due to material circularity mandates. Target regional specialists with strong local feedstock procurement networks or technology innovators in alloy development. A signal to watch is the implementation rate of Deposit Return Schemes, which directly impacts recycled material availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Recycled Feedstock Contracts | Mitigates commodity price volatility and ensures supply for circularity mandates. |
| Invest in Energy-Efficient Production | Reduces operational costs and lowers the carbon footprint of manufacturing processes. |
| Expand Southeast Asian Capacity | Captures new demand from expanding beverage production facilities in Vietnam. |
| Develop Advanced Digital Printing | Enables product differentiation and customization for premium and craft brands. |
| Acquire Regional Collection Networks | Strengthens control over post-consumer scrap for consistent recycled material supply. |
Research Approach
Initial hypotheses were tested against primary input from procurement leads at beverage manufacturers, R&D directors for alloy innovation, and environmental compliance officers. This involved combining insights from these industry stakeholders with secondary validation from LME price data, national environmental agency reports, and industry association publications. Bottom-up aggregation and top-down market sizing ensured data triangulation.
Variance decomposition disaggregated market growth drivers across the analysis window, modeling their individual contributions. The analytical framework segmented the market by product type, application, end-user industry, sales channel, and regional regulatory frameworks. Compound annual growth rates derived from historical trends and projected future demand. Key forecast inputs included recycled content targets and new beverage facility openings.
Decision-makers should treat outputs as directional under current regulatory and economic base assumptions; material deviation would warrant model refresh. Forecasts reflect these assumptions, acknowledging potential risks from commodity price shocks or unforeseen regulatory shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Drums Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Thailand Metal Packaging Market