
 Middle East and Africa Food Cans Market | 2026-2036
Middle East and Africa Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Cans Market Insights
Aluminum is hardening its position against traditional tinplate across the Middle East and Africa Food Cans landscape as weight reduction and recycling economics reshape product economics. Crown Holdings Inc. leverages its regional coil-coating infrastructure to supply beverage and food can makers across the Gulf. Ball Corporation anchors its position through dedicated two-piece aluminum can lines serving Nigerian and Kenyan brewers and soft-drink bottlers. Gulf Can Industries competes on proximity, operating extrusion and coating facilities within Saudi Arabia's industrial cities to serve domestic food processors.
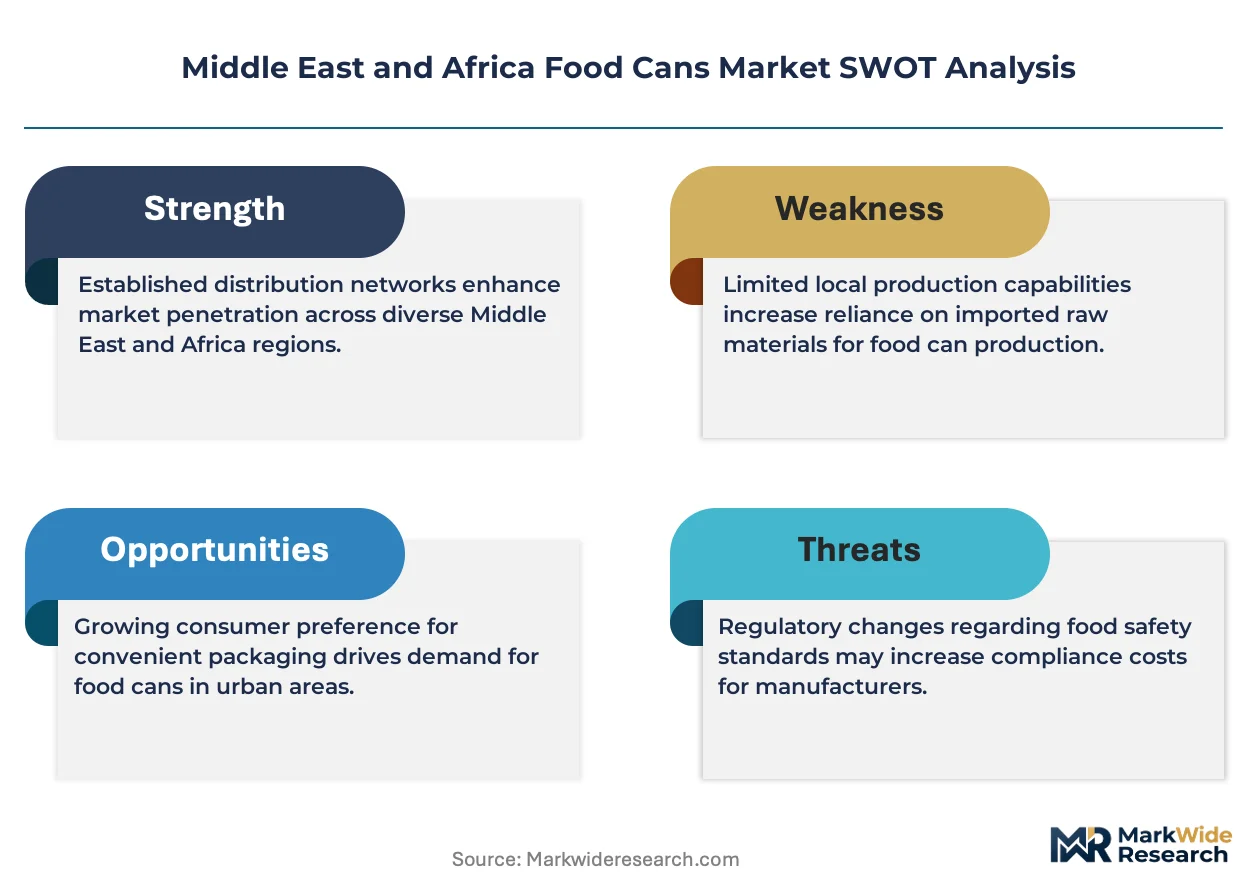
Food cans are cylindrical metal containers manufactured from aluminum or electrolytic tinplate, typically featuring double-seamed ends and interior lacquer coatings to prevent corrosion and preserve organoleptic properties; they function as hermetic barriers against oxygen, light, and microbial ingress for shelf-stable goods. Steel cans dominate volume across North African markets where tomato paste and cooking oil packaging sustain established supply chains, while aluminum cans capture expanding share in ready-to-eat segments where lightweighting and chilled distribution networks matter. Bio-based cans remain nascent but attract pilot interest from UAE-based food manufacturers seeking differentiation in export-oriented halal-certified product lines.
Saudi Food and Drug Authority standards for food-contact substances, South Africa's National Regulator for Compulsory Specifications labeling mandates, and Egypt's import substitution policies governing local content in packaging procurement collectively shape product specifications and market access corridors across the region. The UAE's Emirates Authority for Standardization and Metrology enforces Gulf Standardization Organization technical regulations that harmonize can dimensions and coating compliance across GCC trade blocs. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme proposals now under review in multiple Gulf states, as these mechanisms will determine future collection infrastructure investments and material circularity obligations.
Market Dynamics
Epoxy-phenolic lacquer migration is compressing legacy coating supply chains across the Middle East and Africa Food Cans market as South Africa's National Regulator for Compulsory Specifications tightens food-contact material enforcement.
Growth Catalysts
- Vision 2030 food security investments:Saudi Arabia's domestic canning capacity expansion for dates, dairy, and processed meats is pulling regional equipment and coating demand toward the Kingdom.
- Gulf Standardization Organization harmonization:UAE's Emirates Authority for Standardization and Metrology enforces unified can dimensions and coating compliance across GCC trade blocs, reducing cross-border friction for suppliers.
- Private-label shelf-stable expansion:Gulf retailers are accelerating canned fish and seafood offerings, creating sustained pull for two-piece aluminum can lines and interior lacquer systems.
Market Restraints
- Tinplate input cost volatility:Electrolytic tinplate pricing fluctuations constrain margin stability for North African tomato paste and cooking oil packers dependent on steel can supply chains.
- Coating formulation concentration:Epoxy-phenolic alternative suppliers cluster in European and Asian export hubs, exposing MEA can makers to currency and freight risk.
- Deposit-return scheme uncertainty:Extended producer responsibility frameworks under review in multiple Gulf states delay collection infrastructure investment planning.
Strategic Opportunities
- Kenyan and Nigerian brewer diversification:Two-piece aluminum can lines serving beverage markets can pivot capacity toward ready-to-eat food segments as chilled distribution networks mature.
- Halal-certified bio-based can pilots:UAE-based food manufacturers are testing plant-derived barrier coatings for export-oriented product differentiation.
- Egyptian import substitution:Local content mandates in packaging procurement create captive demand for domestic can forming and coating facilities.
Industry Challenges
- Coating technician scarcity:Epoxy-phenolic application expertise concentrates in legacy tinplate operations, creating workforce gaps as converters migrate to alternative chemistries.
- Legacy line reconfiguration capex:Interior lacquer system upgrades require substantial capital outlay for double-seam compatibility and curing oven modifications.
- Multi-regulator compliance sequencing:Simultaneous alignment with Saudi Food and Drug Authority substance standards and South African labeling mandates stretches quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Cans Market |
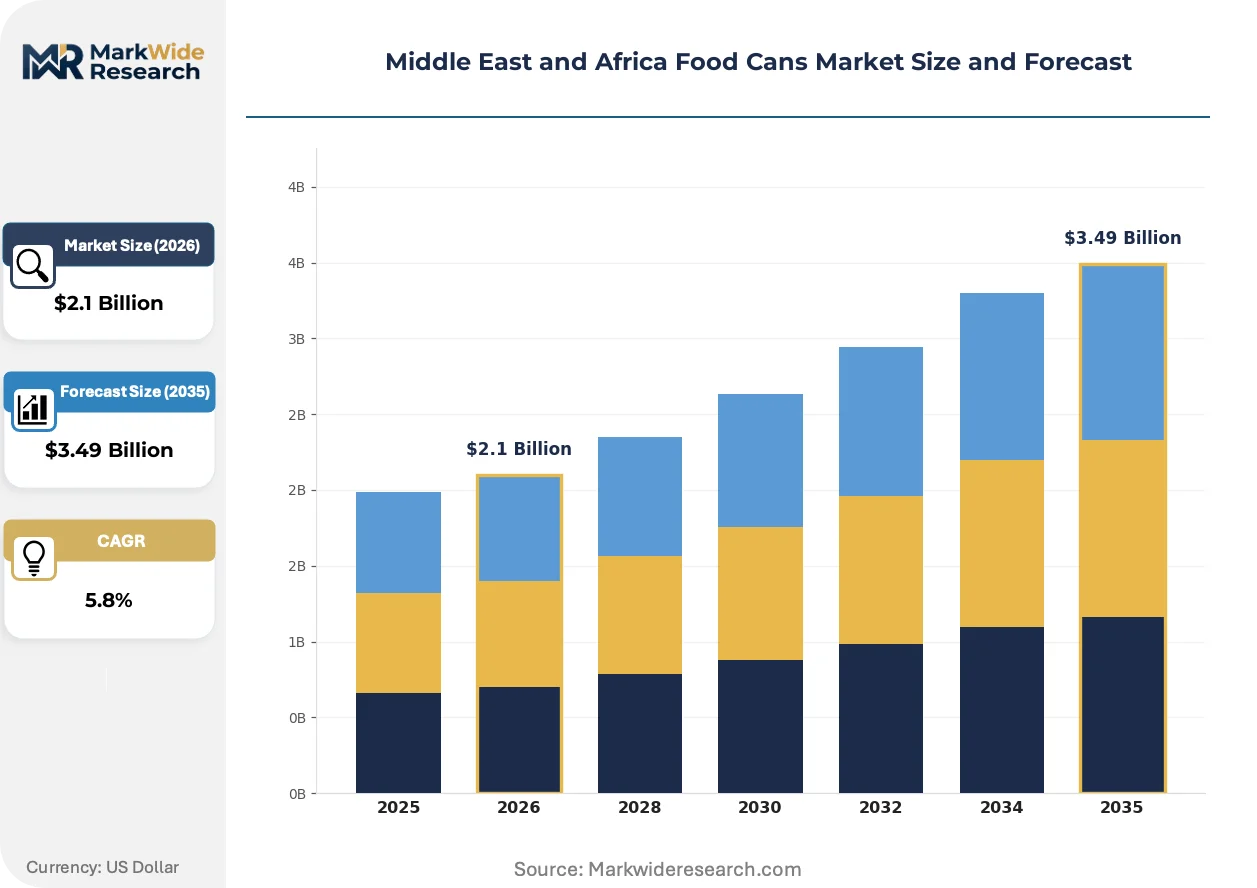
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Bio-Based Cans, Others End User: Food Manufacturers, Retail Chains, Foodservice Providers, Wholesalers Packaging Type: Ready-to-Eat, Preserved Goods, Beverages, Sauces Size: Small, Medium, Large, Extra Large |
| Companies Covered | Crown Holdings Inc., Ball Corporation, Metpac SA, Arabian Can Industry, Sapin UAE, Can-Pack SA, Gulf Can Industries, SAPIN Saudi Arabian Packaging Industry, Middle East Metal Can LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Cans Market Trends and Innovations
Active reshaping of the Middle East and Africa Food Cans market centers on coating chemistry transitions, regulatory harmonization pressures, and aluminum's displacement of legacy steel formats in temperature-sensitive distribution channels.
Digital inline coating inspection is automating quality control workflows for epoxy-phenolic lacquer application. Saudi and UAE can makers are adopting machine-vision systems at pilot scale to reduce human inspection bottlenecks. This technology is automating defect detection and compressing batch-release timelines for halal-certified export lines.
South Africa's National Regulator for Compulsory Specifications is accelerating food-contact material standards beyond legacy bisphenol-A thresholds. Industrial consequence includes forced reformulation of interior barrier coatings for tomato paste and cooking oil packers. North African steel can producers are responding by qualifying epoxy-phenolic alternatives ahead of enforcement deadlines.
Retailer consolidation across Gulf cooperative societies is compressing supplier negotiation cycles for private-label canned goods. Traditional distributor networks serving independent grocers face disintermediation as centralized procurement desks at Saudi and Emirati retail chains consolidate volume. This pattern concentrates specification-setting power with fewer buyers, privileging can makers with regional coil-coating infrastructure.
Middle East and Africa Food Cans Market Segmentation
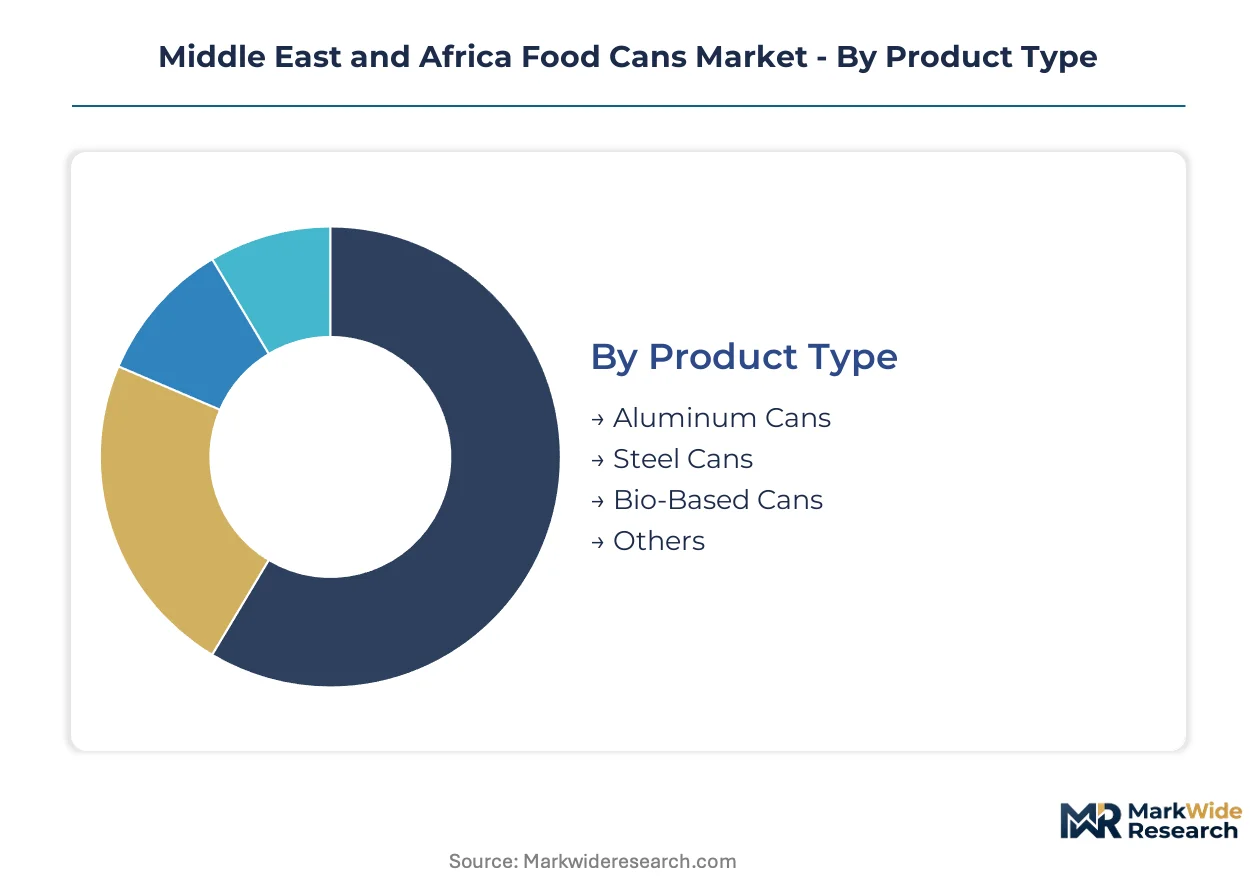
Food can specifications across the Middle East and Africa diverge sharply by material chemistry, end-use thermal requirements, and distribution channel cold-chain maturity. Understanding these segment boundaries clarifies why aluminum displaces steel in certain applications while legacy tinplate persists in others.
Product Type:
Material selection pivots on weight-to-strength ratios, recycling infrastructure access, and compatibility with epoxy-phenolic interior lacquer systems.
- Aluminum Cans:Two-piece drawn-and-wall-ironed construction delivers 30-40% weight reduction versus steel equivalents. Saudi Vision 2030 dairy and date canning investments are pulling demand toward aluminum lines for their compatibility with high-speed filling and chilled distribution.
- Steel Cans:Three-piece welded bodies with electrolytic tinplate coating dominate North African tomato paste and cooking oil packaging where established coil supply chains and lower material costs sustain volume leadership. South Africa's National Regulator for Compulsory Specifications is forcing accelerated coating reformulation timelines.
- Bio-Based Cans:Plant-derived barrier coatings and fiber-composite bodies attract pilot interest from UAE halal-certified exporters seeking differentiation in European premium retail.
- Others:Hybrid material constructions and experimental polymer-metal laminates remain confined to niche pharmaceutical-food crossover applications with limited regional penetration.
Steel cans lead on installed capacity scale; aluminum cans lead on investment momentum.
End User:
Procurement authority concentrates differently across contract manufacturing, captive retail networks, and institutional foodservice channels.
- Food Manufacturers:Date processors in Saudi Arabia's Al-Qassim region and dairy cooperatives in Kenya's Rift Valley operate dedicated canning lines with direct coating specification authority. Their technical staff negotiate directly with epoxy-phenolic suppliers.
- Retail Chains:Emirates-based hypermarket conglomerates and Saudi cooperative societies are consolidating private-label canned fish procurement under centralized technical desks, disintermediating traditional distributors.
- Foodservice Providers:Hotel chains and airline caterers in Dubai and Jeddah specify portion-controlled ready-to-eat formats with premium interior lacquer finishes for extended ambient holding.
- Wholesalers:Independent distributors serving fragmented North African independent grocers retain influence in steel can segments where specification flexibility and credit terms outweigh technical standardization.
Food manufacturers command specification authority; retail chains are gaining procurement concentration fastest.
Packaging Type:
Thermal processing requirements and shelf-stability demands segment can design priorities.
- Ready-to-Eat:Retort-compatible two-piece aluminum cans with modified atmosphere capabilities serve Nigerian and Kenyan urban consumers lacking reliable cold-chain access. Chilled distribution network expansion is enabling format migration.
- Preserved Goods:High-acid tomato paste and low-acid processed meat applications drive divergent interior coating specifications across Egypt's Nile Delta canneries.
- Beverages:Carbonated soft drink and malt beverage can lines operated by Nigerian brewers and Kenyan bottlers represent adjacent capacity that food can specifications increasingly reference.
- Sauces:Viscous product rheology demands wide-mouth steel can configurations with specialized double-seam profiles for clean dispensing.
Preserved goods anchor volume; ready-to-eat climbs fastest on distribution network maturation.
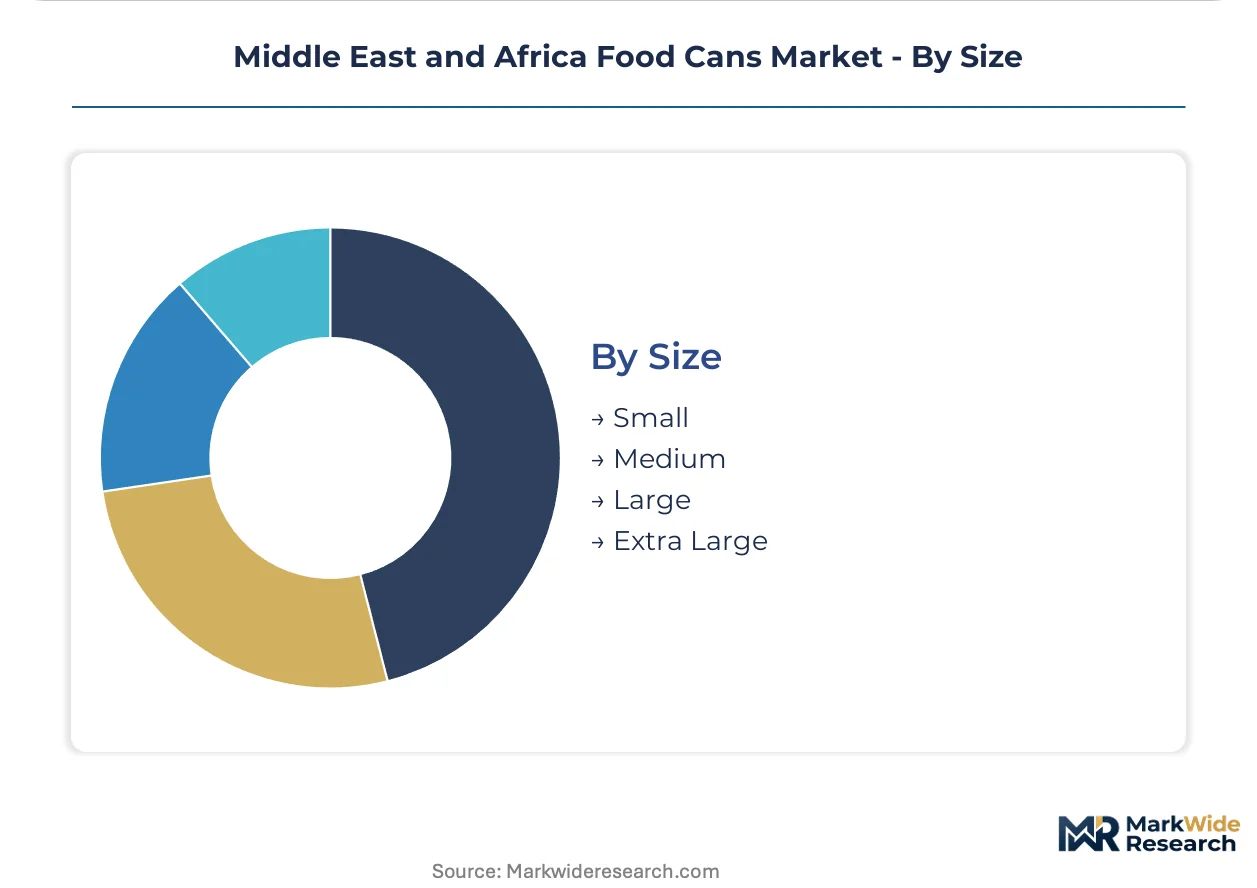
Size:
Portion economics and retail shelf-space allocation determine dimensional standardization.
- Small:Single-serve formats for airline catering and convenience retail in Dubai International Airport duty-free corridors.
- Medium:Family-size tomato paste and cooking oil cans dominating Egyptian and Moroccan household purchasing patterns.
- Large:Institutional foodservice quantities for Saudi Aramco camp feeding and UAE construction site catering contracts.
- Extra Large:Industrial ingredient packs for food manufacturers reprocessing canned fish into ready-meal components.
Medium sizes lead household penetration; small formats expand on travel-sector recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Province of Saudi Arabia anchors regional food can manufacturing through Jubail Industrial City's integrated aluminum extrusion and coating complexes serving domestic date and dairy processors.
Saudi Arabia
Vision 2030 investments are expanding canning capacity for dates, dairy, and processed meats across Al-Qassim and Riyadh. The Saudi Food and Drug Authority enforces strict food-contact substance standards that accelerate coating reformulation timelines. Jubail Industrial City hosts Gulf Can Industries' extrusion facilities supplying domestic food processors with proximity advantages.
United Arab Emirates
UAE-based halal-certified exporters are piloting bio-based barrier coatings for European premium retail differentiation. The Emirates Authority for Standardization and Metrology enforces Gulf Standardization Organization technical regulations harmonizing can dimensions across GCC trade blocs. Dubai's centralized retail procurement desks at hypermarket conglomerates are consolidating private-label canned fish volumes.
South Africa
The National Regulator for Compulsory Specifications is tightening food-contact material standards beyond legacy bisphenol-A thresholds. Tomato paste and cooking oil packers in the Western Cape are qualifying epoxy-phenolic alternatives ahead of enforcement deadlines. Cape Town's canning corridor faces coating technician scarcity as converters migrate from legacy tinplate chemistries.
Egypt
Import substitution policies governing local content in packaging procurement create captive demand for domestic can forming facilities. Nile Delta canneries operate divergent interior coating specifications for high-acid tomato paste versus low-acid processed meat applications. Alexandria's industrial zones sustain established steel can supply chains for household cooking oil packaging.
Nigeria
Two-piece aluminum can lines serving Lagos and Abuja brewers represent adjacent capacity pivoting toward ready-to-eat food segments. Chilled distribution network expansion enables format migration for urban consumers lacking reliable cold-chain access. Nigerian bottlers reference beverage can specifications when configuring food can production parameters.
Middle East and Africa Food Cans Market Competitive Landscape
Global majors compete with regional champions across coating infrastructure and proximity-to-customer dimensions. The vendor base clusters around three tiers: multinational coil-coating operators with integrated Gulf supply chains, Saudi and Emirati national champions embedded in domestic industrial cities, and North African steel can specialists serving established tomato paste markets. Strategic moves center on epoxy-phenolic lacquer migration investments and regional coil-coating capacity expansion.
Within the multinational tier, Crown Holdings Inc. and Ball Corporation exemplify integrated supply chain positioning. Crown leverages regional coil-coating infrastructure spanning beverage and food can makers across Gulf markets. Ball anchors through dedicated two-piece aluminum can lines. Gulf Can Industries occupies a position among proximity-focused national champions operating within Saudi Arabia's industrial cities to serve domestic food processors.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Ball Corporation |
| Metpac SA |
| Arabian Can Industry |
| Sapin UAE |
| Can-Pack SA |
| Gulf Can Industries |
| SAPIN Saudi Arabian Packaging Industry |
| Middle East Metal Can LLC |
| Others |
Pricing and Supply Chain Analysis
South Africa's National Regulator for Compulsory Specifications bisphenol-A phase-out mandates gate qualified supply for epoxy-phenolic lacquer systems and premium-tier pricing access for compliant can makers serving Saudi and Emirati food processors.
Pricing Analysis
Electrolytic tinplate cost pass-through volatility constrains margin stability for North African tomato paste packers dependent on steel can supply chains. Pricing stratifies across premium epoxy-phenolic compliant, standard legacy-coated, and economy uncoated tiers based on certification grade and volume scale. Cost compression in standard-tier steel cans is intensifying because currency exposure on European and Asian coating imports erodes converter margins. Retail chains with centralized procurement desks exhibit lowest price sensitivity; independent North African distributors serving fragmented grocers face highest pressure.
Supply Chain Analysis
Epoxy-phenolic resin supply rests on European and Asian specialty chemical producers, exposing MEA can makers to freight and currency risk. Raw material dependencies center on electrolytic tinplate coil, aluminum sheet stock, and interior lacquer formulations. Single-source vulnerability concentrates in coating formulation supply where alternative suppliers cluster outside the region. Distribution runs through Jubail Industrial City extrusion facilities and Alexandria steel coil stockists serving domestic food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Food Cans Market functions as a geographic-arbitrage play where Egyptian local content mandates create cost-advantaged supply positions against Gulf import-dependent coating infrastructure.
For Market Incumbents: Extend regional coil-coating capacity in Saudi Arabia's industrial cities to capture Vision 2030 date and dairy canning investments. Secure backward integration into epoxy-phenolic resin warehousing to buffer currency exposure on European imports. The threat of retailer procurement desk consolidation demands channel control through direct technical service relationships with Al-Qassim processors. For New Entrants and Emerging Players: SFDA substance standards in Saudi Arabia open a window for halal-certified bio-based barrier coating pilots targeting UAE export-oriented manufacturers. White-space targets cluster in Kenyan and Nigerian ready-to-eat segments where beverage can lines pivot toward food applications. The most penetrable geography is Egypt's Nile Delta under import substitution procurement rules. A technical specification partnership with domestic canneries offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap coating applicators with SFDA compliance because regulatory fragmentation prevents multinational scale and creates local champion premiums. Long-term viability hinges on positioning ahead of deposit-return scheme implementation across Gulf states. The acquisition target archetype is Saudi and Emirati can makers with installed two-piece aluminum capacity and direct retailer relationships. Watch for enforcement deadline announcements from South Africa's National Regulator for Compulsory Specifications as inflection indicators for coating chemistry switchover velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Epoxy-Phenolic Coating Migration | SFDA compliance investments by Saudi date processors lock in specification authority for qualified suppliers. |
| Regional Coil-Coating Expansion | Jubail Industrial City proximity reduces logistics costs for domestic food can makers serving Vision 2030 projects. |
| Bio-Based Barrier Pilot Programs | UAE halal-certified exporters test plant-derived coatings for European premium retail differentiation. |
| Beverage-to-Food Line Pivot | Nigerian and Kenyan brewers redirect two-piece aluminum capacity toward ready-to-eat segments. |
| Deposit-Return Infrastructure Pre-Positioning | Gulf state EPR framework proposals drive collection network investments ahead of mandate finalization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered coating application technicians at Egyptian and South African canneries, procurement leads at Saudi retail cooperative societies, epoxy-phenolic supplier technical directors, and SFDA regulatory affairs specialists. Secondary validation drew from Gulf Standardization Organization technical regulations, Saudi Food and Drug Authority substance standards filings, South African National Regulator for Compulsory Specifications enforcement notices, and customs trade data on tinplate and aluminum coil imports. Bottom-up cannery capacity tallies triangulated against top-down regional demand estimates.
Historical reference periods anchored the projection horizon through verified installed capacity figures and confirmed regulatory enforcement timelines. Segmentation modeling spanned material chemistry, end-use thermal requirements, distribution channel cold-chain maturity, and coating compliance tier. CAGRs were derived from segment-level volume build-ups cross-checked against macroeconomic consumption drivers. Forecast inputs incorporated Vision 2030 capital commitment announcements and coating technician workforce pipeline assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt currency devaluation or accelerated bisphenol-A ban enforcement. Assumptions reflect current regulatory trajectories and announced industrial investments. A small set of triggers—Gulf state deposit-return scheme finalization, Egyptian local content threshold adjustments, and epoxy-phenolic supplier entry into regional production—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Metal Cans Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Tin Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Metal Containers Market
Metal Packaging
Thailand Metal Packaging Market