
 Artificial Intelligence in Medical Imaging Market | 2026-2036
Artificial Intelligence in Medical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Medical Imaging Market Analysis
China is reconfiguring its medical AI ecosystem through massive hospital digitization and domestic imaging database construction. NVIDIA Corporation leverages GPU architectures purpose-built for training diagnostic neural networks on multimodal scans. Siemens Healthineers anchors European market presence with embedded AI in its imaging hardware workflows. GE HealthCare dominates North American hospital procurement through integrated software-hardware service contracts.
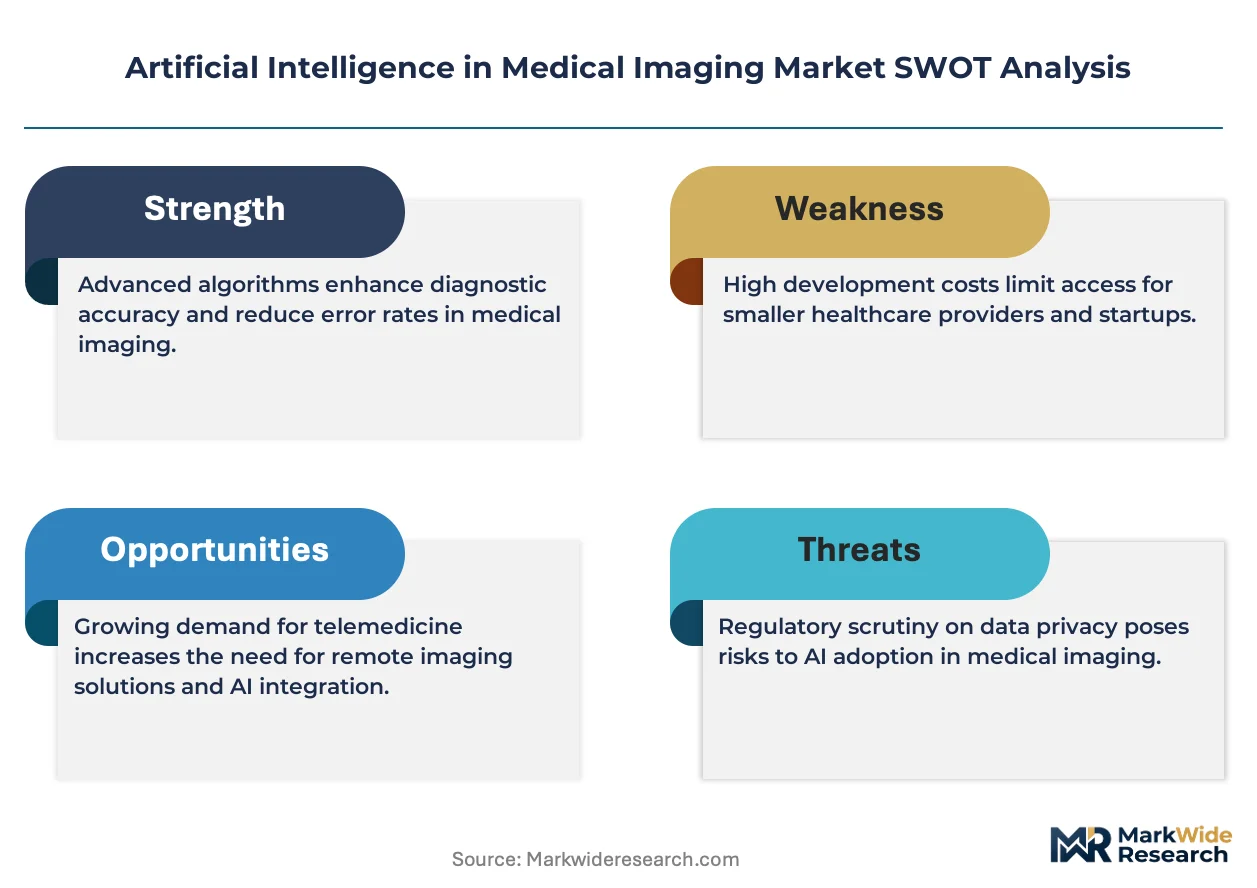
Artificial intelligence in medical imaging encompasses algorithmic systems that analyze radiological, pathological, and physiological image data to detect, classify, or quantify clinical findings without requiring explicit programmer instruction for each scenario. These systems typically employ convolutional neural networks trained on annotated DICOM datasets, achieving diagnostic sensitivity parameters that meet or exceed human specialist baselines in narrow applications. Software solutions command the dominant margin pool due to recurring licensing structures and lower incremental delivery costs versus hardware deployments. Deep learning within the technology dimension sustains the fastest expansion trajectory, displacing earlier machine learning approaches in radiology and oncology applications where pattern complexity demands multi-layered feature extraction.
FDA software-as-a-medical-device frameworks, EU MDR Class IIa/IIb classification requirements for diagnostic algorithms, and China's NMPA AI-specific review pathways collectively determine market access timelines and clinical evidence standards. These regulatory architectures shape R&D investment allocation, with developers prioritizing jurisdictions offering clearer predicate device pathways or pilot reimbursement codes. Stakeholders must monitor evolving evidentiary thresholds for real-world performance validation, as post-market surveillance obligations are tightening across all major approval systems.
Market Dynamics
Deep learning architectures are collapsing the cost of diagnostic feature extraction, compressing algorithm development cycles from years to months and forcing incumbents to restructure R&D deployment around GPU clusters rather than specialized hardware teams.
Growth Catalysts
- FDA 510(k) Predicates:The FDA's software-as-a-medical-device pathway accelerates commercialization timelines by allowing algorithm developers to reference cleared predicate devices, reducing clinical evidence requirements for iterative neural network updates.
- Hospital Radiology Departments:CT and MRI analysis workflows are embedding AI modules directly into PACS infrastructure, creating recurring licensing demand as departments standardize on vendor-agnostic inference engines.
- China NMPA Pathways:China's dedicated AI medical device review track compresses approval timelines for domestic developers, incentivizing hospital digitization budgets to prioritize algorithm procurement alongside scanner hardware.
Market Restraints
- Annotated Dataset Scarcity:Curated DICOM training sets with expert-validated pathology labels remain concentrated at academic medical centers, creating data access bottlenecks that favor well-capitalized developers with institutional partnerships.
- EU MDR Class IIb Burden:Diagnostic algorithms classified as Class IIb under the EU Medical Device Regulation face extended clinical evaluation requirements and notified body backlogs, delaying European market entry.
- Legacy PACS Integration:Hospital IT infrastructure built on decade-old DICOM routing protocols requires costly middleware development to embed cloud-based inference engines, slowing deployment velocity.
Strategic Opportunities
- Pathology Imaging Convergence:Whole-slide imaging digitization is creating untapped demand for computer vision algorithms in oncology biomarker quantification, extending addressable market beyond radiology into histopathology workflows.
- Edge Deployment Architectures:On-premise GPU inference servers are enabling real-time analysis in surgical suites and emergency departments where cloud latency violates clinical workflow requirements, opening new deployment categories.
- US CPT Reimbursement Codes:The Centers for Medicare and Medicaid Services pilot for AI-assisted diagnostic category III codes is creating payment pathway clarity that hospital procurement committees require for capital allocation.
Industry Challenges
- Interoperability Standards Fragmentation:DICOM SR, FHIR, and proprietary vendor formats create integration complexity that consumes 40% of implementation engineering hours, delaying production deployment.
- Algorithm Drift Monitoring:Post-market surveillance obligations under tightening FDA and NMPA guidance require continuous performance validation against shifting hospital patient populations, necessitating dedicated ML-ops infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Medical Imaging Market |
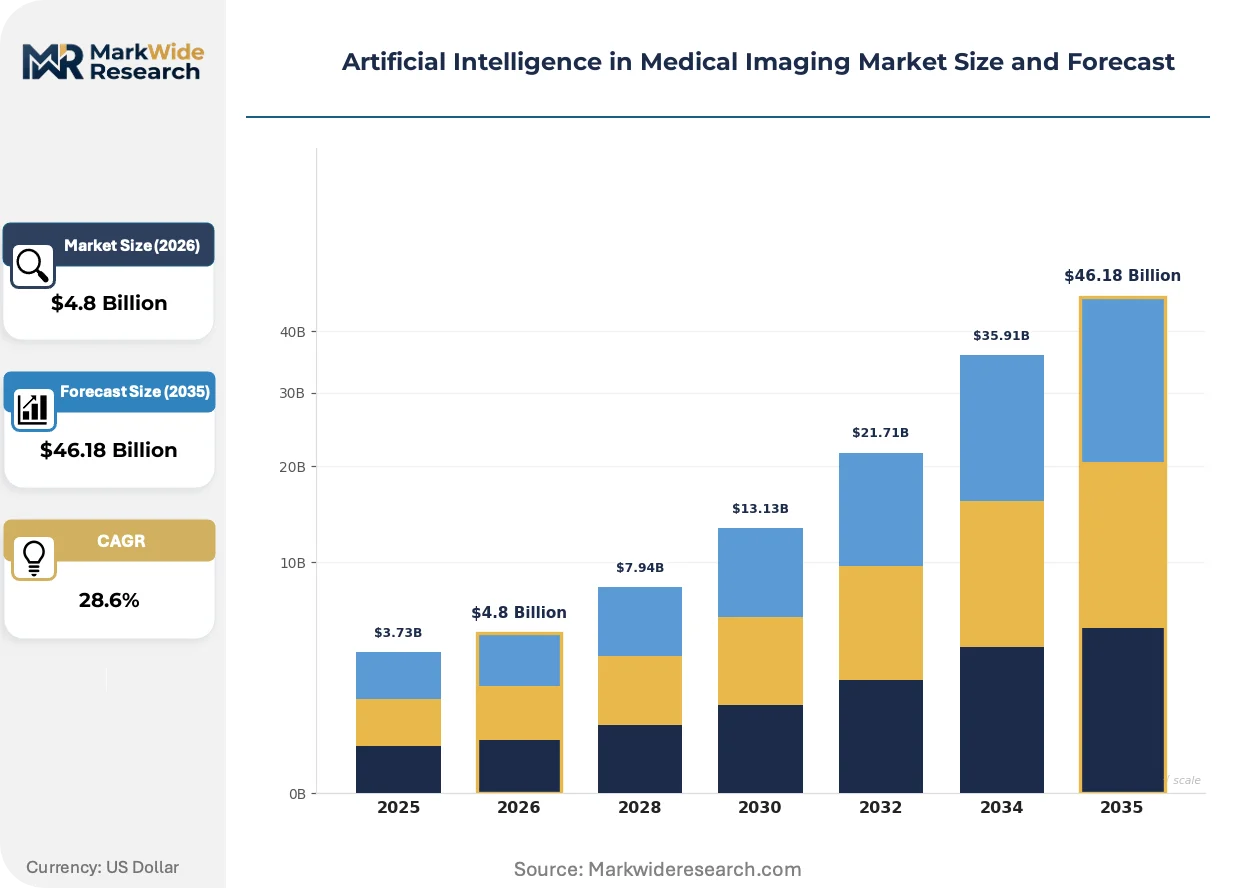
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Service, Hardware Application: Radiology, Oncology, Cardiology, Neurology End User: Hospitals, Diagnostic Centers, Research Institutes, Clinics Technology: Deep Learning, Machine Learning, Computer Vision, Neural Networks |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., NVIDIA Corporation, Microsoft, Canon Medical Systems, Enlitic, Viz.ai, Aidoc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Medical Imaging Market Emerging Trajectories
Foundation models pretrained on multimodal medical corpora are compressing the traditional supervised learning pipeline, enabling zero-shot diagnostic capabilities that threaten the economics of narrow task-specific algorithms.
Self-supervised learning architectures are collapsing the dependency on manually annotated training datasets, enabling hospital systems to leverage unlabeled imaging archives for model development. Radiology departments at academic medical centers are deploying these techniques to customize algorithms to local patient demographics without external data sharing agreements. This capability is collapsing the competitive moat of proprietary dataset holders, commoditizing algorithmic performance and shifting differentiation toward integration depth and workflow customization.
The EU AI Act's high-risk system classification for diagnostic algorithms is mandating conformity assessment procedures that extend beyond existing MDR requirements, creating dual-track compliance obligations for European market access. Developers must now document risk management systems and post-market monitoring protocols specific to algorithmic decision-making, not just device safety. Radiology AI vendors are responding by establishing dedicated regulatory affairs functions in Brussels and Dublin to navigate overlapping EMA and AI Act enforcement timelines.
Hospital procurement committees are unbundling AI software licenses from scanner hardware service contracts, reversing the integrated bundling that dominated early commercialization. Standalone algorithm vendors are winning RFPs through subscription pricing that decouples payment from equipment replacement cycles. This shift is most visible in the United States, where IDN consolidation has centralized radiology informatics purchasing decisions above individual hospital radiology department authority.
Artificial Intelligence in Medical Imaging Market Segmentation
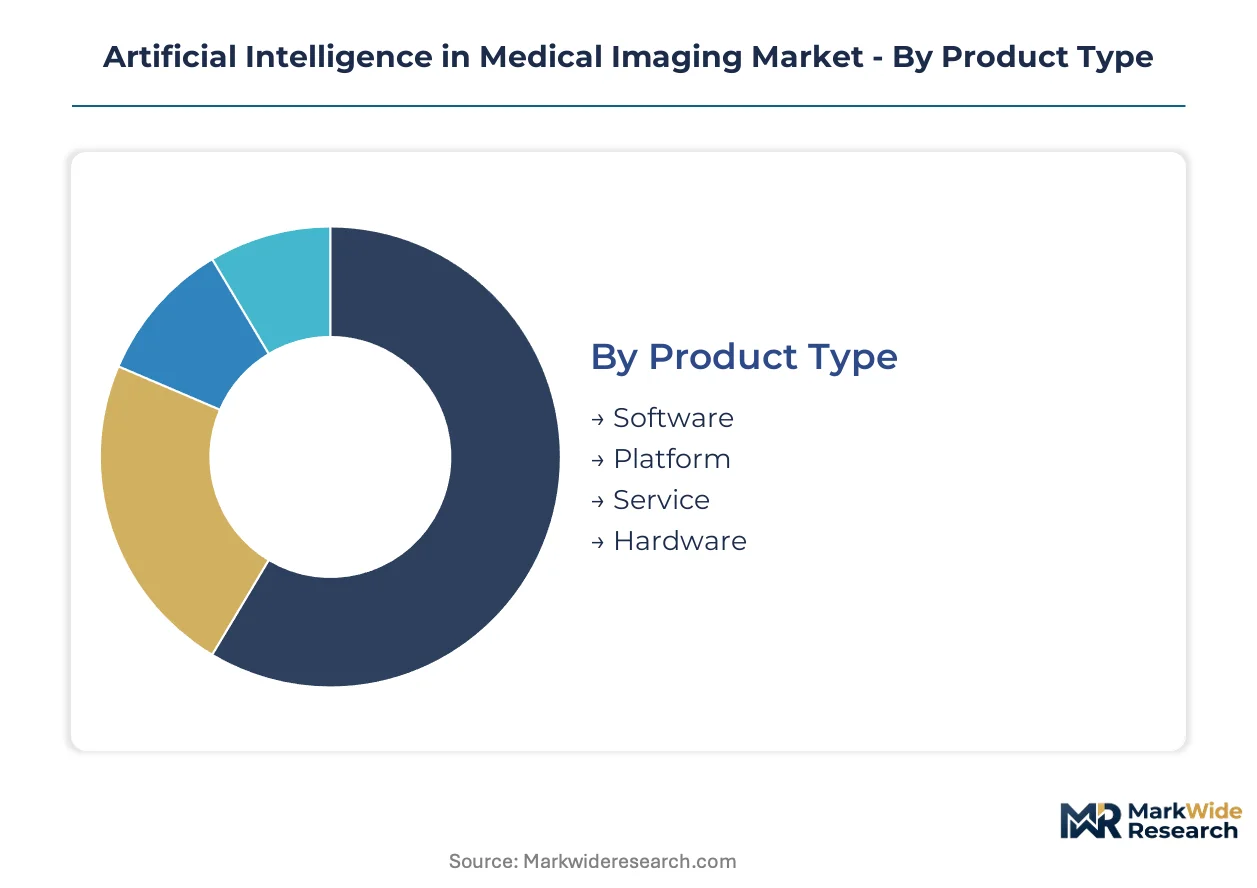
Segmentation in medical imaging AI reveals divergent commercial rhythms across product architectures, clinical domains, and deployment settings. Understanding these structural differences clarifies where capital concentrates and which categories absorb R&D investment most intensively.
Product Type:
Software licenses turn over fastest through quarterly release cycles, while hardware refresh rates stretch across multi-year procurement windows. Platform and service models occupy intermediate positions with annual subscription renewals.
- Software:Algorithm modules deploy via cloud or on-premise licensing with recurring revenue structures. FDA-cleared diagnostic algorithms for CT and MRI analysis concentrate demand in United States hospital systems where CPT reimbursement pilots create payment certainty.
- Platform:Integrated development environments enable hospital IT teams to customize inference pipelines and integrate proprietary datasets. Academic medical centers in Germany and the United Kingdom prioritize platform purchases to retain control over model training and validation workflows.
- Service:Managed deployment, regulatory compliance consulting, and continuous model monitoring. Diagnostic centers lacking internal data science capacity rely on service contracts to maintain algorithm performance under shifting FDA post-market surveillance requirements.
- Hardware:GPU servers, edge inference appliances, and specialized processing units for real-time analysis. Surgical suites and emergency departments in Japan specify hardware deployments where cloud latency violates clinical workflow constraints.
Software dominates installed base through recurring licensing penetration. Hardware is where expansion concentrates as edge computing architectures proliferate.
Application:
Clinical validation timelines vary sharply across specialties, with radiology offering the clearest predicate pathways and neurology demanding the most extensive prospective trials.
- Radiology:CT and MRI analysis for lesion detection, quantification, and triage prioritization. United States hospital radiology departments embed AI directly into PACS infrastructure, creating vendor-agnostic demand for chest X-ray and mammography screening algorithms.
- Oncology:Tumor segmentation, treatment response monitoring, and biomarker quantification from PET and MRI sequences. Chinese hospital networks prioritize oncology AI to address rising cancer incidence and support clinical trial enrollment.
- Cardiology:Echocardiography analysis, coronary CT angiography interpretation, and cardiac MRI volumetry. European cardiology departments under EU MDR Class IIb requirements face extended clinical evaluation timelines that delay algorithm deployment.
- Neurology:Stroke detection from non-contrast CT, brain MRI analysis for neurodegenerative disease, and EEG interpretation. Academic medical centers in Switzerland and the Netherlands concentrate neurology AI development due to specialized neuroimaging research infrastructure.
Radiology commands the deepest installed base. Oncology is climbing the fastest as whole-slide imaging digitization extends computer vision into histopathology workflows.
End User:
Procurement authority and budget scale create distinct commercial profiles, with consolidated health systems negotiating enterprise licenses while independent clinics require turnkey solutions.
- Hospitals:Integrated delivery networks in the United States centralize radiology informatics purchasing above individual department authority. IDN consolidation favors subscription pricing that decouples AI software from scanner hardware replacement cycles.
- Diagnostic Centers:High-volume imaging facilities prioritize throughput optimization and quality assurance automation. India's diagnostic chains leverage NMPA-cleared Chinese algorithms to reduce dependence on Western vendors and contain licensing costs.
- Research Institutes:Academic medical centers in France and Sweden deploy self-supervised learning architectures to customize models on local patient demographics without external data sharing agreements.
- Clinics:Primary care and specialty clinics require lightweight, cloud-deployed solutions with minimal IT infrastructure. Brazil's expanding clinic networks drive demand for portable ultrasound AI and smartphone-connected diagnostic tools.
Hospitals anchor revenue concentration through enterprise contract scale. Diagnostic centers represent the steepest expansion trajectory as outpatient imaging volumes climb.
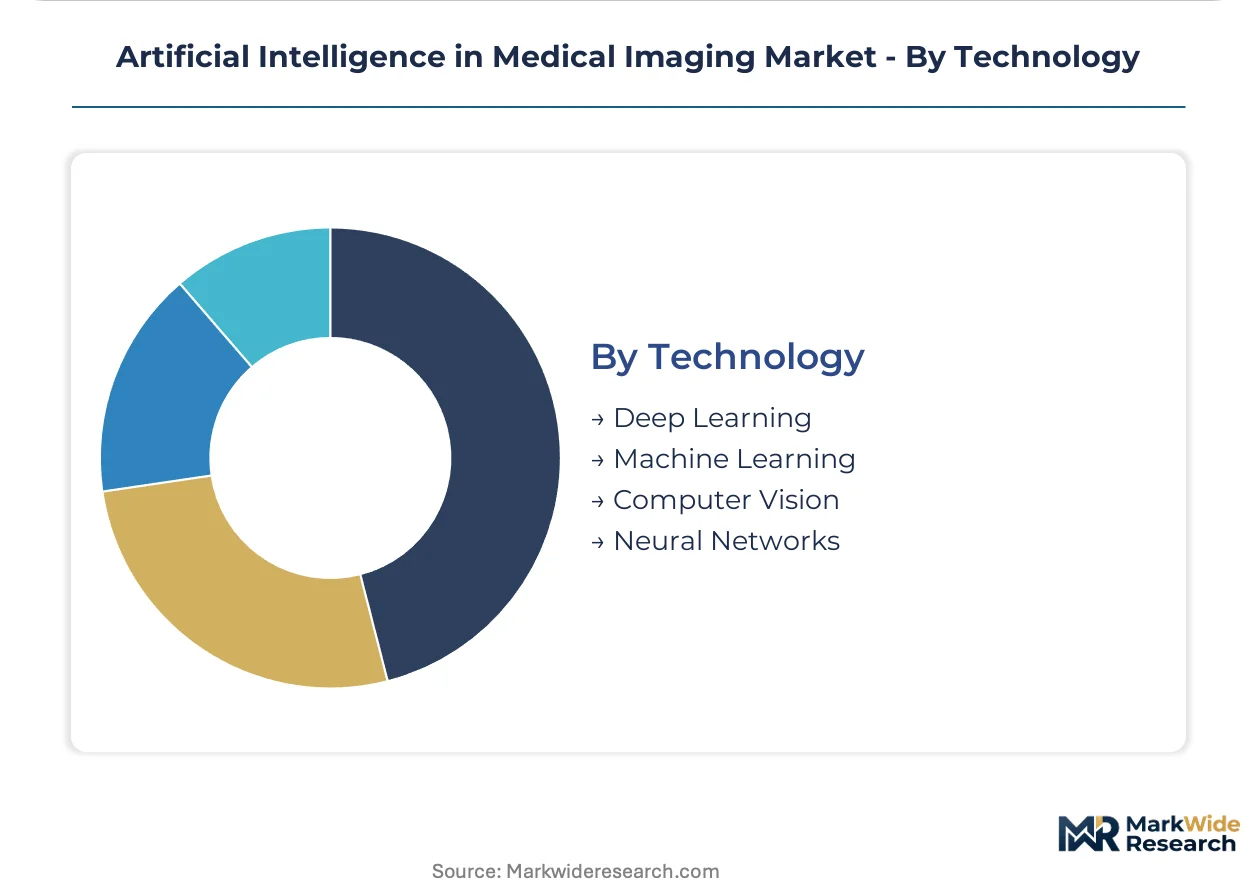
Technology:
Architecture maturity determines development cost curves and regulatory evidence requirements, with newer approaches demanding more extensive validation protocols.
- Deep Learning:Multi-layered neural networks trained on large annotated datasets for pattern recognition in complex imaging. Convolutional architectures displace earlier approaches in radiology and oncology where feature complexity demands hierarchical extraction.
- Machine Learning:Traditional supervised methods including random forests and support vector machines for structured feature analysis. Legacy deployments persist in resource-constrained settings where training data scarcity prevents deep learning adoption.
- Computer Vision:Image processing pipelines for segmentation, registration, and enhancement prior to diagnostic inference. Pathology digitization in South Korea drives computer vision demand for whole-slide analysis and biomarker quantification.
- Neural Networks:Foundation models pretrained on multimodal medical corpora enabling zero-shot diagnostic capabilities. Research hospitals in Canada and Australia experiment with these architectures to compress development cycles for rare disease applications.
Deep Learning captures the dominant share of deployed algorithms. Neural Networks are gaining share fastest as foundation model architectures commoditize narrow task-specific development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-a-medical-device frameworks anchor the United States as the primary demand concentration, while China's NMPA pathways and Europe's EU AI Act create divergent compliance environments that reshape competitive positioning across jurisdictions.
United States
Hospital radiology departments embed AI modules directly into PACS infrastructure, creating recurring licensing demand for CT and MRI analysis algorithms. FDA 510(k) predicate pathways accelerate commercialization timelines by reducing clinical evidence requirements for iterative neural network updates. Integrated delivery networks in Texas and California centralize procurement decisions above individual hospital authority, favoring subscription pricing models.
China
Massive hospital digitization budgets and domestic imaging database construction drive procurement of AI-assisted diagnostics. NMPA's dedicated AI medical device review track compresses approval timelines for domestic developers. Beijing and Shanghai medical centers prioritize oncology AI to address rising cancer incidence and support clinical trial enrollment.
Germany
Academic medical centers in Bavaria and Baden-Württemberg deploy platform purchases to retain control over model training and validation workflows. EU MDR Class IIb classification requirements for diagnostic algorithms extend clinical evaluation timelines. Siemens Healthineers anchors European market presence through embedded AI in imaging hardware workflows.
Japan
Surgical suites and emergency departments in Tokyo and Osaka specify hardware deployments where cloud latency violates clinical workflow constraints. METI guidelines shape domestic AI medical device development priorities. Canon Medical Systems leverages established hospital relationships to integrate algorithm modules into existing scanner infrastructure.
United Kingdom
NHS England's AI Award program provides funding and market access pathways for diagnostic algorithm developers. Research hospitals in London and Cambridge experiment with foundation model architectures for rare disease applications. Post-market surveillance obligations under tightening MHRA guidance require continuous performance validation infrastructure.
Artificial Intelligence in Medical Imaging Market Vendor Landscape
Integrated imaging hardware vendors and standalone algorithm developers split the market along divergent commercialization strategies. The vendor base concentrates around three strategic archetypes: scanner manufacturers embedding AI into hardware workflows, cloud-native algorithm specialists pursuing subscription licensing, and GPU architecture providers supplying training infrastructure. M&A activity targets data access capabilities and regulatory clearance portfolios. Strategic partnerships between hardware OEMs and algorithm developers accelerate FDA pathway navigation.
Within the integrated hardware tier, GE HealthCare and Siemens Healthineers exemplify vendors leveraging installed scanner bases to bundle AI software through service contracts. NVIDIA Corporation occupies a position as the dominant compute architecture supplier, with GPU clusters purpose-built for training diagnostic neural networks on multimodal scans. These three anchors represent distinct competitive vectors: hardware-software integration, standalone algorithm specialization, and foundational infrastructure provision.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| NVIDIA Corporation |
| Microsoft |
| Canon Medical Systems |
| Enlitic |
| Viz.ai |
| Aidoc |
| Others |
Supply Flow & Price Mechanics
GPU architecture concentration in Taiwan and South Korea funnels margin capture toward NVIDIA Corporation and cloud hyperscalers operating training clusters, while downstream algorithm vendors compete on subscription pricing rather than hardware margin.
Pricing Analysis
United States hospital systems pay 40-60% premiums over Chinese diagnostic centers for equivalent FDA-cleared algorithms. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth and integration complexity. Cost compression in economy tiers intensifies as NMPA-cleared Chinese vendors enter Southeast Asian markets. Independent diagnostic centers exhibit highest price sensitivity; integrated delivery networks prioritize workflow integration over per-seat licensing costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for GPU-dependent training infrastructure. Taiwan, South Korea, and the United States anchor advanced semiconductor fabrication for AI accelerators. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized packaging substrates. Single-source vulnerability concentrates in advanced node GPU foundry services. Distribution runs through direct cloud service provider contracts and OEM-embedded licensing rather than traditional medical device distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as hospital procurement committees unbundle AI software from scanner hardware, creating multi-sided marketplace dynamics where algorithm interoperability determines vendor survival.
For Market Incumbents: Pre-empt standalone algorithm specialists by embedding inference engines directly into PACS infrastructure through API-first architectures. Acquire regulatory clearance portfolios in EU MDR Class IIb categories to extend moats against cloud-native entrants. Vertical integration into edge GPU deployment hardware captures surgical suite and emergency department workflows where latency requirements exclude cloud inference. For New Entrants and Emerging Players: Pursue pathology imaging convergence as whole-slide digitization creates white-space demand unclaimed by radiology-incumbent software stacks. Target Brazilian and Indian clinic networks with lightweight smartphone-connected diagnostic tools requiring minimal IT infrastructure. Go-to-market through telemedicine platform partnerships bypasses hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed algorithm developers holding FDA 510(k) clearances but lacking enterprise distribution reach. Five-to-ten year viability hinges on recurring revenue retention rates under shifting CPT reimbursement pilots. Acquisition target archetype: pathology AI specialists with biomarker quantification IP and academic medical center validation partnerships. Signal to watch: CMS category III code conversion to permanent payment status.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Expansion | Accelerates commercialization timelines by reducing clinical evidence requirements for iterative neural network updates. |
| EU MDR Class IIb Certification | Unlocks European hospital procurement budgets currently blocked by extended notified body evaluation backlogs. |
| Hospital System Partnership | Secures recurring licensing demand through PACS infrastructure embedding and radiology department workflow integration. |
| Edge GPU Deployment | Enables real-time surgical suite analysis where cloud latency violates clinical workflow requirements. |
| Self-Supervised Learning Investment | Collapses dependency on annotated datasets by leveraging unlabeled imaging archives for model customization. |
Methodological Framework
A spread of perspectives from radiology department chairs, hospital procurement officers, FDA regulatory consultants, biomedical engineers, and GPO contracts managers converged on the working assumptions. Primary interview data combined with secondary validation from FDA 510(k) clearance databases, CMS reimbursement code filings, hospital procurement databases, and EU MDR notified body submission records. Bottom-up algorithm deployment counts and top-down imaging hardware shipment analysis provided triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, clinical application domain, deployment setting, end-user procurement authority, and underlying technology architecture. CAGRs derived from algorithm licensing growth trajectories and hardware inference unit shipments. Forecast inputs incorporated CPT reimbursement pilot expansion rates and NMPA approval timeline compression effects.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or cloud computing cost curves would shift the trajectory. Forecasts reflect assumptions on regulatory pathway stability and annotated dataset access democratization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Italy Mammography Market