
 Flow Cytometry Market | 2026-2036
Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Cytometry Market Intelligence
The fragmentation of the end-user base across specialized biotech firms and diagnostic laboratories is decoupling purchasing decisions from large, centralized academic institutions. This shift creates opportunities for vendors with tailored solutions. Becton, Dickinson and Company leverages its extensive installed base in clinical settings. Thermo Fisher Scientific competes with a broad portfolio of reagents and consumables. Cytek Biosciences differentiates through its full-spectrum technology, targeting high-parameter research applications.
Flow cytometry is a biophysical technology used to analyze single cells or particles suspended in a fluid stream. It measures their characteristics by passing them through one or more laser beams, detecting scattered light and fluorescent signals. Cell analyzers form the foundational instrument segment, while the reagents and consumables segment generates consistent recurring revenue. Immunology research remains a primary application, driving volume for both instruments and associated chemical reagents.
Regulatory frameworks from the US FDA and the European Union's MDR dictate the validation requirements for clinical diagnostic systems. In parallel, China's NMPA has established stringent local approval pathways for both instruments and reagents entering its domestic market. Instrument manufacturers must decide whether to pursue an open-platform strategy compatible with third-party reagents or a closed-system model to capture recurring revenue.
Market Dynamics
Divergent national regulatory frameworks are the central force shaping the flow cytometry market, compelling manufacturers to pursue localized validation strategies. The need to comply with distinct requirements from the US FDA, EU's MDR, and China's NMPA fragments global product roadmaps.
Growth Catalysts
- Oncology Applications:Expanding use in cancer diagnostics for monitoring minimal residual disease drives adoption in pharmaceutical and clinical labs.
- Government Funding:Significant government investment in life science infrastructure, especially in China, accelerates the procurement of advanced cytometry platforms.
- Immunology Research:Demand for deep immune profiling in vaccine research fuels sales of full-spectrum instruments and associated antibody reagents.
Market Restraints
- High Instrument Cost:The significant capital expenditure for advanced full-spectrum and cell sorting cytometers limits adoption by smaller research labs.
- Regulatory Hurdles:Stringent validation pathways, including the EU's MDR and FDA premarket approval, create lengthy barriers to entry for new clinical systems.
- Data Analysis Complexity:Analyzing high-dimensional data from modern cytometers requires specialized bioinformatics expertise, creating an operational bottleneck for many end-users.
Strategic Opportunities
- Emerging Clinical Markets:Untapped demand for clinical flow cytometry systems exists in countries like Brazil and India as their healthcare infrastructure modernizes.
- Cell Therapy Quality Control:Integrating flow cytometry into biomanufacturing workflows for quality control of cell and gene therapies represents a new high-value application.
- Point-of-Care Instruments:Developing miniaturized, portable flow cytometers can serve decentralized testing needs in remote locations or smaller clinics.
Industry Challenges
- Specialized Talent Scarcity:A shortage of technicians and bioinformaticians skilled in operating complex cytometers and interpreting high-dimensional data hinders effective utilization.
- Inter-laboratory Standardization:A lack of standardized protocols and reference materials makes it difficult to compare data across different sites, impacting multi-center clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Cytometry Market |
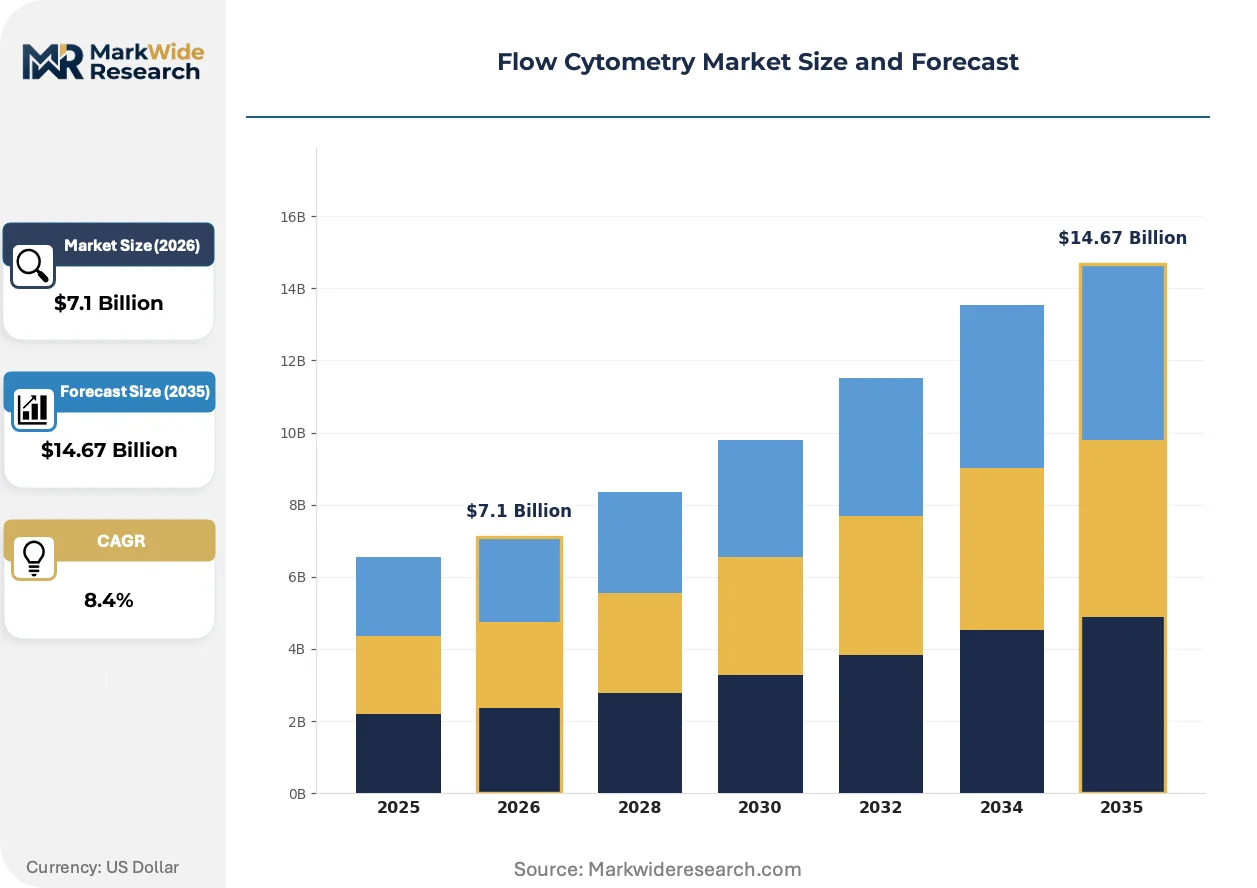
| Market Size in 2026 | $7.1 Billion |
| Market Size in 2035 | $14.67 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Analyzers, Cell Sorters, Reagents, Software Solutions, Consumables Technology: Laser-Based, Image Cytometry, Magnetic Activated, Acoustic Focusing, Electrical Impedance Application: Immunology Research, Cancer Diagnostics, Microbiology, Drug Development, Agricultural Science End User: Research Institutes, Pharmaceutical Manufacturers, Diagnostic Laboratories, Academic Centers, Biotech Firms |
| Companies Covered | Sysmex Corporation, Agilent Technologies, Becton, Dickinson and Company, Cytek Biosciences, Miltenyi Biotec, Danaher Corporation, Bio-Rad Laboratories, Sony Biotechnology, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Cytometry Market Strategic Shifts & Innovations
Automation and data integration are defining the next generation of flow cytometry platforms. The market is moving toward systems that reduce manual intervention and streamline complex analytical workflows, driven by demands for higher throughput and reproducibility in both research and clinical settings.
Full-spectrum flow cytometry captures the entire emission profile from each particle, significantly enhancing the resolution of complex cell populations. High-complexity immunology and oncology research laboratories are the primary adopters, seeking to maximize data from a single tube. The technology is expanding into clinical diagnostics, enabling deeper immunophenotyping from limited patient samples and supporting complex biomarker discovery.
The European Union's Medical Device Regulation (MDR) imposes more stringent requirements for clinical evidence and post-market surveillance on manufacturers. This regulation directly increases the time and cost associated with achieving CE marking for diagnostic flow cytometry systems. Consequently, instrument and reagent vendors targeting the European clinical market are investing heavily in their quality management systems and clinical validation data.
A notable shift in purchasing behavior involves end-users evaluating closed-system models that pair specific instruments with proprietary, pre-optimized reagents. This integrated approach is displacing the traditional open-platform strategy in clinical diagnostic labs that prioritize workflow simplification and result standardization. This trend is most visible in high-throughput clinical environments in the United States and Europe where reproducibility is paramount.
Flow Cytometry Market Segmentation
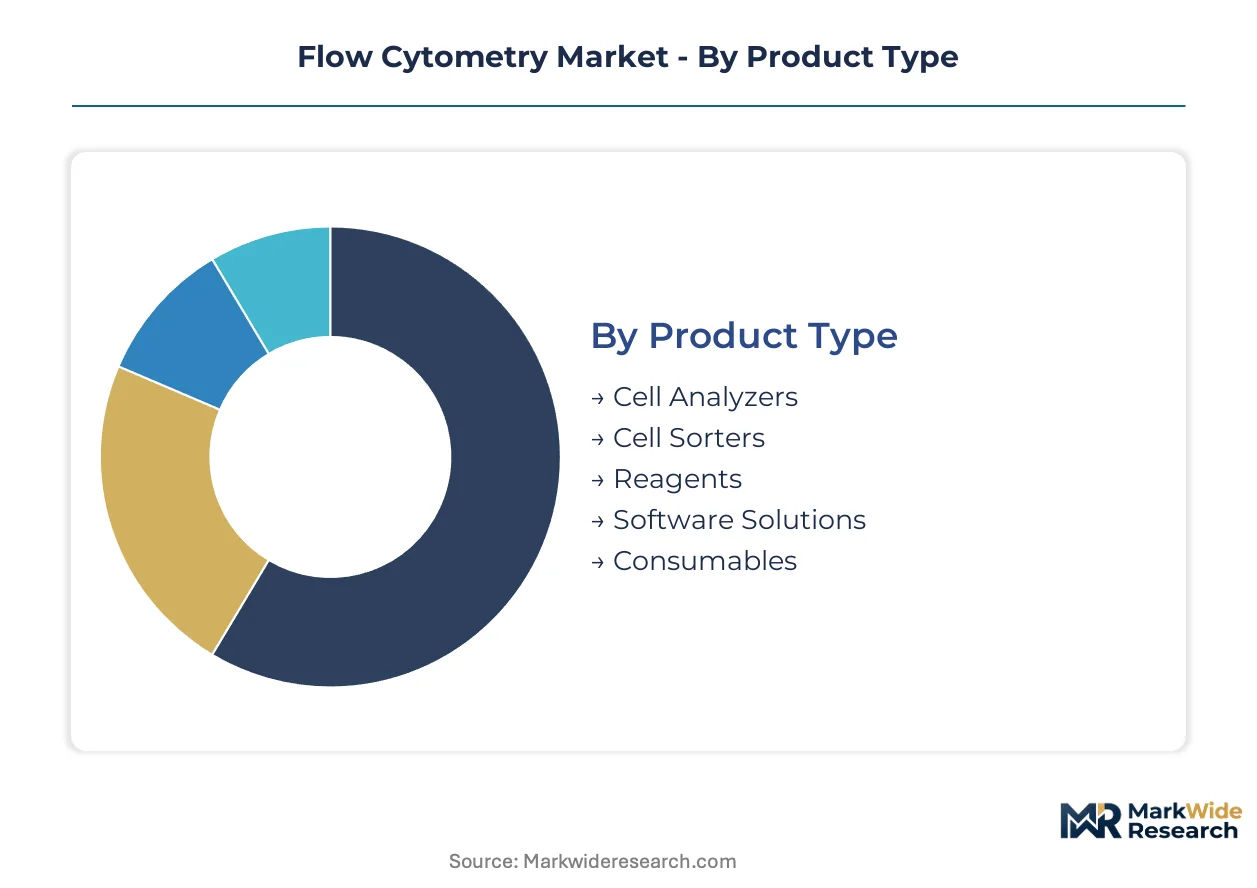
The flow cytometry market exhibits a diverse segmentation, driven by specialized product requirements, technological advancements, varied application needs, and distinct end-user operational models. Understanding these segments is crucial for manufacturers to tailor product development and market entry strategies effectively.
Product Type:
Capital expenditure requirements significantly differentiate product segments within flow cytometry, influencing adoption rates and vendor strategies.
- Cell Analyzers:These foundational instruments measure characteristics of single cells or particles, detecting scattered light and fluorescent signals. Demand for these systems concentrates in clinical diagnostic laboratories and academic research institutions, driven by routine immunophenotyping and disease monitoring.
- Cell Sorters:Advanced cell sorters isolate specific cell populations with high purity for downstream applications like cell therapy development or genomic analysis. Pharmaceutical manufacturers and specialized biotech firms increasingly procure these high-throughput systems to advance complex research initiatives.
- Reagents:This segment includes antibodies, dyes, and buffers essential for cell staining and analysis.
- Software Solutions:Data analysis software and instrument control platforms manage complex data acquisition and interpretation.
- Consumables:Tubes, plates, and other disposable labware support daily flow cytometry operations.
Most installed capacity flows through Cell Analyzers. Expansion is steepest in Reagents.
Technology:
Technological differentiation provides distinct advantages in terms of throughput, resolution, and sample preparation, catering to varied research and clinical needs.
- Laser-Based:This core technology uses one or more laser beams to excite fluorochromes on cells, detecting scattered light and fluorescent signals. It remains the most widely adopted technology across academic research and clinical diagnostic laboratories globally, valued for its robust performance.
- Image Cytometry:Combining microscopy with flow cytometry, this technology captures high-resolution images of individual cells, enabling morphological analysis alongside fluorescent intensity. Oncology applications and drug discovery pipelines in pharmaceutical manufacturers increasingly leverage image cytometry for detailed phenotypic profiling.
- Magnetic Activated:Magnetic beads selectively label and separate cell populations based on specific surface markers.
- Acoustic Focusing:This method uses sound waves to align cells in a single file, improving data acquisition precision and speed.
- Electrical Impedance:Measures changes in electrical resistance as cells pass through an aperture, providing cell size and count data.
The broadest market penetration belongs to Laser-Based systems. New research frontiers are being opened by Image Cytometry.
Application:
Specific application areas dictate instrument configurations and reagent panels, reflecting divergent scientific and clinical priorities.
- Immunology Research:This application involves deep immune profiling, cell subset identification, and functional studies, particularly in vaccine development and autoimmune disease investigation. Academic centers and biotech firms represent the largest end-users, driving consistent demand for high-parameter systems.
- Cancer Diagnostics:Flow cytometry identifies and quantifies malignant cells, monitors minimal residual disease, and characterizes tumor heterogeneity. Clinical diagnostic laboratories and pharmaceutical manufacturers increasingly adopt these systems for patient stratification and treatment monitoring, especially in China.
- Microbiology:Used for bacterial and fungal cell analysis, enumeration, and viability assessment in environmental and clinical samples.
- Drug Development:Supports drug screening, target validation, and toxicity testing in pharmaceutical research pipelines.
- Agricultural Science:Analyzes plant and animal cells for genetic research, pathology, and quality control.
Immunology Research contributes the most significant revenue. Cancer Diagnostics exhibits the most dynamic growth trajectory.
End User:
End-user segments vary significantly in their operational scale, regulatory requirements, and budget constraints, influencing procurement patterns.
- Research Institutes:These organizations engage in fundamental scientific inquiry across diverse disciplines, requiring versatile flow cytometry platforms for exploratory studies. Government funding initiatives in countries like China directly stimulate procurement of advanced systems by these institutes.
- Diagnostic Laboratories:Clinical diagnostic labs prioritize standardized, high-throughput systems for routine patient testing, including immunophenotyping and disease monitoring. Regulatory frameworks like the EU's MDR drive demand for validated, closed-system solutions within these environments.
- Pharmaceutical Manufacturers:Integrate flow cytometry into drug discovery, development, and quality control processes.
- Academic Centers:Focus on basic research and education, often with shared core facilities for cytometry equipment.
- Biotech Firms:Specialized companies leveraging flow cytometry for cell therapy development, biomarker discovery, and niche diagnostic applications.
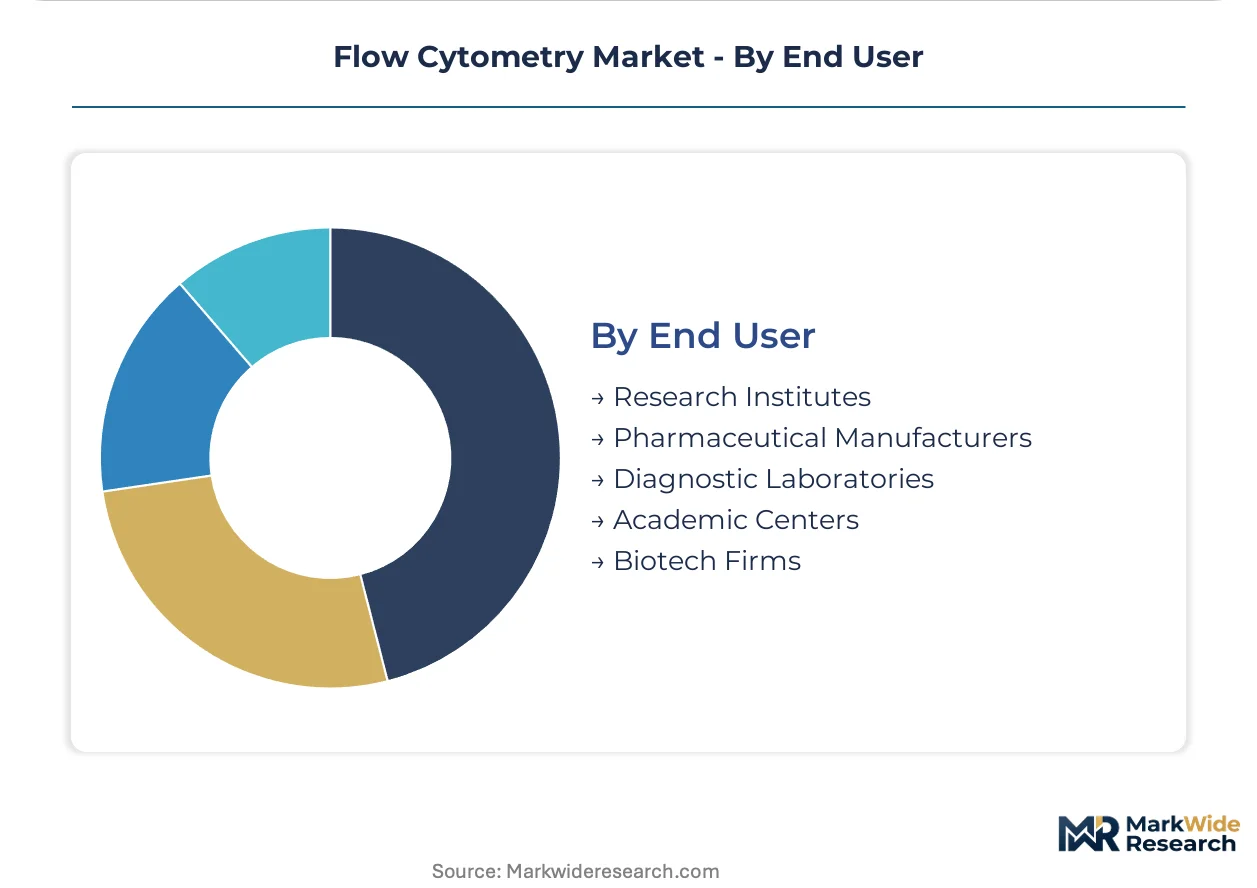
Research Institutes maintain the largest installed base of instruments. Future demand is increasingly driven by Diagnostic Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized scientific talent concentrations drive the adoption of advanced flow cytometry platforms across key global hubs. Demand in these regions reflects both established research infrastructure and evolving clinical diagnostic needs. Localized regulatory frameworks significantly shape market access and product validation strategies for manufacturers.
United States
Immunology research and cell therapy quality control applications generate significant demand for flow cytometry systems. The US FDA's stringent validation requirements influence the development of clinical diagnostic systems. Major biotech hubs like Boston and San Francisco accelerate advanced research and technology adoption.
China
Government investment in life sciences infrastructure and expanding cancer diagnostics applications propel market growth. China's NMPA has established stringent local approval pathways for both instruments and reagents. The Yangtze River Delta region, with its numerous research institutions, drives accelerated procurement of advanced platforms.
Germany
Academic research in immunology and pharmaceutical manufacturing processes create demand for high-parameter cytometers. The European Union's Medical Device Regulation (MDR) dictates rigorous clinical evidence and post-market surveillance. Munich's vibrant biotech cluster focuses on instrument and reagent validation for the European market.
Japan
Advanced immunology research and robust drug development pipelines require sophisticated flow cytometry solutions. The PMDA, Japan's pharmaceutical and medical device agency, oversees medical device approvals. Tokyo's extensive network of research institutions and universities drives demand for high-parameter systems.
India
Modernizing healthcare infrastructure and the emergence of new clinical markets are stimulating interest in flow cytometry. The CDSCO, India's central drug authority, regulates medical devices and diagnostics. Bengaluru's growing life science parks are exploring decentralized testing needs and localized manufacturing.
Flow Cytometry Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the flow cytometry market. The market structure features both large, established players offering broad portfolios and agile innovators introducing disruptive technologies. Strategic partnerships and portfolio diversification are dominant competitive moves for market participants.
Established players with extensive installed bases, such as Becton, Dickinson and Company, anchor significant portions of the clinical market. Thermo Fisher Scientific exemplifies a broad portfolio provider, offering a comprehensive suite of reagents and consumables. Cytek Biosciences occupies a position as a technology innovator, differentiating through its full-spectrum technology for high-parameter research applications.
| Leading Market Players |
|---|
| Sysmex Corporation |
| Agilent Technologies |
| Becton, Dickinson and Company |
| Cytek Biosciences |
| Miltenyi Biotec |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Sony Biotechnology |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Full-spectrum technology development simultaneously reshapes cost economics and supply concentration by demanding highly specialized components and advanced manufacturing capabilities. This innovation influences both instrument pricing and the geographic distribution of key suppliers within the flow cytometry market.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing structures in flow cytometry. Hybrid pricing models combine upfront instrument purchase with recurring reagent subscriptions or per-test fees. Price differentiation stems from regulatory compliance certifications like EU MDR validation and the level of after-sales service provided for complex systems. Pricing pressure stems from the high initial capital expenditure for advanced cytometers, particularly impacting smaller research laboratories. Large pharmaceutical manufacturers exhibit the least price sensitivity, prioritizing validated, integrated solutions.
Supply Chain Analysis
Direct sales channels characterize instrument distribution, while specialized distributors manage reagent and consumable supply for broader market reach. Geographic supply concentration for critical components, such as specialized optics and laser modules, primarily lies within the United States, Germany, and Japan. Raw material dependencies include fluorescent dyes, monoclonal antibodies for cell labeling, and high-purity chemical reagents. A structural supply chain risk is single-source vulnerability for proprietary full-spectrum detection components. Regulatory restrictions, such as varying import/export requirements for biological reagents, also complicate cross-border logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flow cytometry market presents a late-cycle quality story, driven by a demand-shift toward premium, high-parameter systems for complex research and clinical diagnostics.
For Market Incumbents: Deploy integrated instrument-reagent platforms to capture recurring revenue and simplify user workflows in clinical settings. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks and control intellectual property. This strategy addresses the threat from agile technology innovators and safeguards market share. Invest in automation and bioinformatics integration to reduce operational bottlenecks for end-users.
For New Entrants and Emerging Players: China's NMPA local approval pathways open a window for specialized domestic instrument and reagent manufacturers. Target underpenetrated clinical markets in emerging economies like Brazil and India with miniaturized, cost-effective point-of-care solutions. A compelling go-to-market angle involves offering user-friendly software for high-dimensional data analysis, addressing a critical operational bottleneck for many labs.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized reagent manufacturers and software solution providers with strong intellectual property in data analysis. The long-term viability of the market is anchored in sustained demand for precision diagnostics and cell therapy quality control. Target niche technology innovators in full-spectrum cytometry or advanced bioinformatics for strategic acquisitions. Successful clinical adoption of new high-parameter diagnostic panels serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Automated cell sorter with integrated software | Enhances throughput and reduces manual intervention for high-volume research and clinical applications. |
| Regulatory Approval Pathway: Pursue CE marking for new diagnostic assays under MDR | Secures market access and establishes clinical credibility for advanced diagnostic solutions in Europe. |
| Strategic Partnership: Collaborate with bioinformatics firms for data analysis solutions | Addresses end-user challenges in interpreting complex, high-dimensional flow cytometry data. |
| Geographic Expansion: Establish local manufacturing and service hubs in China | Navigates stringent NMPA regulations and captures growing demand in a key life sciences market. |
| Platform Integration: Develop closed-system bundles for clinical diagnostic laboratories | Ensures workflow standardization and improves reproducibility, critical for regulatory compliance and patient outcomes. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to ensure a comprehensive market understanding. Primary data involved discussions with flow cytometry core lab managers, R&D scientists at pharmaceutical manufacturers, clinical pathologists, and regulatory affairs specialists. Secondary validation drew from public company SEC filings, academic research databases, regulatory body guidelines from FDA, EMA, and NMPA, and industry association reports. Both bottom-up market sizing and top-down validation approaches were employed.
The segment-weighting approach was applied to construct the market forecast across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory cluster, alongside the instrument installed base. Compound annual growth rates were derived from historical growth trends, expert projections, and anticipated new product introductions. Key forecast inputs included government funding for life sciences infrastructure and the incidence rates of target diseases like cancer and autoimmune disorders.
Revisions become necessary when significant shifts in regulatory frameworks, major technological breakthroughs, or unforeseen geopolitical events materialize. Forecasts reflect assumptions regarding market dynamics and technological adoption over the projection horizon. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Electroretinogram Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Stem Cell Characterization Kits Market
Medical Diagnostics
Cellular Pathology Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Global HLA Typing for Transplant Market