
 North America Circulating Tumor Cells (CTC) Liquid Biopsy Market | 2026-2036
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market Analytics
Project finance for clinical diagnostic platforms is narrowing the competitive field to well-capitalized developers. QIAGEN leverages its molecular diagnostics infrastructure to sustain assay development across multiple cancer indications. Bio-Rad Laboratories anchors its position through analytical instrumentation that supports downstream CTC characterization workflows. Epic Sciences differentiates via proprietary enumeration platforms that occupy specialized niches in metastatic monitoring.
Circulating Tumor Cells (CTC) Liquid Biopsy isolates rare epithelial cells shed from solid tumors into peripheral blood, typically achieving capture sensitivity at concentrations below one cell per milliliter through microfluidic or immunomagnetic separation. The primary commercial purpose centers on non-invasive cancer detection, prognosis monitoring, and treatment assessment without repeated tissue biopsy. CTC Enrichment technologies currently lead product type revenue due to their position as the obligatory first step in all downstream analytical workflows. Diagnostic Kits directed at hospitals represent the fastest-expanding end user channel as health systems integrate liquid biopsy into standard oncology protocols. Next Generation Sequencing applications in personalized medicine command premium positioning within the technology matrix.
FDA oversight of companion diagnostics and Clinical Laboratory Improvement Amendments standards shape product development pathways and commercial access for CTC liquid biopsy assays in the United States. Health Canada regulates equivalent in vitro diagnostic devices through its Medical Devices Bureau, creating parallel compliance requirements for cross-border market participants. Stakeholders must monitor evolving reimbursement determinations from the Centers for Medicare and Medicaid Services, as coverage decisions for liquid biopsy codes will determine adoption velocity across hospital networks and independent diagnostic laboratories.
Market Dynamics
FDA companion diagnostic guidance is compressing development timelines while academic medical centers in California and Massachusetts expand liquid biopsy programs for real-time treatment assessment. This regulatory acceleration is concentrating investment among well-capitalized assay developers capable of navigating parallel Clinical Laboratory Improvement Amendments compliance.
Growth Catalysts
- Microfluidic enrichment platforms:Capture sensitivity below one cell per milliliter enables earlier metastatic detection in solid tumors. Hospitals in Texas and Florida are prioritizing these systems for oncology protocol integration.
- Centers for Medicare and Medicaid Services reimbursement determinations:Emerging coverage codes for liquid biopsy procedures are accelerating hospital procurement cycles. Independent diagnostic laboratories in Illinois are scaling capacity in anticipation.
- Next Generation Sequencing convergence:Personalized medicine applications command premium positioning as oncologists demand comprehensive genomic profiling from single blood draws. Academic medical centers in New York are leading adoption.
Market Restraints
- Antibody-dependent capture limitations:Epithelial cell heterogeneity creates false-negative rates in mesenchymal-transitioned tumors. Alternative protein biomarker approaches face validation bottlenecks.
- California and Massachusetts supply concentration:Reagent manufacturing and analytical instrumentation production cluster in these coastal corridors. Disruption risks from logistics constraints or talent competition elevate operational vulnerability.
- Health Canada parallel compliance requirements:Cross-border market participants face duplicated quality management system audits and medical device licensing timelines. Smaller developers lack resources for simultaneous FDA and Health Canada submissions.
Strategic Opportunities
- Texas and Florida hospital network expansion:Underpenetrated oncology departments in Sun Belt states lack integrated liquid biopsy workflows. Regional health systems are soliciting turnkey platform partnerships.
- Immunomagnetic-microfluidic hybrid architectures:Convergent capture technologies combine antibody specificity with size-based separation efficiency. Platform developers are filing provisional patents in this white space.
- IRA advanced manufacturing tax credits:Domestic production incentives for diagnostic reagents are reshaping facility location decisions. Ohio and North Carolina are attracting contract manufacturing investments.
Industry Challenges
- Multi-site analytical validation complexity:Reproducibility across hospital laboratories requires standardized pre-analytical handling protocols. Variability in sample transport conditions degrades cell viability metrics.
- ISO 15189 medical laboratory accreditation timelines:Independent diagnostic facilities face 12-18 month certification cycles before CMS reimbursement eligibility. Staff competency documentation for rare cell enumeration consumes disproportionate administrative bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Circulating Tumor Cells (CTC) Liquid Biopsy Market |
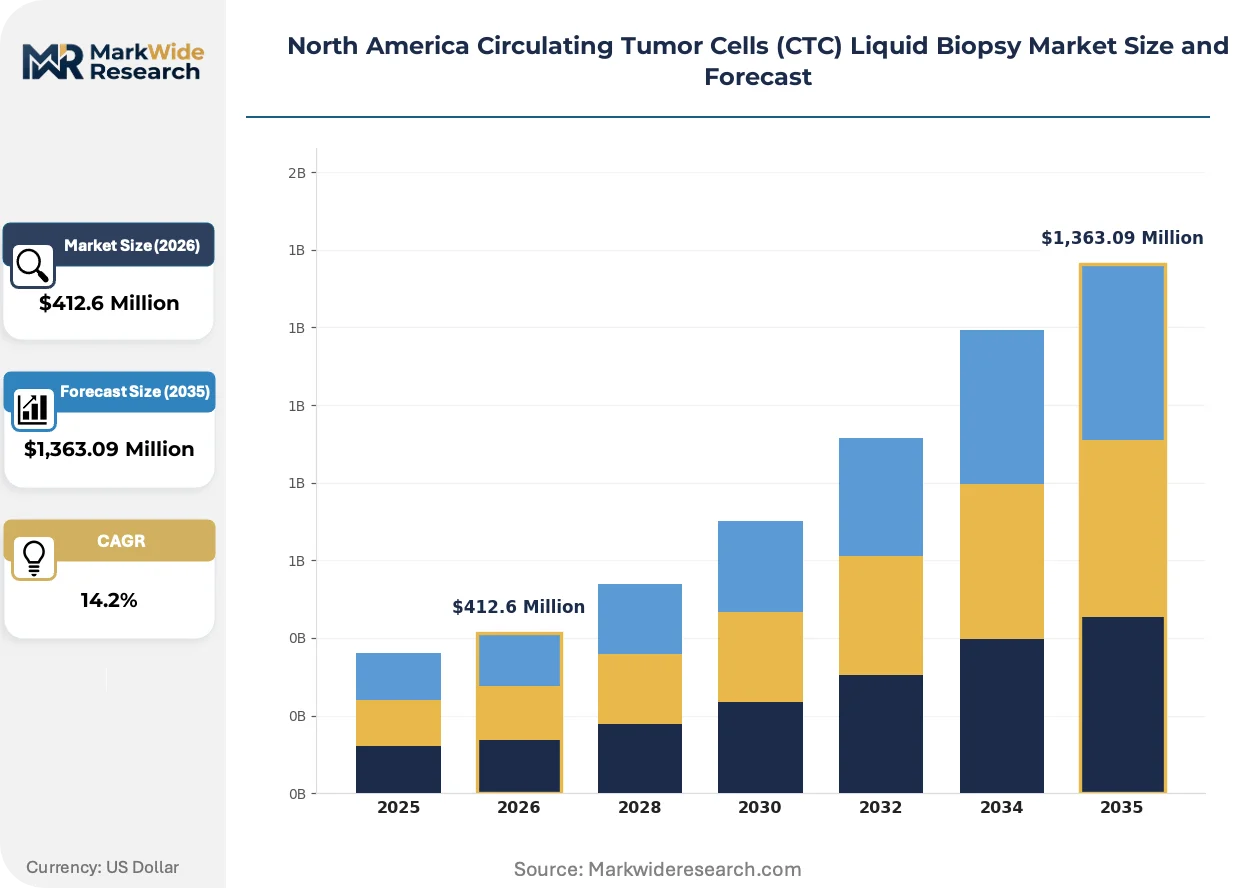
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CTC Enrichment, CTC Analysis, Diagnostic Kits, Research Tools End User: Academic Institutions, Hospitals, Diagnostic Labs, Research Organizations Technology: Microfluidics, Immunocapture, PCR, Next Generation Sequencing Application: Cancer Detection, Prognosis Monitoring, Treatment Assessment, Personalized Medicine |
| Companies Covered | QIAGEN, Miltenyi Biotec, Bio-Techne Corporation, Biocept, Inc., Bio-Rad Laboratories, Inc., Fluxion Biosciences, Inc., Epic Sciences, Greiner Bio-One International GmbH, Ikonisys, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market Evolving Landscape
Platform architectures are converging toward automated sample-to-answer workflows that compress turnaround times from days to hours. This operational compression is reshaping competitive differentiation around pre-analytical standardization rather than capture chemistry alone.
Microfluidic chip designs are hybridizing immunocapture surfaces with inertial focusing channels to achieve simultaneous epithelial and mesenchymal cell recovery. Academic medical centers in Pennsylvania are piloting these dual-mode platforms for longitudinal monitoring of therapy-resistant clones. The structural consequence is compressing the addressable market for single-mechanism enrichment devices.
FDA draft guidance on tumor-informed minimal residual disease assays is clarifying analytical validation requirements for circulating tumor DNA companion diagnostics. This regulatory specificity is accelerating IND-enabling study designs among developers with existing CTC infrastructure. The guidance most directly affects sponsors pursuing simultaneous solid and liquid biopsy approval pathways.
Hospital procurement committees are unbundling instrument placement from reagent supply agreements, favoring capital purchase models over legacy lease-tie arrangements. Independent diagnostic laboratories in Arizona are leveraging this shift to negotiate multi-vendor platform access. This behavioral change is most visible in community oncology practices seeking flexibility across competing assay menus.
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market Segmentation
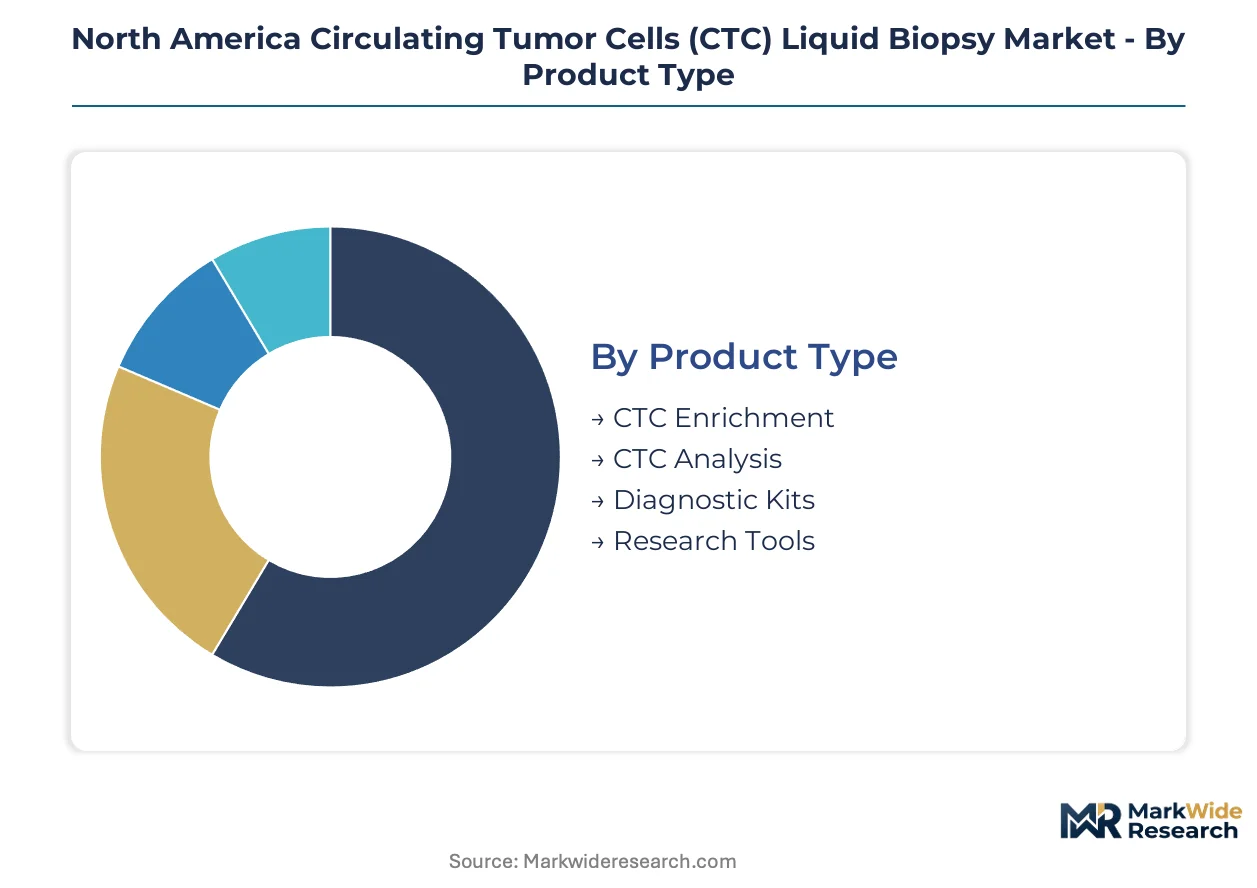
Segmentation in the North America CTC Liquid Biopsy Market reveals distinct technology readiness tiers and divergent customer procurement patterns. Product architecture choices determine downstream analytical capabilities, while end-user sophistication dictates platform complexity requirements.
Product Type:
Mature enrichment technologies anchor current revenue, while emerging assay formats reshape competitive positioning.
- CTC Enrichment:Microfluidic and immunomagnetic separation technologies achieve capture sensitivity below one cell per milliliter. Hospital procurement committees in Texas and Florida prioritize these systems for oncology protocol standardization due to their position as the obligatory first step in all downstream workflows.
- Diagnostic Kits:Pre-configured reagent sets for specific cancer indications enable rapid deployment without extensive in-house development. Health systems in California and Massachusetts biotech corridors are scaling kit-based workflows to compress validation timelines and accelerate clinical utility demonstration.
- CTC Analysis:Downstream characterization platforms enumerate and profile captured cells for phenotypic and genomic assessment.
- Research Tools:Investigational-grade reagents and instrumentation support exploratory studies in academic settings.
CTC Enrichment handles the majority of throughput; Diagnostic Kits are climbing the fastest on share.
End User:
Customer sophistication spans from basic research through regulated clinical diagnostics, with reimbursement eligibility determining access tier.
- Hospitals:Integrated health systems demand sample-to-answer automation with CLIA-compliant quality management. Academic medical centers in New York and Pennsylvania are expanding liquid biopsy programs for real-time treatment assessment, driving premium platform placements.
- Diagnostic Labs:Independent facilities in Illinois and Arizona are scaling capacity in anticipation of CMS reimbursement determinations for liquid biopsy procedure codes.
- Academic Institutions:Research-focused centers prioritize analytical flexibility over regulatory certification.
- Research Organizations:Contract research entities support pharmaceutical development programs with specialized enumeration services.
Hospitals dominate current instrument placements; Diagnostic Labs show the steepest expansion trajectory as reimbursement clarity emerges.
Technology:
Platform architectures range from established molecular methods through convergent capture-and-sequence workflows.
- Microfluidics:Size-based and inertial focusing channels enable label-free cell separation with minimal sample manipulation. Texas hospital networks are prioritizing microfluidic platforms for their compatibility with automated pre-analytical handling.
- Next Generation Sequencing:Comprehensive genomic profiling from single blood draws commands premium positioning in personalized medicine applications. Academic medical centers in California are leading adoption for therapy-resistant clone monitoring.
- Immunocapture:Antibody-dependent surface binding achieves high specificity for epithelial markers.
- PCR:Amplification-based detection supports targeted mutation analysis with established regulatory pathways.
Microfluidics carries the highest installed base; Next Generation Sequencing is gaining share fastest as oncologists demand comprehensive profiling.
Application:
Clinical utility progresses from detection through longitudinal monitoring, with reimbursement tailwinds favoring established indications.
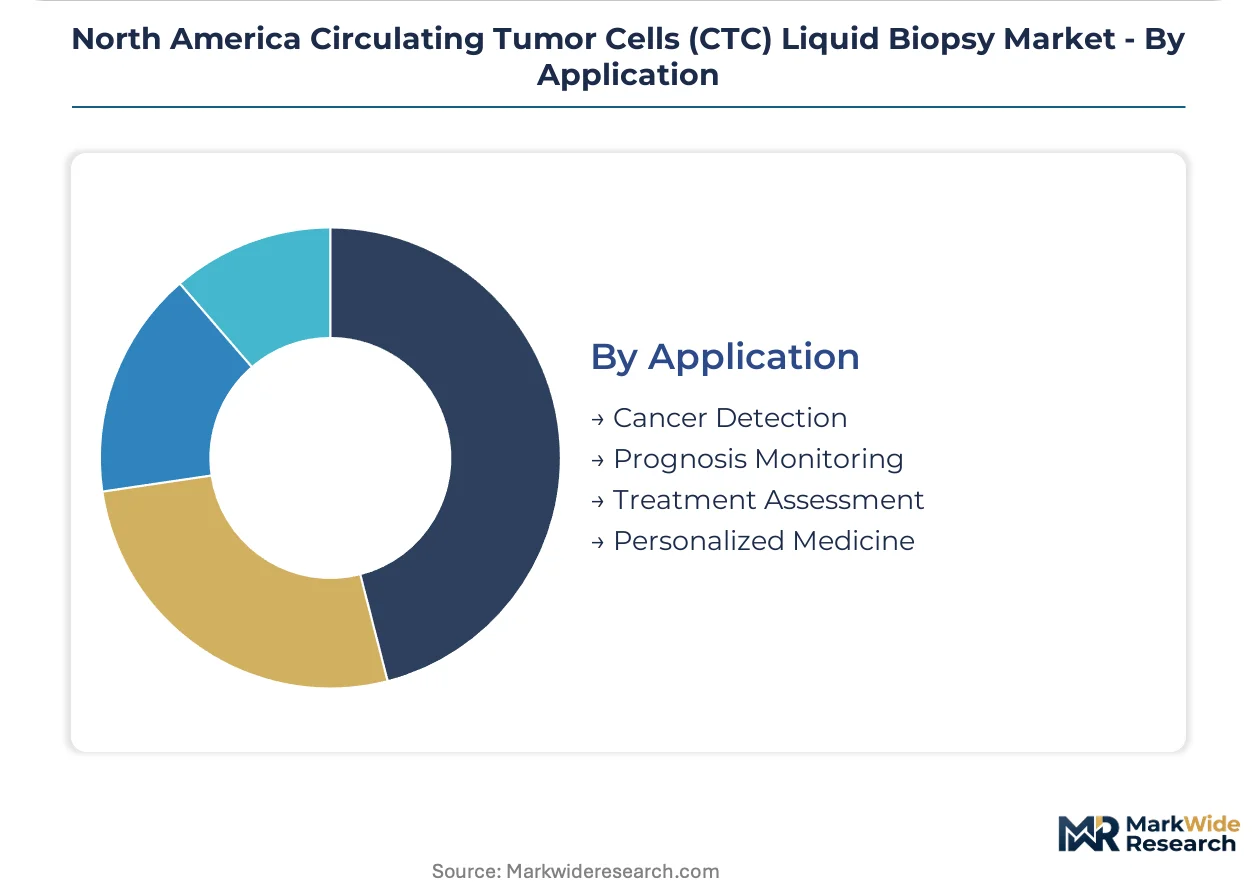
- Treatment Assessment:Real-time therapy response monitoring enables adaptive clinical decision-making without repeated tissue biopsy. Massachusetts academic medical centers are integrating these workflows into standard oncology protocols.
- Personalized Medicine:Genomic profiling from liquid biopsy informs targeted therapy selection and clinical trial matching. New York health systems are scaling these applications for comprehensive cancer center accreditation.
- Cancer Detection:Screening applications in high-risk populations remain investigational with evolving regulatory pathways.
- Prognosis Monitoring:Longitudinal CTC enumeration tracks disease trajectory and residual disease burden.
Treatment Assessment manages the highest procedure volume; Personalized Medicine shows the most rapid share accumulation as companion diagnostic linkages strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA companion diagnostic guidance and IRA advanced manufacturing tax credits are accelerating platform deployment across North American health systems. Academic medical centers and independent diagnostic laboratories are scaling liquid biopsy infrastructure in anticipation of CMS reimbursement determinations.
United States
California and Massachusetts biotech corridors concentrate reagent manufacturing and analytical instrumentation production. FDA oversight of companion diagnostics and CLIA standards shapes product development pathways for assay developers. Texas and Florida hospital networks are prioritizing microfluidic enrichment systems for oncology protocol integration.
Canada
Health Canada regulates in vitro diagnostic devices through its Medical Devices Bureau, creating parallel compliance requirements for cross-border market participants. The country's national pharmaceutical regulator enforces quality management system audits that duplicate FDA timelines. Ontario and Quebec academic medical centers are piloting dual-mode capture platforms for longitudinal therapy monitoring.
Mexico
Mexico City Metro health systems are expanding molecular diagnostics capacity through public-private partnerships with US-based platform developers. The country's federal health regulator oversees medical device registration under COFEPRIS guidelines. Northern Border States manufacturing facilities are attracting contract reagent production investments driven by nearshoring incentives.
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Well-capitalized developers with molecular diagnostics infrastructure anchor the top tier, while analytical instrumentation specialists occupy adjacent positions. The competitive field narrows through project finance constraints that favor established assay developers. Strategic moves concentrate on immunomagnetic-microfluidic hybrid patent filings and turnkey platform partnerships with underpenetrated hospital networks.
Within the infrastructure-leveraged tier, QIAGEN and Bio-Rad Laboratories exemplify channel-controlling archetypes that sustain assay development across multiple cancer indications. Epic Sciences occupies a specialized position in metastatic monitoring through proprietary enumeration platforms. These three companies represent the dominant competitive anchors in a field where regulatory navigation capabilities determine market access velocity.
| Leading Market Players |
|---|
| QIAGEN |
| Miltenyi Biotec |
| Bio-Techne Corporation |
| Biocept, Inc. |
| Bio-Rad Laboratories, Inc. |
| Fluxion Biosciences, Inc. |
| Epic Sciences |
| Greiner Bio-One International GmbH |
| Ikonisys, Inc. |
| Others |
Value Network & Pricing Analysis
Port of Long Beach freight corridors transmit cost volatility from California reagent manufacturing clusters to Texas and Florida hospital networks, compressing margins on standard-grade enrichment platforms while amplifying price premiums for CLIA-validated diagnostic kits.
Pricing Analysis
Certification level (FDA-grade/CLIA-validated/Research-use-only) creates the primary spread between platform tiers, with hospital procurement committees in academic medical centers absorbing 40-60% premiums for turnkey sample-to-answer workflows versus kit-only configurations. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and analytical training depth rather than capture chemistry alone. Cost compression in the standard tier is intensifying because independent diagnostic laboratories in Illinois and Arizona are consolidating purchasing through GPO contracts. Research institutions exhibit highest price sensitivity due to discretionary grant funding cycles, while integrated health systems demonstrate lowest sensitivity where reimbursement codes provide coverage certainty.
Supply Chain Analysis
Upstream microfluidic chip fabrication feeds from Taiwan semiconductor foundries and German precision glass manufacturers, with immunomagnetic bead production anchored in Massachusetts and North Carolina contract manufacturing facilities. Reagent formulation draws from California biotech corridors for antibody development and Texas chemical processing for buffer systems. Single-source vulnerability concentrates in Taiwan for silicon-based microfluidic substrates, where geopolitical logistics chokepoints threaten platform production continuity. Distribution runs through specialized cold-chain logistics providers serving hospital networks and independent diagnostic laboratories, with regional warehousing in Ohio and Georgia compressing delivery windows for time-sensitive biological reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across capture technologies and end-user sophistication tiers generates actionable entry points, as CMS reimbursement determinations for liquid biopsy procedure codes splinter demand into validated clinical versus research-grade purchasing streams.
For Market Incumbents: Build regulatory moats through simultaneous FDA companion diagnostic and Health Canada Medical Devices Bureau submissions, compressing approval timelines for cross-border market access. Anchor defensive positioning by acquiring microfluidic chip design capabilities in Taiwan or Germany, neutralizing single-source substrate vulnerability. Deepen channel control through multi-year reagent supply agreements with Texas and Florida hospital networks, locking out emerging platform developers before reimbursement clarity fully materializes.
For New Entrants and Emerging Players: Build out immunomagnetic-microfluidic hybrid architectures in the white space between established single-mechanism enrichment devices, filing provisional patents ahead of incumbent R&D cycles. Penetrate Sun Belt state oncology departments in Georgia and North Carolina, where underpenetrated hospital networks actively solicit turnkey platform partnerships without legacy vendor entanglements. Lead go-to-market with outcome-based pricing tied to CTC enumeration accuracy metrics, differentiating against incumbent instrument-placement models.
For Investors and Strategic Acquirers: CLIA-certified independent diagnostic laboratories with established CMS reimbursement pathways represent the most defensible acquisition archetype for medium-term value capture. Long-term viability over the coming decade hinges on convergence with minimal residual disease testing workflows and companion diagnostic approval pathways. Monitor FDA draft guidance finalization on tumor-informed liquid biopsy assays as the critical inflection signal for platform valuation repricing across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification | Unlocks CMS reimbursement eligibility for independent diagnostic facilities in Illinois and Arizona. |
| Immunomagnetic-Microfluidic Patent Filing | Secures intellectual property position in convergent capture technology white space before incumbent R&D deployment. |
| Hospital System Partnership | Integrates sample-to-answer platforms into standard oncology protocols at Massachusetts academic medical centers. |
| Reimbursement Strategy Development | Aligns assay menu design with emerging CMS coverage codes for liquid biopsy procedures. |
| Dual-Mode Platform Pilot | Validates simultaneous epithelial and mesenchymal cell recovery at Pennsylvania academic medical centers. |
Research Methodology
A standing panel of molecular diagnostics executives, hospital procurement managers, CLIA laboratory directors, and regulatory affairs specialists provided ongoing calibration across primary interview cycles, with secondary validation drawing from FDA 510(k) filings, CMS Medicare reimbursement databases, Clinical Laboratory Improvement Amendments inspection records, and Health Canada Medical Devices Bureau licensing timelines. Bottom-up triangulation across instrument placement data and reagent consumption patterns converged with top-down market sizing from health system capital expenditure disclosures and GPO contract repositories.
Scenario-bracketing framed analytical sensitivity across regulatory approval velocity, reimbursement code adoption curves, and platform technology substitution risks over the projection horizon. Segmentation dimensions modeled include product architecture (enrichment versus analysis versus kits), end-user sophistication (hospital versus diagnostic lab versus academic), technology convergence (microfluidic, immunocapture, NGS integration), and application progression (detection, prognosis, treatment assessment, personalized medicine). CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in companion diagnostic categories, with inputs from academic medical center expansion timelines and IRA manufacturing tax credit utilization rates.
Practitioners should monitor FDA guidance finalization schedules, CMS national coverage determination timelines, and Taiwan semiconductor export control developments for early signals requiring forecast revision. Cross-checking against published hospital capital expenditure plans and independent diagnostic laboratory accreditation backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Stem Cell Panel Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market