
 Global Hydrophobic Interaction Chromatography Market | 2026-2036
Global Hydrophobic Interaction Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrophobic Interaction Chromatography Market Foresight
Contract research organizations are repositioning their purification service portfolios toward high-value biologics, reshaping resin procurement patterns across the value chain. Thermo Fisher Scientific dominates the consumables segment through its chromatography media platform and extensive distribution infrastructure. Bio-Rad Laboratories differentiates via specialized HIC resins engineered for aggregate removal in antibody downstream processing. Sartorius AG leverages its integrated filtration-chromatography workflow solutions to anchor recurring revenue from biopharmaceutical clients.
Hydrophobic interaction chromatography separates biomolecules based on differential affinity for hydrophobic ligands under high-salt mobile phases, typically employing phenyl, butyl, or octyl ligands immobilized on porous polymer or agarose matrices at 10–100 µm particle sizes. The technique preserves native protein conformation during purification, making it indispensable for aggregate clearance and polishing steps in monoclonal antibody production. Continuous chromatography systems are capturing margin pools as biopharmaceutical manufacturers pursue productivity gains, while batch chromatography remains the volume backbone due to lower capital barriers and operational familiarity. Resins command the largest product value share owing to recurring replacement cycles, whereas detection kits represent a faster-growing niche driven by real-time process analytics integration.
The FDA enforces current Good Manufacturing Practice standards that mandate validated impurity clearance, directly elevating HIC specification requirements for commercial biologics. EMA's MDR framework and REACH chemical safety protocols in Europe impose additional material qualification burdens on resin suppliers seeking market access. China's NMPA has tightened biologics manufacturing guidelines under its revised drug administration law, compelling domestic producers to adopt pharmaceutical-grade chromatography media. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate compliance-driven product specification shifts and qualification timeline extensions.
Market Dynamics
Continuous chromatography systems are displacing batch configurations as the dominant operational paradigm, forcing resin suppliers to reengineer media specifications for multicolumn cycling while biopharmaceutical manufacturers absorb higher upfront capital for productivity gains.
Growth Catalysts
- Monoclonal antibody pipeline expansion:FDA's accelerated approval pathways for oncology biologics are compressing development timelines and multiplying purification campaigns requiring HIC polishing steps.
- EMA quality-by-design mandates:The MDR framework now requires validated impurity clearance documentation, elevating HIC from optional to mandatory in commercial biologics workflows.
- China's biologics manufacturing consolidation:NMPA's revised drug administration law compels domestic producers to adopt pharmaceutical-grade chromatography media, creating captive demand in Shanghai and Suzhou clusters.
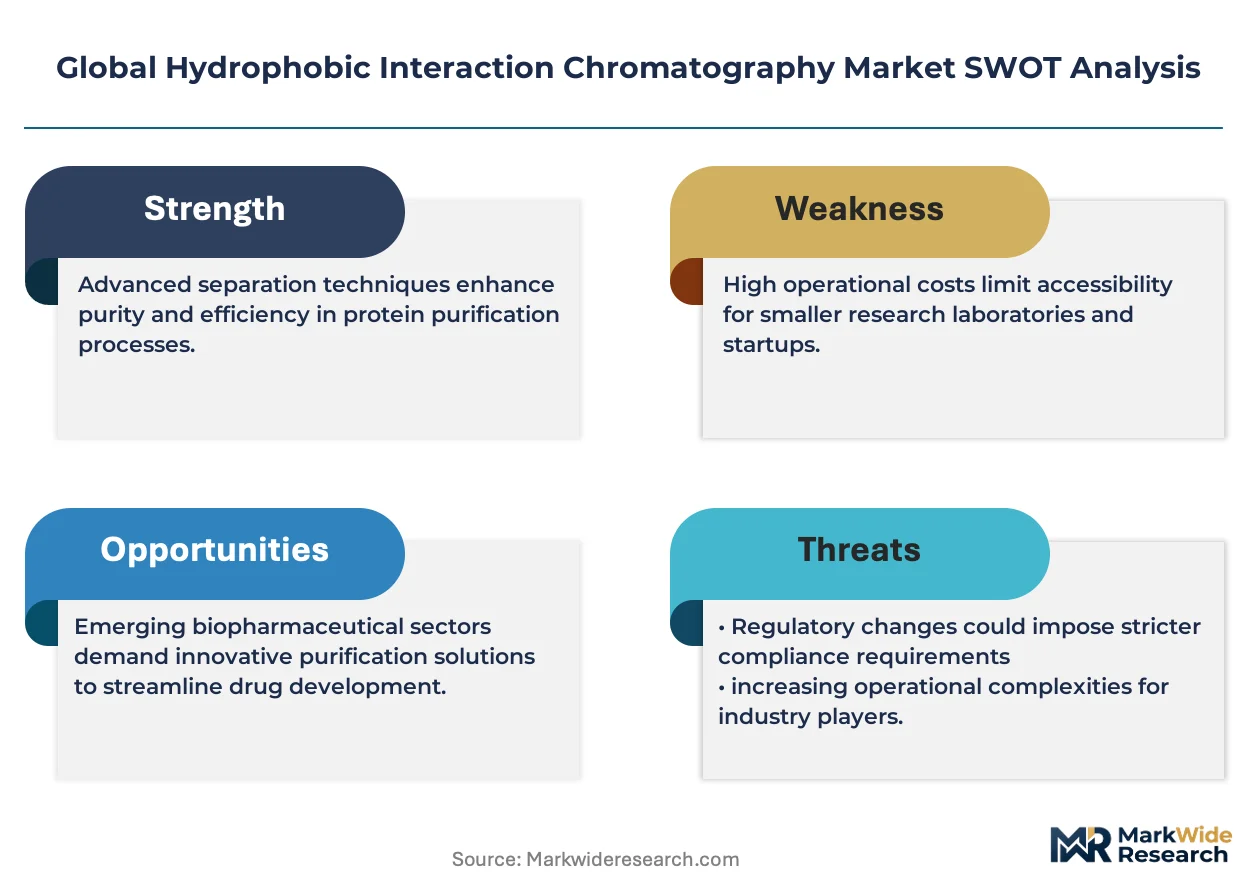
Market Restraints
- Protein A resin cost volatility:Agarose base matrix supply concentrates in Scandinavian coastal harvesting operations, exposing HIC resin pricing to marine raw material fluctuations.
- REACH chemical safety protocols:ECHA's substance authorization requirements extend resin qualification timelines by 12-18 months for European market entry.
- Membrane chromatography substitution:Single-use membrane adsorbers are capturing polishing-step volume in clinical-phase production, constraining HIC resin attach rates in early-stage biologics.
Strategic Opportunities
- India's CDMO capacity buildout:CDSCO's biologics manufacturing guidelines are attracting foreign investment into Hyderabad and Bengaluru purification facilities requiring resin supply partnerships.
- Gene therapy vector purification:AAV and lentiviral vector manufacturing is emerging as a greenfield application with distinct hydrophobic selectivity requirements versus antibody workflows.
- Real-time analytics integration:Process Analytical Technology initiatives are creating demand for HIC detection kits that interface with distributed control systems.
Industry Challenges
- Chromatography method development expertise:Salt gradient optimization for aggregate removal requires specialized analytical chemists in short supply across contract manufacturing organizations.
- Legacy batch system retrofitting:Continuous chromatography skid installation demands facility reconfiguration and validation protocol redevelopment that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrophobic Interaction Chromatography Market |
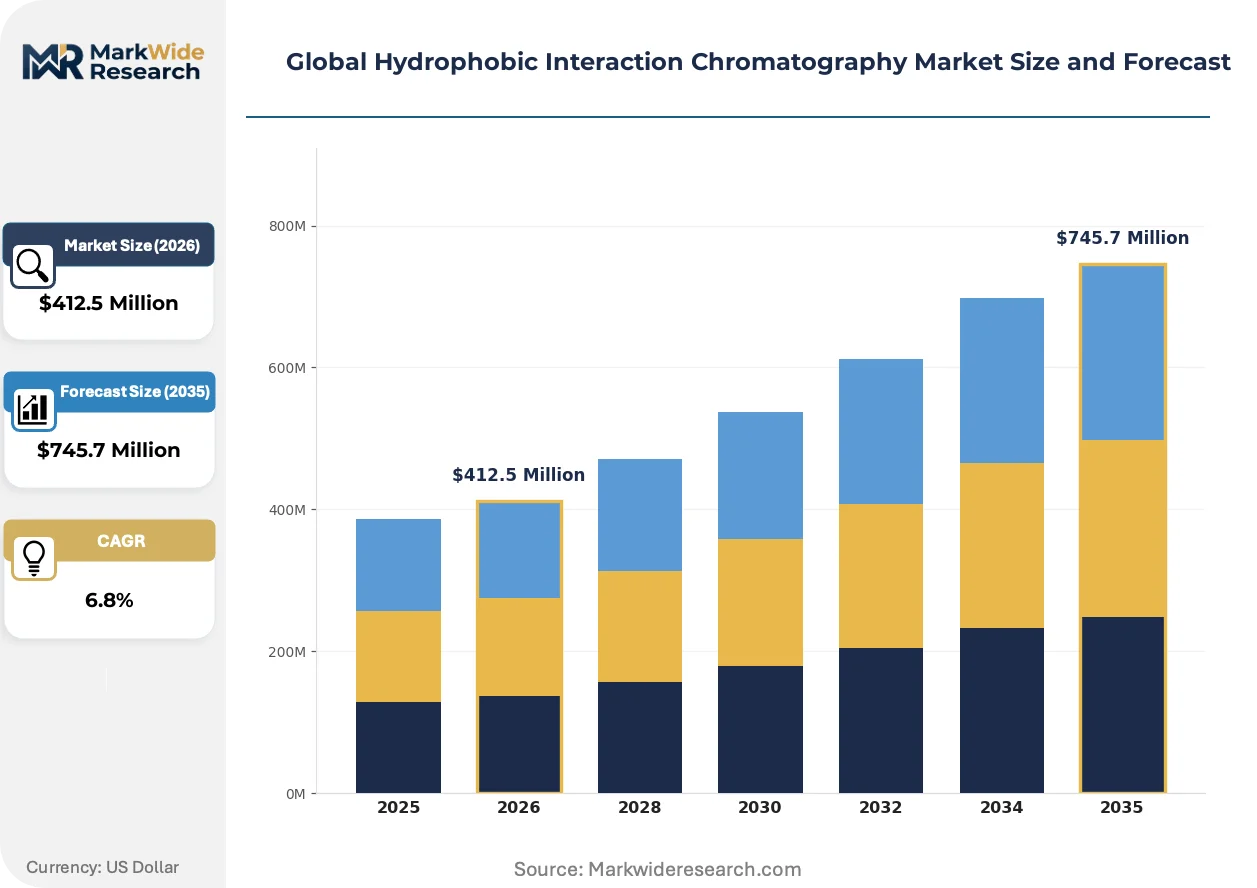
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resins, Columns, Buffers, Detection Kits Application: Protein Purification, Enzyme Isolation, Vaccine Production, Peptide Separation End User: Biopharmaceutical Manufacturers, Research Laboratories, Contract Research Organizations, Academic Institutes Technology: Batch Chromatography, Continuous Chromatography, Simulated Moving Bed, Multimodal Chromatography |
| Companies Covered | Bio-Rad Laboratories, Inc., Thermo Fisher Scientific Inc., Sartorius AG, GE Healthcare, Tosoh Bioscience, Merck KGaA, Waters Corporation, Agilent Technologies, Inc., Bruker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrophobic Interaction Chromatography Market Shifts & Advancements
Process intensification imperatives are compressing purification train footprints while elevating resin performance specifications, reshaping how biopharmaceutical manufacturers evaluate media suppliers.
Multicolumn countercurrent chromatography skids are modularizing downstream processing architectures by enabling parallel loading and elution cycles that boost resin utilization rates. Biologics manufacturers in Germany and Massachusetts are piloting these configurations for high-titer antibody campaigns. The technology is modularizing capital deployment decisions, allowing facilities to scale throughput without proportional cleanroom expansion.
REACH chemical safety protocols are mandating full substance disclosure for ligand chemistries and base matrices, compelling resin suppliers to requalify legacy product lines. EMA's MDR framework extends these requirements to device-classified chromatography systems. European biopharmaceutical manufacturers are responding by consolidating supplier bases to partners with completed regulatory dossiers.
Service unbundling is fragmenting traditional resin-supply relationships as biopharmaceutical manufacturers separate media procurement from method development consulting. Contract research organizations in South Korea and Singapore are capturing method optimization work that resin vendors previously bundled. This pattern concentrates in markets where CDMOs operate at arm's length from originator companies.
Global Hydrophobic Interaction Chromatography Market Segmentation
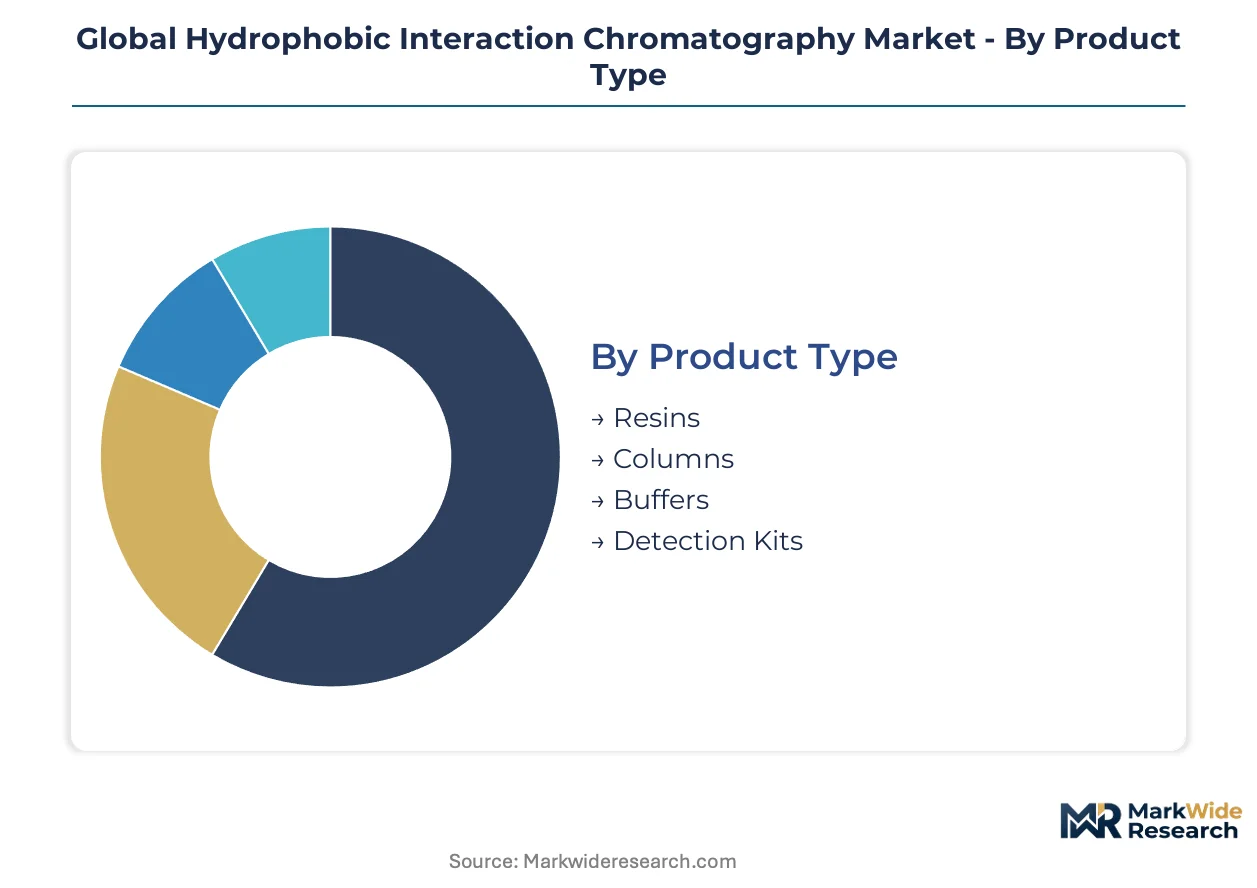
HIC procurement decisions hinge on workflow integration complexity and regulatory validation requirements. Biopharmaceutical manufacturers evaluate segments through total cost of ownership lenses spanning consumable replacement cycles, equipment depreciation, and method transfer overhead.
Product Type:
Capital allocation patterns separate high-frequency consumables from durable hardware investments, with procurement teams weighting inventory carrying costs against qualification timeline risks.
- Resins:Phenyl, butyl, and octyl ligands immobilized on agarose or polymer matrices constitute the recurring revenue backbone. Biopharmaceutical manufacturers in Germany and Massachusetts maintain qualified supplier rosters to mitigate single-source exposure for commercial antibody campaigns.
- Columns:Prepacked formats reduce method development variability and accelerate tech transfer between CMOs and originators. Demand concentrates among CDMOs serving FDA-regulated markets where column-to-column reproducibility documentation is mandatory.
- Buffers:High-salt mobile phase formulations with defined ionic strength and pH specifications support reproducible hydrophobic binding. Academic institutes and research laboratories represent the primary volume for open-format buffer preparation.
- Detection Kits:Real-time analytics modules integrating with distributed control systems enable PAT-compliant process monitoring. These kits are expanding most quickly as EMA quality-by-design mandates elevate in-line detection requirements.
Volume sits with resins; growth tilts toward detection kits.
Application:
Downstream processing complexity varies dramatically by biomolecule class, with aggregate clearance difficulty determining HIC step placement and resin specification intensity.
- Protein Purification:Monoclonal antibody polishing workflows deploy HIC for host cell protein and aggregate removal following Protein A capture. FDA accelerated approval pathways for oncology biologics are multiplying purification campaign frequency.
- Vaccine Production:Recombinant subunit and virus-like particle manufacturing employs HIC for antigen polishing. China's NMPA biologics manufacturing consolidation is driving specification upgrades in Suzhou and Shanghai production clusters.
- Enzyme Isolation:Industrial biocatalyst recovery preserves native conformation through mild elution conditions. Food-grade and diagnostic enzyme producers represent specialized demand pockets with distinct ligand selectivity requirements.
- Peptide Separation:Synthetic and recombinant peptide purification leverages HIC for desalting and aggregate clearance prior to lyophilization. Contract research organizations capture method development work for clinical-phase peptide therapeutics.
Protein purification commands installed base; vaccine production is climbing the fastest.
End User:
Organizational scale and regulatory exposure shape procurement sophistication, with commercial manufacturers demanding extensive supplier qualification dossiers unavailable to research-scale buyers.
- Biopharmaceutical Manufacturers:Integrated originators and CMOs operate under FDA current Good Manufacturing Practice standards requiring validated impurity clearance. These buyers negotiate multi-year resin supply agreements with audit rights and change notification clauses.
- Contract Research Organizations:CDMOs in India and South Korea are repositioning service portfolios toward high-value biologics, fragmenting traditional resin-vendor relationships through unbundled method development procurement.
- Research Laboratories:Discovery-stage groups prioritize flexibility over validation depth, sourcing open-format resins for exploratory purification.
- Academic Institutes:Grant-funded researchers represent price-sensitive volume for basic HIC media, with procurement constrained by institutional purchasing consortium terms.
Biopharmaceutical manufacturers anchor revenue; contract research organizations are gaining share fastest.
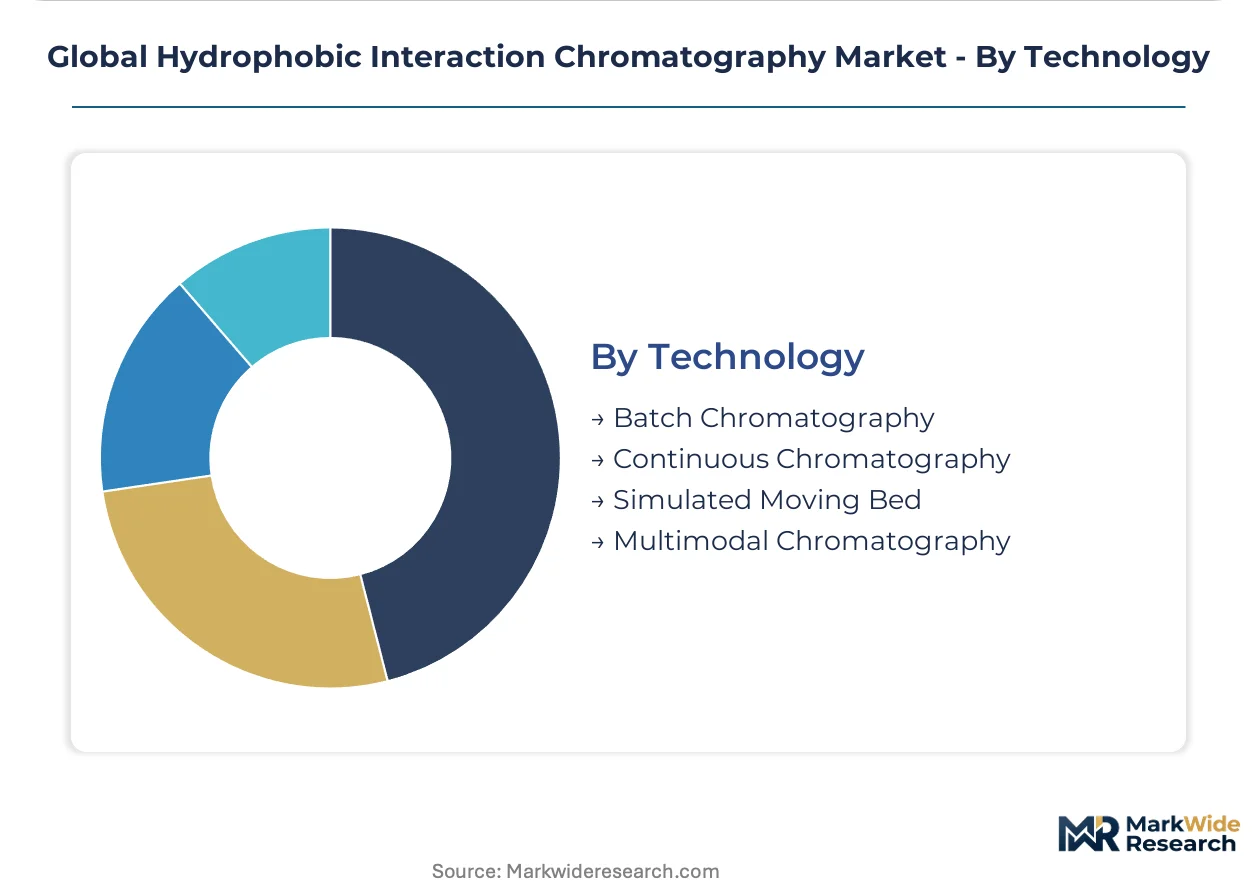
Technology:
Operational paradigm selection determines capital deployment intensity and facility reconfiguration requirements, with productivity gains trading against validation burden and technical risk tolerance.
- Batch Chromatography:Single-column processing remains the volume backbone due to lower capital barriers and extensive operational familiarity. Legacy installations across established biologics facilities constrain migration timelines.
- Continuous Chromatography:Multicolumn countercurrent configurations enable parallel loading and elution cycles that boost resin utilization. German and Massachusetts manufacturers are piloting these systems for high-titer antibody campaigns.
- Simulated Moving Bed:Countercurrent flow simulation through valve switching achieves binary separation efficiency for large-scale industrial applications. Enzyme and peptide producers evaluate SMB for productivity-critical purification steps.
- Multimodal Chromatography:Resins combining hydrophobic and ionic interaction mechanisms reduce purification train footprint through single-step clearance of multiple impurity classes.
Batch chromatography holds installed base; continuous chromatography shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Switzerland, and the United States where resin manufacturing infrastructure serves biopharmaceutical clusters worldwide. Consumption patterns diverge as emerging biologics hubs in China and India expand purification capacity faster than domestic supply development.
United States
FDA accelerated approval pathways for oncology biologics multiply purification campaign frequency at commercial scale. The agency's Process Analytical Technology initiative mandates validated impurity clearance documentation. Massachusetts biopharmaceutical manufacturers pilot multicolumn continuous chromatography systems for high-titer antibody production.
Germany
EMA quality-by-design guidelines and MDR framework elevate HIC from optional to mandatory in commercial biologics workflows. REACH chemical safety protocols extend resin qualification timelines for European market entry. Bavarian biologics manufacturing clusters consolidate supplier rosters to mitigate single-source exposure.
China
NMPA's revised drug administration law compels domestic producers to adopt pharmaceutical-grade chromatography media. The regulator's biologics manufacturing consolidation creates captive demand in Shanghai and Suzhou production clusters. Yangtze River Delta facilities upgrade purification infrastructure to meet export market specifications.
India
CDSCO biologics manufacturing guidelines attract foreign investment into Hyderabad and Bengaluru purification facilities. The country's CDMO capacity buildout fragments traditional resin-vendor relationships through unbundled procurement. Telangana's biologics corridor expands method development service capabilities alongside resin supply partnerships.
Switzerland
Swissmedic enforces pharmaceutical-grade chromatography standards that align with FDA and EMA benchmarks for export-oriented manufacturers. The country's precision chemical sector supplies specialized ligand chemistries to global resin producers. Basel-region biopharmaceutical clusters anchor European demand for high-performance HIC media.
Global Hydrophobic Interaction Chromatography Market Competitive Landscape
Top-tier vendors anchor the premium resin segment, while mid-tier specialists occupy differentiated niches in detection kits and prepacked formats. The vendor base stratifies across three tiers: integrated life science conglomerates with chromatography media platforms, specialized purification technology firms, and regional chemical suppliers serving price-sensitive research markets. Two dominant competitive moves define current positioning: strategic partnerships between resin suppliers and continuous chromatography skid manufacturers, and geographic expansion through qualified distributor networks in emerging biologics hubs.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Bio-Rad Laboratories, Inc. occupy positions exemplifying scale-driven platform strategies, while Sartorius AG represents the integrated workflow solutions archetype. These entities anchor competitive dynamics through recurring revenue models tied to consumable replacement cycles and multi-year supply agreements with audit rights. German and Swiss-origin firms leverage proximity to EMA regulatory processes, while US-based competitors align qualification protocols with FDA accelerated approval pathways.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| GE Healthcare |
| Tosoh Bioscience |
| Merck KGaA |
| Waters Corporation |
| Agilent Technologies, Inc. |
| Bruker |
| Others |
Supply & Pricing Matrix
Family-owned Scandinavian agarose harvesting cooperatives anchor upstream raw material supply, constraining resin pricing discipline through concentrated marine biomass control while contract manufacturers absorb volatility through multi-year offtake agreements with audit rights.
Pricing Analysis
Margin tightening in pharmaceutical-grade resins reflects agarose base matrix scarcity and REACH compliance qualification burdens. Three-tier pricing structure across GMP-certified premium, validated standard, and research-grade economy levels separates biopharmaceutical manufacturers from academic buyers. Cost-down pressure on detection kits accelerates as PAT integration mandates expand real-time analytics procurement. Contract research organizations exhibit highest price sensitivity due to unbundled service margins, while integrated originators prioritize qualification depth over unit cost.
Supply Chain Analysis
Reverse-logistics flows for resin regeneration and solvent recovery are minimal given single-use biopharmaceutical contamination protocols. Supply concentrates in Sweden, Denmark, and coastal Norway for agarose raw material, with Germany and Switzerland hosting ligand chemistry synthesis and final resin formulation. Base matrix production draws from seasonal marine harvesting cycles tethered to North Atlantic kelp populations. Single-source vulnerability concentrates in Scandinavian agarose suppliers exposed to ocean temperature shifts. Distribution runs through qualified distributor networks with temperature-controlled logistics for biopharmaceutical-grade media.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is accelerating into a vertical-integration race, with resin suppliers pursuing backward control over agarose harvesting operations to secure raw material access against marine supply volatility.
For Market Incumbents: Hedge against membrane chromatography substitution by embedding method development consulting into resin supply agreements, locking CDMOs into bundled service relationships. Secure captive agarose supply through coastal harvesting partnerships in Scandinavia, insulating formulation operations from raw material price spikes triggered by ocean ecosystem shifts.
For New Entrants and Emerging Players: Gene therapy vector purification workflows offer a technology-first wedge into underpenetrated AAV manufacturing demand with distinct hydrophobic selectivity requirements versus established antibody markets. Target India's CDSCO-regulated CDMO corridor through Hyderabad and Bengaluru facility partnerships, leveraging unbundled procurement patterns to displace incumbent resin-vendor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized detection kit developers with completed EMA regulatory dossiers in Germany and Switzerland, positioned for PAT mandate acceleration. Long-term viability hinges on continuous chromatography skid compatibility and real-time analytics integration depth. Monitor FDA accelerated approval pathway expansion for oncology biologics as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agarose Harvesting | Secures Scandinavian marine biomass supply against seasonal kelp population volatility. |
| Continuous Chromatography Skid Partnership | Aligns resin specifications with multicolumn cycling demands from German and Massachusetts manufacturers. |
| PAT-Compliant Detection Kit Development | Captures EMA quality-by-design mandate expansion for real-time process analytics. |
| CDMO Method Development Bundling | Counteracts service unbundling trends fragmenting traditional resin supply relationships. |
| Gene Therapy Vector Application Expansion | Opens greenfield AAV and lentiviral purification demand with distinct selectivity requirements. |
Research Methodology
Independent corroboration across resin procurement executives, downstream process engineers, and regulatory affairs specialists at biopharmaceutical manufacturers underwrites the qualitative findings. Primary interviews with CDMO operations directors and academic laboratory managers combined with secondary validation from FDA 510(k) filings, EMA marketing authorization submissions, and REACH substance registration databases. Bottom-up resin volume estimates and top-down biologics purification spending analysis triangulate market sizing.
Rate-of-change decomposition across product type, application, end user, and technology segments structures the analytical framework throughout the forecast period. CAGRs derive from segment-level demand elasticity modeling against monoclonal antibody pipeline expansion and continuous chromatography adoption curves. Industry-specific inputs include Protein A resin replacement cycle frequencies and NMPA biologics manufacturing guideline enforcement timelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory timeline accelerations, disruptive membrane chromatography technology breakthroughs, and marine ecosystem disruptions affecting agarose supply. Forecasts reflect documented assumptions regarding biopharmaceutical capital expenditure continuity and CDMO capacity buildout trajectories. Practitioners should monitor FDA accelerated approval pathway utilization rates and EMA MDR framework enforcement intensity for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
In-Situ Hybridization (ISH) Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Europe Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market