
 Global Histology and Cytology Market | 2026-2036
Global Histology and Cytology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Histology and Cytology Market Foresight
The EU IVDR is repositioning market access requirements for histology and cytology consumables across European diagnostic networks. F. Hoffmann-La Roche Ltd leverages its immunohistochemistry portfolio to sustain laboratory loyalty in high-throughput cancer centers. Abbott Laboratories anchors its position through integrated staining platforms that reduce manual workflow steps. Sysmex Corporation dominates hematology-cytology convergence with automated cell imaging systems that compress diagnostic turnaround.
Histology and cytology encompass the microscopic examination of tissue sections and individual cells, employing formalin-fixed paraffin embedding, microtomy at 3-5 micron thickness, and Papanicolaou staining to enable pathological diagnosis of neoplastic, infectious, and inflammatory conditions. Automated slide scanners with 40x oil-immersion objectives now digitize whole-slide images for remote consultation and AI-assisted pattern recognition. Cancer diagnosis applications command the largest revenue share as precision oncology protocols multiply biomarker-driven testing requirements. Research institutes represent the fastest-growing end-user segment as translational medicine programs expand tissue-based drug target validation. Deployment through semi-automated workflows captures expanding mid-volume laboratories seeking throughput gains without full capital commitment.
FDA premarket notification pathways and EPA chemical safety reviews shape reagent formulation standards and instrument validation protocols in the United States. EMA companion diagnostic guidelines and EU IVDR technical documentation requirements determine market entry sequencing for European clinical laboratories. WHO cancer control initiatives and national screening mandates in Japan and South Korea direct public procurement volumes for cervical cytology and colorectal histology services. Stakeholders must weigh regulatory divergence against platform standardization as digital pathology interoperability becomes a procurement criterion.
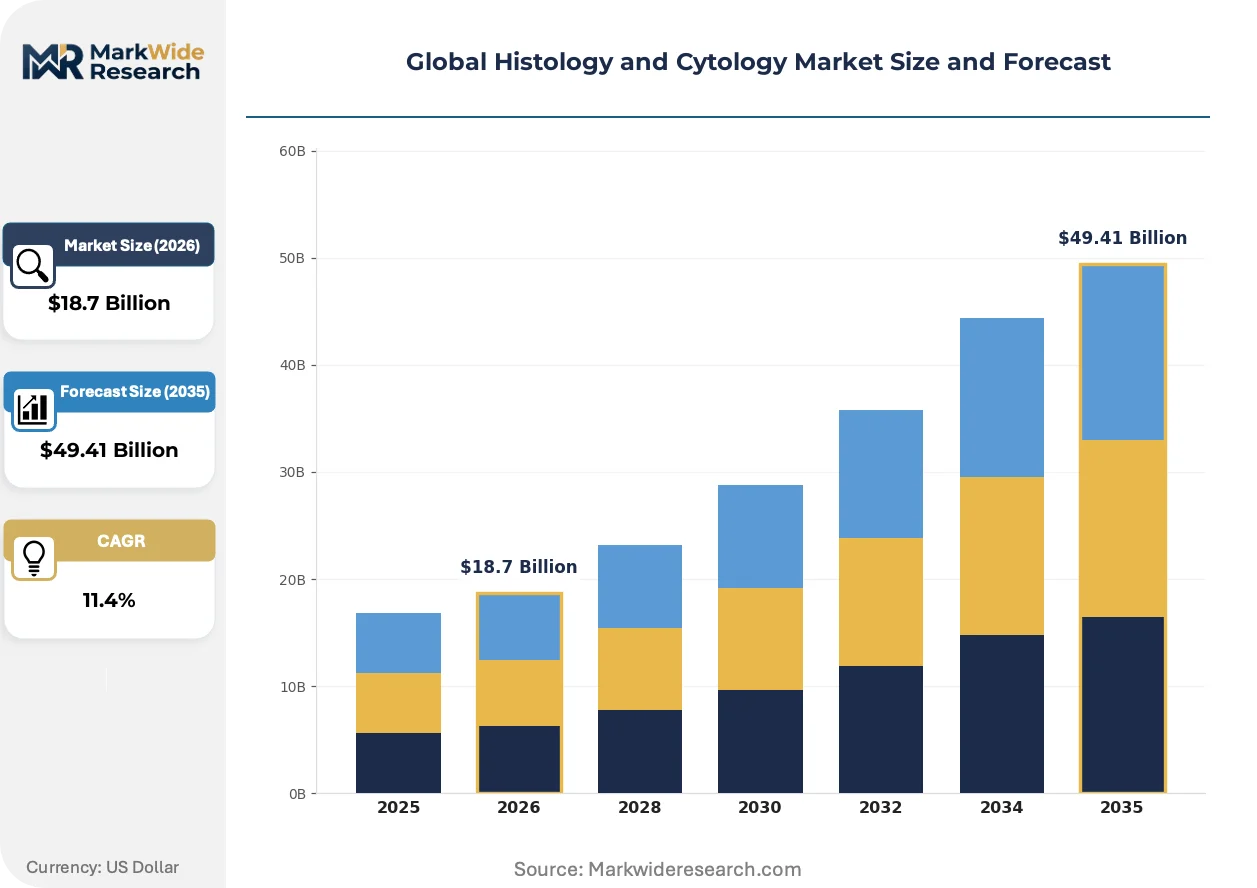
Market Dynamics
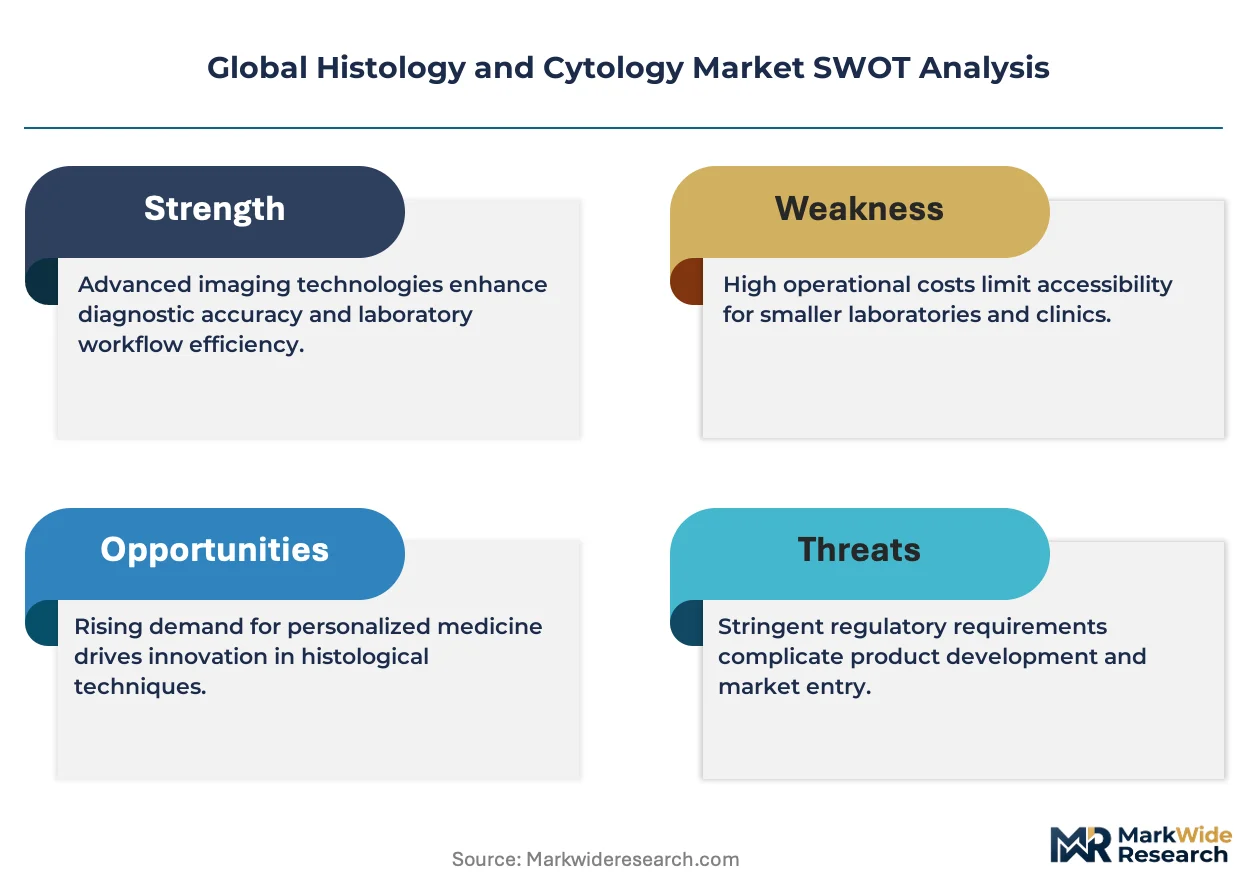
Digital pathology infrastructure deployment is compressing diagnostic turnaround times while forcing laboratories to reconcile capital intensity against reimbursement compression. Automated tissue processing platforms now sit at the center of competitive positioning for high-throughput cancer centers.
Growth Catalysts
- Companion diagnostic expansion:Biomarker-driven oncology protocols are multiplying testing volumes in tertiary care hospitals. The EU IVDR extension timelines provide temporary regulatory relief for IVD manufacturers scaling documentation.
- Japan's national cancer screening mandates:Public procurement volumes for cervical cytology services are expanding under METI-coordinated health initiatives. Regional laboratories are consolidating to capture economies of scale.
- Artificial intelligence pattern recognition:Machine learning algorithms trained on whole-slide images are reducing pathologist review burden. Academic medical centers in Germany and the United States are piloting FDA-cleared diagnostic aids.
Market Restraints
- Xylene and formaldehyde input volatility:Chemical safety reviews under EPA jurisdiction are constraining reagent formulation flexibility. Supply disruptions in specialty solvents inflate processing costs for mid-volume laboratories.
- EU IVDR technical documentation burden:Extended compliance timelines mask underlying resource requirements for performance studies and quality management system upgrades. Smaller IVD manufacturers face capital access constraints.
- Digital pathology interoperability gaps:Proprietary image formats from scanner vendors fragment enterprise-wide deployment. DICOM standard adoption remains uneven across installed bases.
Strategic Opportunities
- India's diagnostic network expansion:CDSCO regulatory pathways for imported IVDs are streamlining market entry for automated staining platforms. Tier-2 city laboratory chains seek throughput solutions without full digital pathology capital commitment.
- AI-assisted cytology screening:Convolutional neural networks applied to Papanicolaou smears are reducing false-negative rates in high-volume cervical cancer programs. South Korea's MFDS is accelerating software-as-medical-device approvals.
- Research institute translational programs:Tissue-based drug target validation workflows are absorbing multiplex immunohistochemistry panels. Biopharma contract research spend is shifting toward integrated histology services.
Industry Challenges
- Pathologist workforce density:Specialized diagnostic expertise concentrates in metropolitan academic centers. Rural and community hospital laboratories face recruitment bottlenecks for subspecialty sign-out.
- Legacy LIS integration complexity:Proprietary middleware requirements from scanner vendors extend implementation timelines. Hospital IT departments prioritize cybersecurity patching over interoperability upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Histology and Cytology Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Histology Reagents, Cytology Stains, Microtomes, Slide Scanners, Immunohistochemistry Kits Application: Cancer Diagnosis, Infectious Disease Testing, Genetic Analysis, Drug Development, Toxicology Studies End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Academic Centers, Veterinary Clinics Deployment: Manual Processing, Automated Systems, Semi-Automated Workflows, Remote Digital Pathology, Point-of-Care Testing |
| Companies Covered | Hologic, Inc., F. Hoffmann-La Roche Ltd, Abbott Laboratories, BD, Danaher Corporation, Merck KGaA, Thermo Fisher Scientific, Inc., Sysmex Corporation, Trivitron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Histology and Cytology Market Shifts & Advancements
Multiplex staining technologies and cloud-based image analysis are converging to reshape laboratory economics. Regulatory frameworks across the United States, European Union, and Asia-Pacific are adapting to software-enabled diagnostic workflows.
Multiplex immunofluorescence panels are integrating up to nine biomarkers per tissue section, enabling comprehensive tumor microenvironment characterization. Comprehensive cancer centers in the United States and Germany are adopting these platforms for immuno-oncology clinical trials. The technology is integrating biomarker discovery workflows with companion diagnostic development timelines, compressing translational research cycles.
The EU IVDR is extending compliance deadlines for legacy IVD devices while tightening performance evidence requirements for novel assays. European diagnostic networks are resequencing product launch timelines to prioritize high-revenue oncology portfolios. Medium-sized IVD manufacturers are redirecting regulatory affairs resources from MDR technical files toward IVDR conformity assessments.
Hospital procurement departments are consolidating histology and cytology consumables under enterprise laboratory agreements. Group purchasing organizations are extracting volume commitments in exchange for preferred vendor status. This concentration is most visible in United States health system networks, where integrated delivery networks negotiate multi-year supply contracts spanning reagents, instruments, and digital pathology subscriptions.
Global Histology and Cytology Market Segmentation
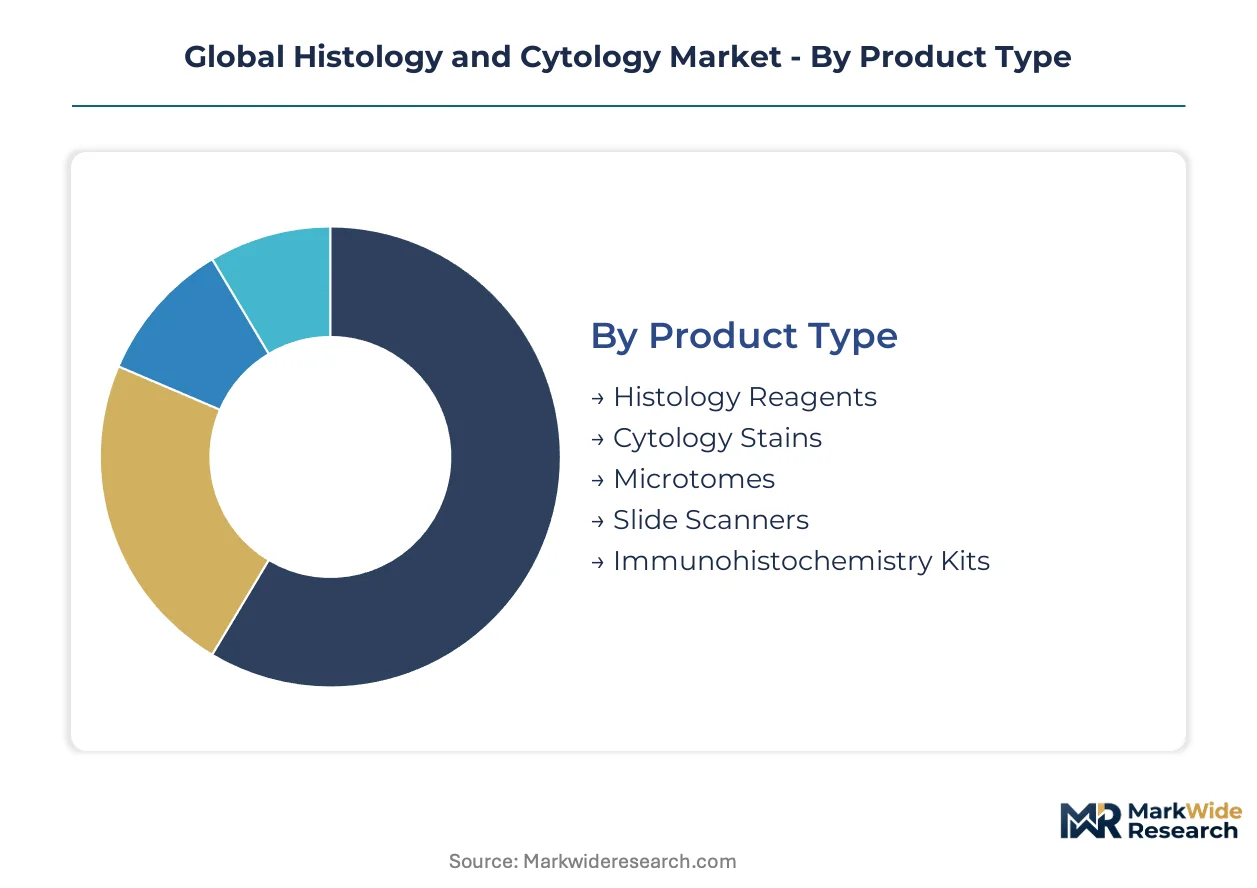
Histology and cytology procurement patterns diverge sharply across laboratory workflows, with capital intensity and regulatory burden driving distinct buyer behaviors. Segment-level demand mapping reveals where automation investments concentrate versus where manual protocols persist.
Product Type:
Cost tier separates high-volume consumable purchasers from capital-equipment buyers in this category.
- Histology Reagents:Formalin fixatives, xylene substitutes, and dehydration alcohols constitute the recurring spend base for processing laboratories. Demand concentrates in United States cancer centers facing EPA chemical safety reviews, with procurement officers negotiating multi-year supply contracts to lock pricing amid solvent volatility.
- Slide Scanners:Whole-slide imaging systems with 40x oil-immersion objectives digitize tissue sections for remote consultation and AI-assisted analysis. Germany and Japan lead deployment as academic medical centers pilot FDA-cleared and PMDA-registered diagnostic aids, though interoperability gaps with legacy LIS platforms extend implementation timelines.
- Immunohistochemistry Kits:Antibody-based detection systems enable biomarker-driven oncology protocols with companion diagnostic claims.
- Cytology Stains:Papanicolaou and Romanowsky formulations support cervical cancer screening programs under national mandates.
- Microtomes:Rotary and cryostat models produce 3-5 micron sections for paraffin-embedded tissue analysis.
Volume sits with Histology Reagents; growth tilts toward Slide Scanners.
Application:
Reimbursement rates and test complexity determine where laboratories allocate technical resources across disease areas.
- Cancer Diagnosis:Tissue-based pathology and liquid cytology dominate revenue as precision oncology multiplies biomarker testing requirements. Tertiary care hospitals in the United States and Japan absorb multiplex immunohistochemistry panels for immuno-oncology clinical trials, compressing turnaround expectations.
- Drug Development:Tissue-based drug target validation workflows absorb contract research spend from biopharma sponsors. Research institutes in Germany and academic centers in the United States represent expanding demand as translational medicine programs scale integrated histology services.
- Infectious Disease Testing:Cytology-based detection supports tuberculosis and fungal pathogen identification in high-burden settings.
- Genetic Analysis:Fluorescence in situ hybridization and chromogenic in situ hybridization enable HER2 and ALK testing.
- Toxicology Studies:Histopathological evaluation supports preclinical safety assessment in pharmaceutical development.
Revenue concentrates in Cancer Diagnosis; Drug Development is climbing the fastest.
End User:
Capital access and technical staffing depth fragment procurement authority across institutional types.
- Diagnostic Laboratories:High-throughput cancer centers and regional reference labs drive automation adoption to compress turnaround times. United States health system networks consolidate consumables purchasing under enterprise agreements, extracting volume commitments from vendors for preferred status.
- Research Institutes:Translational medicine programs represent the steepest expansion trajectory as tissue-based drug target validation absorbs multiplex panel deployment. Biopharma contract research spend is shifting toward integrated histology services in Germany and the United States.
- Pharmaceutical Companies:In-house pathology capabilities support companion diagnostic co-development timelines.
- Academic Centers:Training programs and NIH-funded research sustain manual processing workflows alongside pilot digital pathology installations.
- Veterinary Clinics:Companion animal oncology drives cytology service demand in specialty referral practices.
Procurement scale favors Diagnostic Laboratories; Research Institutes are gaining share fastest.
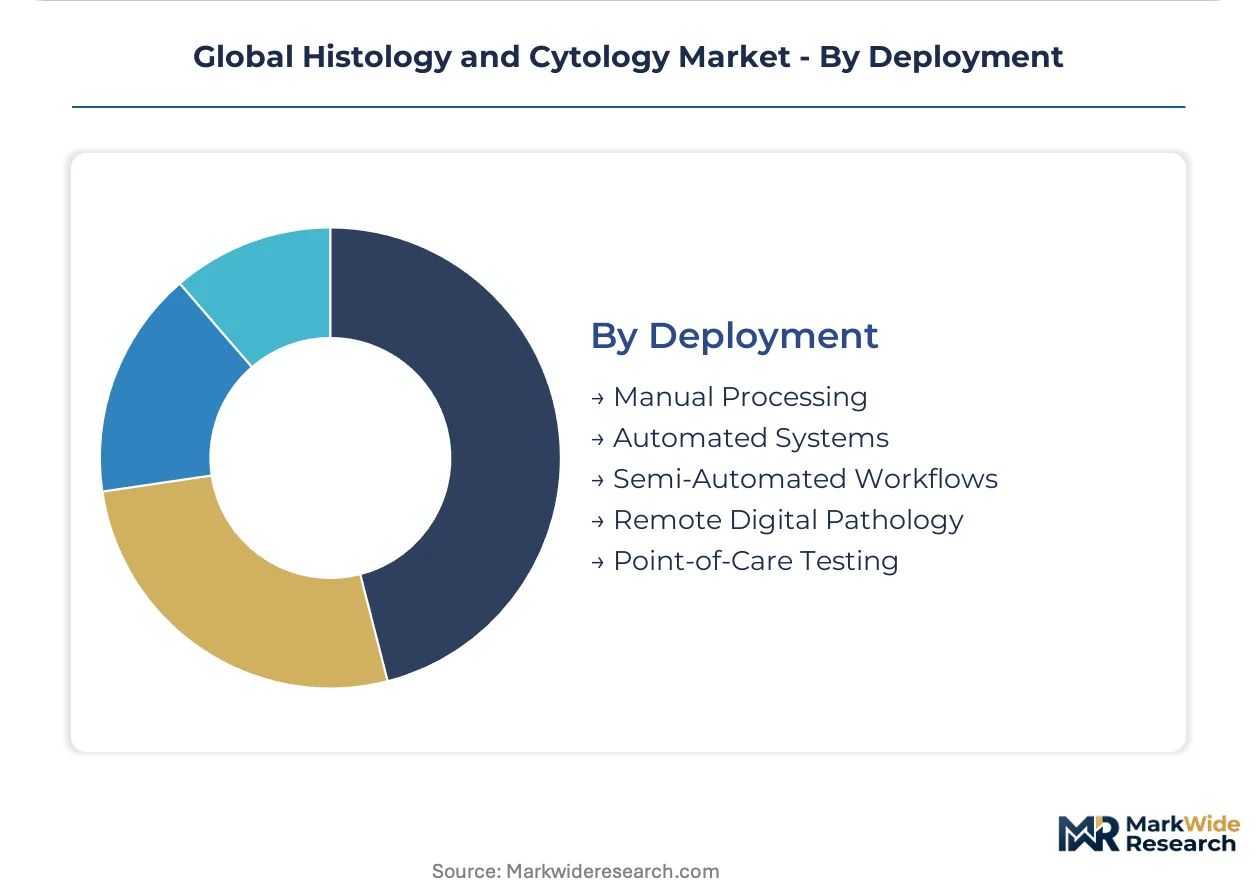
Deployment:
Workflow maturity and IT infrastructure readiness determine automation adoption curves.
- Automated Systems:Integrated staining platforms and tissue processors reduce manual steps in high-throughput environments. Japan's METI-coordinated cancer screening expansion and United States integrated delivery network consolidation drive capital deployment, though pathologist workforce density constraints limit rural penetration.
- Semi-Automated Workflows:Mid-volume laboratories capture throughput gains without full digital pathology commitment. India's CDSCO-streamlined IVD import pathways enable tier-2 city laboratory chains to upgrade from manual processing, avoiding enterprise-scale capital outlays.
- Manual Processing:Legacy workflows persist in resource-constrained settings and specialized research applications.
- Remote Digital Pathology:Cloud-based image distribution enables subspecialty consultation across geographic distances.
- Point-of-Care Testing:Rapid cytology applications serve screening programs with limited laboratory infrastructure.
Installed base remains with Manual Processing; investment momentum favors Automated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Route 128 biotechnology corridor concentrates digital pathology R&D investment alongside Germany's MedTech cluster around Munich and Heidelberg. Japan's Kanto region anchors automated staining platform deployment under METI-coordinated cancer screening expansion. India's CDSCO regulatory streamlining enables tier-2 city laboratory chains to upgrade processing capabilities.
United States
Integrated delivery networks in the Northeast and California consolidate histology consumables purchasing under enterprise agreements spanning reagents, instruments, and digital pathology subscriptions. FDA premarket notification pathways and EPA chemical safety reviews shape reagent formulation standards for processing laboratories. The Boston-Cambridge biotechnology corridor anchors multiplex immunohistochemistry panel development for precision oncology protocols.
Germany
Academic medical centers in Heidelberg and Munich pilot FDA-cleared and PMDA-registered diagnostic aids for AI-assisted pattern recognition on whole-slide images. EMA companion diagnostic guidelines and EU IVDR technical documentation requirements determine market entry sequencing for European clinical laboratories. The Baden-Württemberg MedTech cluster concentrates automated tissue processing platform manufacturing for high-throughput cancer centers.
Japan
Public procurement volumes for cervical cytology services expand under METI-coordinated national cancer screening mandates in the Kanto and Kansai regions. PMDA registration pathways govern automated cell imaging system approvals for hematology-cytology convergence applications. Regional laboratories in Osaka and Tokyo consolidate operations to capture economies of scale from screening volume concentration.
India
Tier-2 city laboratory chains in Maharashtra and Karnataka seek throughput solutions through CDSCO-streamlined IVD import pathways for automated staining platforms. The country's national pharmaceutical regulator accelerates market entry timelines for mid-volume laboratories upgrading from manual processing workflows. Hyderabad's diagnostic services cluster absorbs capital equipment deployment without full digital pathology infrastructure commitment.
South Korea
Convolutional neural networks applied to Papanicolaou smears reduce false-negative rates in high-volume cervical cancer screening programs under MFDS oversight. The national medical device regulator accelerates software-as-medical-device approvals for AI-assisted cytology applications. Seoul's academic medical centers pilot cloud-based image distribution for subspecialty consultation across geographic distances.
Global Histology and Cytology Market Competitive Landscape
United States producers anchor the premium instrumentation tier; German and Japanese specialists hold dominant positions in automated processing platforms. The vendor base separates into three distinct layers: diversified conglomerates with full histology-cytology portfolios, mid-scale regional equipment fabricators, and niche reagent formulators serving specific staining protocols. Two strategic archetypes predominate: integrated diagnostics platforms that compress workflow steps, and specialized imaging systems that enable remote consultation. Competitive moves concentrate on portfolio diversification into multiplex staining technologies and strategic partnerships with academic medical centers for AI training data access.
Among Switzerland-based diversified healthcare conglomerates, F. Hoffmann-La Roche Ltd occupies a position exemplifying the integrated diagnostics archetype through immunohistochemistry portfolio breadth. Abbott Laboratories and Sysmex Corporation represent distinct competitive vectors within automated platform deployment, with the former exemplifying workflow integration strategies and the latter occupying a position in hematology-cytology convergence systems. These three anchors illustrate how geographic origin and corporate structure shape strategic positioning without determining specific product-market outcomes.
| Leading Market Players |
|---|
| Hologic, Inc. |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| BD |
| Danaher Corporation |
| Merck KGaA |
| Thermo Fisher Scientific, Inc. |
| Sysmex Corporation |
| Trivitron Healthcare |
| Others |
Supply & Pricing Matrix
Automated slide scanner deployment is compressing cost economics for digital pathology infrastructure while concentrating supply authority among integrated platform vendors in the United States, Germany, and Japan. This technology shift simultaneously elevates capital intensity for high-throughput laboratories and fragments procurement leverage for mid-volume buyers dependent on reagent consumables.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from scheduled inventory in histology consumables, with premium markups attaching to spot xylene substitute orders amid EPA chemical safety review delays. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-IVD marked reagents command sustained premiums against research-use-only alternatives. Cost compression in standard-grade consumables is intensifying because group purchasing organizations extract volume commitments from United States health system networks. Mid-volume diagnostic laboratories in India's tier-2 cities exhibit highest price sensitivity, while academic medical centers in Germany and Japan absorb premium instrumentation with bundled service contracts.
Supply Chain Analysis
Pathologist workforce density constraints in specialized manufacturing geographies—particularly Germany's MedTech cluster and Japan's Kanto region—extend lead times for precision-engineered microtome components and automated staining modules. Supply concentration rests on Germany, Japan, and the United States for high-end instrumentation, with China and India anchoring consumable reagent formulation. Raw material dependencies include optical-grade glass for scanner objectives, specialty solvents for tissue processing, and antibody conjugates for immunohistochemistry kits. Single-source vulnerability in 40x oil-immersion objective manufacturing creates chokepoint exposure. Distribution runs through authorized dealer networks for capital equipment and direct-to-laboratory fulfillment for recurring consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as platform vendors pursue captive control over antibody supply chains and cloud-based image analysis software to lock laboratory switching costs.
For Market Incumbents: Cement laboratory loyalty through multi-year enterprise agreements spanning reagents, instruments, and digital pathology subscriptions. Deepen backward integration into antibody production to secure immunohistochemistry kit margins against emerging reagent formulators. Prioritize certification investment in EU IVDR technical documentation to exploit extended compliance timelines that strain smaller competitors.
For New Entrants and Emerging Players: Cloud-based AI diagnostic aid distribution offers lower-friction market entry than capital-intensive hardware manufacturing. Target India's tier-2 city laboratory chains seeking semi-automated workflow upgrades without full digital pathology commitment. Pursue CDSCO regulatory pathway partnerships with established distributors to compress market entry timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified diagnostics conglomerates seeking multiplex staining technology capabilities. Long-term viability hinges on software-enabled recurring revenue models rather than transactional instrument sales. Watch FDA clearance velocity for AI-assisted pattern recognition algorithms as inflection indicator for platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Conformity Investment | Extended timelines provide temporary relief while performance evidence requirements reshape competitive tiers. |
| Multiplex Immunofluorescence Launch | Nine-biomarker panels integrate tumor microenvironment characterization with companion diagnostic development workflows. |
| Cloud-Based Image Analysis Partnership | Academic medical centers in Germany and the United States pilot FDA-cleared diagnostic aids for remote consultation. |
| Antibody Supply Chain Integration | Captive production of immunohistochemistry reagents protects margin structure against specialty chemical volatility. |
| Tier-2 City Distribution Expansion | India's CDSCO-streamlined pathways enable automated staining platform deployment without enterprise-scale capital outlays. |
Research Methodology
SEC 10-K filings, EMA companion diagnostic guidelines, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with pathology laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at IVD manufacturers supplied operational validation and procurement pattern detail. Bottom-up triangulation across product-type demand curves and top-down reconciliation against national cancer screening program budgets anchored volume estimates.
Historical trendline analysis across automated platform installation rates and consumable reagent consumption patterns informed projection modeling over the analysis window. Segmentation dimensions included deployment mode, end-user institutional type, application workflow, and regional regulatory cluster. CAGRs derived from slope-stability testing against biomarker-driven oncology protocol expansion rates and digital pathology infrastructure investment cycles. Industry-specific inputs incorporated EU IVDR compliance timeline shifts and Japan's METI-coordinated screening mandate procurement schedules.
The model holds under stable regulatory enforcement intensity and continued precision oncology protocol expansion; deviation in EPA chemical safety review stringency or pathologist workforce availability would shift instrument replacement cycle assumptions. Forecasts reflect documented base-case assumptions regarding reimbursement stability and interoperability standard adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Fluorescence Cell Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Global HLA Typing Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Asia Pacific Immunohistochemistry Market