
 Asia Pacific Immunohistochemistry Market | 2026-2036
Asia Pacific Immunohistochemistry Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Immunohistochemistry Market Insights
Platform licensing revenue from multiplex staining protocols is reconfiguring margin pools away from standalone antibody sales toward integrated workflow contracts. F. Hoffmann-La Roche Ltd. anchors its position through automated staining instruments bundled with proprietary reagent menus. Thermo Fisher Scientific Inc. extends reach via direct distribution into hospital pathology departments across China and Japan. Danaher Corporation leverages its diagnostics conglomerate structure to cross-sell consumables with Leica Biosystems hardware.
Immunohistochemistry denotes a laboratory method using antibody-antigen binding to visualize protein expression in fixed tissue sections, typically employing chromogenic or fluorescent detection with DAB or AEC substrates to map cellular markers for disease classification. Antibodies constitute the largest product segment due to recurring purchase requirements and expanding biomarker panels, while instruments command premium pricing through automated throughput gains. Oncology applications dominate volume as companion diagnostic mandates expand across Asia Pacific, though infectious disease testing grows fastest where tuberculosis and HPV-related malignancies drive protocol adoption.
Japan's PMDA enforces stringent analytical validation for IHC-based companion diagnostics, while China's NMPA accelerates review pathways for innovative antibody reagents under revised medical device rules. Australia's TGA harmonizes with IHC quality standards through its pathology accreditation program, shaping import requirements for multinational suppliers. Stakeholders must monitor evolving reimbursement decisions for automated IHC platforms in South Korea and Singapore, where health technology assessment bodies increasingly influence capital procurement cycles.
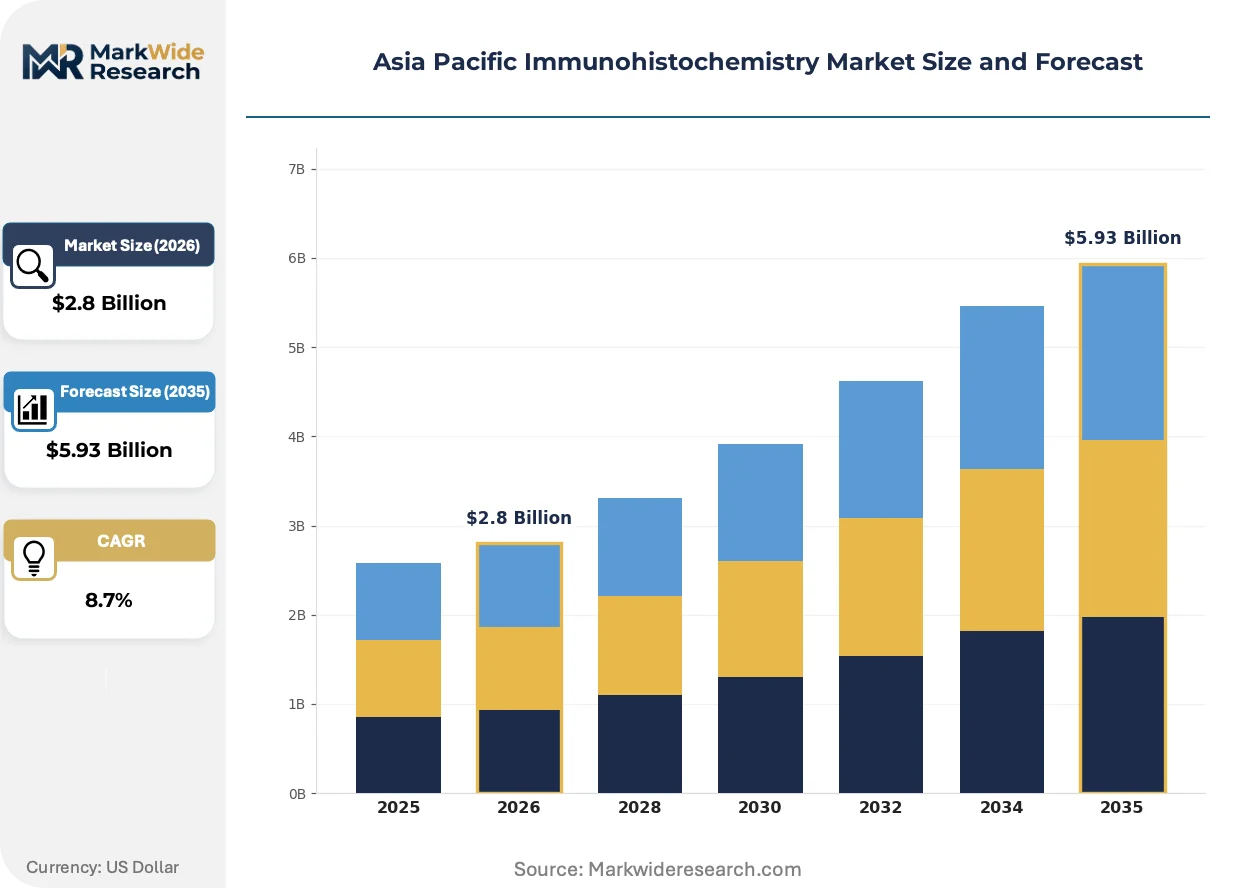
Market Dynamics
Platform licensing revenue from multiplex staining protocols is reconfiguring margin pools away from standalone antibody sales toward integrated workflow contracts across Asia Pacific diagnostic networks. CDSCO tightening of antibody validation requirements in India and NMPA accelerated review pathways in China are compressing supplier qualification timelines while elevating technical barriers to market entry.
Growth Catalysts
- Oncology companion diagnostic mandates:Regulatory frameworks in Japan and South Korea now require IHC-based biomarker testing prior to targeted therapy authorization, expanding protocol volumes in hospital pathology departments.
- CDSCO state-level accreditation tightening:India's clinical laboratory framework mandates documented antibody lot validation, driving replacement cycles and premium reagent sourcing from validated suppliers.
- Automation investments in China's tier-one hospitals:Beijing and Shanghai hospital networks are deploying integrated staining platforms that lock in consumable contracts through proprietary reagent menus.
Market Restraints
- Antibody supply concentration:Rabbit monoclonal antibody production concentrates among a limited set of GMP-certified bioreactor facilities, creating vulnerability to batch variability and import delays.
- PMDA analytical validation burden:Japan's pharmaceutical regulator demands extensive cross-laboratory reproducibility studies for companion diagnostic IHC assays, extending time-to-market by 18-24 months.
- Technical limitation in multiplex chromogenic detection:Spectral overlap constraints in DAB-AEC dual staining protocols limit biomarker panel expansion beyond three targets per tissue section.
Strategic Opportunities
- Underpenetrated Southeast Asia expansion:Vietnam and Indonesia diagnostic laboratories currently operate manual IHC workflows with minimal automation, presenting greenfield platform installation potential.
- Fluorescence in situ hybridization convergence:Combined IHC-FISH workflows for HER2 and ALK testing are creating integrated pathology platform demand in Australia's TGA-accredited networks.
- NMPA innovative reagent pathway:China's revised medical device rules offer priority review for novel antibody clones targeting emerging oncology biomarkers, compressing approval timelines.
Industry Challenges
- Histopathologist workforce scarcity:Interpretation of complex multiplex staining patterns requires specialized training that outpaces graduation rates from accredited pathology programs across India and Southeast Asia.
- Legacy LIS integration friction:Automated IHC platforms must interface with heterogeneous laboratory information systems deployed across China's provincial hospital tiers, delaying workflow optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Immunohistochemistry Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Detection Kits, Reagents, Instruments Application: Oncology, Infectious Diseases, Autoimmune Disorders, Neurological Disorders End User: Hospitals, Diagnostics Labs, Research Institutes, Pharmaceutical Companies Delivery Mode: Manual, Automated, Semi-Automated, Point-of-Care |
| Companies Covered | Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., Danaher Corporation, Merck KGaA, Agilent Technologies, Inc., PerkinElmer, Inc., Bio-Rad Laboratories, Inc., Cell Signaling Technology, Inc., Abcam plc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Immunohistochemistry Market Trends and Innovations
Multiplex immunofluorescence protocols are displacing chromogenic methods in precision oncology workflows across Asia Pacific academic medical centers. Regulatory harmonization efforts and platform consolidation are compressing vendor diversity while elevating technical performance thresholds.
Multiplex immunofluorescence imaging systems is hybridizing traditional brightfield pathology with quantitative digital analysis. Shanghai and Tokyo cancer centers are adopting 7-plex and 9-plex panels for immune-oncology biomarker profiling. The technology is hybridizing diagnostic and research applications, enabling pharmaceutical sponsors to leverage clinical pathology infrastructure for trial enrollment stratification.
NMPA's revised medical device classification rules reclassify novel antibody reagents as Class III devices requiring clinical validation studies. This elevates development costs for domestic Chinese suppliers while creating compliance advantages for multinationals with established quality management systems. The regulation most affects companion diagnostic antibody developers, who are responding by pre-submission engagement with the regulator's technical review center.
Pathology departments are consolidating reagent procurement through multi-year enterprise agreements rather than transactional antibody purchases. Hospital networks in South Korea and Singapore are unbundling instrument placement from consumable supply, negotiating separate pricing for staining platforms and per-test reagent volumes. This behavioral shift is most visible in Australia's public hospital pathology services, where state-level tendering aggregates demand across multiple facilities.
Asia Pacific Immunohistochemistry Market Segmentation
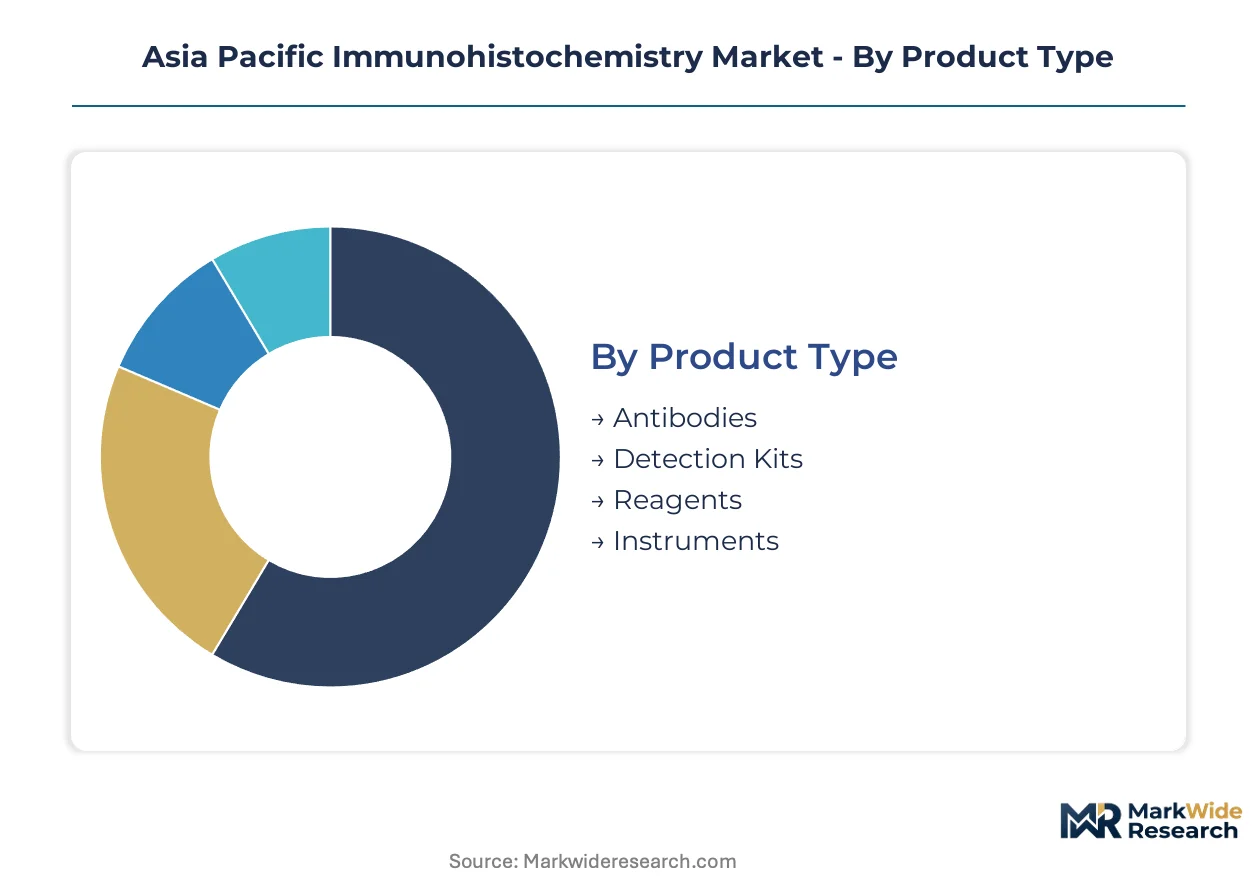
Immunohistochemistry purchasing patterns in Asia Pacific diverge sharply by product lifecycle and capital intensity. Antibodies and reagents turn over in weeks, while staining platforms lock hospitals into multi-year contracts. Understanding these velocity differences shapes vendor strategy across fragmented diagnostic networks.
Product Type:
Antibody lots rotate fastest through pathology departments, while instruments anchor decade-long procurement cycles with locked consumable streams.
- Antibodies:Rabbit monoclonal and recombinant rabbit formats dominate precision oncology workflows across Japan's PMDA-regulated hospital networks. CDSCO's tightened lot validation requirements in India are compressing supplier qualification timelines while elevating technical barriers for unvalidated clones.
- Instruments:Automated staining platforms from Leica Biosystems and Roche command premium positioning through throughput gains and proprietary reagent menus. China's tier-one hospital networks in Beijing and Shanghai are consolidating procurement around integrated workflow contracts rather than standalone hardware sales.
- Detection Kits:Chromogenic DAB and AEC substrate systems remain standard across Southeast Asian diagnostic laboratories with limited fluorescence infrastructure.
- Reagents:Buffer solutions, antigen retrieval agents, and counterstains constitute recurring purchase categories with minimal brand loyalty.
Antibodies dominate installed base consumption volumes. Instruments anchor the fastest-expanding contract value pools as automation penetrates tier-one hospital networks.
Application:
Oncology commands the steepest per-test pricing while infectious disease protocols are climbing fastest where tuberculosis and HPV-related malignancies drive menu expansion.
- Oncology:Companion diagnostic mandates from Japan's PMDA and South Korea's MFDS require IHC-based biomarker testing prior to targeted therapy authorization. HER2, PD-L1, and ALK testing protocols concentrate volume in hospital pathology departments with automated platform investments.
- Infectious Diseases:Tuberculosis and HPV-related cancer screening protocols are expanding fastest across India's state-level laboratory networks and Vietnam's diagnostic infrastructure. Manual IHC workflows predominate where capital constraints limit automation deployment.
- Autoimmune Disorders:Renal biopsy and dermatopathology applications concentrate in Australia's TGA-accredited pathology services with established quality frameworks.
- Neurological Disorders:Neurodegenerative biomarker research applications remain concentrated in academic medical centers across Tokyo and Singapore with limited clinical reimbursement.
Oncology anchors current revenue concentration. Infectious disease testing is where expansion concentrates as Southeast Asian laboratory networks broaden screening menus.
End User:
Hospital pathology departments command the highest per-test margins through integrated platform contracts, while diagnostics labs optimize for reagent cost efficiency at scale.
- Hospitals:China's provincial hospital tiers and Japan's cancer centers are deploying automated staining platforms with proprietary reagent lock-in. NMPA's revised medical device rules elevate compliance costs for instrument suppliers while favoring multinationals with established quality systems.
- Diagnostics Labs:India's CDSCO-accredited commercial laboratories are expanding IHC testing menus as cancer incidence reporting improves and state-level accreditation tightens antibody validation requirements.
- Research Institutes:Multiplex immunofluorescence panel development concentrates in Shanghai and Tokyo academic medical centers with pharmaceutical trial enrollment partnerships.
- Pharmaceutical Companies:Companion diagnostic development partnerships leverage clinical pathology infrastructure for biomarker validation and regulatory submission support.
Hospitals dominate installed base platform placements. Diagnostics labs are where expansion concentrates as India's commercial laboratory sector scales IHC service offerings.
Delivery Mode:
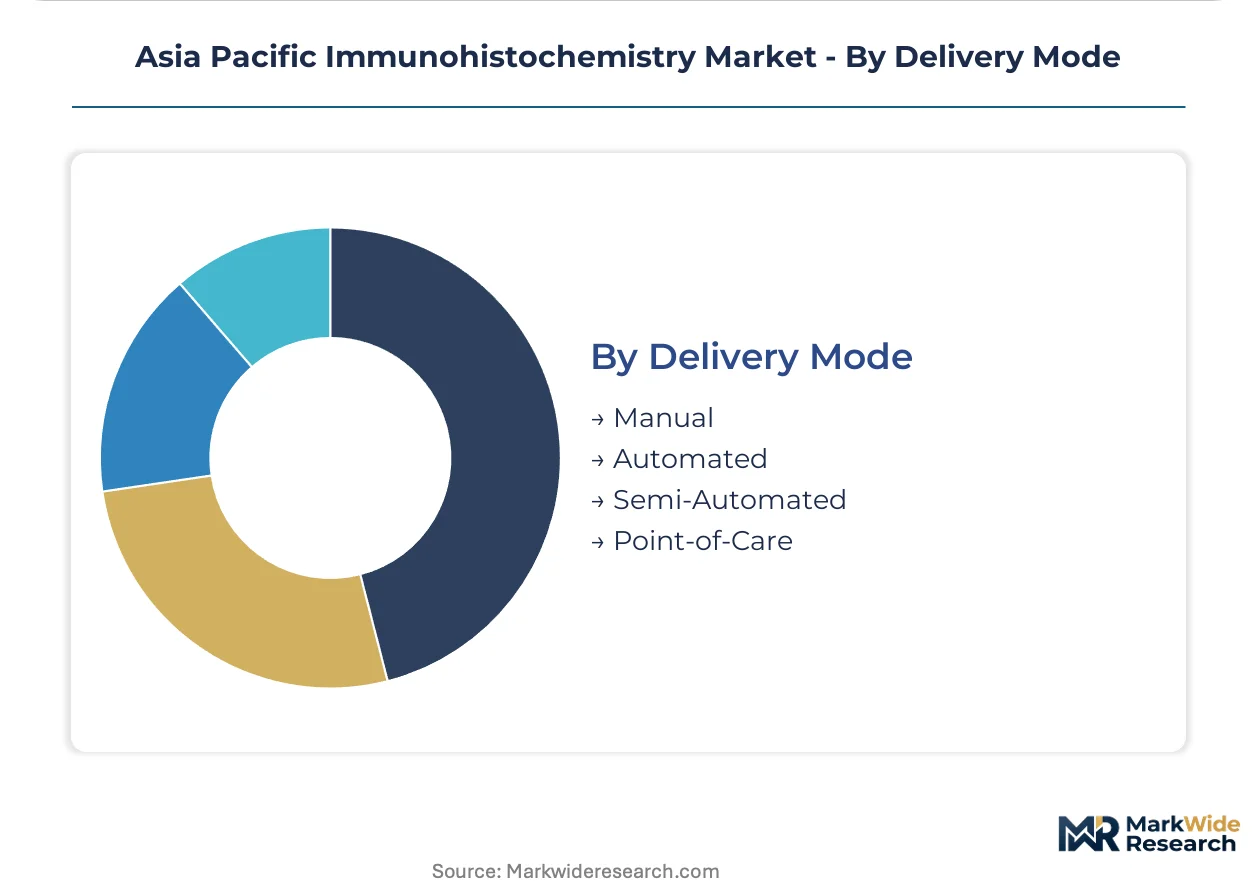
Manual workflows persist where capital scarcity constrains automation investment, while semi-automated platforms bridge cost-performance gaps in mid-tier hospital networks.
- Automated:Fully integrated staining platforms with barcode tracking and LIS connectivity command premium positioning in South Korea's health technology assessment-influenced procurement cycles. Singapore's hospital networks are unbundling instrument placement from consumable supply through separate pricing negotiations.
- Manual:Open staining baths and microwaves remain prevalent across Indonesia and Vietnam diagnostic laboratories with minimal pathology automation infrastructure.
- Semi-Automated:Batch processing stations with partial liquid handling are penetrating India's mid-tier hospital networks as CDSCO accreditation requirements elevate workflow standardization needs.
- Point-of-Care:Limited deployment confined to research applications and specialized surgical pathology consultations with rapid turnaround requirements.
Manual systems dominate installed base across Southeast Asia. Automated platforms are where expansion concentrates as tier-one hospital networks in China, Japan, and South Korea consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody production concentrates in GMP-certified bioreactor facilities across Japan, China, and South Korea, creating import dependencies for Southeast Asian diagnostic networks. Tier-one hospital procurement in Beijing, Tokyo, and Seoul locks suppliers into multi-year platform contracts with proprietary reagent menus.
China
NMPA's revised medical device classification rules elevate novel antibody reagents to Class III status, requiring clinical validation studies that favor multinationals with established quality systems. Beijing and Shanghai hospital networks are consolidating procurement around integrated staining platforms with barcode tracking and LIS connectivity. The Yangtze River Delta cancer centers are deploying 7-plex immunofluorescence panels for immune-oncology biomarker profiling.
Japan
PMDA enforces stringent analytical validation requirements for IHC-based companion diagnostics, demanding cross-laboratory reproducibility studies that extend time-to-market by 18-24 months. Tokyo and Osaka cancer centers anchor demand for automated staining platforms with HER2, PD-L1, and ALK testing protocols. Kanto region academic medical centers are adopting multiplex immunofluorescence imaging systems that hybridize brightfield pathology with quantitative digital analysis.
India
CDSCO state-level accreditation frameworks mandate documented antibody lot validation, compressing supplier qualification timelines while elevating technical barriers for unvalidated clones. Maharashtra and Karnataka diagnostic laboratories are expanding IHC testing menus as cancer incidence reporting improves. Commercial laboratories in Delhi-NCR are scaling semi-automated batch processing stations to meet workflow standardization requirements.
South Korea
MFDS companion diagnostic mandates require IHC-based biomarker testing prior to targeted therapy authorization, expanding protocol volumes in Seoul Capital Area hospital pathology departments. Health technology assessment bodies increasingly influence capital procurement cycles for automated IHC platforms. Busan-Ulsan medical centers are unbundling instrument placement from consumable supply through separate pricing negotiations.
Australia
TGA harmonizes with IHC quality standards through its pathology accreditation program, shaping import requirements for multinational suppliers. New South Wales and Victoria public hospital pathology services aggregate demand through state-level tendering across multiple facilities. Sydney and Melbourne diagnostic networks are adopting combined IHC-FISH workflows for HER2 and ALK testing.
Asia Pacific Immunohistochemistry Market Competitive Landscape
Diagnostics conglomerates and life science specialists split the market through divergent channel strategies. The vendor base organizes around three archetypes: integrated platform providers bundling hardware with proprietary reagent menus, standalone antibody suppliers competing on biomarker panel breadth, and regional distributors bridging import logistics for mid-tier hospital networks. Competitive moves concentrate on multi-year enterprise procurement agreements and pre-submission regulatory engagement with NMPA and PMDA technical review centers.
Within the integrated platform tier, F. Hoffmann-La Roche Ltd. and Danaher Corporation anchor positions through automated staining instruments with locked consumable streams. Thermo Fisher Scientific Inc. exemplifies the direct distribution archetype, extending reach into hospital pathology departments through field service infrastructure. These three entities represent the dominant competitive anchors as China's tier-one networks consolidate procurement and India's CDSCO accreditation tightens validation requirements for antibody sourcing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies, Inc. |
| PerkinElmer, Inc. |
| Bio-Rad Laboratories, Inc. |
| Cell Signaling Technology, Inc. |
| Abcam plc. |
| Others |
Pricing and Supply Chain Analysis
GMP-certified bioreactor undercapacity across Japan and South Korea is elevating antibody lot premiums while compressing qualification timelines for Indian diagnostic networks. This utilization squeeze simultaneously tightens supplier pricing power in premium monoclonal segments and accelerates cost-optimization investments in automated platform contracts.
Pricing Analysis
After-sales consumable streams and multi-year reagent lock-in contracts drive lifetime value for automated staining platforms across Asia Pacific hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates proprietary instrument-reagent bundles from validated standalone antibodies and unvalidated manual workflow inputs. Price differentiation centers on CDSCO lot validation status and NMPA Class III registration tier. Cost compression in manual reagent tiers is intensifying because India's state-level accreditation mandates are forcing replacement cycles toward validated suppliers. Commercial diagnostic laboratories exhibit highest price sensitivity, while China's tier-one cancer centers prioritize throughput guarantees over per-test economics.
Supply Chain Analysis
Extended payment terms from platform vendors to GMP-certified antibody producers are stabilizing working capital across tier-one hospital procurement cycles. Geographic supply concentration in Japan, China, and South Korea creates import dependencies for Southeast Asian diagnostic networks. Raw material dependencies span recombinant rabbit hybridoma cell lines, chromogenic DAB substrates, and fluorescence detection fluorophores. Single-source vulnerability concentrates in rabbit monoclonal antibody production where batch variability propagates through qualification workflows. Distribution runs through direct field service infrastructure for automated platforms and regional distributor networks for manual reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as CDSCO accreditation tightening and NMPA Class III reclassification create supplier qualification niches for validated antibody specialists. The demand-side shift toward companion diagnostic mandates is splintering procurement authority between hospital pathology departments and centralized laboratory networks.
For Market Incumbents: Build regulatory moat through pre-submission engagement with PMDA and NMPA technical review centers for companion diagnostic assay validation. Incumbents should deepen backward integration into GMP-certified bioreactor capacity to secure antibody supply continuity against batch variability risks. Channel control through multi-year enterprise procurement agreements with China's provincial hospital tiers locks out emerging platform competitors. R&D investment in 7-plex and 9-plex immunofluorescence panels addresses the spectral overlap constraints limiting chromogenic protocol expansion. For New Entrants and Emerging Players: Build out semi-automated batch processing station deployments across India's mid-tier hospital networks where CDSCO workflow standardization requirements outpace capital availability for fully integrated platforms. Vietnam and Indonesia diagnostic laboratories represent the most penetrable geography, operating manual IHC workflows with minimal automation infrastructure. A go-to-market angle anchored to NMPA innovative reagent pathway pre-submission support captures priority review compression for novel antibody clones targeting emerging oncology biomarkers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multiplex immunofluorescence imaging systems as 7-plex panel development requires specialized optical hardware and software analytics integration. Long-term viability over the next decade favors platform providers with locked consumable revenue streams over standalone antibody suppliers facing margin compression from validation mandates. Acquisition target archetype: regional distributors with established CDSCO-accredited logistics infrastructure and relationships with Maharashtra and Karnataka diagnostic laboratory networks. The signal to watch is unbundling negotiations in South Korea and Singapore where hospital networks are separating instrument placement from consumable supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Submission Engagement | PMDA and NMPA technical review center relationships compress companion diagnostic assay time-to-market. |
| Backward Integration into GMP Bioreactor Capacity | In-house recombinant rabbit monoclonal production mitigates batch variability and import delay risks. |
| Multiplex Panel Platform Development | 7-plex immunofluorescence imaging systems address spectral overlap constraints in chromogenic protocols. |
| Enterprise Procurement Agreement Consolidation | Multi-year contracts with China's tier-one hospital networks lock in proprietary re menu streams. |
| Semi-Automated Platform Deployment | Batch processing stations bridge cost-performance gaps in India's CDSCO-accredited mid-tier hospitals. |
Research Methodology
A spread of perspectives from pathology department heads, diagnostic laboratory operations directors, regulatory affairs specialists at antibody suppliers, and hospital procurement committee members converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from CDSCO accreditation circulars, NMPA medical device classification rulings, PMDA companion diagnostic guidance documents, and TGA pathology quality standards. Bottom-up triangulation across instrument installation databases and top-down reconciliation against regional healthcare expenditure reports anchored volume estimates.
Demand-supply balance modeling across the projection horizon calibrated antibody consumption rates against GMP-certified bioreactor capacity utilization in Japan, China, and South Korea. Segmentation dimensions spanned product type, application, end user, and delivery mode, with additional granularity on regulatory approval tier and automation integration level. CAGRs derived from slope analysis of historical platform placement trajectories and forward projection of CDSCO and NMPA compliance-driven replacement cycles. Industry-specific forecast inputs incorporated PMDA analytical validation timeline assumptions and health technology assessment influence coefficients for South Korean capital procurement.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic Chinese suppliers exploiting NMPA innovative reagent pathway compression would shift outcomes. Forecasts reflect assumptions regarding regulatory enforcement consistency and bioreactor capacity expansion schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
AI in Medical Diagnostics Market
Medical Diagnostics
MUC1 Antibody Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
US Molecular Diagnostics Market
Medical Diagnostics
Karyotype Analysis Service Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market