
 Artificial Intelligence in Medicine Market | 2026-2036
Artificial Intelligence in Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Medicine Market Analysis
Modular platform bundling is rebalancing how hospitals evaluate AI procurement, shifting from point solutions to integrated suites that span imaging, workflow, and decision support. NVIDIA Corporation leverages its GPU compute architecture to anchor the infrastructure layer for medical AI training and inference. Microsoft competes through cloud-native health data fabrics that extend Azure's reach into clinical environments. Siemens Healthineers differentiates by embedding AI directly into imaging hardware, controlling the full diagnostic stack from acquisition to analysis.
Artificial intelligence in medicine encompasses computational systems that process clinical data through machine learning, natural language processing, and deep learning algorithms to assist diagnosis, treatment planning, and operational management, typically requiring validation against ground-truth clinical outcomes and regulatory benchmarks for safety and efficacy. Its primary purpose is to augment clinician decision-making while reducing diagnostic latency and systemic healthcare costs. Deep learning within imaging analytics occupies the largest current revenue pool as convolutional neural networks achieve radiologist-equivalent performance in lesion detection. Natural language processing applied to clinical documentation and workflow optimization represents the fastest-expanding segment as health systems automate administrative burden and unstructured data extraction.
The FDA's Software as a Medical Device framework and the EU AI Act's risk-classification system for clinical AI are tightening conformity requirements, forcing developers to invest in prospective clinical validation and post-market surveillance infrastructure. HIPAA in the United States and GDPR in Europe impose parallel constraints on training data access and cross-border model deployment. China's NMPA algorithm registration rules add a third compliance frontier for vendors seeking multi-region scale. Stakeholders must monitor divergence in regulatory evidence standards to avoid fragmented product architectures that duplicate compliance costs across jurisdictions.
Market Dynamics
Modular platform bundling is rebalancing hospital procurement calculus, shifting evaluation criteria from standalone algorithm accuracy to integrated workflow coverage across imaging, documentation, and decision support layers.
Growth Catalysts
- FDA Software as a Medical Device framework:Clearer authorization pathways reduce regulatory uncertainty for developers, accelerating time-to-market for validated clinical algorithms.
- Convolutional neural networks in lesion detection:Radiologist-equivalent diagnostic performance in imaging analytics validates clinical utility and drives hospital adoption.
- China's national health AI infrastructure investment:Government-funded deployment programs create institutional demand for diagnostic and operational AI systems.
Market Restraints
- GPU compute cost concentration:Training infrastructure dependence on NVIDIA hardware creates input cost volatility and supply bottleneck risk.
- Cross-border model deployment restrictions:GDPR data localization requirements fragment training data access and complicate multi-region product architectures.
- Prospective clinical validation mandates:EU AI Act risk-classification system forces developers to fund expensive pre-market evidence generation.
Strategic Opportunities
- German hospital system consolidation:Large integrated delivery networks seek unified AI platforms, favoring vendors with broad workflow coverage.
- Natural language processing for clinical documentation:Unstructured data extraction from physician notes remains underpenetrated relative to imaging analytics.
- Convergence of federated learning with edge deployment:Privacy-preserving model training enables hospital network collaboration without centralizing sensitive patient data.
Industry Challenges
- Interoperability with legacy EHR systems:Integration friction slows deployment timelines and inflates implementation costs.
- Post-market surveillance infrastructure:Continuous algorithm performance monitoring requires capabilities most developers lack.
- Regulatory evidence standard divergence:FDA, EU AI Act, and NMPA impose non-overlapping validation requirements that fragment product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Medicine Market |
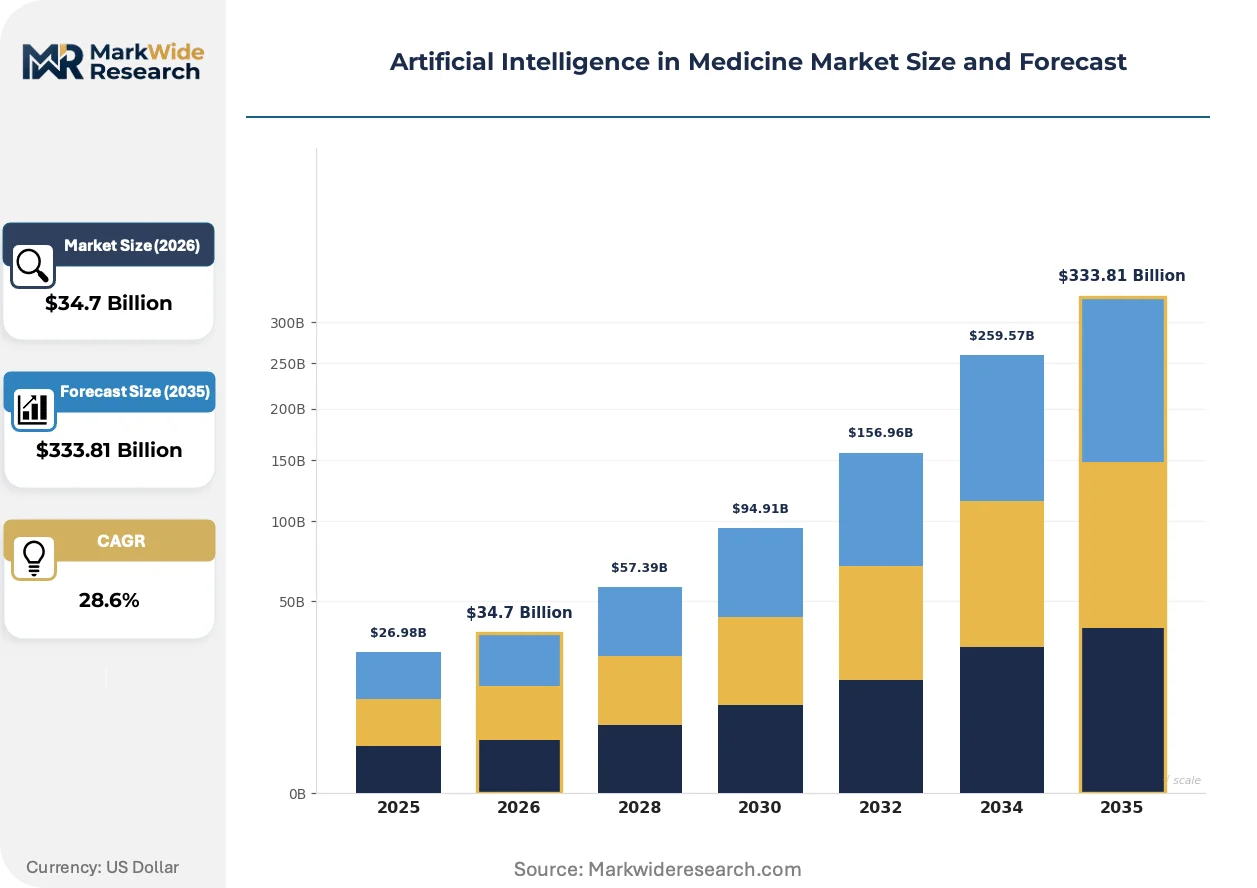
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $333.81 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Imaging Analytics, Workflow Optimization, Virtual Assistants End User: Hospitals, Outpatient Clinics, Research Labs, Diagnostics Centers Application: Radiology, Pathology, Surgery, Patient Monitoring Technology: Machine Learning, Natural Language Processing, Robotics, Deep Learning |
| Companies Covered | Microsoft, NVIDIA Corporation, Google, IBM, Amazon Web Services, GE HealthCare, Siemens Healthineers, Intel Corporation, Tempus Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Medicine Market Emerging Trajectories
Foundation models trained on massive clinical corpora are compressing development timelines and enabling zero-shot adaptation to narrow diagnostic tasks previously requiring specialist architectures.
Multimodal foundation models that jointly process imaging, text, and structured data are overtaking single-modality convolutional networks in hospital procurement evaluations. Academic medical centers in the United States are piloting these systems for differential diagnosis support. The technology is enabling diagnostic platforms that span radiology, pathology, and clinical notes without separate algorithm development for each modality.
The EU AI Act's risk-classification system for clinical decision support is tightening conformity assessment requirements for high-risk applications. Developers must now maintain quality management systems and post-market monitoring infrastructure previously unnecessary for lower-risk software. Radiology AI vendors targeting European hospital systems are restructuring product portfolios to clarify risk tier assignments and streamline notified body engagement.
Subscription-based platform licensing is displacing per-study pricing in health system procurement negotiations. Integrated delivery networks in Germany and the United States favor predictable operational expenditure models that align vendor incentives with long-term outcome improvement. This shift concentrates contract value with vendors offering comprehensive workflow integration rather than point-solution accuracy.
Artificial Intelligence in Medicine Market Segmentation
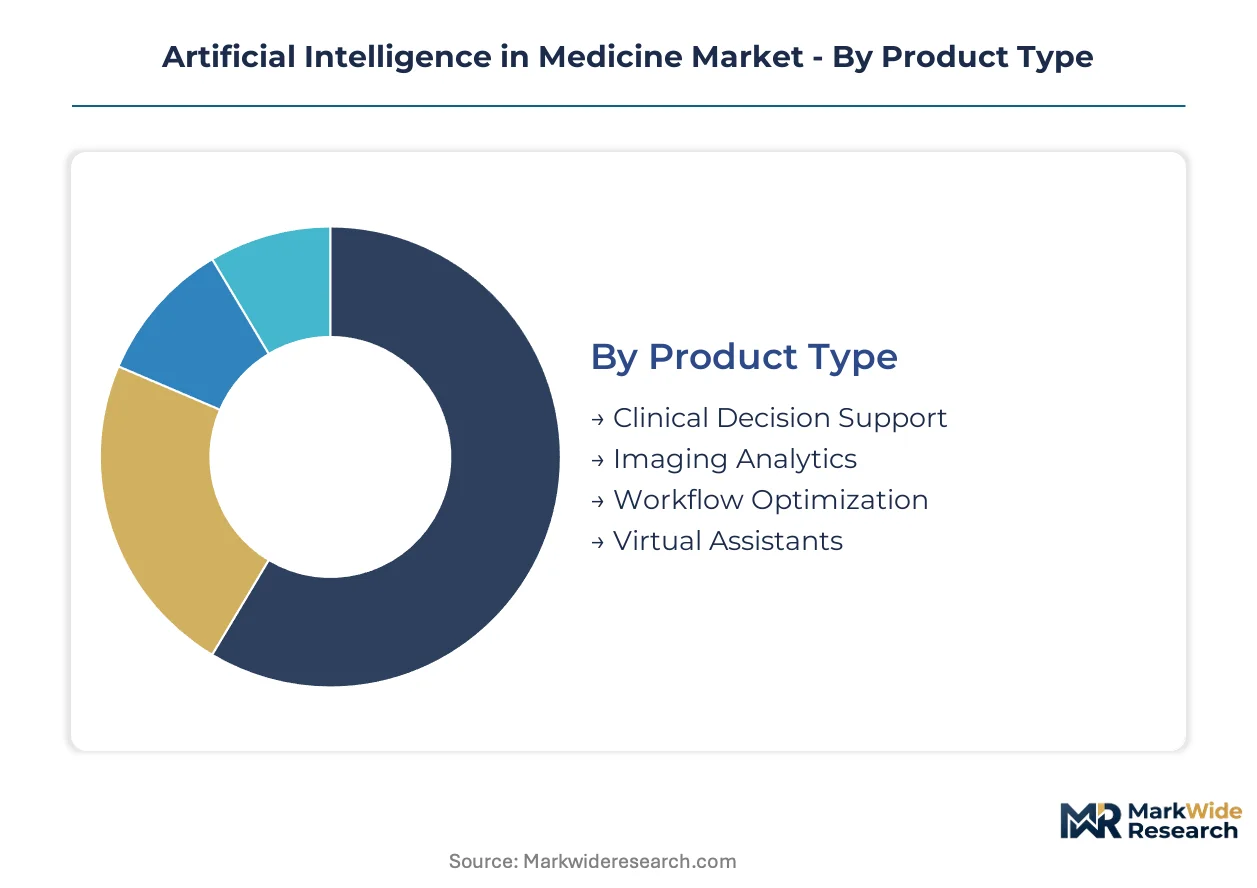
Hospital procurement cycles for AI systems follow distinct replacement timelines across product categories, with imaging hardware upgrades occurring every 5-7 years while software layers refresh on 2-3 year cycles. Understanding these asynchronous upgrade patterns clarifies why vendors bundle modular platforms rather than selling isolated algorithms.
Product Type:
Replacement urgency varies sharply across product categories, with hardware-tied systems demanding capital budget cycles and cloud-native tools fitting operational expenditure frameworks.
- Imaging Analytics:Convolutional neural networks process CT, MRI, and X-ray data for lesion detection and quantification. Demand clusters in United States academic medical centers and German university hospitals pursuing radiologist-equivalent diagnostic performance. FDA 510(k) clearance pathways and EU MDR conformity assessments shape vendor investment priorities.
- Clinical Decision Support:Algorithms synthesize patient data to generate differential diagnoses and treatment recommendations. Deployment concentrates in China's tier-1 hospital systems under government-funded national health AI infrastructure programs. NMPA algorithm registration rules impose distinct validation requirements from Western regulators.
- Workflow Optimization:Systems automate scheduling, resource allocation, and operational forecasting.
- Virtual Assistants:Conversational interfaces handle patient intake, medication adherence, and post-discharge follow-up.
Volume placements concentrate in Imaging Analytics; the faster expansion belongs to Clinical Decision Support.
End User:
Customer scale determines integration complexity, with large integrated delivery networks demanding enterprise-wide platforms and smaller facilities accepting standardized configurations.
- Hospitals:Multi-department health systems deploy AI across radiology, pathology, and emergency departments. Procurement in Germany favors unified platforms spanning imaging and clinical documentation. Siemens Healthineers and Microsoft compete for enterprise contracts through differentiated bundling strategies.
- Diagnostics Centers:Specialized imaging and laboratory facilities prioritize high-throughput algorithm accuracy over workflow breadth. United States outpatient imaging chains drive demand for FDA-cleared lesion detection tools. Per-study pricing persists here longer than in hospital settings.
- Outpatient Clinics:Smaller facilities adopt point solutions for specific clinical tasks.
- Research Labs:Academic and pharmaceutical research environments utilize AI for biomarker discovery and clinical trial optimization.
Contract value pools deepest in Hospitals; Diagnostics Centers gain share fastest as outpatient volume shifts from inpatient settings.
Application:
Clinical domain maturity varies, with some specialties achieving regulatory validation while others remain in pilot phases.
- Radiology:Image interpretation for detection, classification, and quantification of abnormalities. Convolutional neural networks achieve performance parity with specialist radiologists in United States and Chinese validation studies. FDA algorithm authorization and NMPA registration create parallel compliance tracks for multi-region vendors.
- Surgery:Intraoperative guidance, robotics integration, and outcome prediction. Adoption concentrates in German and United States academic medical centers with established surgical robotics programs. Real-time inference requirements demand edge computing infrastructure.
- Pathology:Whole-slide image analysis for cancer diagnosis and biomarker quantification.
- Patient Monitoring:Continuous physiological signal analysis for early deterioration detection.
Revenue concentration sits with Radiology; Surgery climbs the fastest as robotics platforms proliferate.
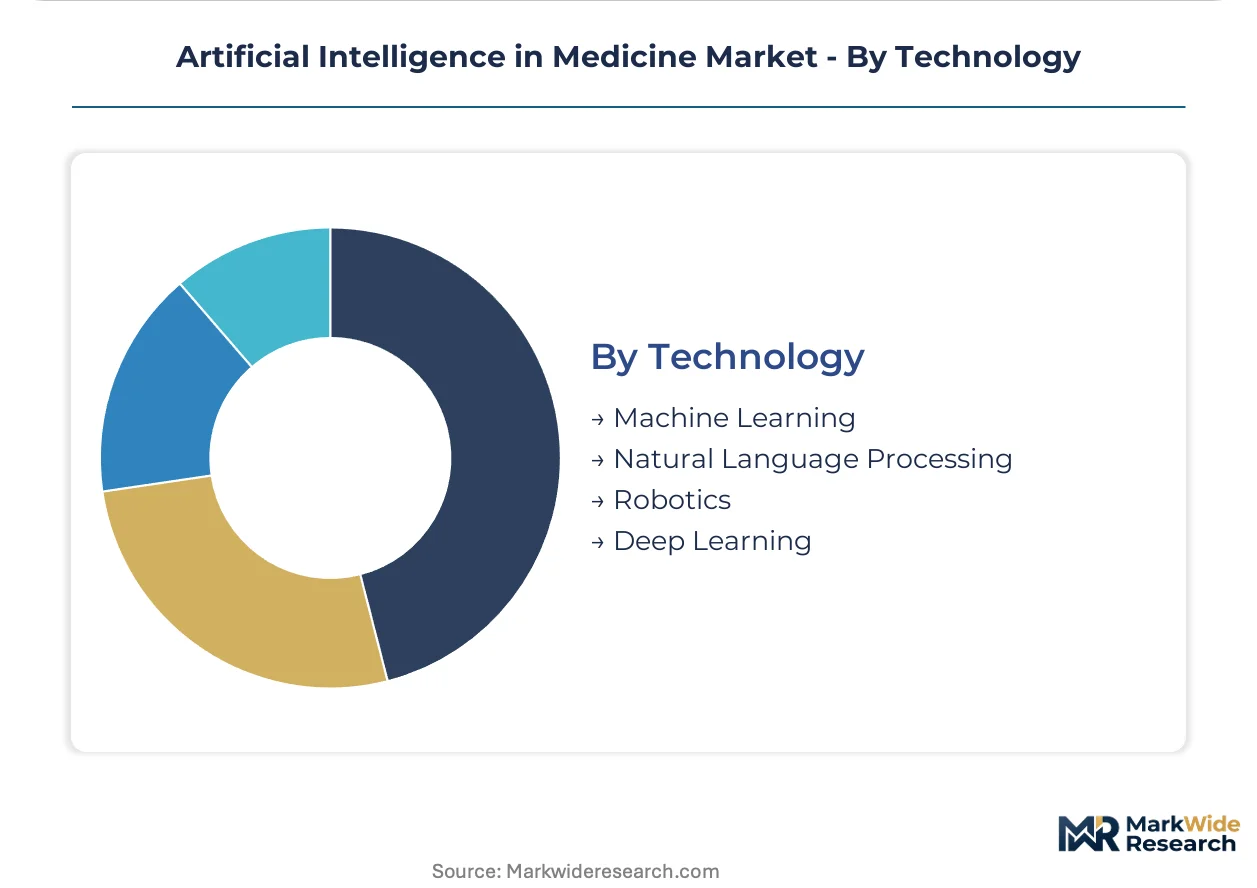
Technology:
Computational architecture choices determine training costs, deployment flexibility, and regulatory classification.
- Deep Learning:Multi-layer neural networks for pattern recognition in imaging and signal data. Training infrastructure dependence on NVIDIA GPU clusters creates cost concentration risks for developers. United States cloud providers and Chinese hardware manufacturers compete for training workload placement.
- Natural Language Processing:Text analysis for clinical documentation, literature mining, and conversational interfaces. Expansion runs fastest as health systems automate administrative burden and unstructured data extraction from physician notes. GDPR constraints on cross-border model deployment complicate European scaling.
- Machine Learning:Traditional statistical learning methods for structured data analysis and risk stratification.
- Robotics:Physical system integration for surgical assistance, rehabilitation, and laboratory automation.
Deployment scale favors Deep Learning; Natural Language Processing shows the steepest expansion trajectory as documentation automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentive zones in Shenzhen and Shanghai are concentrating health AI development capital, while similar zones in Bavaria and North Carolina are accelerating clinical validation infrastructure deployment.
United States
Academic medical centers in Boston and Stanford are piloting multimodal foundation models for differential diagnosis. FDA Software as a Medical Device framework provides clearer authorization pathways for clinical algorithms. The Research Triangle Park cluster in North Carolina is emerging as a hub for health data fabric infrastructure development.
Germany
Large integrated delivery networks in Bavaria and North Rhine-Westphalia are consolidating procurement around unified AI platforms. EU AI Act risk-classification requirements are restructuring product portfolios for European hospital compliance. Berlin's Charité university hospital is establishing a reference site for surgical robotics AI integration.
China
Tier-1 hospital systems in Beijing and Shanghai are deploying government-funded diagnostic AI under national health infrastructure programs. NMPA algorithm registration rules impose distinct validation requirements from Western regulators. The Shenzhen special economic zone is concentrating venture capital for medical imaging AI startups.
United Kingdom
NHS England's AI Lab is accelerating procurement of imaging analytics for cancer detection pathways. GDPR data localization requirements are fragmenting cross-border model deployment strategies. London's King's College Hospital is piloting federated learning networks for privacy-preserving multi-site algorithm training.
Japan
PMDA is streamlining approval pathways for AI-enabled diagnostic software to address radiologist workforce shortages. METI funding programs are supporting hospital digitization in Osaka and Nagoya. The Kobe medical device cluster is integrating AI into existing imaging hardware manufacturing supply chains.
Artificial Intelligence in Medicine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the medical AI value chain. The market structure shows concentration at the infrastructure layer alongside fragmentation in clinical application development. Three strategic archetypes dominate: cloud-native platform vendors, hardware-embedded AI providers, and clinical workflow specialists. M&A activity targets algorithm developers with regulatory clearances, while strategic partnerships between imaging hardware and cloud computing vendors are reshaping distribution channels.
Within the infrastructure tier, NVIDIA Corporation and Microsoft exemplify divergent platform strategies—one anchoring GPU compute architecture for training workloads, the other extending cloud-native data fabrics into clinical environments. Siemens Healthineers occupies a position spanning hardware-embedded AI and enterprise imaging systems.
| Leading Market Players |
|---|
| Microsoft |
| NVIDIA Corporation |
| IBM |
| Amazon Web Services |
| GE HealthCare |
| Siemens Healthineers |
| Intel Corporation |
| Tempus Labs |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity assessment mandates gate qualified supply access and premium-tier pricing eligibility for clinical algorithm vendors seeking European hospital contracts. Developers lacking quality management system certification face exclusion from high-risk application procurement while compliant vendors command subscription premiums.
Pricing Analysis
Cost-down pressure on cloud-native platforms accelerates as subscription-based licensing displaces per-study pricing in German and United States hospital negotiations. Three-tier pricing structure across enterprise, departmental, and point-solution levels separates vendors by workflow integration depth. FDA 510(k) clearance tier and EU MDR conformity status drive price differentiation. Diagnostics Centers exhibit highest price sensitivity; academic medical centers prioritize accuracy over cost.
Supply Chain Analysis
ISO 13485 quality management certification and FDA establishment registration gate supplier eligibility for clinical AI hardware-software bundles. GPU compute infrastructure concentrates in Taiwan, South Korea, and the United States. NVIDIA H100 clusters and specialized AI training silicon constitute critical input dependencies. Single-source vulnerability in advanced node semiconductor fabrication threatens training capacity expansion. Distribution runs through cloud service provider marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over imaging hardware or cloud infrastructure determines platform bundling power. Winners anchor either the compute layer or the diagnostic acquisition stack.
For Market Incumbents: Lock in hospital system loyalty through federated learning infrastructure that enables multi-site collaboration without data centralization. Siemens Healthineers and NVIDIA should deepen hardware-software bundling to defend against cloud-native entrants. Post-market surveillance capabilities and quality management systems address EU AI Act compliance threats.
For New Entrants and Emerging Players: Outpatient clinic chains in the United States represent an underserved buyer archetype with unmet demand for affordable point-solution lesion detection tools. Natural language processing for clinical documentation automation offers faster regulatory pathways than imaging analytics. Target GPO contracts and ambulatory surgery centers with simplified deployment models.
For Investors and Strategic Acquirers: NMPA algorithm registration announcements from tier-1 Chinese hospitals are the leading indicator that government-funded deployment programs are converting pilot contracts to scaled revenue. Long-term viability hinges on multi-regulatory clearance portfolios spanning FDA, EU AI Act, and NMPA frameworks. Acquisition targets should demonstrate deployed validation studies and established quality management infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as Medical Device Submission | 510(k) clearance unlocks United States hospital procurement and validates clinical algorithm safety. |
| EU AI Act Conformity Assessment Pathway | Notified body engagement enables high-risk clinical decision support deployment across German integrated networks. |
| Hospital System Partnership | Charité and Stanford reference sites establish clinical validation credibility for multimodal foundation models. |
| Software Companion Development | Embedded AI modules for Siemens imaging hardware control full diagnostic stack from acquisition to analysis. |
| Reimbursement Strategy | CPT code establishment for AI-assisted diagnosis secures sustainable revenue from United States payers. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, EU MDR notified body certificates, NMPA algorithm registries, and hospital procurement contract filings, complemented by interviews with radiology department chairs, biomedical engineers, health system CIOs, GPO contracts managers, and regulatory affairs leads at AI developers. Secondary validation drew from SEC filings of publicly traded health technology vendors, hyperscaler healthcare vertical revenue disclosures, and academic medical center pilot study publications. Bottom-up deployment estimates triangulated against top-down health IT spending projections.
Market sizing outputs reflect algorithm authorization counts, hospital procurement cycle timing, and cloud infrastructure capacity expansion across the projection horizon. Segmentation modeling incorporated product type, end user scale, clinical application domain, and underlying computational architecture. CAGRs derived from fitted adoption curves weighted by regulatory clearance velocity and health system consolidation patterns. Federated learning penetration and foundation model deployment timelines served as key technology adoption inputs.
Revisions become necessary when FDA algorithm authorization pathways materially expand or restrict, EU AI Act enforcement priorities shift risk-classification interpretations, or NMPA registration rules diverge further from Western standards. A model refresh is warranted upon material change in GPU compute cost structures or hospital capital expenditure cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
AI Health and Fitness Products Market