
 Global Abdominal Aortic Aneurysm Treatment Market | 2026-2036
Global Abdominal Aortic Aneurysm Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Abdominal Aortic Aneurysm Treatment Market Foresight
Modular stent graft bundling with pre-loaded delivery systems is hardening as the dominant procurement configuration. Medtronic leverages its integrated manufacturing footprint to control catheter-stent compatibility. Cook Medical sustains competitive positioning through specialized fenestrated graft engineering for complex anatomies.
Abdominal aortic aneurysm treatment encompasses surgical and endovascular interventions to reinforce or exclude dilated aortic segments exceeding three centimeters in diameter, typically employing nitinol-framed polyester or ePTFE grafts deployed via transfemoral access. Endovascular repair now leads procedural volume globally while emergency intervention applications command premium pricing due to compressed decision windows and specialized staffing requirements. Stent grafts capture the dominant device margin pool as catheter-delivered platforms displace open surgical grafts in elective settings.
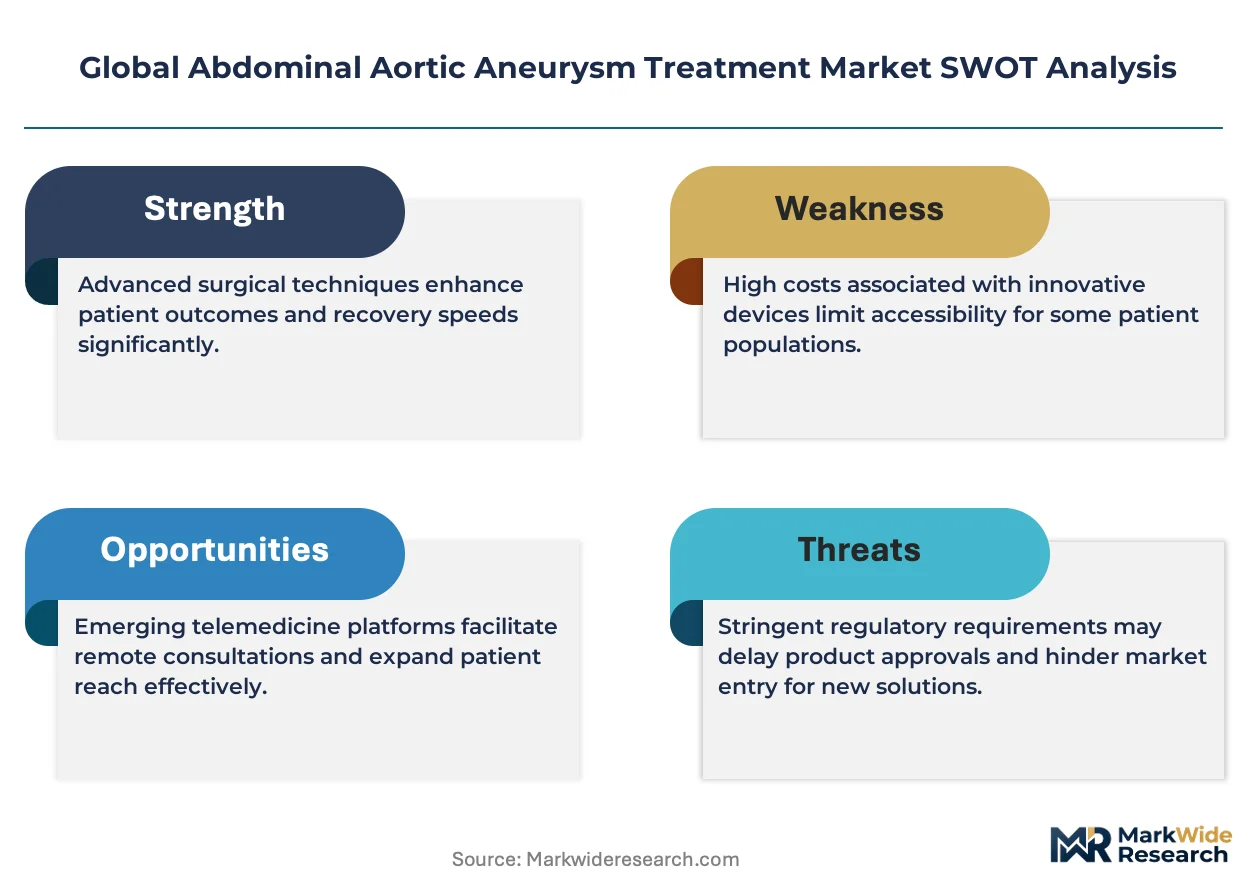
FDA premarket approval and EU MDR conformity assessments shape market access timelines and clinical evidence requirements for new graft platforms. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility and fatigue-testing standards that fragment regulatory strategy for multinational manufacturers. Stakeholders must monitor evolving aneurysm screening guidelines and reimbursement thresholds as health technology assessment bodies recalibrate cost-effectiveness benchmarks for preventive versus emergency intervention pathways.
Market Dynamics
Endovascular repair platforms are absorbing procedural volume from open surgical grafts as hospital outpatient departments in Germany and the United States consolidate purchasing around pre-loaded delivery systems. This shift compresses device compatibility requirements and rewards integrated manufacturing footprints.
Growth Catalysts
- EU MDR conformity pathways:Streamlined CE marking under the Medical Device Regulation is compressing commercialization timelines for nitinol-framed graft platforms, accelerating market entry for compliant manufacturers.
- Japan's expanded screening eligibility:PMDA reimbursement adjustments for aging populations are extending preventive intervention coverage, concentrating demand in Tokyo and Osaka metropolitan hospital networks.
- Fenestrated graft engineering:Specialized branch vessel preservation techniques are enabling treatment of complex juxtarenal anatomies previously excluded from endovascular repair protocols.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster in specific mining and refining geographies, exposing stent graft manufacturers to input cost volatility and geopolitical disruption risk.
- South Korea's MFDS fatigue-testing standards:Distinct biocompatibility protocols fragment regulatory strategy, forcing duplicate validation studies that extend approval timelines for multinational device platforms.
- Open surgical graft substitution ceiling:Emergency rupture presentations and unfavorable aortic anatomy maintain residual demand for conventional repair, limiting total addressable market expansion for endovascular systems.
Strategic Opportunities
- India's underpenetrated screening infrastructure:Low abdominal aortic aneurysm detection rates in urban tertiary centers create whitespace for mobile ultrasound deployment partnerships with state health ministries.
- 3D-printed patient-specific graft interfaces:Convergence of computed tomography segmentation and additive manufacturing enables custom fenestration patterns for hostile neck anatomies.
- Japan's preventive intervention incentives:METI-backed cost-effectiveness recalibration is elevating elective repair reimbursement above emergency thresholds, rewarding early detection programs.
Industry Challenges
- Specialized vascular surgeon training pipelines:Fenestrated and branched graft deployment demands advanced endovascular skill sets that outpace fellowship program output in most markets.
- EU MDR clinical evidence requirements:Post-market surveillance obligations and periodic safety update reports consume regulatory affairs bandwidth, delaying portfolio expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Abdominal Aortic Aneurysm Treatment Market |
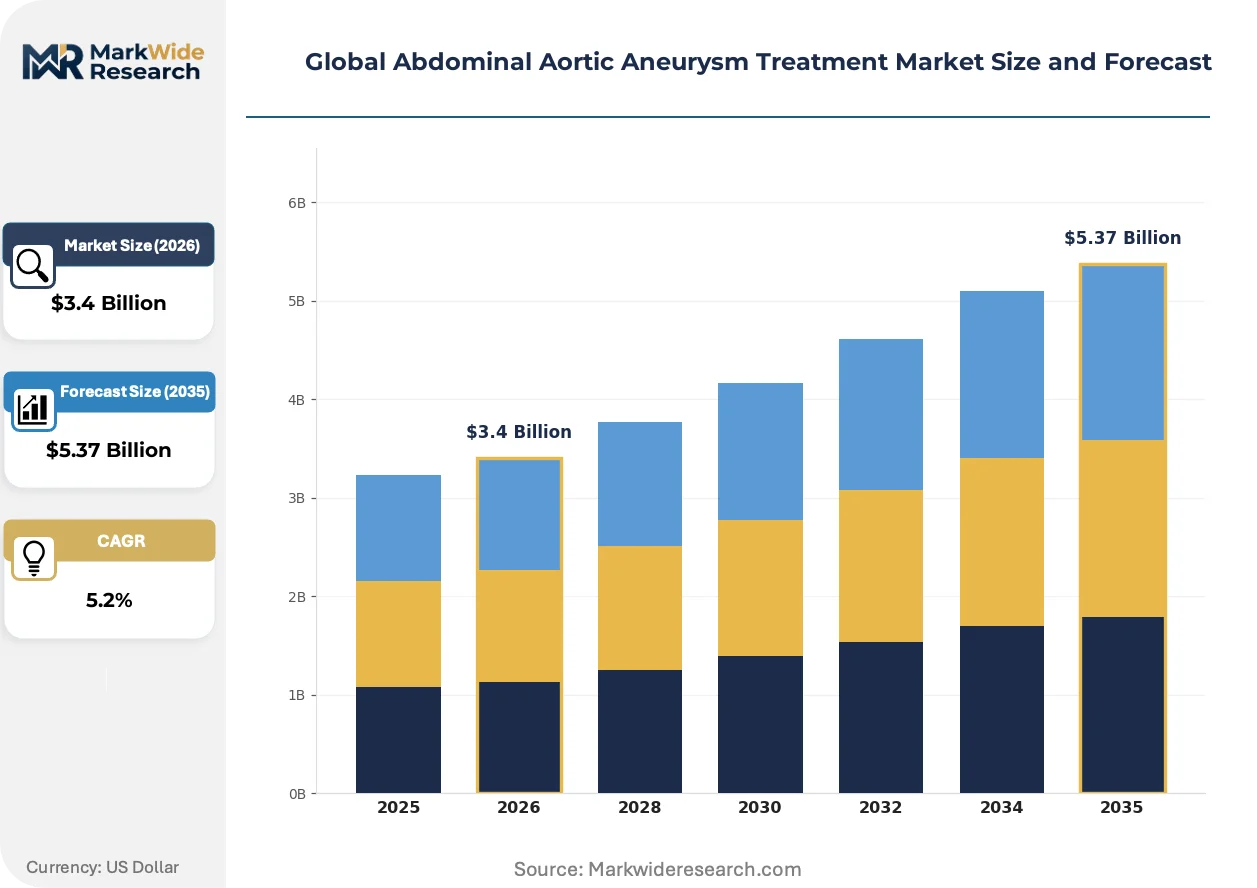
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Open Surgery, Endovascular Repair, Hybrid Procedure, Medical Management Device Type: Stent Grafts, Surgical Grafts, Coils, Vascular Plugs Application: Elective Repair, Emergency Intervention, Surveillance, Preventive Therapy End User: Vascular Surgeons, Interventional Radiologists, Cardiologists, Specialized Clinics |
| Companies Covered | Medtronic, Cook Medical, W. L. Gore & Associates, Cardinal Health, Endologix, Terumo Corporation, Boston Scientific Corporation, MicroPort Scientific Corporation, Artivion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Abdominal Aortic Aneurysm Treatment Market Shifts & Advancements
Device miniaturization and procedural migration to outpatient settings are restructuring how stent graft systems are designed, purchased, and deployed across hospital networks.
Polyester and ePTFE graft materials with laser-cut nitinol scaffolding are absorbing the functional requirements previously served by woven surgical grafts. Academic medical centers in Germany and the United States are adopting these platforms for elective infrarenal repairs, compressing average length of stay and shifting reimbursement risk to outpatient prospective payment models.
FDA premarket approval pathways are hardening evidentiary standards for new graft geometries, requiring larger pivotal trial cohorts and longer follow-up intervals. This regulatory friction disproportionately affects small and mid-cap manufacturers, forcing strategic partnerships or portfolio divestitures to fund clinical programs.
Hospital procurement committees are consolidating vendor relationships around integrated catheter-stent platforms that guarantee compatibility. This buyer concentration is displacing modular component purchasing in United States hospital outpatient departments, where supply chain simplification now outweighs unit cost minimization in sourcing criteria.
Global Abdominal Aortic Aneurysm Treatment Market Segmentation
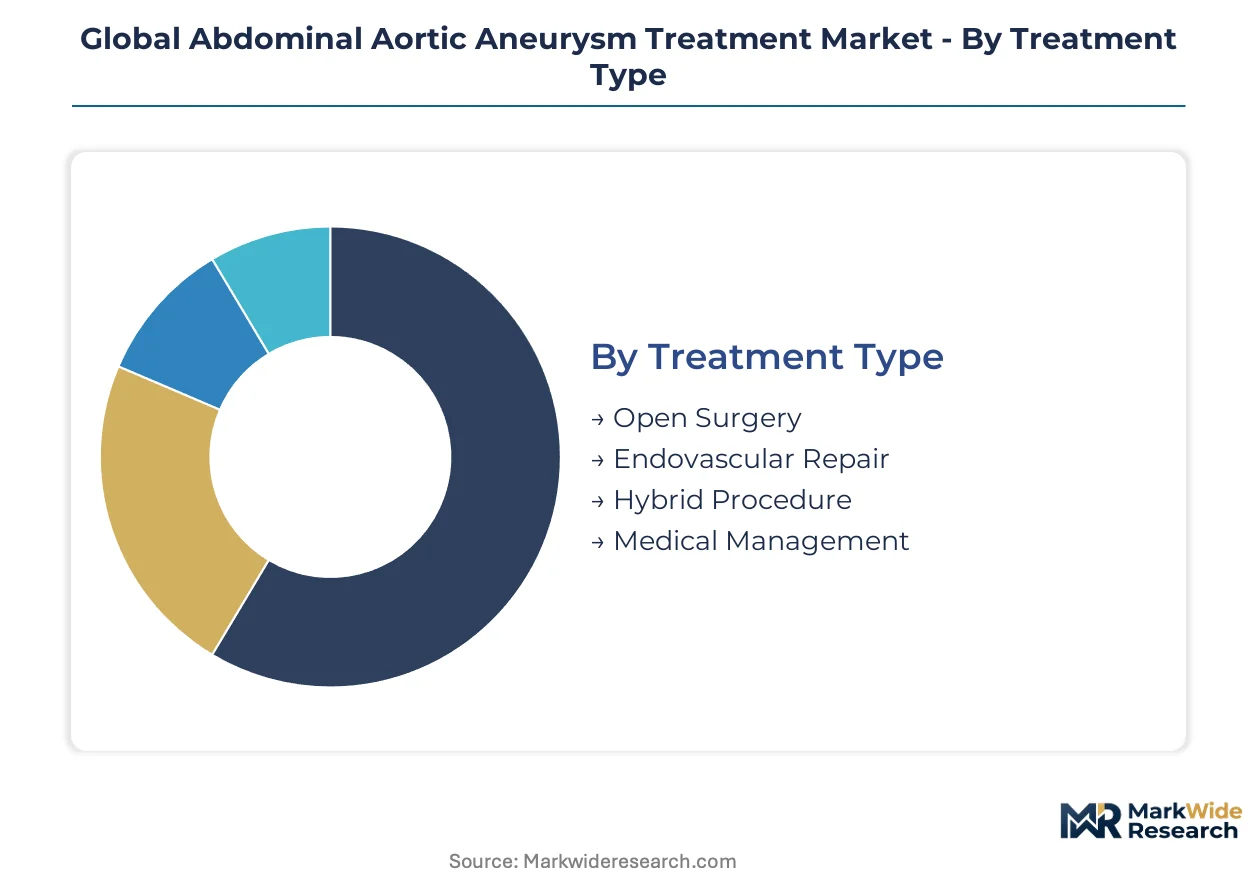
Treatment modality selection determines reimbursement pathways, device procurement cycles, and clinical training investments across hospital systems. Segmentation reveals where endovascular platforms displace conventional surgery and which specialist disciplines control purchasing decisions.
Treatment Type:
Volume concentrates in outpatient-compatible interventions while premium pricing attaches to emergency presentations requiring specialized staffing.
- Open Surgery:Conventional graft replacement via transabdominal or retroperitoneal approach employs woven polyester or ePTFE conduits sutured to healthy aortic tissue. Residual demand persists in Germany and Japan for rupture presentations and hostile anatomies beyond endovascular feasibility.
- Endovascular Repair:Catheter-delivered stent graft deployment via transfemoral access now dominates elective procedural volume across United States hospital outpatient departments and German ambulatory surgical centers. FDA premarket approval requirements and EU MDR conformity assessments shape commercialization timelines for new graft geometries.
- Hybrid Procedure:Combined open debranching with endovascular exclusion addresses complex juxtarenal anatomies. Demand clusters in Tokyo and Osaka academic medical centers where fenestrated graft engineering remains unavailable.
- Medical Management:Pharmacologic blood pressure control and statin therapy for sub-threshold aneurysms below intervention diameter. Screening program expansion in South Korea and Japan extends surveillance population eligibility.
Today's leader: Endovascular Repair. Tomorrow's challenger: Hybrid Procedure.
Device Type:
Procurement committees prioritize integrated catheter-stent compatibility over modular component sourcing.
- Stent Grafts:Nitinol-framed polyester or ePTFE platforms delivered via pre-loaded systems capture dominant device margins. United States hospital outpatient departments consolidate purchasing around guaranteed catheter-stent compatibility.
- Surgical Grafts:Woven polyester conduits for open repair retain position in emergency rupture protocols. Japan's PMDA maintains distinct biocompatibility standards that fragment manufacturing specifications.
- Coils:Embolization devices for branch vessel occlusion during complex endovascular procedures. Specialized vascular surgeons in German academic centers deploy these adjunctively.
- Vascular Plugs:Occlusion devices for iliac or lumbar artery management during graft extension procedures. Adoption tracks fenestrated and branched graft complexity escalation.
Procurement gravity centers on Stent Grafts, though Surgical Grafts defend emergency niches.
Application:
Reimbursement differentiation between scheduled and urgent presentations reshapes screening investment economics.
- Elective Repair:Scheduled infrarenal interventions in asymptomatic patients with diameter thresholds triggering intervention. Japan's METI-backed cost-effectiveness recalibration elevates preventive reimbursement above emergency thresholds.
- Emergency Intervention:Rupture or symptomatic presentations demanding immediate repair command premium pricing due to compressed decision windows and 24-hour specialized staffing requirements. South Korea's MFDS maintains distinct fatigue-testing standards for emergency-use device platforms.
- Surveillance:Serial imaging protocols for sub-intervention diameter aneurysms. United States Medicare screening eligibility for male smokers drives imaging volume.
- Preventive Therapy:Risk factor modification and pharmacologic management to delay expansion. India's underpenetrated screening infrastructure creates whitespace for mobile ultrasound deployment.
Elective Repair generates volume scale; Emergency Intervention extracts margin premiums.
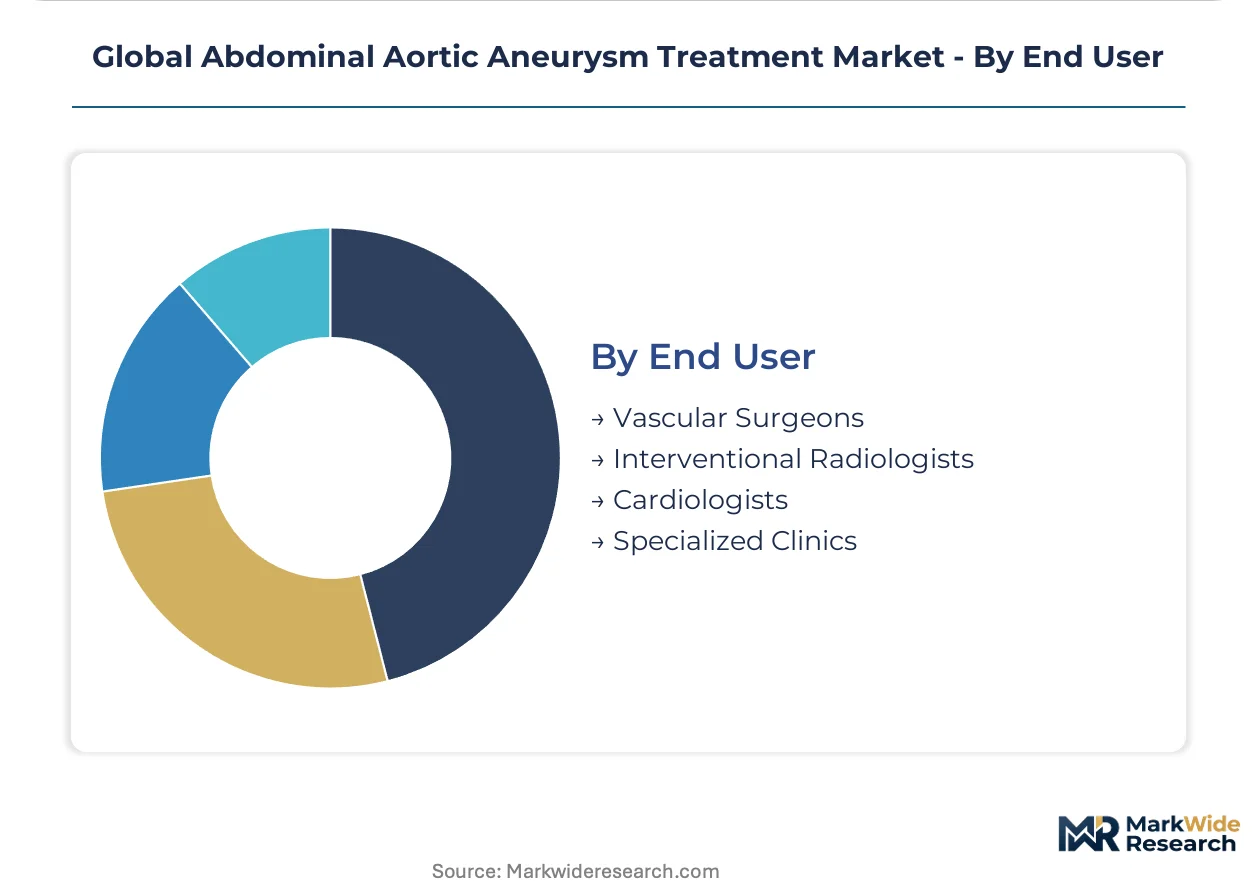
End User:
Specialist discipline boundaries determine device training requirements and purchasing committee composition.
- Vascular Surgeons:Traditional custodians of aortic intervention performing both open and endovascular repairs. Fellowship program output in Germany and the United States constrains expansion of complex fenestrated graft capabilities.
- Interventional Radiologists:Image-guided catheter specialists increasingly co-deploying endovascular platforms in United States hospital outpatient departments. Reimbursement parity disputes with surgical colleagues shape practice economics.
- Cardiologists:Coronary intervention specialists expanding into peripheral vascular territory. Training pipeline heterogeneity limits procedural standardization across South Korean hospital networks.
- Specialized Clinics:Dedicated aortic centers consolidating high-volume elective practice in Tokyo and Osaka metropolitan areas. PMDA reimbursement adjustments concentrate demand in these accredited facilities.
Vascular Surgeons retain procedural control; Interventional Radiologists gain deployment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endovascular repair platforms first achieved commercial scale in United States hospital systems during the late 1990s, establishing the procedural template that German and Japanese regulators later adapted to their national healthcare frameworks.
United States
Medicare screening expansion for male smokers and hospital outpatient department purchasing consolidation drive procedural volume concentration. FDA premarket approval pathways harden evidentiary standards for new graft geometries, extending commercialization timelines. Device procurement gravity centers on Texas and California metropolitan hospital networks where integrated catheter-stent compatibility dominates sourcing criteria.
Germany
Ambulatory surgical center adoption of pre-loaded delivery systems accelerates elective infrarenal repair migration from inpatient settings. EU MDR conformity assessments under CE marking reshape post-market surveillance obligations for nitinol-framed platforms. Stuttgart and Munich academic medical centers anchor fenestrated graft engineering demand for complex juxtarenal anatomies.
Japan
PMDA reimbursement adjustments for aging populations extend preventive intervention coverage beyond emergency thresholds. METI-backed cost-effectiveness recalibration elevates elective repair incentives above rupture presentation pricing. Tokyo and Osaka metropolitan hospital networks concentrate specialized aortic center accreditation and high-volume elective practice.
South Korea
MFDS fatigue-testing standards and distinct biocompatibility protocols fragment regulatory strategy for multinational manufacturers. Expanded screening eligibility for urban elderly populations drives imaging volume in Seoul Capital Area tertiary centers. Daegu-Gyeongbuk regional hospitals develop vascular surgeon training pipelines for complex endovascular deployment.
India
Underpenetrated abdominal aortic aneurysm detection rates in urban tertiary centers create whitespace for mobile ultrasound deployment partnerships. State health ministry screening infrastructure investments lag established markets by approximately fifteen years. Maharashtra and Karnataka urban hospital networks pilot preventive detection programs with metropolitan cardiology referral pathways.
Global Abdominal Aortic Aneurysm Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capability and integrated manufacturing footprint dimensions. Market structure consolidates around three to five dominant platform holders with pre-loaded delivery system bundling power, while mid-cap specialists defend niche positions in fenestrated graft engineering. Strategic archetypes include diversified cardiovascular conglomerates with catheter-stent integration, mid-cap endovascular pure-plays with complex anatomy specialization, and regional Asian manufacturers with cost-optimized commodity platforms. Dominant competitive moves encompass strategic partnerships to fund clinical trial programs and geographic licensing arrangements to navigate fragmented regulatory requirements.
Within the diversified cardiovascular conglomerate tier, Medtronic and Boston Scientific Corporation occupy positions defined by integrated manufacturing footprints and hospital purchasing committee relationships. Cook Medical exemplifies the mid-cap specialist archetype with concentrated expertise in complex anatomical applications. Terumo Corporation represents the Asia-Pacific headquartered multinational with established regulatory navigation capabilities across PMDA and MFDS jurisdictions.
| Leading Market Players |
|---|
| Medtronic |
| Cook Medical |
| W. L. Gore & Associates |
| Cardinal Health |
| Endologix |
| Terumo Corporation |
| Boston Scientific Corporation |
| MicroPort Scientific Corporation |
| Artivion |
| Others |
Supply & Pricing Matrix
Specialized vascular surgeon concentration in German academic medical centers compresses labor-cost differentials between premium fenestrated graft deployment and standard infrarenal repair, widening pricing-tier spreads across EU hospital networks. This workforce scarcity in Stuttgart and Munich anchors premium service pricing while outpatient migration in the United States compresses standard-tier margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with FDA premarket approval tier and CE marking under EU MDR serving as primary price differentiation drivers. Pricing pressure stems from hospital purchasing committee consolidation around integrated catheter-stent bundles in United States outpatient departments. Academic medical centers in Tokyo and Osaka exhibit lowest price sensitivity due to METI-backed reimbursement premiums, while Indian state hospital networks remain most cost-constrained.
Supply Chain Analysis
Reverse-logistics flows for explanted stent grafts remain minimal given permanent implant nature, though nitinol raw material recovery from manufacturing scrap feeds secondary alloy markets. Nitinol superelastic alloy supply concentrates in United States, Germany, and Japan mining-refining corridors, with polyester and ePTFE graft materials drawing from textile chemical processing hubs in China and South Korea. Single-source vulnerability in nitinol superelastic wire exposes manufacturers to commodity price volatility. Distribution runs through hospital procurement committees and GPO contracts in United States metropolitan networks, direct manufacturer relationships in German ambulatory surgical centers, and PMDA-accredited specialized clinic channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR conformity assessment acceleration and PMDA reimbursement recalibration compound demand expansion beyond demographic aging alone.
For Market Incumbents: Anticipate fenestrated graft engineering skill shortages constraining complex procedure volume expansion in German and United States markets. Defend positioning through backward integration into nitinol wire drawing to secure superelastic alloy supply against geopolitical disruption. Prioritize CE marking pathway investments to compress commercialization timelines under EU MDR post-market surveillance obligations. For New Entrants and Emerging Players: Begin with India's underpenetrated mobile ultrasound screening infrastructure as the most penetrable whitespace, where state health ministry partnerships enable preventive detection program deployment ahead of established competitors. Target Maharashtra and Karnataka urban tertiary centers with cost-optimized stent graft platforms. Pursue geographic licensing arrangements to navigate MFDS fatigue-testing standards without duplicate validation investment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap endovascular pure-plays with complex anatomy specialization but limited integrated manufacturing footprints. Long-term viability over the next decade hinges on regulatory navigation bandwidth across FDA, PMDA, and MFDS jurisdictions. Monitor EU MDR periodic safety update report filing rates as the inflection signal for compliance cost burden differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments compress commercialization timelines for nitinol-framed graft platforms entering German markets. |
| Hospital System Partnership | United States outpatient department purchasing consolidation rewards integrated catheter-stent compatibility guarantees. |
| Software Companion Development | Computed tomography segmentation tools enable 3D-printed patient-specific fenestration patterns for hostile neck anatomies. |
| Reimbursement Strategy | METI-backed cost-effectiveness recalibration in Japan elevates elective repair incentives above emergency thresholds. |
| Backward Integration | Captive nitinol superelastic alloy supply mitigates raw material concentration risk in United States and German manufacturing. |
Research Methodology
Direct dialogue with vascular surgeons, interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers grounded qualitative insights, validated against FDA premarket approval filings, PMDA reimbursement databases, EU MDR conformity assessment records, and hospital procurement transaction data. Bottom-up and top-down triangulation reconciled procedural volume estimates with device shipment records across the analysis window.
Bottom-up modeling anchored in treatment modality segmentation, device type procurement patterns, application-specific reimbursement pathways, and end-user discipline boundaries. CAGRs derived from regression analysis against aging population screening eligibility expansion, regulatory timeline compression effects, and technology substitution curves. Industry-specific forecast inputs incorporated EU MDR transition completion rates and PMDA preventive intervention incentive adjustments.
Several conditions sit outside the modeled scope, including emergency rupture presentation volume volatility, open surgical graft substitution ceiling effects, and nitinol supply chain disruption scenarios. Forecasts reflect assumptions about regulatory pathway stability and screening program funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
UAE Cardiovascular Devices Market