
 Portable Diagnostic Devices Market | 2026-2036
Portable Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Diagnostic Devices Market Outlook
Subscription-based leasing and pay-per-test financing is reconfiguring capital deployment across the portable diagnostics value chain, allowing smaller clinics and home-care networks to access premium instrumentation without upfront equipment purchases. Abbott Laboratories leverages its vertically integrated biosensor manufacturing to sustain margin control across glucose monitoring portfolios. Roche Diagnostics anchors its competitive position through specialized optical chemistry platforms that dominate laboratory-caliber accuracy in handheld formats. Siemens Healthineers competes by extending its imaging expertise into portable ultrasound systems with proprietary transducer miniaturization.
Portable diagnostic devices are compact, battery-powered instrumentation designed to perform clinical assays or physiological measurements outside centralized laboratory infrastructure, typically operating with sample volumes below 500 microliters and delivering results within fifteen minutes for acute-care decision support. Their primary commercial purpose is to collapse the temporal and spatial gap between patient presentation and actionable diagnostic data. Point-of-care systems command the largest revenue pool due to their deployment across emergency services and rural clinics where infrastructure scarcity elevates willingness-to-pay for rapid turnaround. Smartphone-integrated delivery modes represent the fastest-expanding segment as microfluidics and electrochemical sensor architectures shrink sufficiently to embed within consumer electronics form factors. Biosensor technology underpins the most defensible margin structure because enzyme and antibody immobilization processes create formulation IP barriers that commodity optical components cannot replicate.
FDA 510(k) clearance timelines and EMA's In Vitro Diagnostic Regulation shape product development roadmaps by mandating clinical validation cohorts that extend R&D cycles and favor incumbents with established quality management systems. The EU AI Act adds compliance layers for algorithm-enabled devices that interpret raw sensor signals into diagnostic recommendations, creating divergence between software-embedded and hardware-only product strategies. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and the United States calibrate remote monitoring codes against real-world evidence thresholds, as these decisions will determine which delivery modes achieve economic viability at scale.
Market Dynamics
Decentralized healthcare delivery is compressing the diagnostic workflow from centralized laboratories to point-of-care settings, forcing manufacturers to miniaturize optical and electrochemical platforms without sacrificing analytical accuracy.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:Stabilized CPT codes in the United States now compensate physicians for continuous glucose and cardiac marker surveillance outside hospital walls, accelerating capital deployment into ambulatory networks.
- Microfluidic Integration:Advances in lab-on-chip architectures enable multiplexed assays from capillary blood volumes, expanding test menus in resource-constrained emergency departments and rural clinics.
- EMA Streamlined Pathways:The In Vitro Diagnostic Regulation's performance-based conformity routes compress EMA clearance timelines for Class B and C devices, rewarding manufacturers with established quality management systems.
Market Restraints
- Precious Metal Input Volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress gross margins for disposable test strip producers, forcing reformulation toward carbon-based alternatives.
- Optics Supply Concentration:German and Japanese specialty glass manufacturers control photonic component supply for fluorescence-based readers, creating single-source vulnerability for handheld immunoassay platforms.
- EU AI Act Compliance Burden:Algorithm-enabled diagnostic interpretation now requires notified body review of training datasets and performance monitoring systems, extending R&D cycles for software-embedded devices.
Strategic Opportunities
- Home Hemodialysis Monitoring:Underpenetrated self-care markets in Germany and Japan present white space for creatinine and electrolyte meters designed for residential use with nephrology telemedicine integration.
- 5G-Enabled Real-Time Transmission:Convergence of low-latency cellular networks with edge-computing diagnostics enables ambulance-based troponin results to trigger cath lab activation before hospital arrival.
- Subscription Leasing Models:Pay-per-test financing reconfigures capital deployment for smaller clinics, allowing premium instrument access without upfront equipment purchases.
Industry Challenges
- Multidisciplinary Talent Scarcity:The intersection of microfluidics engineering, clinical biochemistry, and regulatory affairs commands premium compensation, constraining scale-up velocity for emerging manufacturers.
- Interoperability Friction:Legacy hospital information systems lack standardized APIs for point-of-care device data streams, forcing costly middleware development for EHR integration.
- Clinical Validation Burden:FDA 510(k) submissions now require prospective studies against predicate devices, extending time-to-revenue for novel biomarker platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Diagnostic Devices Market |
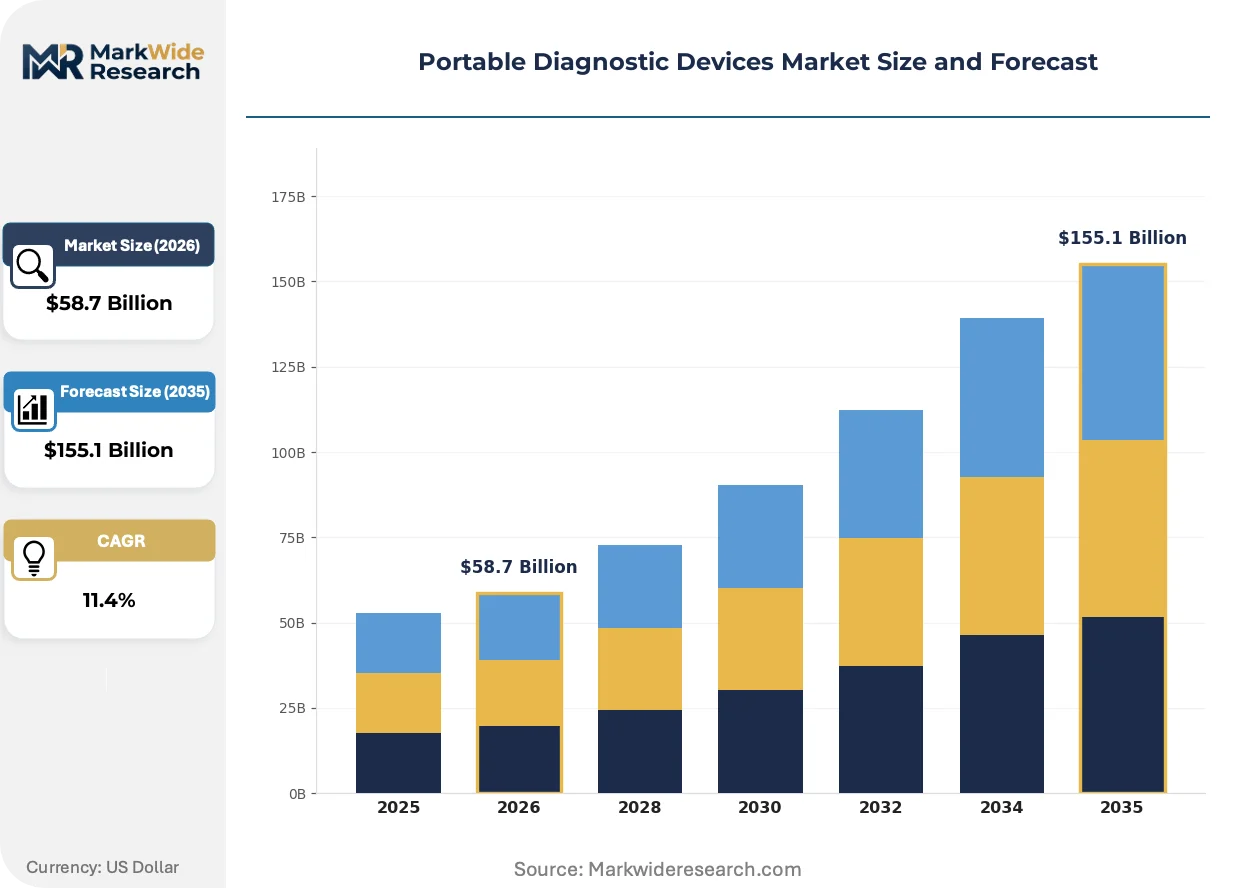
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Care, Glucometers, ECG Monitors, Portable Ultrasound Technology: Biosensors, Optical, Electrochemical, Microfluidics End User: Clinics, Home Care, Emergency Services, Laboratories Delivery Mode: Handheld, Wearable, Smartphone-Integrated, Diagnostic Kit |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Philips Healthcare, GE Healthcare, Medtronic, Becton Dickinson and Company, Thermo Fisher Scientific, Mindray Medical International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Diagnostic Devices Market Strategic Shifts
Electrochemical biosensor miniaturization and algorithmic signal processing are converging to enable diagnostic-grade accuracy within consumer electronics form factors, rewriting competitive boundaries between medical device and technology hardware sectors.
CMOS-integrated photodetection arrays is collapsing the cost structure of fluorescence-based immunoassay readers. Emergency departments in the United States and tertiary hospitals in Japan are adopting these silicon-based alternatives to traditional photomultiplier tubes, compressing the price-performance gap between laboratory and point-of-care platforms.
FDA's evolving guidance on artificial intelligence-enabled devices is mandating predetermined change control plans for machine learning algorithms that interpret raw sensor signals. Manufacturers must now submit protocols for post-market performance monitoring before clearance, shifting development resources toward clinical validation infrastructure rather than algorithm refinement.
Hospital procurement committees are unbundling after-sales service contracts from instrument purchases, demanding à-la-carte maintenance options and third-party calibration verification. This pattern is most pronounced in German hospital networks, where centralized purchasing cooperatives negotiate multi-vendor service agreements independent of capital equipment tenders.
Portable Diagnostic Devices Market Segmentation
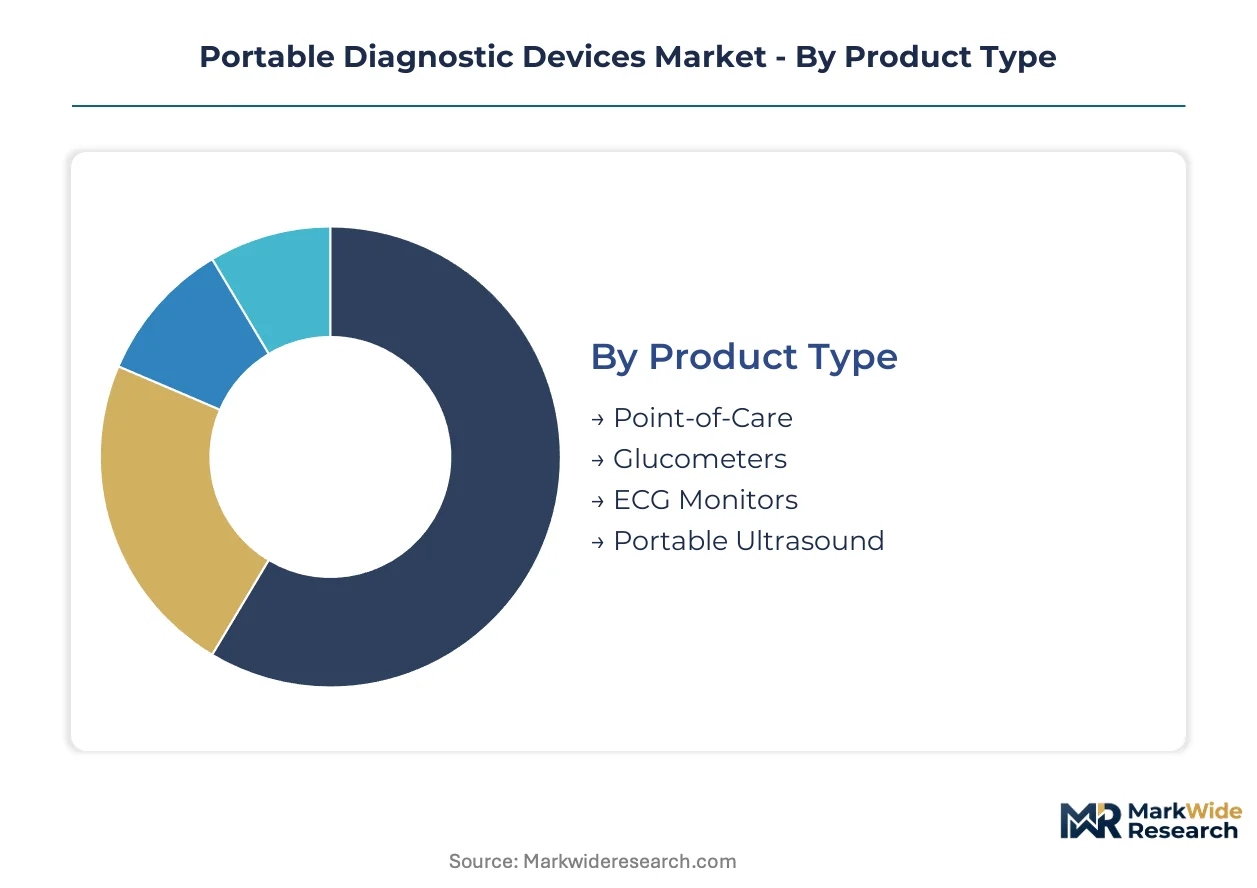
Portable diagnostic devices fragment across multiple technical and commercial dimensions. Understanding these boundaries clarifies where margin concentrates and which configurations face regulatory or reimbursement headwinds.
Product Type:
Cost tier determines hardware sophistication, with premium optical systems commanding hospital budgets while single-use electrochemical strips penetrate price-sensitive home segments.
- Point-of-Care:Multiplexed platforms integrate sample preparation, assay execution, and result display within sealed cartridges. Demand clusters in United States emergency departments and Japanese rural clinics where infrastructure scarcity elevates willingness-to-pay for rapid turnaround.
- Glucometers:Enzyme-immobilized electrochemical strips dominate glucose surveillance through capillary blood volumes. Germany's home-care reimbursement frameworks stabilize recurring revenue for connected meter ecosystems.
- ECG Monitors:Single-lead to twelve-lead configurations enable arrhythmia detection outside cardiology suites.
- Portable Ultrasound:Phased-array transducers deliver imaging resolution previously confined to cart-based systems.
Point-of-Care commands the established base. The steepest expansion runs through Portable Ultrasound.
Technology:
Application context dictates sensor selection, with acute-care settings prioritizing accuracy while consumer formats emphasize miniaturization and power efficiency.
- Biosensors:Enzyme and antibody immobilization on electrode surfaces enables substrate-specific detection with minimal sample preparation. Abbott Laboratories leverages captive manufacturing of glucose oxidase formulations to sustain margin control.
- Optical:Fluorescence and absorbance-based detection deliver laboratory-caliber sensitivity in handheld immunoassay readers. Japanese specialty glass manufacturers control photonic component supply, creating single-source vulnerability for fluorescence-based platforms.
- Electrochemical:Amperometric and potentiometric methods translate biochemical events into electrical signals.
- Microfluidics:Lab-on-chip architectures manipulate sub-microliter volumes through passive capillary forces.
Biosensors anchor current revenue. Microfluidics is climbing the fastest as multiplexed assay menus expand.
End User:
Customer type shapes procurement patterns, with institutional buyers negotiating service bundles while individual consumers prioritize retail accessibility and subscription pricing.
- Clinics:Ambulatory networks deploy portable chemistry and hematology platforms to reduce send-out laboratory dependency. United States CPT code stabilization for remote patient monitoring accelerates capital deployment into these settings.
- Home Care:Patients with chronic conditions perform self-monitoring between clinical encounters. Japan's aging demographic and Germany's nephrology telemedicine integration drive demand for residential creatinine and electrolyte meters.
- Emergency Services:Pre-hospital troponin and lactate testing guides triage decisions.
- Laboratories:Satellite and near-patient testing extensions of centralized core labs.
Clinics represent the deepest installed base. Home Care is gaining share fastest through reimbursement alignment.
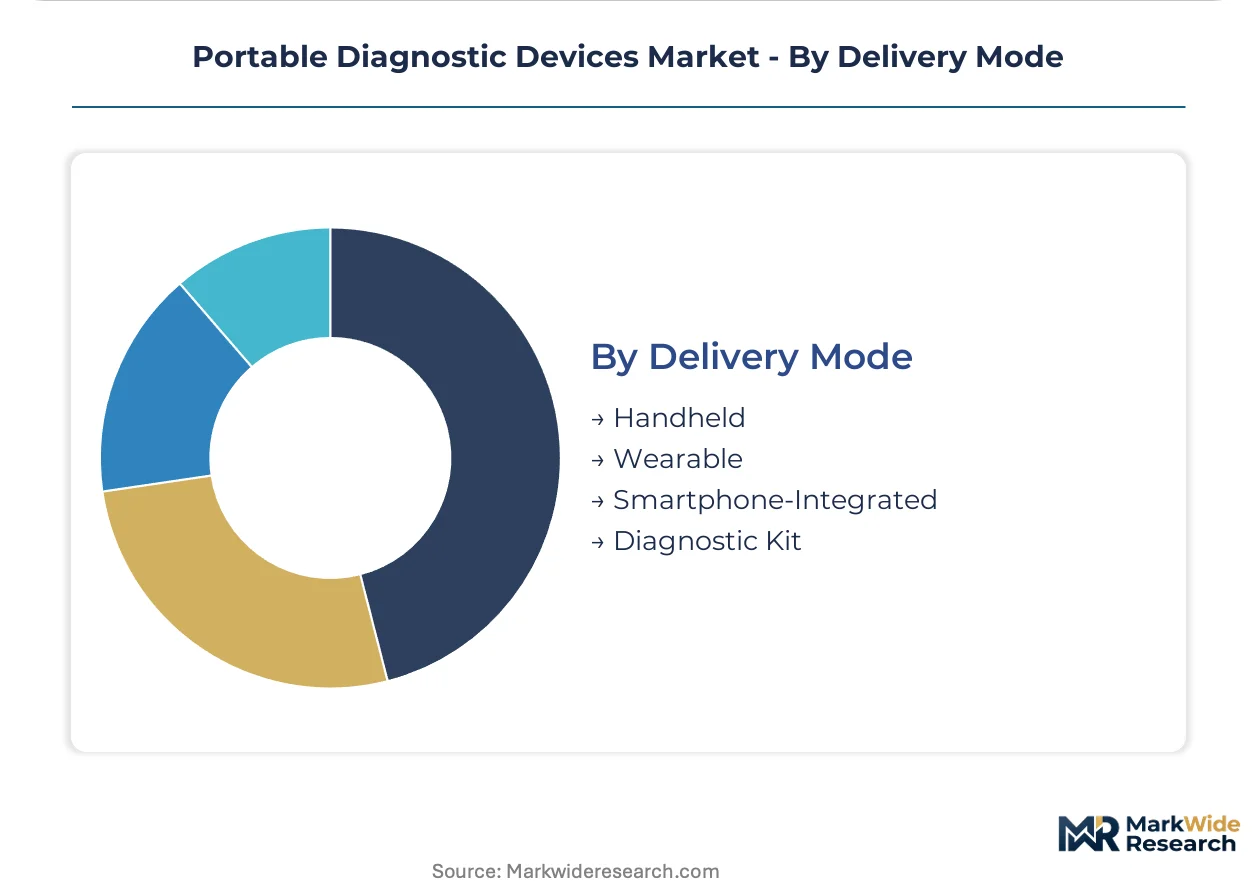
Delivery Mode:
Form factor maturity ranges from established handheld instruments to emerging smartphone-integrated architectures that collapse hardware costs through consumer electronics scale.
- Handheld:Dedicated single-purpose devices with integrated displays and onboard processing dominate current deployment. Emergency services in the United States and tertiary hospitals in Japan adopt these for immediate clinical decision support.
- Smartphone-Integrated:Microfluidic cartridges and electrochemical dongles leverage mobile computing power and connectivity. FDA and EMA clearance pathways for these configurations compress time-to-market for algorithm-enabled interpretation.
- Wearable:Continuous monitoring through skin-interfaced sensors.
- Diagnostic Kit:Single-use consumables with minimal instrumentation requirements.
Handheld configurations retain volume leadership. Smartphone-Integrated delivery is expanding most quickly as sensor miniaturization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement stability for remote patient monitoring in Germany, Japan, and the United States is accelerating capital deployment into ambulatory diagnostic networks. FDA and EMA clearance pathway refinements are compressing time-to-market for smartphone-integrated devices. Manufacturing clusters in precision optics and electrochemical sensors concentrate in specific metropolitan regions.
United States
Stabilized CPT codes now compensate physicians for continuous glucose and cardiac marker surveillance outside hospital walls. FDA 510(k) submissions require prospective studies against predicate devices, extending validation timelines for novel biomarker platforms. Emergency departments in metropolitan hospital networks adopt CMOS-integrated photodetection arrays for fluorescence-based immunoassay readers.
Germany
Centralized purchasing cooperatives negotiate multi-vendor service agreements independent of capital equipment tenders. EMA's In Vitro Diagnostic Regulation performance-based conformity routes compress clearance timelines for Class B and C devices. Bavaria's precision optics manufacturers control photonic component supply for handheld diagnostic platforms.
Japan
Aging demographics drive demand for residential creatinine and electrolyte meters with nephrology telemedicine integration. PMDA regulatory frameworks align with international standards for point-of-care device approvals. Tertiary hospitals in the Kanto region adopt portable ultrasound systems with proprietary transducer miniaturization.
China
NMPA streamlined review pathways for innovative medical devices accelerate domestic market entry for electrochemical biosensor platforms. Provincial healthcare procurement reforms favor cost-competitive point-of-care systems for rural clinic networks. Yangtze River Delta manufacturing clusters specialize in microfluidic cartridge production for smartphone-integrated diagnostics.
United Kingdom
NHS long-term plan commitments expand community-based diagnostic capacity through point-of-care testing deployment. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for algorithm-enabled devices. London-Southeast research institutions concentrate clinical validation infrastructure for novel biomarker platforms.
Portable Diagnostic Devices Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated biosensor manufacturers and diversified diagnostic conglomerates with captive optical chemistry platforms. Three archetypes dominate: enzyme immobilization specialists controlling formulation IP, optical system integrators leveraging precision photonics supply chains, and imaging technology extenders miniaturizing transducer architectures. Competitive moves center on strategic partnerships for microfluidic cartridge development and backward integration into specialty glass and electrode material supply.
Within the diversified diagnostic tier, Abbott Laboratories, Roche Diagnostics, and Siemens Healthineers exemplify distinct competitive positions. Abbott's captive glucose oxidase manufacturing represents backward integration into enzyme formulation supply. Roche's specialized optical chemistry platforms anchor laboratory-caliber accuracy in handheld formats. Siemens extends imaging expertise into portable ultrasound through proprietary transducer miniaturization capabilities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| Mindray Medical International |
| Others |
Value Chain & Pricing Dynamics
German and Japanese specialty glass manufacturers command photonic component supply for fluorescence-based immunoassay readers, anchoring margin capture in optical detection tiers while carbon-based electrode alternatives reshape electrochemical strip economics.
Pricing Analysis
Certification level creates the primary spread across portable diagnostic price tiers. FDA 510(k)-cleared and CE-IVD-marked devices command substantial premiums over research-use-only configurations. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and calibration support intensity. Cost compression in disposable test strips intensifies as manufacturers reformulate platinum electrodes toward carbon alternatives. Home-care segments exhibit highest price sensitivity, while emergency services prioritize turnaround speed over unit cost.
Supply Chain Analysis
Electronics manufacturing services in China, Malaysia, and Mexico hold contract assembly capacity for handheld diagnostic platforms. Microfluidic cartridge production draws from Yangtze River Delta precision molding clusters. Platinum and palladium supply from South African and Russian mining operations creates commodity price volatility exposure. Distribution runs through hospital purchasing cooperatives in Germany, GPO contracts in the United States, and provincial procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-integrated diagnostic architectures are compressing hardware cost structures and collapsing traditional competitive boundaries between medical device and consumer electronics sectors.
For Market Incumbents: Pre-empt algorithm-enabled device proliferation by acquiring machine learning validation capabilities before EU AI Act compliance burdens harden. Lock in multi-year supply agreements with Bavarian photonics specialists to defend against single-source vulnerability. Accelerate backward integration into enzyme formulation supply to neutralize emerging biosensor competitors. For New Entrants and Emerging Players: Establish a beachhead in Japan's residential hemodialysis monitoring segment where aging demographics and nephrology telemedicine integration create reimbursement-aligned white space. Target smartphone-integrated delivery modes where FDA and EMA clearance pathways compress time-to-market versus traditional handheld formats. Pursue pay-per-test financing partnerships with ambulatory networks to bypass capital equipment procurement friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed point-of-care platform specialists lacking algorithm development infrastructure. Five-to-ten year viability hinges on successful navigation of software-embedded device regulatory divergence between FDA and EMA frameworks. Monitor PMDA alignment with international standards as signal for Japanese market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses validation timelines for novel biomarker platforms against predicate devices. |
| CE Marking Pathway Optimization | Leverages EMA performance-based conformity routes for Class B and C device clearance. |
| Hospital System Partnership | Unlocks GPO contract access and EHR integration requirements for point-of-care deployment. |
| Software Companion Development | Enables algorithm-enabled diagnostic interpretation under predetermined change control plans. |
| Reimbursement Strategy Alignment | Secures CPT code coverage for remote patient monitoring in United States ambulatory networks. |
Study Parameters
Desk research of FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, and hospital procurement databases preceded structured interviews with biomedical engineers, GPO contracts managers, and point-of-care device product managers. Primary fieldwork with clinicians and regulatory affairs specialists validated secondary findings on clearance pathway timelines. Bottom-up instrument shipment modeling and top-down healthcare expenditure allocation were cross-referenced for triangulation.
Assumptions held reimbursement code stability in the United States, Germany, and Japan constant while varying microfluidic integration rates and smartphone-embedded sensor adoption curves across the analysis window. Segmentation dimensions included product type, technology platform, end-user setting, and delivery mode. CAGRs derived from logistic diffusion curves fitted to historical point-of-care testing penetration patterns, with sensitivity to precious metal input cost trajectories and optical component supply constraints.
Sensitivities concentrate around EU AI Act implementation timelines, platinum price volatility, and German hospital purchasing cooperative negotiation outcomes. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and reimbursement stability. Quarterly review of FDA guidance document releases, EMA notified body capacity indicators, and CMS remote monitoring code valuation updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Europe Point of Care Diagnostics Market