
 Global Abdominal Surgical Robot Market | 2026-2036
Global Abdominal Surgical Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Abdominal Surgical Robot Market Intelligence
Advanced robotics manufacturers in Germany and Switzerland are pivoting toward modular system architectures to challenge incumbent market leaders. Intuitive Surgical sustains its dominant market share through a large installed base and extensive surgeon training programs. Medtronic competes by bundling robotic systems with its broader portfolio of surgical instruments and consumables. Johnson & Johnson leverages its global hospital network to introduce its integrated digital surgery platform, creating a comprehensive ecosystem for surgical procedures.
Abdominal surgical robots are mechatronic systems with a patient-side cart, a surgeon's console, and a 3D vision system. The robotic arms provide enhanced dexterity, often with seven degrees of freedom, to enable minimally invasive procedures. Laparoscopic robots form the core product category, while systems with haptic feedback and artificial intelligence see rapid uptake. Gastrointestinal surgery and colorectal procedures represent the largest application segments due to high procedural volumes.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA), the European Medicines Agency (EMA), and China's National Medical Products Administration (NMPA) is stringent. These agencies enforce rigorous pre-market approval pathways and post-market surveillance, shaping product development cycles and market access strategies. Future platform differentiation will hinge on demonstrating quantifiable improvements in surgical outcomes and reducing the total cost of care for hospital providers.
Market Dynamics
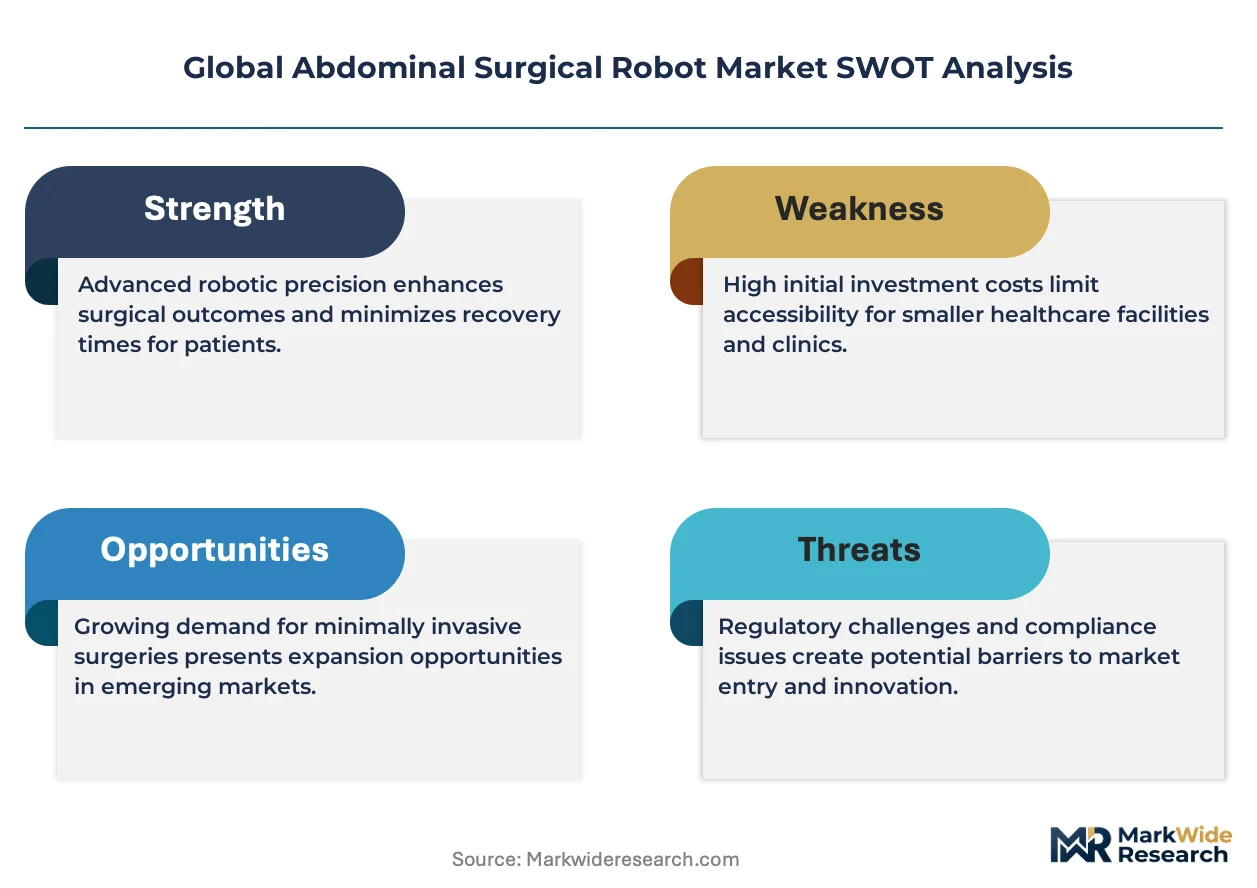
The central dynamic shaping the abdominal surgical robot market is the pivot from demonstrating technical feasibility to proving economic value. Hospital providers now demand quantifiable improvements in clinical outcomes and a reduction in the total cost of care, shifting manufacturer focus toward data analytics and procedural efficiency.
Growth Catalysts
- Procedure Volume Expansion:Growth in high-volume procedures such as bariatric and colorectal surgeries, particularly within aging populations in countries like Germany and Japan, creates a consistent demand stream for robotic systems.
- Value-Based Healthcare Initiatives:Policy shifts in the United States toward reimbursement models that reward improved patient outcomes and reduced hospital stays incentivize the adoption of minimally invasive robotic technologies.
- Artificial Intelligence Integration:The maturation of AI for enhanced 3D visualization and surgical planning, supported by FDA and EMA pathways for Software as a Medical Device (SaMD), enhances system capabilities.
Market Restraints
- High Capital Expenditure:The substantial upfront acquisition cost of robotic systems, coupled with ongoing expenses for maintenance and proprietary instruments, restricts adoption to large, well-funded hospital networks.
- Steep Surgical Learning Curve:Surgeons require extensive, specialized training to achieve proficiency with robotic platforms, creating a bottleneck that slows the return on investment for healthcare providers and limits system utilization.
- Lack of Interoperability:Proprietary, closed-ecosystem designs for most robotic platforms hinder integration with existing hospital IT systems and third-party instruments, creating workflow inefficiencies and data silos.
Strategic Opportunities
- Ambulatory Surgical Centers:Developing smaller-footprint, lower-cost robotic systems specifically for outpatient procedures like hernia repair can unlock the large and growing ambulatory surgical center market segment.
- Telesurgery Development:Leveraging 5G network expansion to enable remote proctoring and telesurgery addresses specialist shortages in rural areas of countries like Australia and Canada, expanding geographic reach. *Data Monetization: Creating new revenue streams through subscription-based access to advanced software, including pre-operative planning tools and post-operative performance analytics, offers a path beyond hardware sales.
Industry Challenges
- Specialized Talent Scarcity:A shortage of trained robotic surgeons, specialized nurses, and technicians capable of operating and maintaining these complex systems constrains the pace of adoption for many hospitals.
- Cybersecurity and Data Privacy:Securing connected robotic platforms from cyberattacks and ensuring compliance with patient data regulations like HIPAA in the US and GDPR in Europe is a complex operational challenge.
- Reimbursement Ambiguity:Inconsistent and evolving reimbursement policies for robotic-assisted procedures across different public and private payers create financial uncertainty for healthcare providers evaluating system purchases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Abdominal Surgical Robot Market |
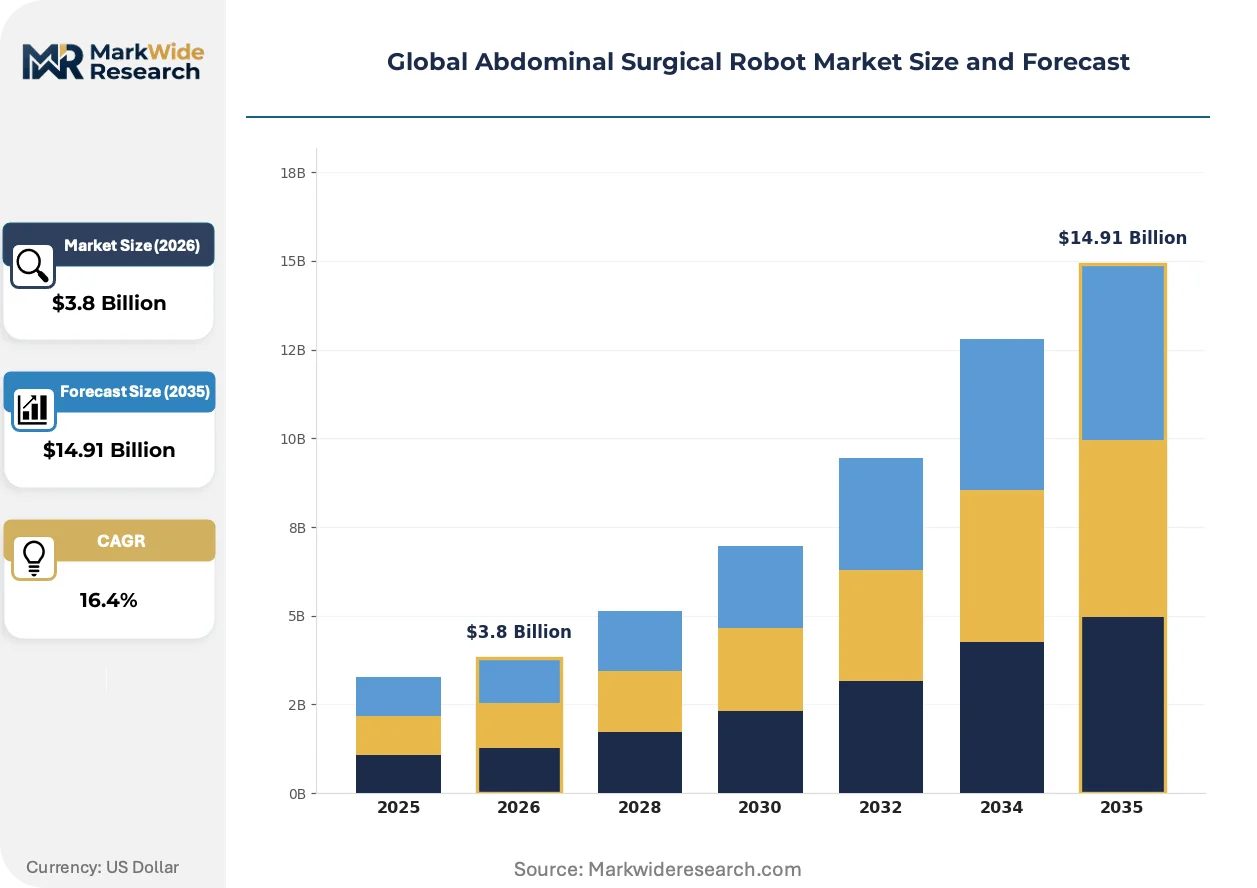
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Robots, Laparoscopic Robots, Endoscopic Robots, Assistive Robots, Autonomous Robots Technology: Haptic Feedback, 3D Visualization, Motion Scaling, Voice Recognition, Artificial Intelligence Application: Gastrointestinal Surgery, Colorectal Procedures, Hepatobiliary Surgery, Urological Surgery, Bariatric Procedures End User: Specialty Surgical Centers, Academic Medical Institutions, Private Medical Clinics, Government Hospitals, Ambulatory Surgery Centers |
| Companies Covered | Intuitive Surgical, Medtronic, Stryker Corporation, CMR Surgical Ltd, Johnson & Johnson, Smith & Nephew, Zimmer Biomet, TransEnterix Surgical, Accuray Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Abdominal Surgical Robot Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of hardware miniaturization with advanced software intelligence. This combination is creating more accessible, data-driven surgical ecosystems that extend beyond the physical capabilities of the robot itself, focusing on the entire perioperative workflow.
Single-port and specialized instrument systems provide surgeons with enhanced access for complex procedures through a single, small incision. Hospitals and specialty surgical centers are the primary adopters, seeking to minimize patient trauma and recovery times. This technology is modularizing the operating room, enabling facilities to configure platforms for specific procedural needs rather than investing in monolithic, all-purpose systems.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This regulation is forcing manufacturers to generate more robust, long-term data demonstrating the safety and efficacy of their robotic systems. The colorectal and gynecological surgery segments are most affected, heavily investing in clinical trials to maintain CE marking and market access.
A shift from one-time capital purchases to flexible, usage-based financial models is altering hospital acquisition strategies. This disrupts the traditional sales cycle, replacing it with long-term partnership agreements that often bundle instruments, service, and software upgrades. This trend is most visible in large United States hospital networks seeking to manage capital budgets more effectively and align costs with procedural volume.
Global Abdominal Surgical Robot Market Segmentation
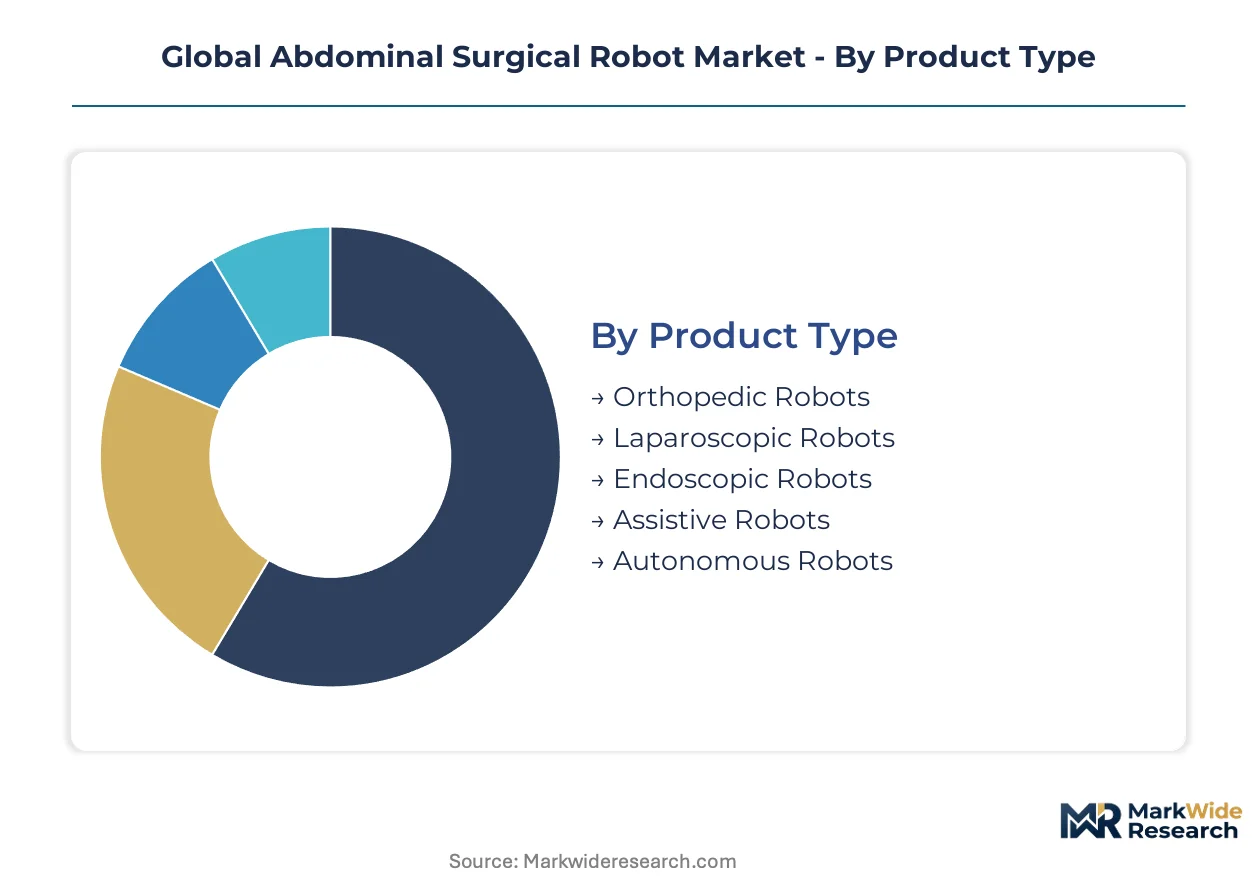
The global abdominal surgical robot market segments across various dimensions, reflecting diverse product capabilities, technological advancements, and end-user requirements. Understanding these segments is crucial for manufacturers tailoring solutions and for healthcare providers optimizing their investment strategies. This detailed breakdown highlights areas of concentrated demand and innovation.
Product Type:
The product type segmentation reveals a spectrum from highly specialized, standardized systems to more customizable, modular robotic platforms. This differentiation influences procurement decisions based on surgical volume and specific procedural needs.
- Laparoscopic Robots:These mechatronic systems form the foundation of minimally invasive abdominal surgery, offering enhanced dexterity and 3D visualization. Demand concentrates in large hospital networks in the United States, driven by established procedural protocols and surgeon familiarity.
- Autonomous Robots:These advanced systems integrate artificial intelligence for independent task execution or highly guided surgical assistance, minimizing human intervention. Their uptake is currently limited to research institutions and highly specialized centers in Germany, focusing on complex, repetitive tasks.
- Orthopedic Robots:These robots assist in precise bone cutting and implant placement, primarily for joint replacement procedures, though not directly abdominal.
- Endoscopic Robots:These systems navigate internal body cavities via natural orifices, supporting diagnostic and therapeutic interventions within the GI tract.
- Assistive Robots:These platforms provide real-time guidance and instrument stabilization, augmenting surgeon capabilities without full automation.
Leading the category by volume: Laparoscopic Robots. Growing fastest: Autonomous Robots.
Technology:
Technology segmentation reflects the maturity curve of integrated features, spanning foundational capabilities to cutting-edge innovations. Each technological advancement aims to improve surgical precision, reduce invasiveness, or enhance surgeon control and feedback mechanisms.
- Artificial Intelligence:AI systems enhance surgical planning and intraoperative guidance through advanced image processing and predictive analytics. Adoption is accelerating in academic medical institutions across Europe, driven by regulatory support for Software as a Medical Device.
- Haptic Feedback:This technology provides tactile sensations to the surgeon, replicating the feel of tissue interaction and improving surgical precision. Its integration is a significant differentiator for advanced robotic platforms in the United States, enhancing safety during delicate procedures.
- 3D Visualization:High-definition stereoscopic imaging offers depth perception, critical for complex minimally invasive procedures.
- Motion Scaling:This feature translates large surgeon hand movements into smaller, more precise instrument movements, enhancing dexterity.
- Voice Recognition:Voice commands allow surgeons to control robot functions hands-free, streamlining workflow in the operating room.
Key for precision: Haptic Feedback. Driving future innovation: Artificial Intelligence.
Application:
Application segmentation illustrates the procedural volumes driving robotic system utilization across various surgical specialties. High-volume procedures offer significant opportunities for efficiency gains and patient outcome improvements through robotic assistance.
- Bariatric Procedures:These surgeries address severe obesity, often requiring complex maneuvers in confined spaces, making robotic assistance highly beneficial. Growth is particularly strong in specialty surgical centers in the United States, linked to rising obesity rates.
- Colorectal Procedures:Robotic platforms facilitate precise resections and anastomoses in colorectal surgery, minimizing trauma and recovery times for patients. These procedures represent a substantial application segment globally, with increasing demand in aging populations like Japan.
- Gastrointestinal Surgery:This broad category includes procedures on the stomach, small intestine, and esophagus, benefiting from robotic precision.
- Hepatobiliary Surgery:Complex liver, gallbladder, and bile duct procedures gain from enhanced visualization and instrument control.
- Urological Surgery:Robotic systems are well-established for prostatectomies and nephrectomies, offering superior outcomes.
Procedures with largest volume: Colorectal Procedures. Expanding most quickly: Bariatric Procedures.
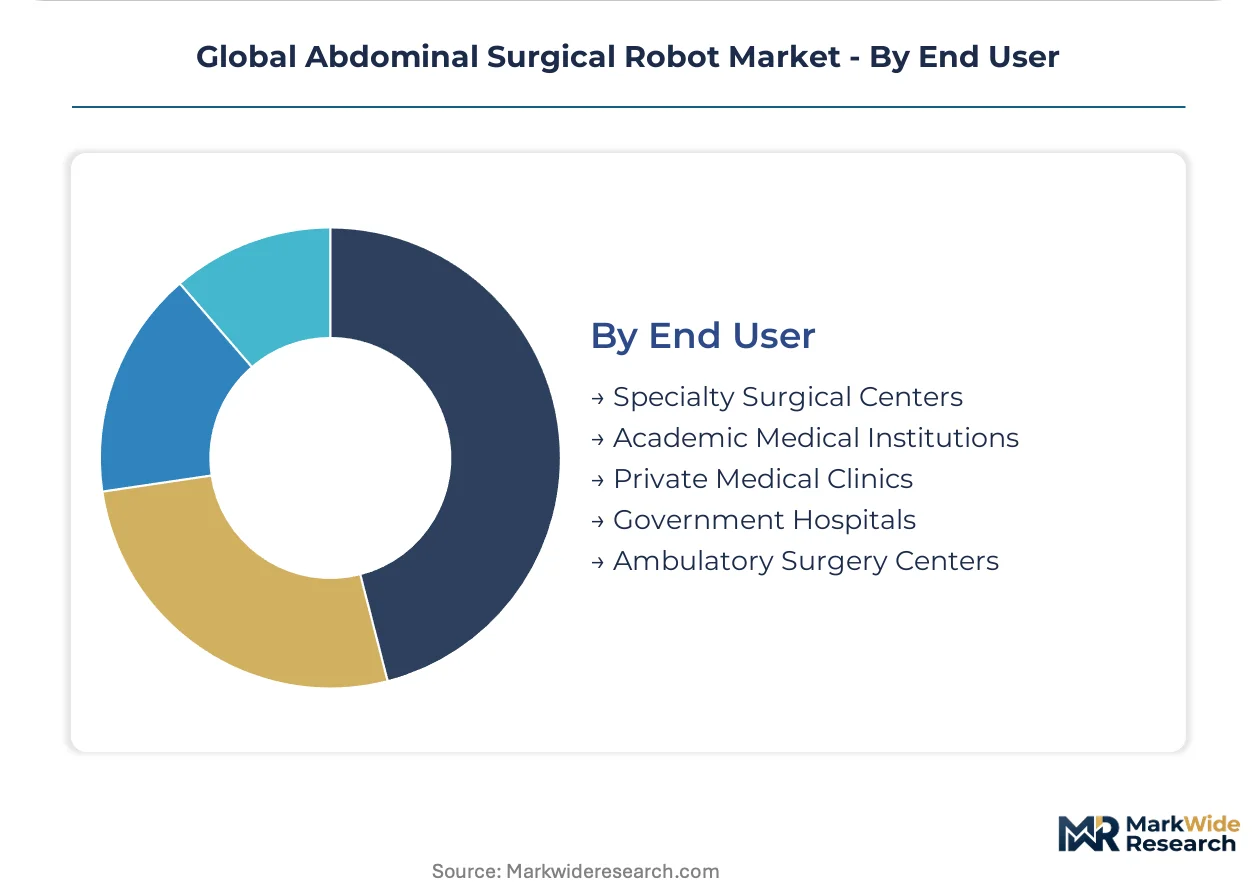
End User:
End-user segmentation highlights the varying procurement capabilities and strategic priorities of different healthcare institutions. Each facility type evaluates robotic systems based on patient volume, capital expenditure budgets, and specialized surgical requirements.
- Specialty Surgical Centers:These centers focus on specific surgical disciplines, often prioritizing efficiency and rapid patient turnover for elective procedures. They are a significant demand driver in the United States, particularly for bariatric surgeries, due to focused investment.
- Academic Medical Institutions:These institutions combine patient care with research and education, often adopting advanced robotic technologies for complex cases and surgeon training. They represent early adopters for new AI-integrated systems across Germany and Switzerland.
- Private Medical Clinics:Smaller, privately-owned clinics typically have limited capital budgets, restricting adoption to less expensive or shared robotic platforms.
- Government Hospitals:Publicly funded hospitals balance patient access with cost-effectiveness, favoring systems that demonstrate clear economic value.
- Ambulatory Surgery Centers:These outpatient facilities require smaller footprint, lower-cost systems for rapid, less invasive procedures like hernia repair.
Largest purchasing power: Academic Medical Institutions. Emerging growth segment: Ambulatory Surgery Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors significant demand for abdominal surgical robots, driven by its advanced healthcare infrastructure and high procedural volumes. This market's geographical distribution reflects varying healthcare policies and technological adoption rates across developed economies. Significant investment in robotic systems is concentrated in regions prioritizing minimally invasive surgery and value-based care.
United States
United States demand for abdominal surgical robots stems from high capital expenditure budgets within large hospital networks. Value-based healthcare initiatives, particularly Medicare reimbursement models, incentivize the adoption of technologies that reduce hospital stays. Major hospital systems in urban centers like Boston are leading in integrating advanced robotic platforms.
Germany
Germany showcases strong demand for sophisticated robotic systems, propelled by advanced robotics manufacturers and academic medical institutions. The European Medicines Agency (EMA) regulatory pathways for Software as a Medical Device support artificial intelligence integration. Research hubs in cities like Heidelberg are at the forefront of developing and implementing AI-enhanced surgical planning tools.
Japan
Japan's market for abdominal surgical robots is shaped by an aging population and a high volume of colorectal procedures. The Ministry of Health, Labour and Welfare (MHLW) reviews reimbursement policies for advanced medical technologies. Hospitals across the Kanto region, particularly in Tokyo, are strategically investing in robotic systems to manage increasing surgical demands.
Switzerland
Switzerland, home to advanced robotics manufacturers, also sees significant adoption within its academic medical institutions. Swissmedic's stringent regulatory oversight ensures high-quality, clinically proven robotic systems gain market access. Research and development clusters around Lausanne are actively pioneering modular surgical robot designs and advanced haptic feedback systems.
Australia
Australia presents an opportunity for telesurgery development to address specialist shortages in rural and remote areas. The Therapeutic Goods Administration (TGA) ensures strict compliance for medical devices, including robotic platforms, before market entry. Hospitals in Melbourne are actively piloting remote proctoring programs to enhance surgeon training and expand access to robotic-assisted procedures.
Global Abdominal Surgical Robot Market Key Industry Players
Global majors compete with regional champions across technological innovation and market penetration within the abdominal surgical robot market. This landscape is largely consolidated, dominated by a few established incumbents, advanced robotics specialists, and diversified medical device conglomerates. Competition centers on enhancing system capabilities, expanding geographic reach, and demonstrating economic value to healthcare providers. Strategic partnerships, extensive surgeon training programs, and portfolio diversification represent common competitive moves.
Within the established incumbent tier, Intuitive Surgical exemplifies market dominance through its extensive installed base and comprehensive surgeon training programs, which foster deep customer loyalty. Medtronic occupies a position as a diversified medical device conglomerate, strategically bundling robotic systems with its broader portfolio of surgical instruments and consumables to enhance market penetration. Johnson & Johnson represents another major player, leveraging its global hospital network to introduce an integrated digital surgery platform, creating a comprehensive ecosystem for surgical procedures and expanding its footprint.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Stryker Corporation |
| CMR Surgical Ltd |
| Johnson & Johnson |
| Smith & Nephew |
| Zimmer Biomet |
| TransEnterix Surgical |
| Accuray Incorporated |
| Others |
Cost & Logistics Intelligence
Vertical integration into proprietary instrument manufacturing anchors the supply position for incumbent abdominal surgical robot manufacturers. This control allows for strategic pricing power over consumables and maintenance contracts, influencing hospital procurement decisions.
Pricing Analysis
Warranty and service bundling often dictates the total cost of ownership for abdominal surgical robots. Flexible, usage-based financial models, which bundle instruments and software upgrades, are gaining traction over one-time capital purchases. Price differentiation stems from advanced technological features like haptic feedback and artificial intelligence, alongside demonstrated improvements in surgical outcomes. Pricing pressure stems from hospital providers demanding quantifiable economic value, making government hospitals highly price-sensitive.
Supply Chain Analysis
Logistics and freight costs for complex mechatronic systems add significantly to the overall supply chain expense for abdominal surgical robots. Supply concentration centers on Germany and Switzerland for advanced robotics components, with final assembly and distribution often managed from the United States. The industry relies on high-precision mechatronics and specialized optical systems, creating single-source vulnerability as a structural risk. Distribution runs through direct sales channels to large hospital networks and specialty surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The abdominal surgical robot market is fundamentally a consolidation play, driven by the substantial capital expenditure required for system development and regulatory approval. This financial barrier forces smaller, less capitalized players to either specialize narrowly or exit the market.
For Market Incumbents:To counter Medtronic's bundling strategy and J&J's integrated ecosystem, incumbent players should deepen surgeon training programs and expand their installed base in key urban centers. Investing in AI-driven outcome analytics can demonstrate superior economic value, reinforcing hospital partnerships. Strategic acquisitions of specialized software firms will enhance digital surgery platforms, securing long-term customer loyalty.
For New Entrants and Emerging Players:Begin with developing smaller-footprint, lower-cost robotic systems specifically for outpatient procedures like hernia repair. This approach targets the growing ambulatory surgical center market segment, which is currently underserved by monolithic systems. Partnering with regional hospital networks to offer flexible financing models can accelerate adoption. Focus on demonstrating quantifiable cost savings and rapid patient recovery times to gain market entry.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized software developers and modular system manufacturers, particularly those advancing AI integration or telesurgery capabilities. The long-term viability of this market hinges on continued demand for minimally invasive procedures and an aging global population. Investors should target firms demonstrating clear pathways to reducing the total cost of care. The signal to watch is widespread reimbursement for AI-assisted surgical planning and remote proctoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-integrated 3D visualization | Enhances surgical precision and planning, supporting Software as a Medical Device regulatory pathways. |
| Expand surgeon training programs | Reduces learning curve bottlenecks and strengthens market share for established platforms. |
| Introduce modular robotic platforms | Lowers capital expenditure for specialty surgical centers, expanding market access. |
| Invest in telesurgery infrastructure | Addresses specialist shortages in rural areas, expanding geographic reach for advanced procedures. |
| Secure CE marking under EU MDR | Ensures continued market access in Europe and validates system safety and efficacy. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic publications underwrites the qualitative findings of this study. Primary interviews with hospital procurement managers, robotic surgeons, and medical device R&D directors informed key insights. Secondary data from clinical trial databases and health ministry reports provided additional validation. A bottom-up and top-down triangulation approach ensured data accuracy.
Comparable historical periods anchored the forecast window, ensuring the quantitative model reflected market evolution. The analytical framework segmented the market by product type, technology, application, end user, and regional adoption patterns. Compound Annual Growth Rates were derived from historical growth trends and projected future demand. Key forecast inputs included surgical procedure volumes and healthcare capital expenditure budgets.
Underlying measurement precision varies by segment; laparoscopic robots and bariatric procedures carry tighter precision than autonomous systems. Forecasts reflect assumptions regarding evolving reimbursement policies and new regulatory pathways. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Global Pacemakers Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Artificial Respirator Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Stool Management Systems Market
Medical Devices
Ambulatory X-Ray Devices Market