
 Anticoagulation Market | 2026-2036
Anticoagulation Market Size, Share, and Industry Trends Forecast 2026-2036
Anticoagulation Market Analysis
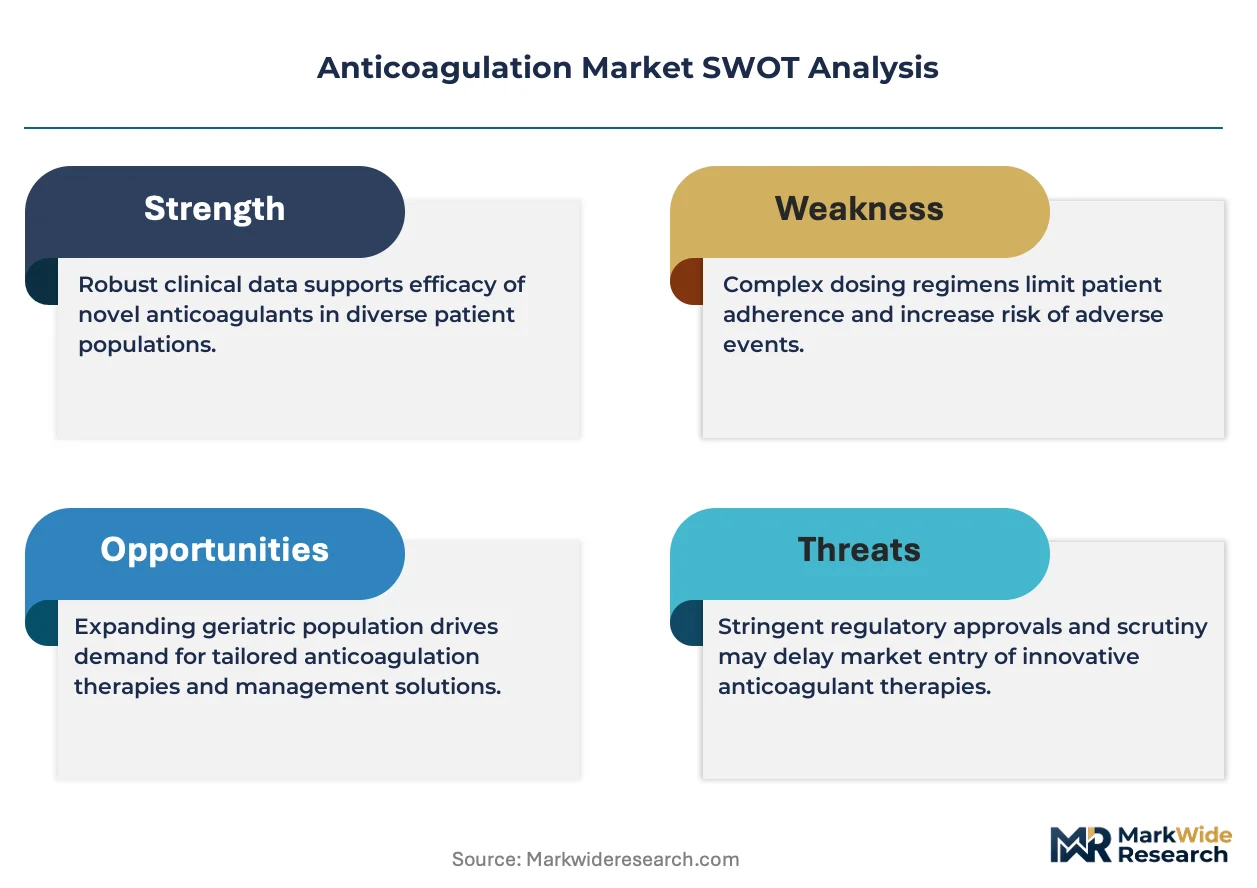
The EU Green Deal is decoupling anticoagulant procurement from carbon-intensive heparin supply chains, pressuring manufacturers to certify sustainable porcine sourcing. Bristol-Myers Squibb Company leverages its apixaban franchise to anchor North American hospital formularies. Pfizer Inc. competes through integrated heparin production networks that sustain raw material security.
Anticoagulation encompasses pharmacological agents that interrupt coagulation cascade enzymes—thrombin, factor Xa, or vitamin K-dependent factors—to prevent or treat thromboembolic events, with heparin requiring a specific antithrombin III cofactor concentration for therapeutic activity. Direct Oral Anticoagulants occupy the fastest-expanding margin pool as physicians favor fixed-dose regimens over INR monitoring, while Vitamin K Antagonists retain substantial volume in emerging markets where cost constraints dominate procurement. Hospital Pharmacies control the dominant distribution channel for acute anticoagulation initiation, though Home Care channels are gaining share as post-discharge DOAC protocols lengthen prescription windows.
The FDA maintains stringent pharmacovigilance requirements for bleeding risk labeling, while the EMA's MDR framework elevates post-market surveillance obligations for device-drug combinations such as heparin-coated catheters. Japan's PMDA imposes localized clinical data requirements that extend registration timelines for novel anticoagulant entrants. Stakeholders must monitor evolving thrombosis treatment guidelines from ACC and ESC that reshape prescribing patterns across cardiology and orthopedic surgery.
Market Dynamics
Hospital cardiology departments are abandoning warfarin in favor of fixed-dose direct oral anticoagulants, eliminating INR monitoring infrastructure and compressing the therapeutic window management burden that previously dominated anticoagulation protocols.
Growth Catalysts
- EMA MDR Surveillance:Elevated post-market obligations for heparin-coated device-drug combinations are accelerating investment in integrated safety databases across European hospital procurement networks.
- Japan PMDA Localization:Extended clinical data requirements for novel entrants are forcing sponsors to establish dedicated Japanese trial infrastructure, deepening regulatory expertise pools.
- Atrial Fibrillation Prevalence:Aging demographics in Germany, the United States, and Japan are expanding the addressable patient base for stroke prevention therapies.
Market Restraints
- Porcine Heparin Concentration:Over 80% of unfractionated heparin derives from Chinese pig farms, creating single-source vulnerability for European and North American manufacturers.
- FDA Bleeding Risk Labeling:Stringent pharmacovigilance requirements for DOACs impose lengthy post-approval monitoring obligations that constrain marketing claims.
- Warfarin Cost Floor:Generic vitamin K antagonists priced below $10 monthly in emerging markets block DOAC penetration where procurement budgets dominate clinical preference.
Strategic Opportunities
- EU Green Deal Certification:Sustainable sourcing mandates for heparin supply chains create first-mover advantage for manufacturers with verified low-carbon porcine procurement.
- Home Care Channel Expansion:Post-discharge DOAC protocols are lengthening prescription windows beyond hospital pharmacy control, opening direct-to-patient distribution models.
- Reversal Agent Integration:Development of specific antidotes for factor Xa inhibitors enables expansion into surgical populations previously excluded from DOAC therapy.
Industry Challenges
- Hematology Specialist Scarcity:Shortage of clinicians trained in coagulation cascade management limits safe DOAC initiation in rural and community hospital settings.
- Legacy INR Infrastructure Stranded:Hospital investments in warfarin monitoring laboratories face write-down pressure as formularies shift, creating capital allocation friction.
- Cross-Border Reference Pricing:Parallel trade across EU member states compresses net pricing realization for manufacturers despite divergent list prices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticoagulation Market |
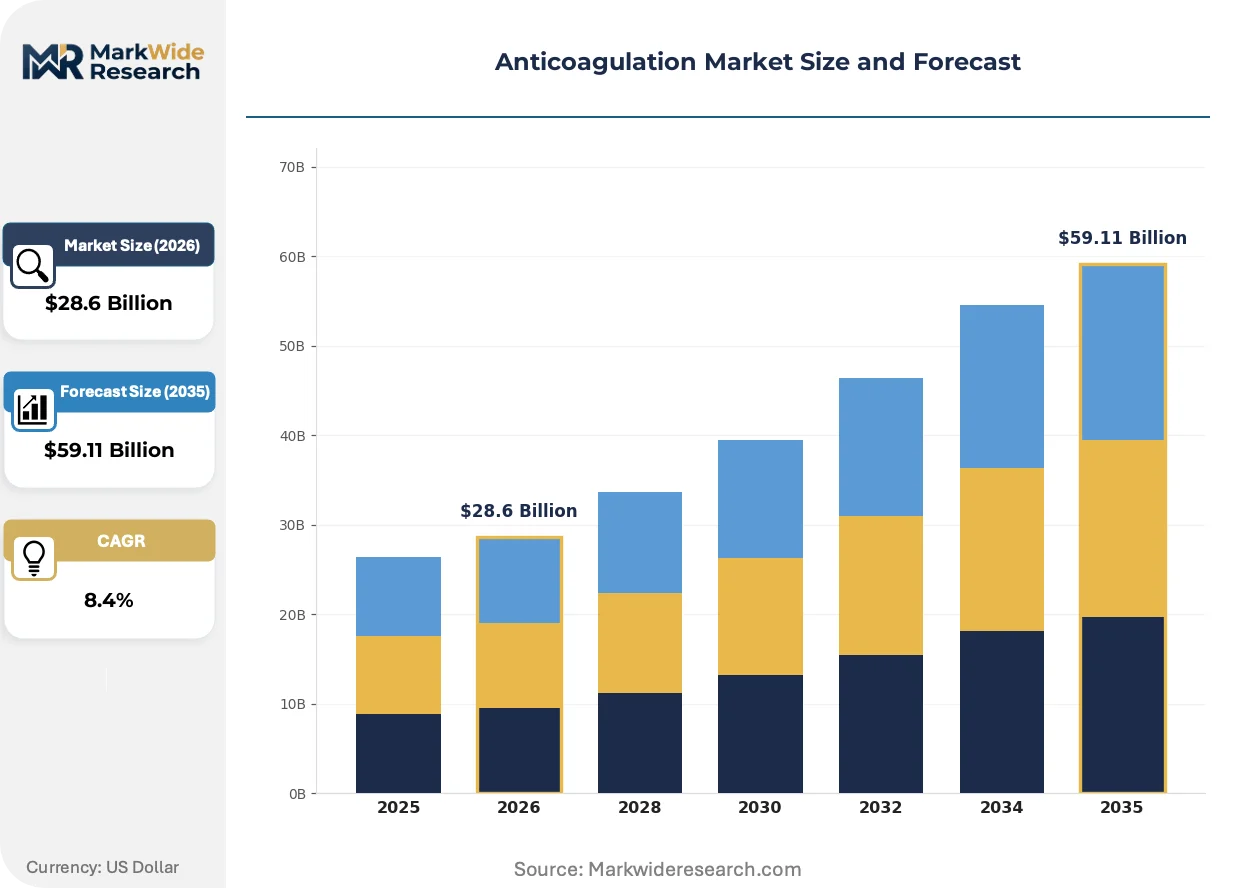
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Oral Anticoagulants, Vitamin K Antagonists, Heparin, Low Molecular Weight Heparin End User: Hospitals, Ambulatory Surgical Centers, Home Care, Blood Donation Centers Application: Thrombosis Treatment, Stroke Prevention, Myocardial Infarction, Atrial Fibrillation Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Clinics |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer Inc., Bayer AG, Johnson & Johnson, Boehringer Ingelheim, Daiichi Sankyo Company, Sanofi, Aspen Holdings, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticoagulation Market Emerging Trajectories
Point-of-care coagulation testing is collapsing the laboratory-to-bedside diagnostic loop, enabling real-time therapeutic decision-making that bypasses centralized hospital laboratory workflows and their associated delays.
Portable thromboelastography devices are decentralizing coagulation monitoring from hospital core laboratories to emergency departments and ambulatory surgical centers. Anesthesiology and trauma teams at Cleveland Clinic and Mayo Clinic satellite facilities are deploying these units for rapid perioperative bleeding assessment. This technology is decentralizing anticoagulation reversal decisions, compressing the time from abnormal coagulation detection to therapeutic intervention from hours to minutes.
REACH regulation amendments are tightening disclosure requirements for heparin supply chain carbon intensity across EU member states. Manufacturers must now document porcine farm energy consumption and transportation emissions for market access. German hospital purchasing consortia in Bavaria and North Rhine-Westphalia are prioritizing certified low-carbon heparin in tender evaluations, pressuring Chinese suppliers to adopt renewable energy or risk volume displacement.
Orthopedic surgery departments are unbundling anticoagulation protocols from bundled payment contracts, creating standalone thromboprophylaxis purchasing decisions. Hospital pharmacy committees in Texas, Florida, and California are negotiating DOAC formularies separately from joint replacement episode-of-care agreements. This purchasing pattern shift is most visible in United States Medicare Advantage networks, where at-risk providers seek granular control over drug costs that bundled payments previously obscured.
Anticoagulation Market Segmentation
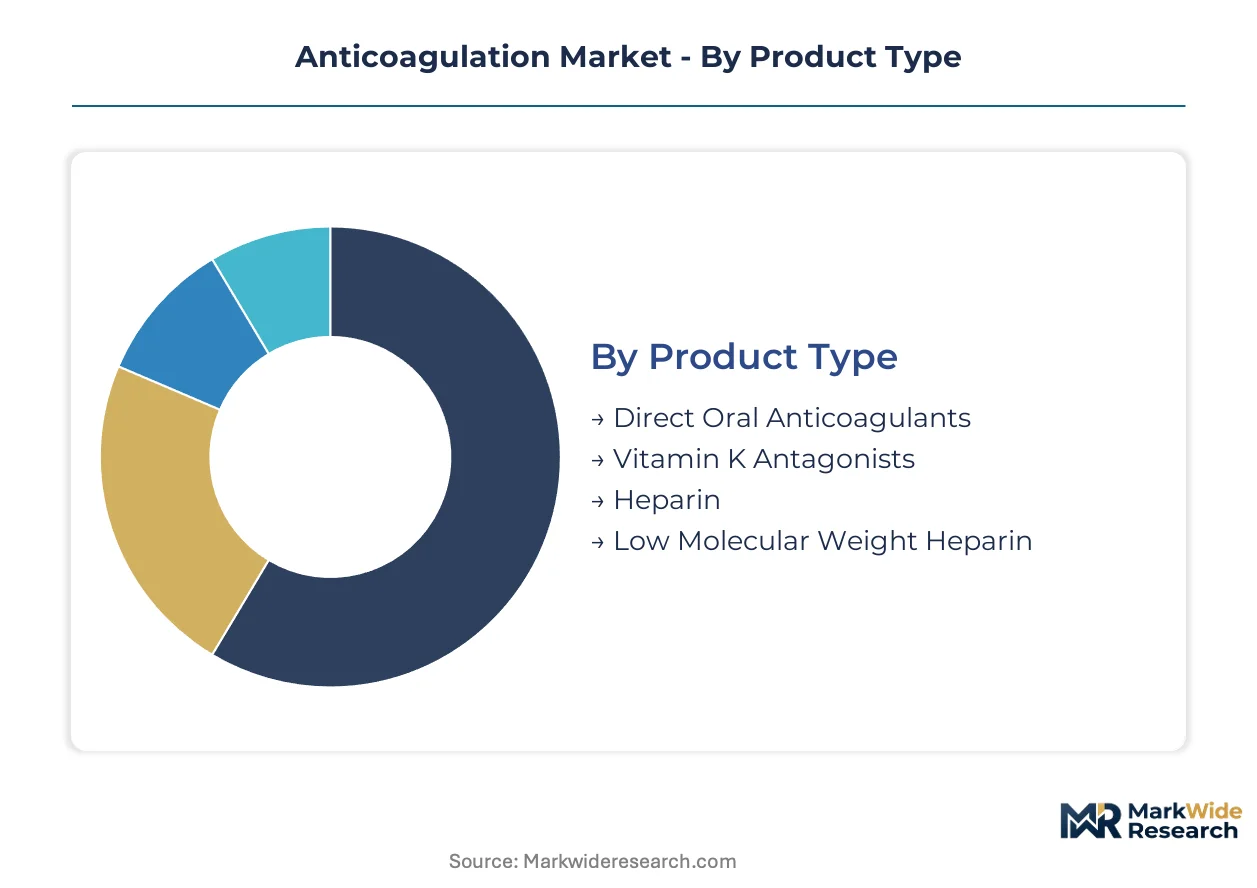
Anticoagulation procurement decisions split across clinical setting, therapeutic indication, and supply chain reliability. Hospital pharmacy committees weigh reversal agent availability against total cost of care, while outpatient channels prioritize patient adherence mechanisms.
Product Type:
Clinicians select agents based on monitoring infrastructure, reversal requirements, and renal clearance profiles.
- Direct Oral Anticoagulants:Factor Xa and direct thrombin inhibitors deliver fixed-dose regimens without INR surveillance. Demand concentrates in United States cardiology departments eliminating warfarin clinics, driven by compressed therapeutic window management.
- Heparin:Unfractionated formulations require antithrombin III cofactor concentration for therapeutic activity and permit rapid reversal with protamine sulfate. German and Japanese hospitals favor this agent for surgical populations where bleeding risk demands immediate intervention capability.
- Vitamin K Antagonists:Warfarin maintains volume in cost-constrained procurement environments through generic pricing below newer alternatives.
- Low Molecular Weight Heparin:Enoxaparin and dalteparin enable outpatient subcutaneous administration with predictable pharmacokinetics reducing laboratory monitoring burden.
Volume sits with Heparin; growth tilts toward Direct Oral Anticoagulants.
End User:
Care setting determines anticoagulation initiation protocols and duration of therapy.
- Hospitals:Acute care facilities control initial anticoagulation decisions for stroke, pulmonary embolism, and post-surgical thromboprophylaxis. United States hospital pharmacy committees in Texas and California negotiate DOAC formularies separately from bundled payment contracts.
- Home Care:Post-discharge DOAC protocols extend prescription windows beyond institutional control. Japanese home nursing services manage bridging therapy for patients transitioning from parenteral to oral agents.
- Ambulatory Surgical Centers:Orthopedic procedures in Bavaria and North Rhine-Westphalia drive short-duration prophylaxis with LMWH.
- Blood Donation Centers:Plasma collection operations require anticoagulant citrate dextrose formulations for apheresis procedures.
Procurement authority rests with Hospitals; expansion concentrates in Home Care.
Application:
Therapeutic indication shapes dosing intensity, duration, and monitoring requirements.
- Atrial Fibrillation:Chronic stroke prevention in aging populations drives sustained prescription volume. German electrophysiology clinics prioritize DOACs for non-valvular cases given elimination of dietary interaction management.
- Thrombosis Treatment:Deep vein thrombosis and pulmonary embolism management demands rapid therapeutic anticoagulation with parenteral bridging. United States emergency departments favor heparin infusion protocols permitting immediate procedural reversibility.
- Stroke Prevention:Secondary prevention protocols in Japan emphasize combination antiplatelet strategies with careful bleeding surveillance.
- Myocardial Infarction:Adjunct anticoagulation during percutaneous coronary intervention favors short-acting agents with rapid offset.
Prescription volume clusters around Atrial Fibrillation; therapeutic innovation targets Thrombosis Treatment.
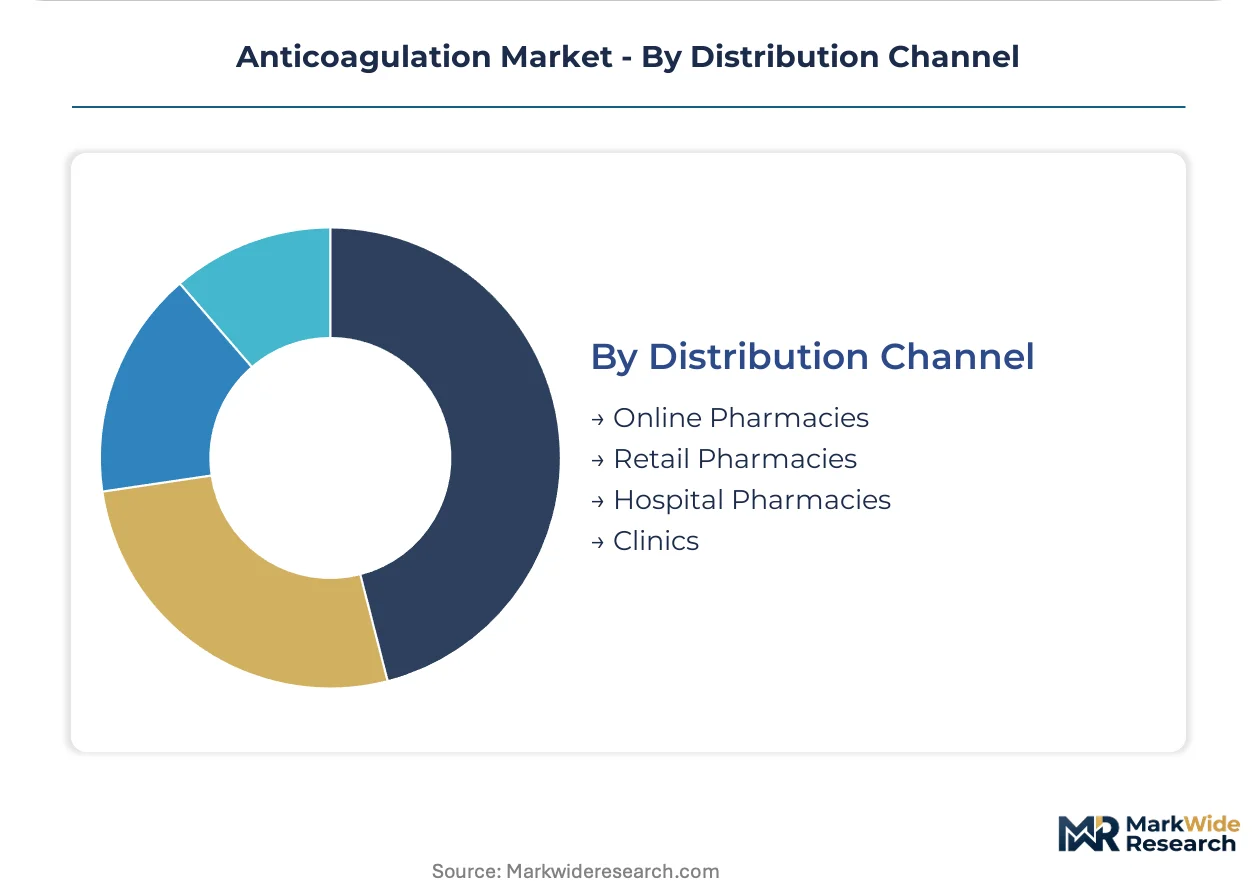
Distribution Channel:
Channel selection reflects prescription duration, reimbursement mechanics, and patient mobility constraints.
- Hospital Pharmacies:Institutional formularies gate access to newer agents through pharmacy and therapeutics committee approval. Cleveland Clinic and Mayo Clinic satellite facilities deploy point-of-care coagulation testing to accelerate therapeutic decisions.
- Retail Pharmacies:Community dispensing captures maintenance therapy for stable outpatients with established anticoagulation regimens.
- Online Pharmacies:Direct-to-patient distribution models emerge for post-discharge DOAC protocols extending beyond traditional pharmacy capture.
- Clinics:Anticoagulation management services in rural United States settings bridge specialist scarcity through protocolized dosing.
Revenue concentration favors Hospital Pharmacies; channel expansion moves toward Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing consortia in Bavaria and North Rhine-Westphalia are prioritizing certified low-carbon heparin in tender evaluations, pressuring Chinese suppliers to adopt renewable energy or risk volume displacement across European procurement networks.
United States
Texas, Florida, and California hospital pharmacy committees negotiate DOAC formularies separately from joint replacement episode-of-care agreements. FDA streamlined approval pathways for anticoagulant generics are reshaping competitive dynamics. Cleveland Clinic and Mayo Clinic satellite facilities deploy point-of-care coagulation testing to accelerate therapeutic decisions.
Germany
Aging demographics and atrial fibrillation prevalence drive prescription volumes for stroke prevention therapies. EU Green Deal decouples anticoagulant procurement from carbon-intensive heparin supply chains. Bavarian and North Rhine-Westphalian hospital purchasing consortia prioritize certified low-carbon heparin in tender evaluations.
Japan
PMDA localized clinical data requirements extend registration timelines for novel anticoagulant entrants, forcing sponsors to establish dedicated Japanese trial infrastructure. Aging populations expand the addressable patient base for stroke prevention therapies. Tokyo-based home nursing services manage bridging therapy for patients transitioning from parenteral to oral agents.
China
Over 80% of unfractionated heparin derives from Chinese pig farms, creating single-source vulnerability for European and North American manufacturers. The country's national pharmaceutical regulator maintains stringent oversight of active pharmaceutical ingredient exports. Zhejiang and Jiangsu provinces concentrate porcine processing operations serving international heparin demand.
United Kingdom
London and Southeast England cardiology departments shift away from warfarin monitoring burdens toward fixed-dose direct oral anticoagulants. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for novel anticoagulant formulations. Oxford and Cambridge research clusters advance next-generation thrombin inhibitor development programs.
Anticoagulation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reversal agent availability and sustainable sourcing certification dimensions. The anticoagulation sector exhibits tiered concentration with established pharmaceutical conglomerates anchoring hospital formularies while generic manufacturers compete on cost in emerging markets. Three archetypes dominate: integrated heparin producers controlling raw material security, DOAC franchise holders leveraging fixed-dose convenience, and specialty reversal agent developers enabling surgical expansion. Competitive moves center on backward integration into porcine supply chains and strategic partnerships for point-of-care diagnostic bundling.
Among US-based pharmaceutical conglomerates, Bristol-Myers Squibb Company and Pfizer Inc. exemplify contrasting strategic positions. Bristol-Myers Squibb Company occupies a position within the DOAC franchise tier, anchoring North American hospital formularies through fixed-dose regimen adoption. Pfizer Inc. represents the integrated production archetype, sustaining raw material security through captive heparin manufacturing networks. German chemical-pharmaceutical hybrid Bayer AG sits within the European premium tier, leveraging decades of anticoagulant development expertise across vitamin K antagonist and direct factor Xa inhibitor portfolios.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Bayer AG |
| Johnson & Johnson |
| Boehringer Ingelheim |
| Daiichi Sankyo Company |
| Sanofi |
| Aspen Holdings |
| GSK plc |
| Others |
Supply Flow & Price Mechanics
United States hospital pharmacy committees in Texas and California anchor pricing power through formulary control, compressing net prices via unbundled DOAC procurement from episode-of-care contracts. This buyer concentration forces manufacturers to absorb margin erosion or risk volume displacement across Medicare Advantage networks.
Pricing Analysis
Value-based pricing anchors on total cost of care outcomes, with reversal agent availability and bleeding risk profiles determining premium tier placement. Three-tier pricing structure across premium DOACs, standard LMWH, and economy warfarin segments reflects certification grade and monitoring infrastructure requirements. Cost compression in the generic vitamin K antagonist tier is intensifying because Indian and Chinese manufacturers flood emerging markets with sub-$10 monthly regimens. Government procurement programs in Germany and Japan exhibit lowest price sensitivity, while community hospital systems in rural United States settings drive hardest bargain.
Supply Chain Analysis
Porcine mucosa supply rests on Chinese agricultural processing infrastructure concentrated in Zhejiang and Jiangsu provinces, with secondary sourcing from Brazilian and Spanish farms. Heparin crude material, antithrombin III cofactor concentrates, and recombinant factor Xa inhibitor APIs constitute critical input dependencies. Single-source vulnerability pervades the heparin value chain, as over four-fifths of unfractionated material originates from Chinese pig farms. Distribution runs through hospital pharmacy consortia and GPO contracts in developed markets, with direct-to-patient channels emerging for post-discharge DOAC protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive heparin sourcing and DOAC reversal agent portfolios, as EU Green Deal certification requirements and FDA pharmacovigilance burdens force subscale competitors toward exit.
For Market Incumbents: Extend formulary anchoring through integrated reversal agent bundling, securing pharmacy committee preference against generic DOAC entrants. Deepen backward integration into certified low-carbon porcine supply chains to defend margin position against REACH-regulated European procurement. Prioritize point-of-care diagnostic partnerships to embed coagulation testing within hospital workflow capture. For New Entrants and Emerging Players: Direct-to-patient digital pharmacy platforms offer the lowest friction route for post-discharge DOAC capture, bypassing entrenched hospital formulary gatekeepers. Target Japanese home nursing services and United States ambulatory surgical centers as underpenetrated channels with less consolidated purchasing. Lead with sustainability certification to differentiate in Bavarian and North Rhine-Westphalian tender evaluations where EU Green Deal compliance gates market access. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale heparin producers with verified porcine sourcing in Spain and Brazil, positioned for European volume displacement from carbon-intensive Chinese supply. Long-term viability hinges on reversal agent integration enabling surgical population expansion. Watch FDA generic approval velocity and EMA MDR surveillance cost escalation as consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Reversal Agent Integration | Specific antidote development unlocks surgical populations previously excluded from DOAC therapy. |
| EU Green Deal Certification | Verified low-carbon porcine sourcing secures preferential tender positioning in German hospital consortia. |
| Point-of-Care Diagnostic Bundling | Portable thromboelastography partnerships embed manufacturers within Cleveland Clinic and Mayo Clinic satellite workflows. |
| Backward Integration into Porcine Supply | Captive sourcing from Spanish and Brazilian farms mitigates Chinese single-source concentration risk. |
| Home Care Channel Expansion | Direct-to-patient distribution captures post-discharge prescription windows beyond hospital pharmacy control. |
Methodological Framework
Independent corroboration across hospital pharmacy directors, formulary committee chairs, and heparin procurement managers underwrites the qualitative findings on pricing dynamics and supply chain vulnerability. Secondary validation draws from FDA Orange Book filings, EMA MDR surveillance databases, EU REACH supply chain disclosure registries, and hospital GPO contract repositories. Bottom-up patient volume modeling triangulates against top-down pharmaceutical revenue estimates across the analysis window.
Rate-of-change decomposition separates volume expansion from price realization across product type, end user, application, and distribution channel dimensions. Segmentation modeling incorporates therapeutic indication intensity, renal clearance profiling requirements, and regional regulatory cluster heterogeneity. CAGRs derive from iterative convergence between epidemiological prevalence projections and prescription volume elasticity assumptions, with atrial fibrillation aging demographics and orthopedic surgery protocol shifts as primary forecast inputs.
The model holds under stable regulatory enforcement intensity and continued hospital formulary consolidation; deviation in FDA generic approval acceleration or EU carbon border adjustment implementation would shift competitive positioning. Forecasts reflect documented assumptions regarding DOAC substitution rates and heparin supply chain reshoring feasibility. A small set of named triggers—PMDA localization timeline extensions, REACH amendment enforcement patterns, and Medicare Advantage bundling policy evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Global Aortic Repair Devices Market