
 Chlamydia Infection Treatment Market | 2026-2036
Chlamydia Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chlamydia Infection Treatment Market Analysis
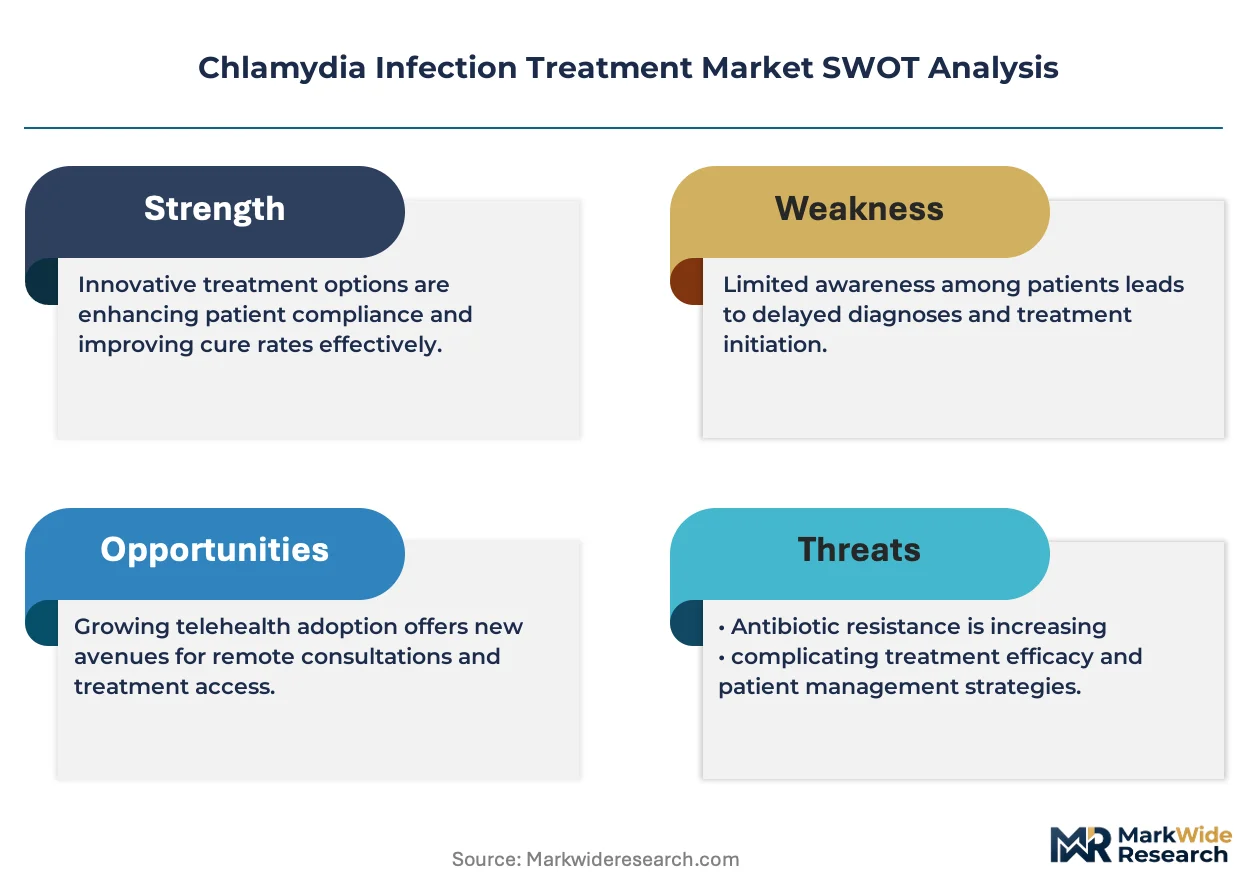
Hospital pharmacy procurement is reconfiguring as integrated delivery networks consolidate purchasing power across regional health systems. Pfizer Inc. leverages its manufacturing scale to maintain supply chain reliability for azithromycin formulations. Teva Pharmaceutical Industries Ltd. competes aggressively on generic doxycycline pricing, while Lupin Pharmaceuticals specializes in oral suspension formats for pediatric compliance.
Chlamydia infection treatment encompasses antimicrobial therapies targeting Chlamydia trachomatis, a gram-negative obligate intracellular bacterium requiring cell-mediated immune response for clearance. Oral azithromycin and doxycycline remain first-line therapies per CDC guidelines, with single-dose regimens preferred for adherence in community settings. The antibiotics segment anchors current revenue, though combination therapy formats are gaining traction where co-infection with gonorrhea demands dual coverage. Online pharmacy distribution is expanding fastest among channels, driven by telehealth prescribing and patient preference for discreet fulfillment.
The FDA oversees antibiotic efficacy standards and post-market surveillance, while the CDC publishes treatment guidelines that directly shape prescribing patterns across U.S. health systems. State-level Medicaid expansion decisions influence access volumes at community health organizations and urgent care centers. Stakeholders must monitor emerging antimicrobial resistance surveillance data and generic pricing volatility to optimize portfolio positioning.
Market Dynamics
FDA's accelerated generic approval pathways are compressing time-to-market for antibiotic manufacturers while Medicaid expansion decisions at state level directly shape patient access volumes at community health centers.
Growth Catalysts
- Telehealth prescribing expansion:Digital health platforms enable discreet consultation and prescription fulfillment, removing stigma barriers that previously delayed treatment-seeking behavior in sexually transmitted infection cases.
- CDC guideline updates:Revised treatment protocols emphasizing single-dose azithromycin regimens simplify adherence for community health workers managing high-volume screening programs.
- Community health organization outreach:Federally qualified health centers deploy mobile screening units to reach rural and underserved urban populations previously excluded from diagnostic access.
Market Restraints
- Active pharmaceutical ingredient concentration:Azithromycin precursor manufacturing clusters in Chinese chemical hubs, creating single-source vulnerability for generic formulators.
- Antimicrobial resistance surveillance gaps:Incomplete real-time monitoring of doxycycline-resistant Chlamydia trachomatis strains delays guideline adjustments and threatens first-line therapy efficacy.
- Reimbursement compression:State Medicaid formulary restrictions on branded antibiotic coverage limit physician prescribing flexibility in publicly insured populations.
Strategic Opportunities
- Point-of-care diagnostic integration:Nucleic acid amplification test platforms paired with same-visit prescribing create one-stop treatment models at urgent care chains.
- Pediatric formulation gaps:Oral suspension development for weight-based dosing in adolescents addresses compliance failures linked to tablet-swallowing difficulties.
- Online pharmacy channel expansion:Direct-to-patient fulfillment models bypass traditional brick-and-mortar pharmacy stigma concerns while capturing cash-pay segments.
Industry Challenges
- Clinical trial recruitment friction:Sexually transmitted infection stigma complicates patient enrollment for novel antibiotic efficacy studies, extending development timelines.
- Supply chain reconfiguration costs:Pharmaceutical manufacturers face capital outlays for dual-sourcing active ingredients as geopolitical risk reshapes API procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlamydia Infection Treatment Market |
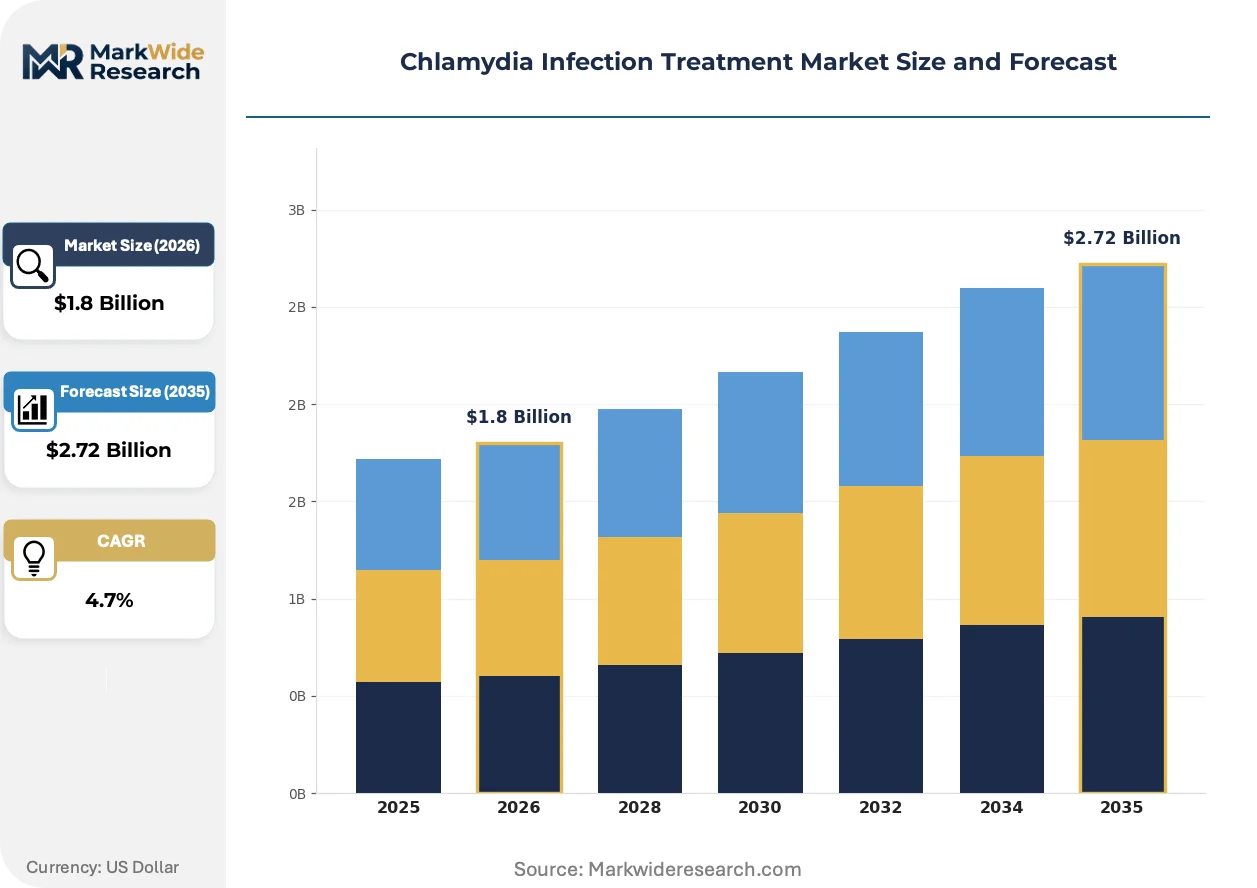
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Doxycycline, Azithromycin, Ofloxacin Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Clinics End User: Hospitals, Specialty Clinics, Urgent Care Centers, Community Health Organizations Form: Tablets, Oral Suspension, Injectable, Combination Therapy |
| Companies Covered | Johnson & Johnson, Novartis AG, Pfizer Inc., Bayer AG, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Sanofi S.A., Lupin Pharmaceuticals, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlamydia Infection Treatment Market Emerging Trajectories
Antibiotic stewardship programs and diagnostic-platform convergence are restructuring how Chlamydia infections move from detection through treatment completion, with technology vendors and health systems renegotiating their respective roles.
Multiplex nucleic acid amplification technology is hybridizing with cloud-based epidemiological surveillance, enabling real-time resistance tracking across regional health networks. Public health laboratories in high-incidence states deploy these integrated platforms to compress outbreak response timelines. The convergence is forcing standalone diagnostic manufacturers to develop API-compatible data architectures or risk exclusion from integrated delivery network procurement.
EMA's revised clinical trial guidelines for anti-infective agents now mandate pharmacokinetic modeling in adolescent subpopulations, raising development standards for pediatric indications. European generic manufacturers must generate additional safety data to maintain market authorization for established antibiotics. Pediatric-focused formulators in Germany and France are responding by front-loading juvenile toxicology studies to preempt regulatory delays.
Retail pharmacy chains now bundle STI screening with prescription fulfillment through private consultation rooms, displacing traditional clinic-based care pathways. Young adult populations in metropolitan areas favor these discreet, after-hours access points over scheduled primary care appointments. This channel pivot concentrates treatment volume in pharmacy-led models across the United States, particularly in states with expanded scope-of-practice regulations for pharmacist prescribing.
Chlamydia Infection Treatment Market Segmentation
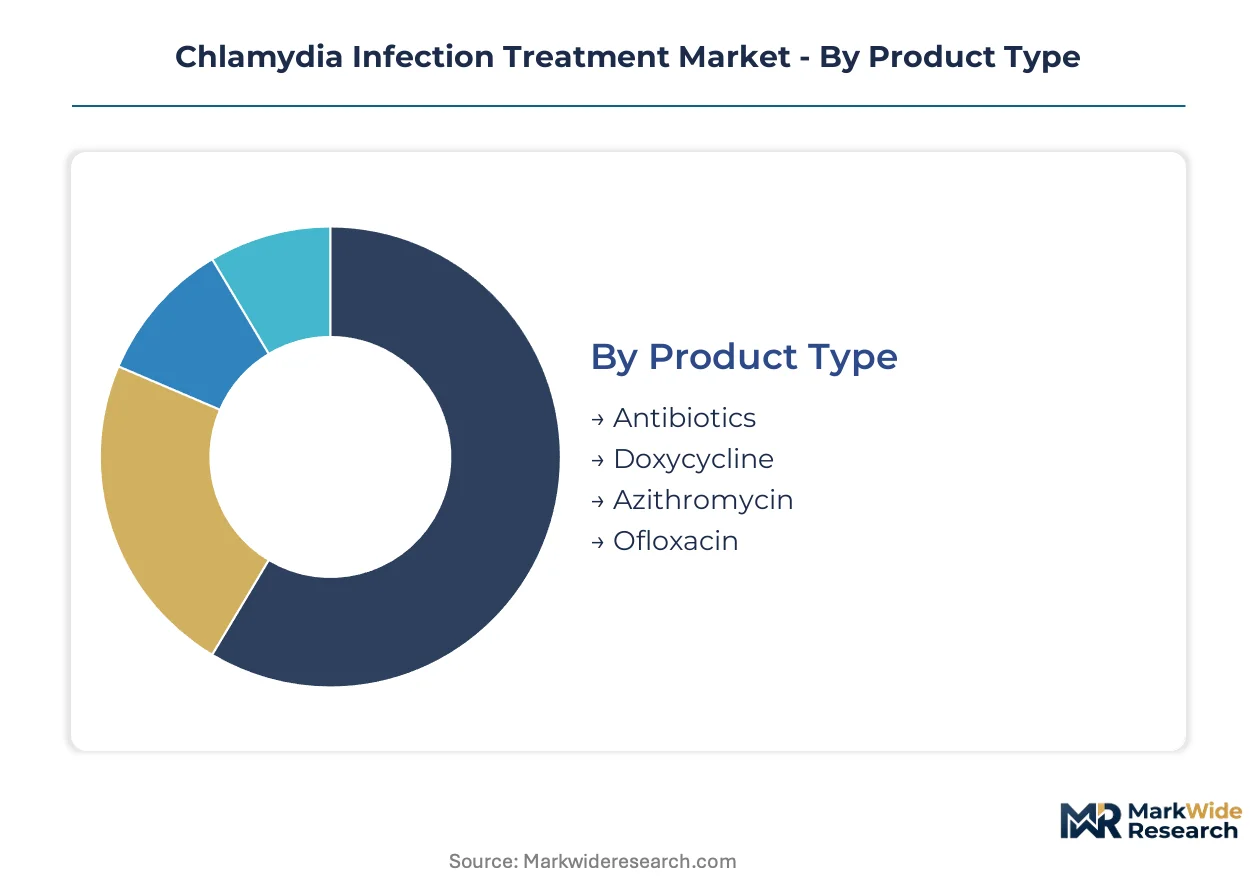
Segmentation in the Chlamydia infection treatment market reveals distinct procurement rhythms across product categories and delivery channels. Prescribing patterns diverge sharply between institutional buyers managing formulary compliance and direct-to-consumer platforms optimizing for discretion.
Product Type:
Azithromycin and doxycycline formulations turn over fastest in community health settings where single-dose adherence drives protocol selection, while ofloxacin and combination therapies move more deliberately through specialty channels managing co-infection complexity.
- Azithromycin:Macrolide antibiotic formulated as single-dose 1g oral tablets or powder-for-oral-suspension. Demand concentrates at community health organizations and urgent care centers where CDC-preferred single-dose regimens maximize completion rates in high-volume screening programs.
- Doxycycline:Tetracycline-class antibiotic administered as 100mg twice-daily for seven days. Prescribing clusters at hospital outpatient pharmacies and specialty clinics managing pelvic inflammatory disease complications where longer courses demonstrate superior tissue penetration.
- Antibiotics:Broad-spectrum agents including erythromycin and levofloxacin reserved for macrolide-tetracycline intolerance cases.
- Ofloxacin:Fluoroquinolone alternative deployed where resistance surveillance indicates susceptibility and patient allergies preclude first-line options.
Azithromycin anchors the volume base while doxycycline gains share at the steepest rate among cost-conscious payers prioritizing generic substitution.
Distribution Channel:
Cost tier stratification separates institutional procurement through hospital pharmacies from cash-pay premiums at online platforms, with retail chains occupying the mid-market volume position.
- Hospital Pharmacy:Integrated delivery network procurement with formulary restrictions and 340B pricing eligibility. Volume concentrates at academic medical centers and public hospital systems where Medicaid patient density drives generic substitution mandates.
- Online Pharmacy:Direct-to-patient fulfillment with telehealth prescribing integration. Growth concentrates among young adult demographics in metropolitan areas prioritizing discreet packaging and after-hours access over insurance reimbursement optimization.
- Retail Pharmacy:Chain and independent brick-and-mortar locations with private consultation room screening services.
- Clinics:Federally qualified health center and Planned Parenthood affiliate dispensing with same-visit treatment protocols.
Retail pharmacy maintains the volume base while online pharmacy climbs the fastest as telehealth prescribing scope expands across state-level regulatory frameworks.
End User:
Customer type segmentation separates high-acuity institutional settings from ambulatory access points, with urgent care and community health organizations capturing the patient volume shift away from traditional primary care.
- Urgent Care Centers:Walk-in diagnostic and treatment facilities with point-of-care nucleic acid amplification testing. Demand concentrates at national chain locations in metropolitan corridors where extended hours and no-appointment access remove traditional primary care friction.
- Community Health Organizations:Federally qualified health centers and mobile screening units serving uninsured and underinsured populations. Volume expansion tracks Medicaid expansion decisions at state level and federal Title X funding allocations.
- Hospitals:Emergency departments and outpatient clinics managing complicated cases with pelvic inflammatory disease or pregnancy.
- Specialty Clinics:Infectious disease and reproductive health practices handling recurrent or resistant infections.
Community health organizations anchor the volume base while urgent care centers gain share at the steepest rate as scope-of-practice regulations enable independent prescribing authority.
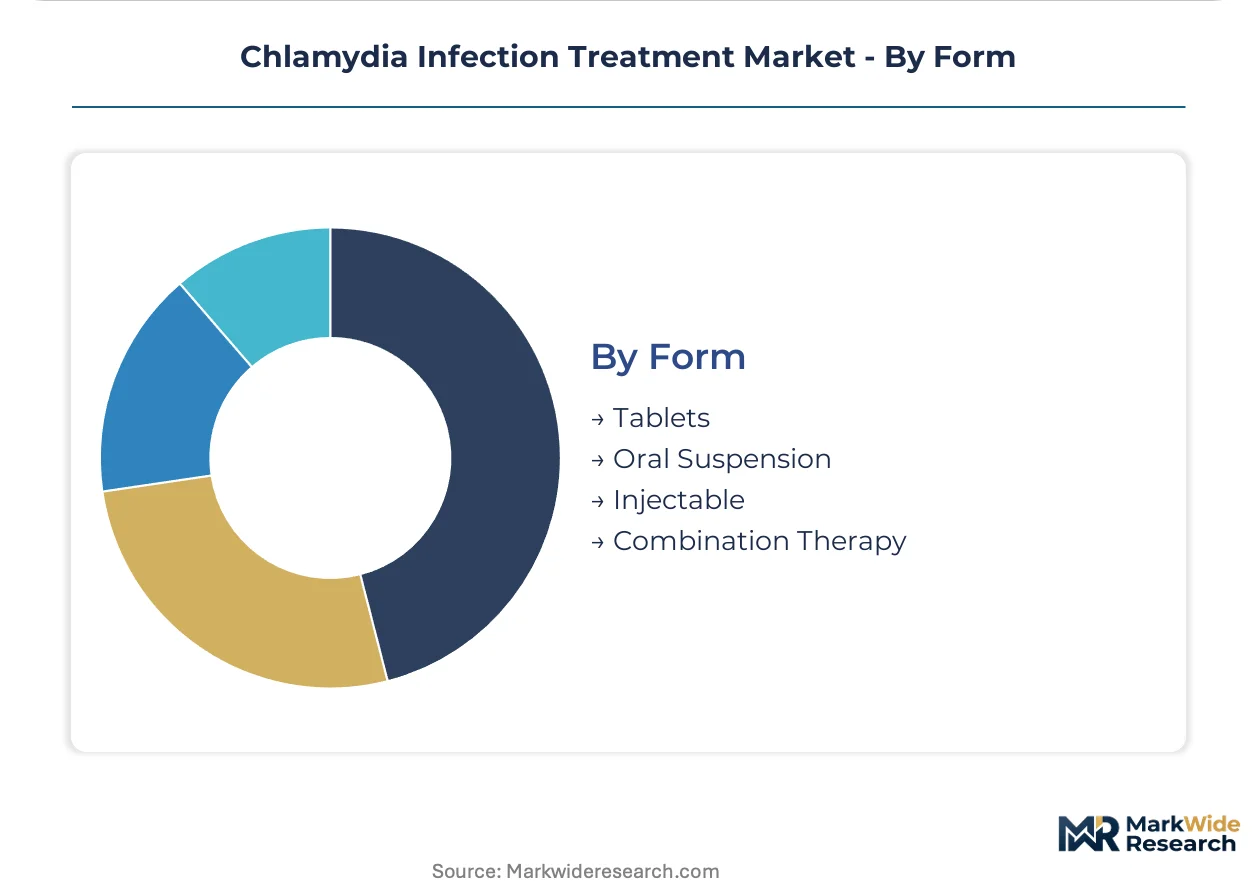
Form:
Supply concentration in tablet manufacturing creates cost advantages for solid oral dosage forms, while suspension and injectable formats command formulation premiums addressing specific patient compliance barriers.
- Tablets:Compressed solid dosage forms in 100mg, 250mg, and 500mg strengths for adult and adolescent patients. Manufacturing concentrates at Indian and Chinese contract development and manufacturing organizations serving generic formulators with API-to-finished-dose integration.
- Oral Suspension:Powder-for-reconstitution or ready-to-use liquid formulations enabling weight-based pediatric dosing. Development investment tracks EMA pediatric investigation plan requirements and FDA guidance for adolescent pharmacokinetic modeling.
- Injectable:Intravenous formulations reserved for hospitalized patients with severe complications or vomiting precluding oral absorption.
- Combination Therapy:Co-packaged azithromycin-ceftriaxone regimens for gonorrhea-chlamydia co-infection management per CDC sexually transmitted infection treatment guidelines.
Tablets anchor the volume base while oral suspension expands most quickly as pediatric indication approvals and adolescent compliance studies reshape formulary positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution infrastructure underwrites Western Europe's antibiotic supply security, while Singapore's Changi air cargo hub enables just-in-time API movements across Asia-Pacific manufacturing networks.
United States
Medicaid expansion decisions at state level directly shape patient access volumes at community health organizations and federally qualified health centers. The CDC publishes treatment guidelines that reshape prescribing patterns across hospital systems and urgent care chains. Texas and Florida concentrate retail pharmacy screening volume where scope-of-practice regulations enable pharmacist-initiated prescribing.
Germany
EMA's revised clinical trial guidelines for anti-infective agents mandate pharmacokinetic modeling in adolescent subpopulations, raising development standards for pediatric indications. German generic manufacturers front-load juvenile toxicology studies to preempt regulatory delays. The Rhine-Ruhr pharmaceutical cluster anchors European formulation capacity for oral suspension development.
India
CDSCO's accelerated approval pathways for generic antibiotics compress time-to-market for domestic formulators serving export markets. Indian contract development and manufacturing organizations integrate API-to-finished-dose production for azithromycin tablet supply. Hyderabad and Ahmedabad concentrate manufacturing infrastructure serving North American and European procurement contracts.
China
NMPA oversight of active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces creates regulatory leverage over global azithromycin precursor supply. Chinese chemical hubs face geopolitical risk reconfiguration as manufacturers diversify sourcing strategies. The Yangtze River Delta anchors fermentation-based macrolide production for international generic formulators.
United Kingdom
NHS England's sexual health service procurement frameworks concentrate treatment volume at integrated community clinics and online pharmacy platforms. The MHRA post-Brexit regulatory autonomy enables streamlined generic antibiotic authorization pathways. London's digital health startup cluster drives telehealth prescribing platform development for discreet STI consultation models.
Chlamydia Infection Treatment Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturing scale advantages and generic portfolio breadth rather than novel compound development. Large-cap pharmaceutical conglomerates with established antibiotic franchises compete against mid-tier generic specialists on price and formulation flexibility. Three archetypes dominate: vertically integrated API-to-finished-dose manufacturers, pediatric formulation specialists, and telehealth-integrated direct-to-consumer platforms. Competitive moves concentrate on supply chain dual-sourcing investments and point-of-care diagnostic partnerships that lock in treatment protocol placement.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson occupy positions exemplifying manufacturing scale and distribution infrastructure depth. Teva Pharmaceutical Industries Ltd. represents the generic specialist archetype competing on cost positioning across oral antibiotic categories. These three entities anchor competitive dynamics through their respective control over supply chain reliability, branded portfolio legacy, and aggressive generic substitution strategies.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis AG |
| Pfizer Inc. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Lupin Pharmaceuticals |
| Merck & Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese azithromycin precursor manufacturing determines both the spread between branded and generic pricing tiers and the geographic reconfiguration of API procurement strategies. Pharmaceutical formulators face compressed margins in the generic economy tier while branded manufacturers leverage supply chain redundancy to sustain premium positioning.
Pricing Analysis
Volume-discount tiering structures separate hospital pharmacy 340B procurement at the economy end from cash-pay online pharmacy premiums at the top. Price differentiation hinges on generic substitution eligibility and pediatric formulation complexity, with Medicaid formulary restrictions intensifying cost compression in publicly insured segments. Community health organizations exhibit highest price sensitivity due to federal funding constraints, while urgent care chains prioritize formulary compliance over unit cost optimization.
Supply Chain Analysis
Export-control regime scrutiny over fermentation-based macrolide technology limits technology transfer to Indian and Southeast Asian manufacturing hubs. Active pharmaceutical ingredient production draws from Zhejiang and Jiangsu provinces in China, with secondary formulation capacity anchored in Hyderabad and Ahmedabad. Single-source vulnerability in azithromycin precursor supply creates structural exposure to geopolitical disruption. Distribution runs through integrated delivery network procurement for institutional buyers and direct-to-patient fulfillment for telehealth-integrated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth prescribing expansion signals early-cycle penetration growth as stigma-reducing digital access protocols expand addressable patient populations beyond traditional clinic-based screening models.
For Market Incumbents: Pre-empt generic substitution mandates by securing dual-source API contracts in India and establishing point-of-care diagnostic partnerships that lock in protocol placement. Deepen backward integration into oral suspension manufacturing to defend pediatric formulation premiums against emerging generic specialists. For New Entrants and Emerging Players: Mobile screening units serving Medicaid-expansion states represent the most penetrable entry point for Federally Qualified Health Center supply contracts. Pediatric weight-based dosing formats for adolescent populations offer formulation differentiation where EMA pediatric investigation plans create regulatory barriers to incumbent line extensions. Partner with telehealth platforms for discreet fulfillment integration. For Investors and Strategic Acquirers: FDA streamlined generic approval pathways reshape the acquisition landscape toward API-to-finished-dose integrated manufacturers with established CDSCO or NMPA supplier relationships. Target generic formulators with pediatric suspension capabilities and dual-source supply documentation. Monitor antimicrobial resistance surveillance data releases as inflection indicators for guideline-driven product substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source API Procurement | Reduces single-source exposure to Chinese chemical hub concentration for azithromycin precursors. |
| Pediatric Formulation Development | Addresses EMA pharmacokinetic modeling requirements for adolescent weight-based dosing compliance. |
| Point-of-Care Diagnostic Integration | Locks in treatment protocol placement at urgent care chains through same-visit NAAT platforms. |
| Telehealth Platform Partnership | Captures cash-pay volume via discreet prescribing and direct-to-patient fulfillment channels. |
| Antimicrobial Resistance Surveillance | Enables preemptive guideline adaptation before CDC protocol shifts displace first-line therapies. |
Methodological Framework
Desk research of FDA approval databases, CDC treatment guideline archives, and Medicaid formulary filings preceded structured interviews with infectious disease clinicians, hospital pharmacy procurement directors, generic manufacturing executives, and telehealth platform operators. Secondary validation drew from ClinicalTrials.gov entries, EMA pediatric investigation plans, and CMS utilization data. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical shipment analytics.
Assumptions held CDC guideline stability and current antimicrobial susceptibility profiles constant while varying Medicaid expansion trajectories and telehealth regulatory scope across state-level scenarios. Segmentation dimensions included product type, distribution channel, end-user setting, and patient age cohort. CAGRs derived from prescription volume trend extrapolation adjusted for generic substitution rates and pediatric indication approval timelines. Resistance surveillance data and API pricing volatility served as scenario-branching inputs.
Macroeconomic conditions sit as an overlay; deviation in federal Title X funding allocations or state Medicaid reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and formulary placement continuity. Material shifts in CDC first-line therapy recommendations or NMPA export licensing enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Brucellosis Market
Infectious Disease
Efavirenz Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market