
 Mexico Dental Devices Market | 2026-2036
Mexico Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Dental Devices Market Outlook
Buyer concentration among Mexico's private dental clinic chains is decoupling from traditional hospital-based procurement, redirecting volume toward independent multi-location operators. Kerr Corporation leverages its restorative materials portfolio to anchor relationships with these expanding clinic networks. Danaher Corporation sustains instrument sterilization and imaging workflows across Mexico's federal dental service contracts. Straumann Holding AG specializes in premium implantology systems, competing for positioning within Monterrey's growing cosmetic dentistry sector.
Dental devices encompass instruments, equipment, and consumables engineered from stainless steel, titanium alloys, zirconia ceramics, and medical-grade polymers, manufactured through precision machining, sintering, and additive processes to diagnose, treat, or restore oral structures. Restorative materials and orthodontic appliances dominate current revenue pools, while CAD/CAM systems and 3D printing technology segments capture accelerating margin expansion as Mexican laboratories adopt chairside digital workflows. Surgical instruments maintain stable replacement cycles, though laser dentistry applications remain nascent outside major metropolitan teaching hospitals.
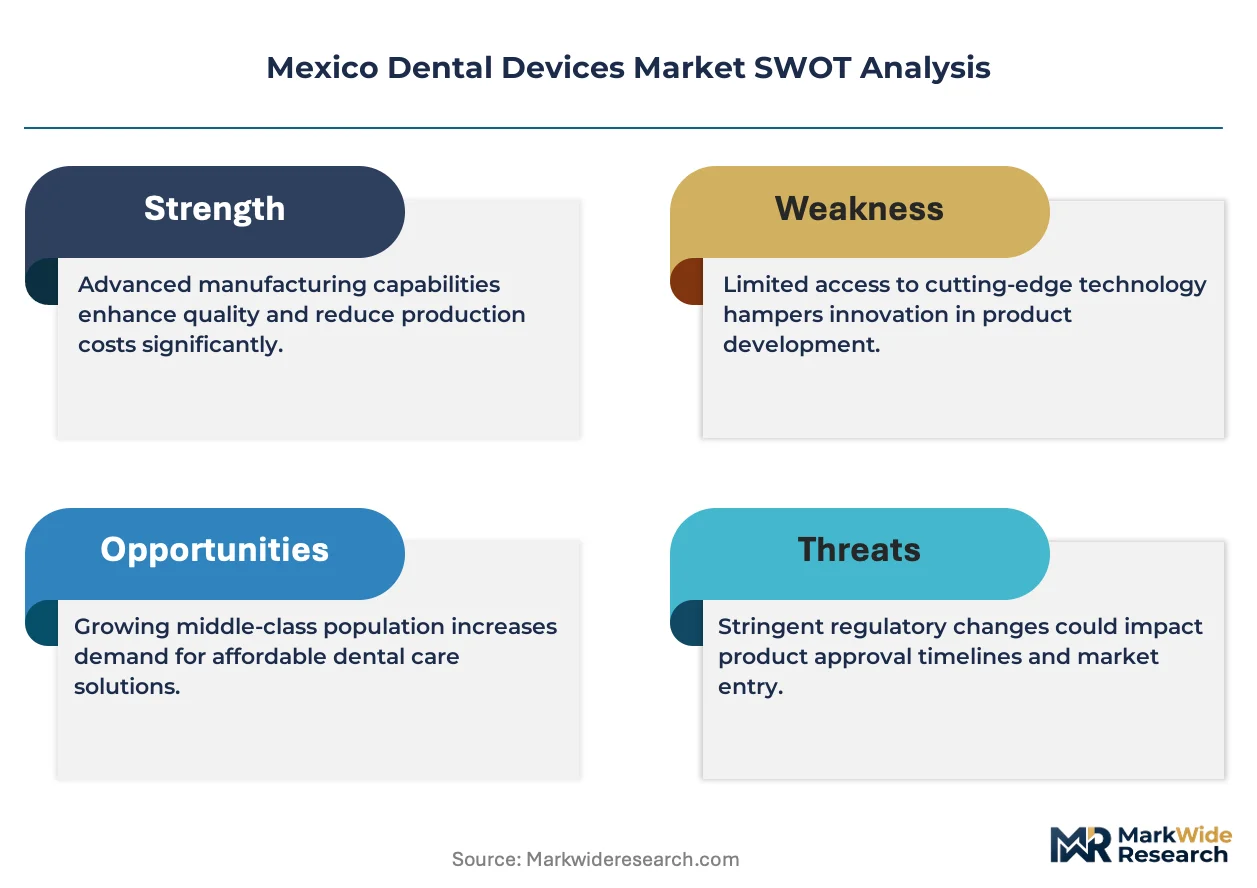
COFEPRIS regulates medical device registration, importation, and post-market surveillance, while NOM standards establish biocompatibility and sterility benchmarks that foreign manufacturers must satisfy before commercialization. Mexico's alignment with MDSAP audit recognition streamlines multinational quality system compliance, reducing redundant facility inspections for holders of FDA or Health Canada certifications. Stakeholders must monitor pending updates to NOM-240 pharmacovigilance requirements and assess whether domestic production incentives alter import dependency for Class III implantable devices.
Market Dynamics
Digital chairside workflows are compressing turnaround times for crown and bridge restorations across Mexico's metropolitan dental corridors, forcing laboratories and clinics to reconfigure capital deployment toward intraoral scanning and milling systems.
Growth Catalysts
- COFEPRIS Registration Streamlining:The regulator's alignment with MDSAP audit recognition is reducing redundant facility inspections for foreign manufacturers holding FDA or Health Canada certifications, accelerating Class II and III device import clearances.
- Cosmetic Dentistry Concentration:Mexico City's metropolitan dental corridor is generating concentrated demand for premium aesthetic restorations, pulling specialized ceramic and composite material volumes toward private clinic chains.
- Chairside CAD/CAM Adoption:Guadalajara and Monterrey clinic networks are deploying intraoral scanners and milling units to capture same-day restoration revenue previously lost to external laboratories.
Market Restraints
- Titanium Alloy Price Volatility:Implant manufacturers face margin compression from fluctuating titanium sponge costs, with Mexico's import-dependent supply chain amplifying exposure to spot market swings.
- Class III Device Registration Friction:COFEPRIS maintains extended review timelines for implantable devices, creating working capital strain for distributors awaiting commercialization authorization.
- Domestic Laboratory Competition:Low-cost denture and crown laboratories in border states compete on price, limiting margin expansion for premium digital workflow providers.
Strategic Opportunities
- Monterrey Implantology Expansion:The city's growing medical tourism infrastructure creates positioning space for premium implant system providers serving cross-border patients.
- 3D Printing Convergence:Integration of photopolymer printing with intraoral scanning is enabling same-day surgical guides and temporary restorations, compressing multi-appointment protocols.
- Federal Dental Service Contracts:Seguro Popular procurement channels offer volume access for sterilization and imaging equipment meeting NOM biocompatibility benchmarks.
Industry Challenges
- Digital Workflow Integration:Legacy practice management systems in established clinics resist seamless data exchange with new chairside hardware, forcing middleware investments.
- Technician Retraining Requirements:Laboratory personnel require certification in CAD design and milling operation, with training program availability lagging equipment sales velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Dental Devices Market |
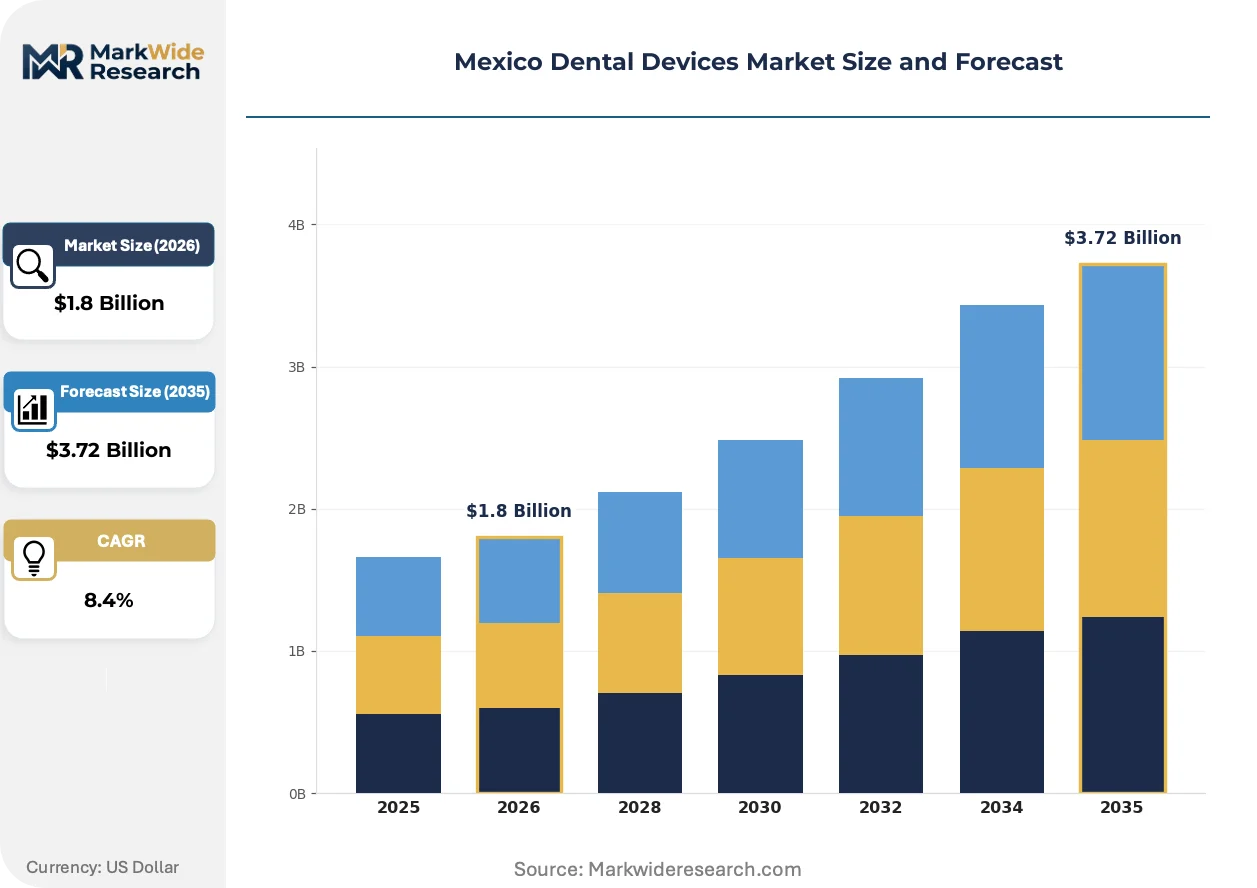
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontic Appliances, Endodontic Devices, Restorative Materials, Surgical Instruments Technology: Digital Impressions, CAD/CAM Systems, 3D Printing, Laser Dentistry Application: Oral Surgery, Preventive Care, Cosmetic Dentistry, Pediatric Dentistry End User: Dental Clinics, Hospitals, Research Institutions, Home Care |
| Companies Covered | Kerr Corporation, Danaher Corporation, 3M, Straumann Holding AG, Planmeca, Dentsply Sirona, Envista Holdings Corporation, Henry Schein, Zimmer Biomet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Dental Devices Market Strategic Shifts
Chairside digitization is collapsing the traditional separation between clinical diagnosis and laboratory fabrication, with hardware-software integration now determining competitive positioning across Mexico's dental supply chain.
Intraoral scanning systems are rewriting the economics of fixed prosthodontics by eliminating physical impression materials and enabling real-time design validation. Private clinic chains across Guadalajara are deploying these systems at accelerating rates, compressing the traditional two-week crown delivery cycle into single-visit protocols that capture premium pricing.
COFEPRIS pharmacovigilance updates under NOM-240 are tightening post-market surveillance requirements for implantable devices. Manufacturers must now maintain active complaint monitoring and adverse event reporting systems, with compliance costs falling disproportionately on smaller foreign suppliers lacking Mexican regulatory infrastructure.
Buyer concentration among multi-location dental clinic chains is consolidating procurement leverage previously dispersed across independent practitioners. These networks are negotiating direct supply relationships with restorative material manufacturers, bypassing traditional distributor markups in Mexico City and Monterrey metropolitan markets.
Mexico Dental Devices Market Segmentation
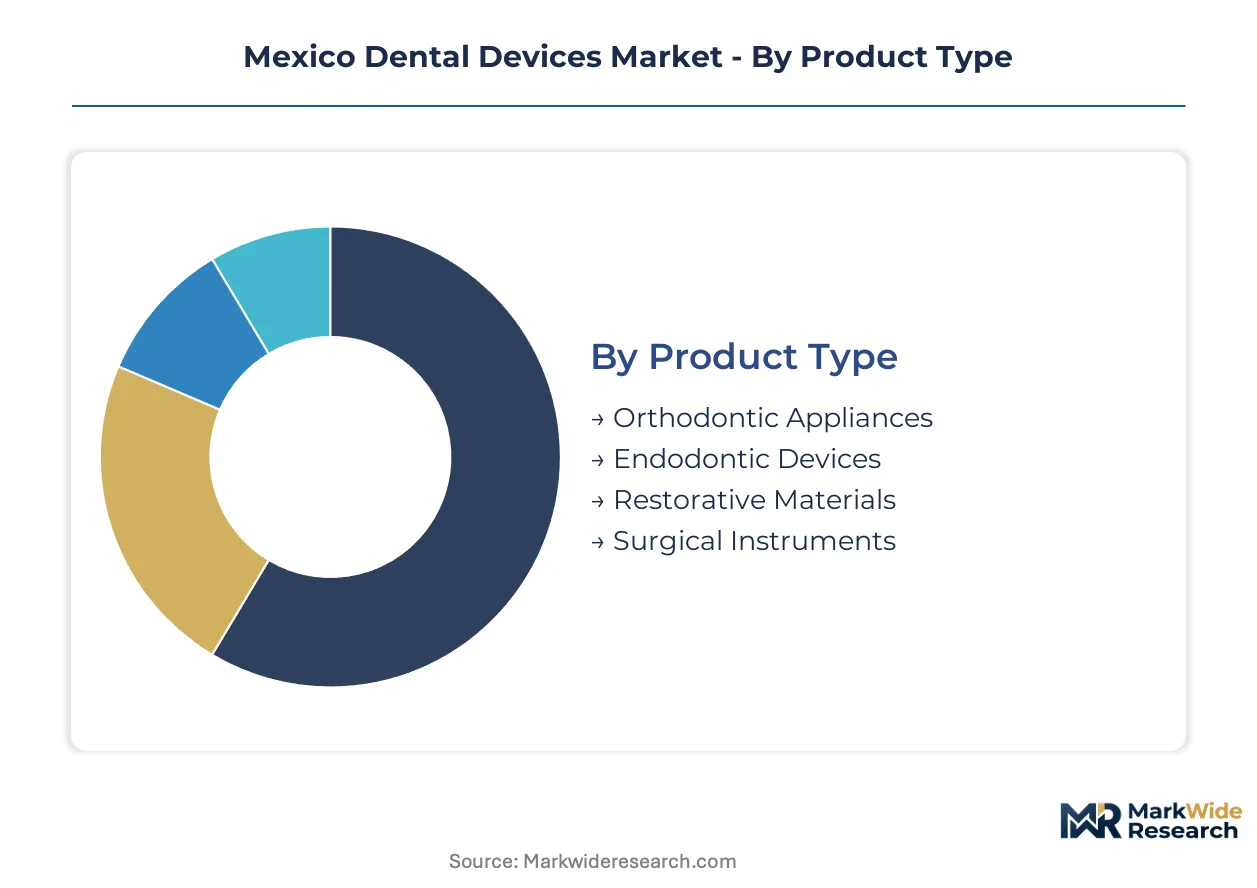
Segmentation reveals how procurement leverage concentrates across Mexico's dental supply chain. Product type and technology splits expose where clinic networks deploy capital versus where federal contracts sustain volume.
Product Type:
Supply concentration tilts toward consumables and instruments that private clinic chains replenish at scale.
- Restorative Materials:Composite resins, glass ionomers, and ceramic compounds formulated for crown and bridge applications. Mexico City's metropolitan dental corridor pulls concentrated volume for aesthetic restorations, with COFEPRIS registration streamlining import clearances for Class II materials.
- Orthodontic Appliances:Fixed brackets, archwires, and clear aligner systems manufactured from nickel-titanium alloys and medical-grade polymers. Guadalajara clinic networks are scaling procurement of chairside aligner fabrication systems to capture same-day treatment starts.
- Endodontic Devices:Nickel-titanium rotary files, obturation systems, and apex locators for root canal therapy.
- Surgical Instruments:Stainless steel and titanium alloy forceps, elevators, and osteotomes with stable replacement cycles across federal dental service contracts.
Restorative materials absorb the bulk of installed capacity; orthodontic appliances are expanding most quickly.
Technology:
Cost tier stratification separates premium digital workflows from legacy equipment still dominant in peripheral markets.
- CAD/CAM Systems:Chairside milling units and design software integrating intraoral scan data with ceramic block machining. Monterrey's cosmetic dentistry sector is deploying these systems to compress multi-appointment crown protocols into single visits.
- 3D Printing:Photopolymer and resin-based additive manufacturing for surgical guides, temporary restorations, and orthodontic models. Border state laboratories are adopting entry-level printers to compete on denture and crown turnaround times.
- Digital Impressions:Intraoral scanners capturing optical data to replace physical impression materials.
- Laser Dentistry:Erbium and diode laser systems for soft tissue procedures, with adoption concentrated in major metropolitan teaching hospitals.
CAD/CAM systems command the premium tier of capital deployment; 3D printing is climbing the fastest as equipment costs decline.
Application:
Volume concentrates in procedures reimbursable through Seguro Popular, while margin expansion tracks elective services.
- Cosmetic Dentistry:Veneers, whitening systems, and aesthetic restorations targeting private-pay patients. Monterrey's medical tourism infrastructure is generating cross-border demand for premium ceramic and zirconia applications.
- Preventive Care:Prophylaxis equipment, sealants, and diagnostic imaging for routine patient maintenance. Federal dental service contracts sustain steady volume for sterilization and radiography systems meeting NOM biocompatibility benchmarks.
- Oral Surgery:Implant placement, extraction, and bone grafting procedures requiring specialized instrumentation.
- Pediatric Dentistry:Sized instruments, behavior management tools, and early orthodontic intervention systems.
Preventive care absorbs the bulk of patient throughput; cosmetic dentistry is gaining share fastest.
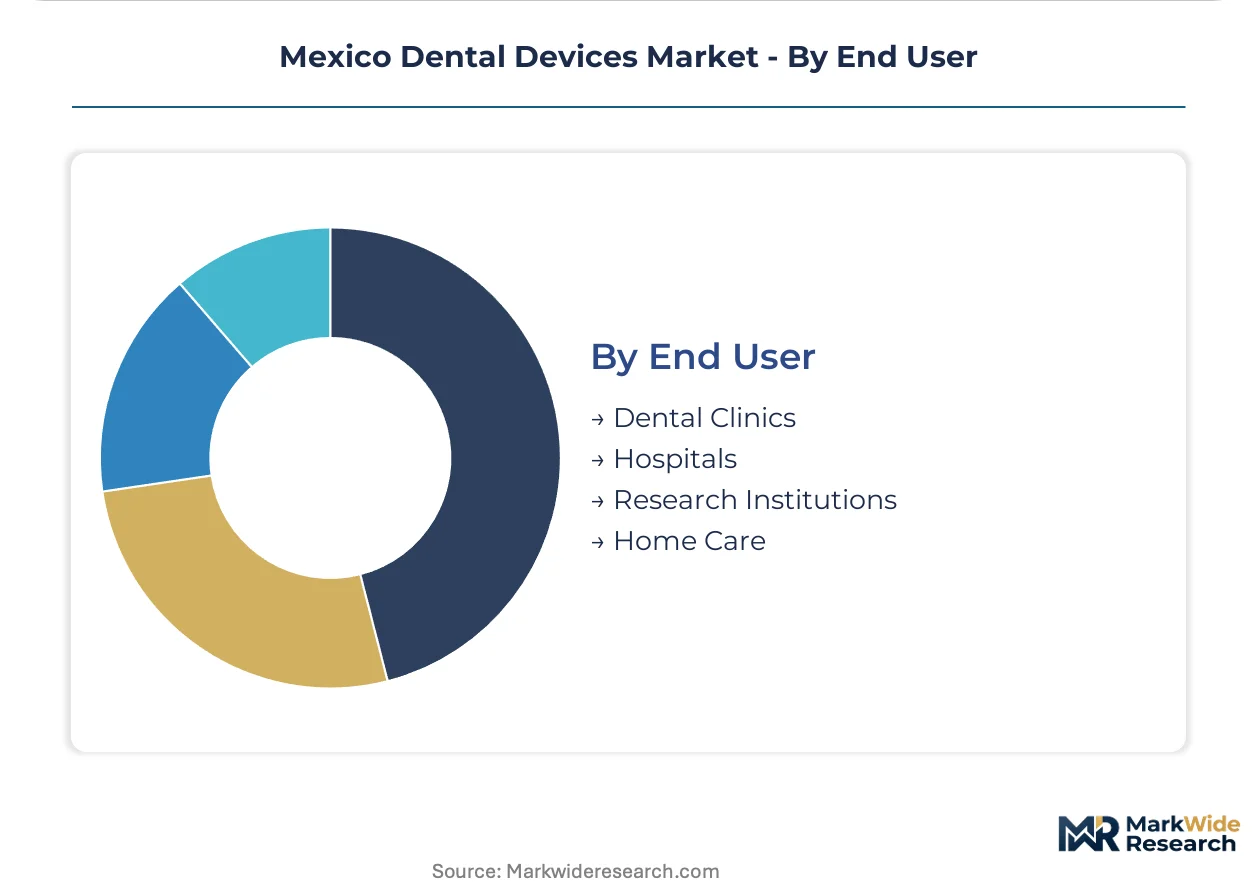
End User:
Customer type determines procurement channel structure, with private networks bypassing traditional distributor layers.
- Dental Clinics:Independent and multi-location private practices across Guadalajara, Monterrey, and Mexico City. These networks are negotiating direct supply relationships with restorative material manufacturers, consolidating procurement leverage previously dispersed across individual practitioners.
- Hospitals:Tertiary care centers and teaching institutions maintaining surgical suites and emergency dental services. NOM-240 pharmacovigilance compliance costs fall disproportionately on hospital-based implant programs with adverse event reporting obligations.
- Research Institutions:Universities and dental schools conducting clinical trials and device validation studies.
- Home Care:Over-the-counter whitening kits, orthodontic retainers, and oral hygiene devices distributed through retail pharmacy channels.
Dental clinics command the dominant share of device procurement; hospitals maintain the steepest compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private dental clinic chains across Mexico City's metropolitan corridor concentrate procurement leverage for premium aesthetic restorations. COFEPRIS regulatory streamlining and MDSAP alignment are accelerating device clearances in key sub-regions.
Mexico City Metropolitan Area
Cosmetic dentistry applications drive concentrated demand for ceramic and composite restorative materials. COFEPRIS Class II registration pathways expedite import clearances for aesthetic-focused devices. Polanco and Santa Fe districts host premium clinic networks deploying chairside CAD/CAM systems for same-day crown protocols.
Nuevo León
Monterrey's medical tourism infrastructure generates cross-border patient flows for implantology procedures. The state's alignment with federal Seguro Popular procurement channels sustains volume for sterilization and imaging equipment. San Pedro Garza García anchors premium clinic chains negotiating direct supply relationships with restorative material manufacturers.
Jalisco
Guadalajara clinic networks scale procurement of intraoral scanning and milling systems for chairside workflows. COFEPRIS pharmacovigilance requirements under NOM-240 impose compliance costs on implantable device distributors. Zapopan's dental corridor concentrates multi-location operators capturing same-day restoration revenue.
Bajío Region
León and Querétaro manufacturing bases support domestic laboratory competition for denture and crown fabrication. The region's lower-cost production environment limits margin expansion for premium digital workflow providers. Industrial parks near Silao host entry-level 3D printing operations serving price-sensitive border state markets.
Northern Border States
Tijuana and Ciudad Juárez laboratories compete on turnaround times for cross-border dental tourism. Titanium alloy import dependency amplifies exposure to spot market price volatility for implant manufacturers. Maquiladora-adjacent logistics infrastructure facilitates rapid device clearance through COFEPRIS streamlined pathways.
Mexico Dental Devices Market Competitive Environment
US-based producers anchor the premium tier through restorative materials and imaging portfolios; Swiss and German specialists hold positioning in implantology and precision instrumentation. Market structure tilts toward consolidated procurement relationships with multi-location clinic chains, displacing fragmented distributor networks. Three archetypes dominate: diversified multinationals with federal contract access, premium implantology specialists, and integrated dental supply distributors. Competitive moves center on direct supply negotiations with clinic networks and MDSAP certification investments to accelerate COFEPRIS clearances.
Within the diversified multinational tier, Danaher Corporation and Dentsply Sirona occupy positions spanning sterilization workflows and digital dentistry platforms. Kerr Corporation exemplifies the restorative materials specialist archetype, while Straumann Holding AG anchors the premium implantology segment competing for Monterrey's cosmetic dentistry volume. These three companies represent distinct competitive vectors: federal contract penetration, direct clinic network supply relationships, and medical tourism positioning.
| Leading Market Players |
|---|
| Kerr Corporation |
| Danaher Corporation |
| 3M |
| Straumann Holding AG |
| Planmeca |
| Dentsply Sirona |
| Envista Holdings Corporation |
| Henry Schein |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
CAD/CAM technicians concentrated in Guadalajara's dental corridor create labor-cost differentials that widen pricing-tier spreads between chairside digital workflows and conventional laboratory services. COFEPRIS registration tiers compound these spreads, with Class III implantable devices commanding premium positioning against Class II material imports.
Pricing Analysis
Volume concentrates in restorative materials and orthodontic consumables, while margin expansion accrues to CAD/CAM system providers and premium implantology portfolios. Three-tier pricing structure across premium, standard, and economy levels separates MDSAP-certified manufacturers from regional distributors and border-state laboratory competitors. Pricing pressure stems from titanium alloy spot market volatility and low-cost denture laboratories in Bajío industrial parks. Federal dental service contracts exhibit highest price sensitivity; cosmetic dentistry patients in Monterrey and Mexico City show lowest.
Supply Chain Analysis
Reverse logistics for intraoral scanner refurbishment and milling unit remanufacturing flow through Monterrey's medical device service hubs, creating secondary equipment channels for price-sensitive clinic networks. Manufacturing concentrates in the United States, Switzerland, and Germany for precision instrumentation; China and South Korea supply entry-level 3D printing hardware and photopolymer resins. Raw material dependencies center on titanium sponge, zirconia ceramics, and nickel-titanium alloys. Single-source vulnerability persists for FDA-cleared implant systems awaiting COFEPRIS parallel review. Distribution runs through direct supply contracts with multi-location clinic chains, displacing traditional distributor layers in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where COFEPRIS pharmacovigilance compliance costs under NOM-240 force smaller foreign suppliers without Mexican regulatory infrastructure toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from domestic laboratory competition by deepening backward integration into zirconia ceramic production and securing captive supply of titanium alloy feedstock. Invest in MDSAP certification maintenance to accelerate Class III device clearances before regulatory review timelines extend further. Channel control through direct procurement portals with Guadalajara and Monterrey clinic networks defends positioning against emerging restorative material specialists. For New Entrants and Emerging Players: Mid-tier private clinic operators in Zapopan and León represent an underserved buyer archetype seeking affordable chairside digital workflows without premium-brand pricing. Target entry-level intraoral scanner and 3D printing bundles for these expanding multi-location networks. A go-to-market angle anchored in technician training partnerships addresses the certification gap lagging equipment deployment velocity. For Investors and Strategic Acquirers: Re-rating potential sits with MDSAP-certified mid-cap manufacturers given COFEPRIS alignment with international audit recognition reducing redundant facility inspections. Long-term viability over the next decade favors targets with established Mexican regulatory infrastructure and direct clinic network relationships. Monitor NOM-240 pharmacovigilance update implementation timelines as an inflection indicator for compliance cost burdens shifting market structure.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS MDSAP Certification Investment | Accelerates Class II and III device import clearances for foreign manufacturers holding FDA or Health Canada certifications. |
| Direct Clinic Network Supply Contracts | Bypasses traditional distributor markups in Mexico City and Monterrey metropolitan procurement channels. |
| Chairside CAD/CAM System Deployment | Captures same-day restoration revenue previously lost to external laboratories across Guadalajara networks. |
| Technician Certification Program Development | Addresses training availability lagging intraoral scanner and milling equipment sales velocity. |
| Titanium Alloy Supply Agreement | Reduces margin exposure to spot market volatility for implant manufacturers in import-dependent supply chains. |
Study Parameters
COFEPRIS registration databases, Mexican customs import records, and hospital procurement disclosures formed the secondary backbone of this analysis. Primary interviews with dental clinic chain procurement directors, biomedical equipment distributors, and COFEPRIS regulatory consultants combined with secondary validation across these sources. Bottom-up triangulation against top-down macroeconomic indicators anchored volume estimates. Segmentation modeling captured product type splits, technology tiers, application categories, and end-user channel structures.
Historical trendline analysis of restorative material volumes and capital equipment deployment patterns informed projection frameworks across the analysis window. Analytical modeling incorporated price elasticity differentials between federal contract and private-pay segments, COFEPRIS clearance velocity variations by device class, and geographic concentration of clinic network expansion. CAGRs derived from regression analysis of import growth trajectories and equipment installation rates. Forecast inputs included titanium alloy price indices and intraoral scanner adoption curves in metropolitan dental corridors.
Revisions become necessary when COFEPRIS regulatory updates alter Class III device review timelines, when titanium alloy supply disruptions extend beyond spot market volatility, or when domestic laboratory competition intensifies in border states. Practitioners should monitor NOM-240 implementation progress, MDSAP audit recognition expansion, and clinic network consolidation rates for early signals warranting forecast adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Obturators Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Impression System Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Crown Removal Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental Braces Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Aligners Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Dental Forceps Market