
 China Vascular Grafts Market | 2026-2036
China Vascular Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
China Vascular Grafts Market Intelligence
The capital-intensity divergence between domestic and multinational players is unwinding as local manufacturers scale cleanroom capacity and polymer synthesis capabilities. Medtronic plc leverages its integrated graft-textile operations to sustain premium positioning in aortic reconstructions. Shanghai Suokang Medical Implants anchors its competitive stance through domestic regulatory familiarity and cost-optimized polyester graft production. W.L. Gore & Associates differentiates via proprietary expanded polytetrafluoroethylene architectures that command preference in small-diameter bypass indications.
Vascular grafts are implantable tubular conduits, typically woven or knitted from polyethylene terephthalate or extruded from expanded polytetrafluoroethylene, designed to restore blood flow across diseased or damaged vascular segments. These devices must demonstrate burst strength exceeding 300 mmHg, suture retention resistance, and compliance matched to native vessel biomechanics to prevent intimal hyperplasia and graft failure. Synthetic grafts occupy the dominant revenue position due to standardized manufacturing scalability and broad surgical familiarity, while biological grafts capture expanding share in pediatric and infection-prone settings where tissue integration and biocompatibility outweigh cost considerations. Endovenous grafts represent the fastest-growing product category as catheter-based delivery techniques displace open surgical harvest in select venous insufficiency protocols.
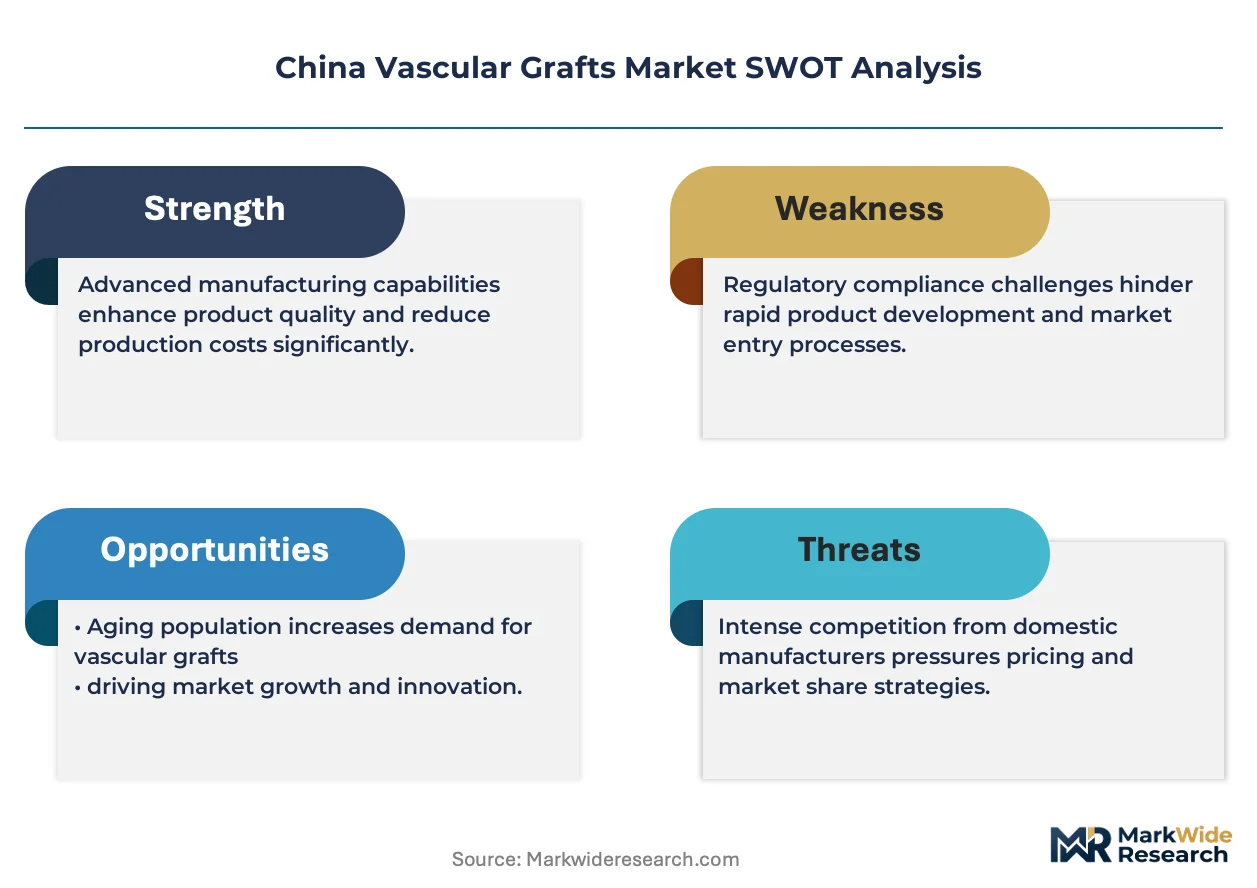
NMPA oversight through Class III medical device registration mandates extensive biocompatibility testing and clinical trial evidence for permanent implants, elevating barriers for new entrants while reinforcing incumbent quality systems. GB standards for surgical implants align with ISO 10993 biological evaluation frameworks, creating dual-compliance obligations for manufacturers targeting both domestic and export markets. Stakeholders must monitor NMPA's evolving technical review guidelines for tissue-engineered vascular constructs, as these determinations will reshape competitive boundaries between synthetic, biological, and hybrid graft platforms.
Market Dynamics
NMPA's tightening Class III device registration timelines are compressing product development cycles, forcing manufacturers to front-load clinical evidence generation while tier-three hospitals in Shanghai and Beijing accelerate adoption of advanced graft solutions for complex aortic reconstructions.
Growth Catalysts
- Dialysis access expansion:End-stage renal disease prevalence drives graft demand for arteriovenous access in tier-three hospitals. Polyester and ePTFE configurations dominate this indication due to puncture resistance and long-term patency requirements.
- GB standards alignment:Harmonization with ISO 10993 biological evaluation frameworks streamlines dual-market certification for domestic manufacturers targeting export opportunities. This reduces redundant testing burdens while elevating quality benchmarks.
- Catheter-based delivery maturation:Endovenous graft platforms capture share in venous insufficiency protocols as interventional cardiologists shift from open surgical harvest. Training infrastructure expansion in Beijing and Guangzhou accelerates technique dissemination.
Market Restraints
- Polymer feedstock concentration:Medical-grade PET and ePTFE resin supply concentrates among multinational chemical suppliers, exposing domestic graft manufacturers to import dependency and currency fluctuation risk.
- NMPA clinical trial mandates:Class III implantable device registration requires extensive local clinical evidence, extending time-to-market for novel graft architectures and favoring incremental modifications over breakthrough designs.
- Biological graft cost premium:Tissue-engineered and xenogeneic constructs face price resistance in volume-driven procurement environments, limiting penetration beyond pediatric and infection-prone niches.
Strategic Opportunities
- Central China hospital network expansion:Tier-two facilities in Chengdu and Wuhan are upgrading vascular surgery capabilities, creating first-mover advantage for graft suppliers establishing direct procurement relationships.
- Tissue-engineered hybrid platforms:Cell-seeded synthetic scaffolds combining mechanical durability with biological integration address unmet needs in small-diameter bypass applications where pure synthetics fail.
- Provincial centralized procurement adaptation:Volume-based purchasing pilots in Jiangsu and Zhejiang reward manufacturers with domestic production scale and cost-optimized logistics networks.
Industry Challenges
- Cleanroom capacity scaling:ISO 14644 Class 7 and 8 facility construction requires substantial capital deployment, straining mid-tier manufacturers seeking to compete with multinational quality systems.
- Biocompatibility testing backlog:NMPA-designated laboratories face capacity constraints for cytotoxicity and sensitization studies, delaying submission timelines for novel graft materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Vascular Grafts Market |
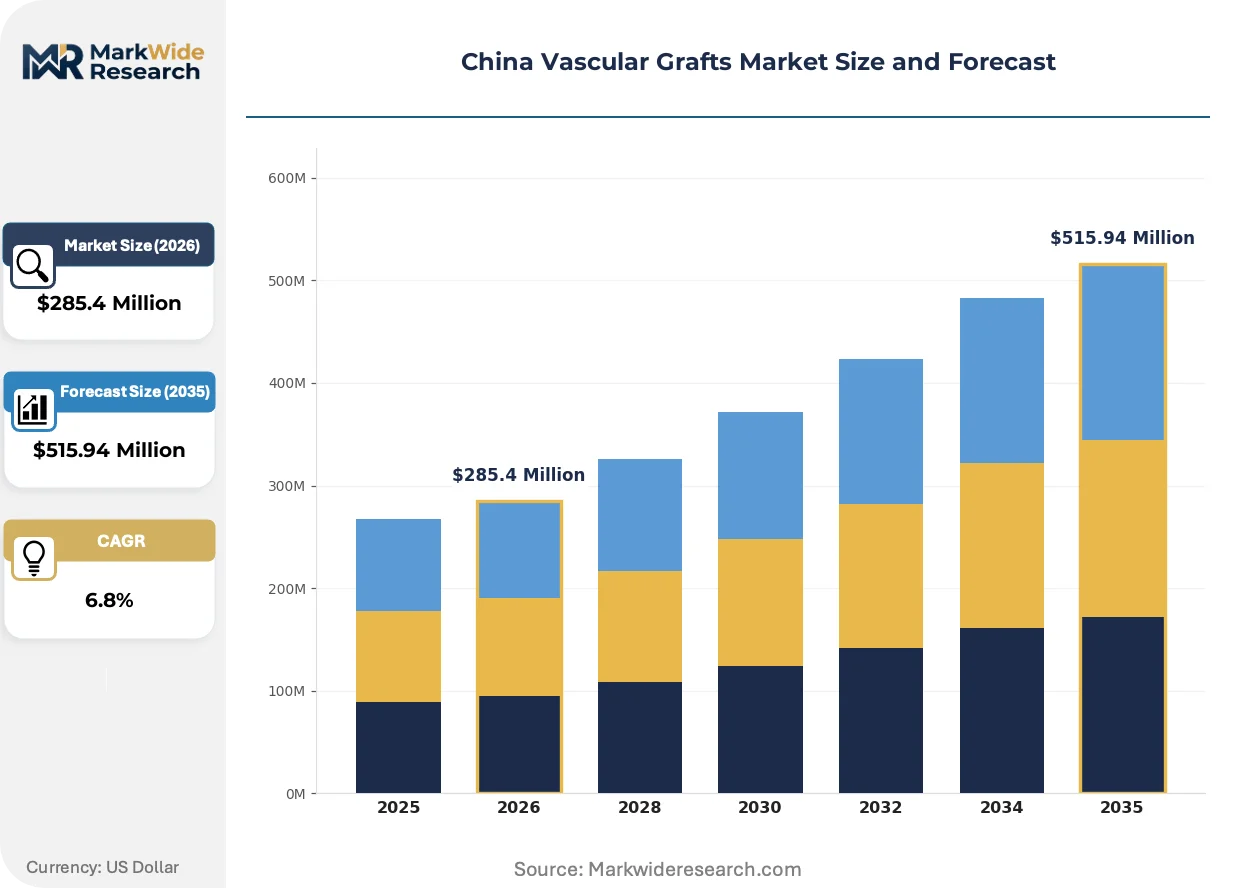
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Grafts, Biological Grafts, Combination Grafts, Endovenous Grafts Material: Polyester, Polytetrafluoroethylene, Collagen, Dacron End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Laboratories Application: Cardiovascular Surgery, Peripheral Vascular Surgery, Dialysis Access, Trauma Surgery |
| Companies Covered | W.L. Gore & Associates, Terumo Corporation, Getinge AB, Medtronic plc, LeMaitre Vascular, C.R. Bard, Cook, Shanghai Suokang Medical Implants, Becton Dickinson & Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Vascular Grafts Market Strategic Shifts & Innovations
Catheter-based deployment systems are redefining graft delivery economics, compressing procedure times and shifting site-of-care patterns while regulatory frameworks scramble to accommodate real-world evidence generation for these minimally invasive platforms.
Endovenous graft technology is decomposing traditional open surgical workflows in venous insufficiency treatment. Interventional suites in Shanghai's tier-three hospitals are adopting these platforms at accelerating pace. The technology is decomposing referral patterns between vascular surgeons and interventional cardiologists, creating new competitive battlegrounds for device selection influence.
NMPA's evolving technical review guidelines for tissue-engineered vascular constructs are elevating preclinical evidence requirements. Domestic manufacturers must demonstrate scaffold degradation kinetics and neotissue formation in large-animal models. Synthetic-biological hybrid graft categories face the steepest compliance burden as regulators parse boundaries between device and biologic classification.
Hospital procurement committees are consolidating supplier relationships around full-line vascular solution providers. Tier-three facilities in Beijing increasingly bundle graft procurement with endovascular device and imaging system contracts. This concentration trend is most visible in municipal hospital networks where centralized purchasing offices negotiate multi-year supply agreements.
China Vascular Grafts Market Segmentation
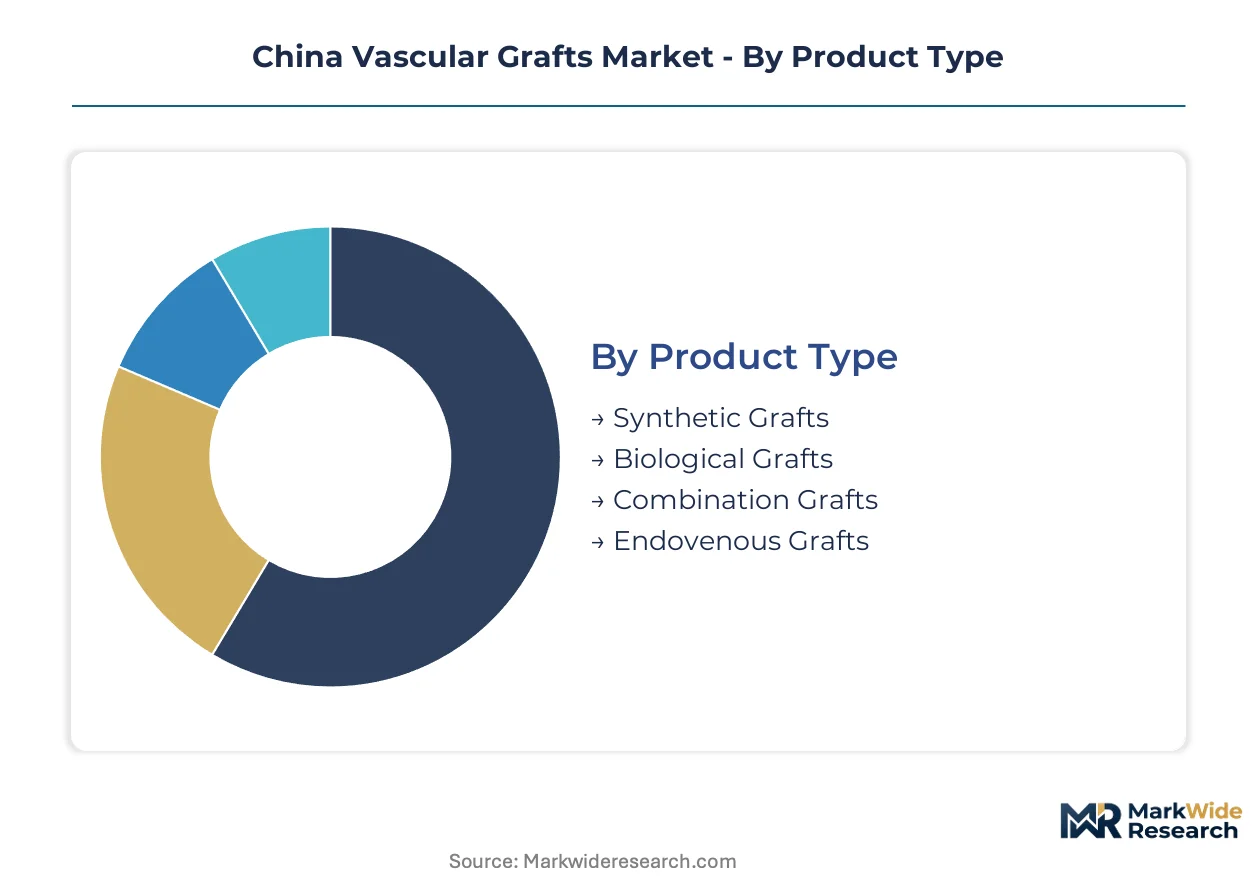
Vascular graft segmentation in China reflects divergent supply chain realities: synthetic platforms dominate domestic manufacturing capacity while biological and hybrid architectures depend on imported tissue-engineering inputs. Procurement committees in Shanghai and Beijing tier-three hospitals weight material specifications against NMPA registration status when segmenting vendor shortlists.
Product Type:
Domestic production concentrates in synthetic platforms where polymer synthesis capabilities anchor manufacturing scale; biological and hybrid categories remain import-dependent due to cell-culture and tissue-processing constraints.
- Synthetic Grafts:Woven or knitted polyethylene terephthalate and extruded expanded polytetrafluoroethylene conduits deliver burst strength exceeding 300 mmHg with standardized manufacturing scalability. Demand concentrates in tier-three hospitals across Shanghai and Beijing for aortic reconstructions and dialysis access procedures, driven by established surgeon familiarity and cost-optimized procurement frameworks.
- Biological Grafts:Tissue-engineered and xenogeneic constructs prioritize biocompatibility and cellular integration over mechanical durability. Pediatric cardiac centers and infection-prone cases in Guangzhou specialist hospitals drive niche adoption, constrained by price resistance in volume-driven purchasing environments.
- Combination Grafts:Cell-seeded synthetic scaffolds merge mechanical performance with biological integration potential.
- Endovenous Grafts:Catheter-deployable platforms for venous insufficiency protocols.
Synthetic grafts hold the largest share; momentum sits with endovenous platforms as interventional suites expand across tier-three hospital networks.
Material:
Material selection tracks directly to application-specific performance requirements: polyester and ePTFE serve high-pressure arterial indications while collagen addresses biocompatibility-critical niches.
- Polyester:Woven polyethylene terephthalate delivers puncture resistance and long-term patency for dialysis access grafts. Domestic manufacturers in Jiangsu and Zhejiang have scaled cleanroom capacity for medical-grade PET processing, reducing import dependency for standard-diameter configurations.
- Polytetrafluoroethylene:Expanded PTFE architectures command preference in small-diameter bypass applications where compliance matching to native vessel biomechanics prevents intimal hyperplasia. Shanghai Suokang and multinational suppliers compete on proprietary node-fibril microstructures that influence suture retention and tissue ingrowth kinetics.
- Collagen:Biological matrix material for tissue-engineered constructs.
- Dacron:Branded polyester variant with established surgical familiarity.
Polyester and polytetrafluoroethylene together dominate procurement volumes; collagen is expanding most quickly in pediatric specialist settings.
End User:
End-user segmentation reflects site-of-care economics: tier-three hospitals absorb complex reconstructive procedures while ambulatory centers capture catheter-based delivery growth.
- Hospitals:Tier-three facilities in Beijing, Shanghai, and Guangzhou perform complex aortic reconstructions, peripheral bypasses, and dialysis access procedures requiring immediate ICU backup and multidisciplinary surgical teams. NMPA Class III device registration mandates align procurement decisions with established quality systems and clinical evidence portfolios.
- Ambulatory Surgical Centers:Catheter-based endovenous graft deployment shifts lower-acuity venous insufficiency procedures to outpatient settings. Chengdu and Wuhan ASC networks are upgrading interventional capabilities to capture this volume migration from traditional hospital admission workflows.
- Clinics:Limited to post-operative monitoring and graft surveillance.
- Research Laboratories:Preclinical testing and tissue-engineering development.
Hospitals retain the dominant procurement position; ambulatory surgical centers are gaining share fastest as catheter-based protocols mature.
Application:
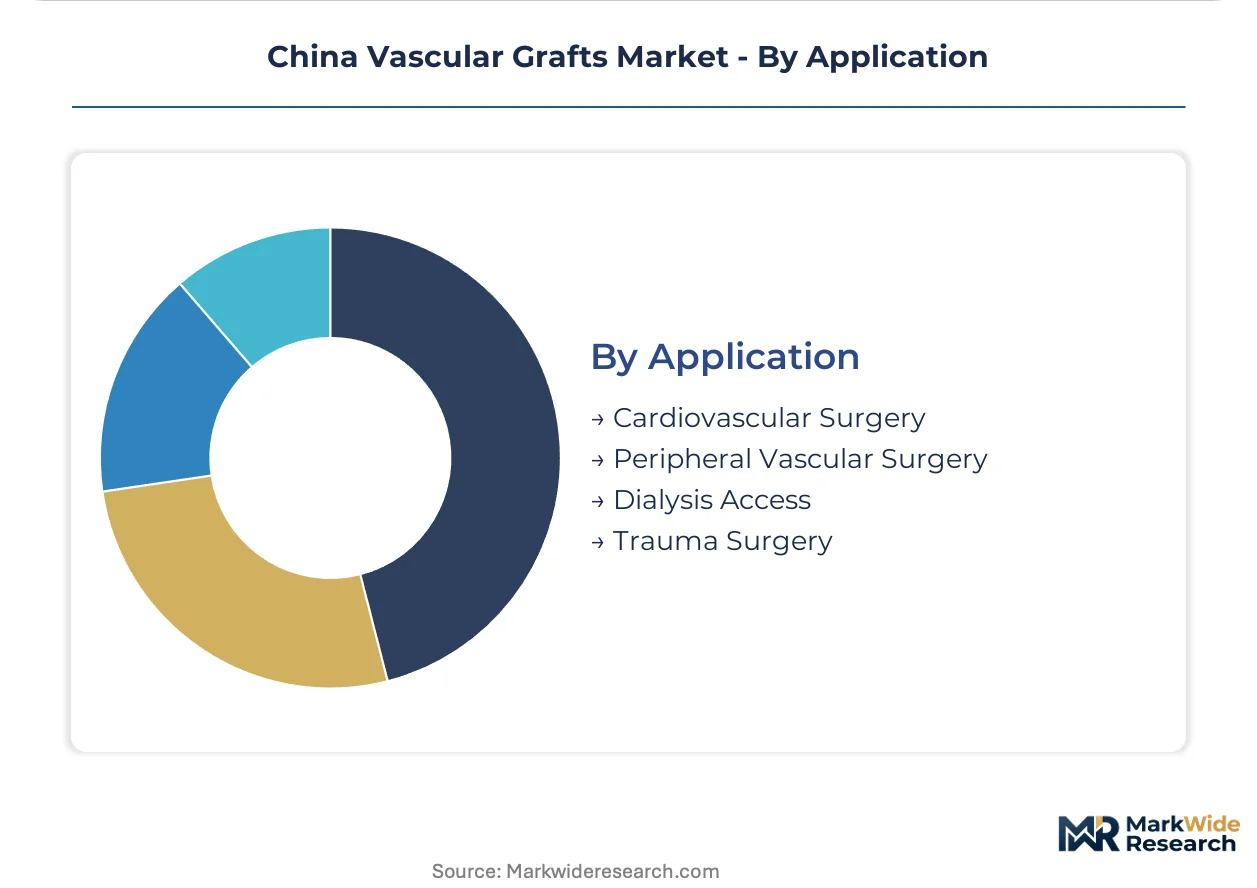
Application segmentation tracks disease prevalence and reimbursement pathways: dialysis access expansion drives volume while cardiovascular surgery commands premium pricing.
- Cardiovascular Surgery:Aortic aneurysm repair and coronary artery bypass grafting demand high-performance synthetic conduits with demonstrated long-term patency. Beijing Anzhen Hospital and Fuwai Hospital anchor demand concentration for ascending aorta and arch reconstructions requiring custom-fenestrated graft configurations.
- Dialysis Access:End-stage renal disease prevalence generates sustained graft demand for arteriovenous fistula alternatives and bridge configurations. Polyester and ePTFE grafts dominate this indication due to repeated cannulation tolerance and infection resistance requirements in Shanghai's municipal hospital networks.
- Peripheral Vascular Surgery:Lower-extremity bypass and revascularization procedures.
- Trauma Surgery:Emergency vascular repair requiring rapid graft deployment.
Cardiovascular surgery captures the highest value per procedure; dialysis access delivers the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Beijing command pricing premiums for complex aortic reconstructions while provincial hubs in Sichuan and Hubei compete on volume throughput for dialysis access procedures. This geographic asymmetry concentrates procurement power in coastal tier-three hospitals.
Beijing-Tianjin-Hebei
Fuwai Hospital and Beijing Anzhen Hospital anchor demand for ascending aorta and arch reconstructions requiring custom-fenestrated graft configurations. NMPA Class III device registration mandates align procurement with established quality systems. Municipal hospital networks consolidate supplier relationships around full-line vascular solution providers.
Yangtze River Delta
Shanghai's tier-three facilities drive adoption of catheter-based endovenous graft platforms for venous insufficiency protocols. GB standards alignment with ISO 10993 frameworks streamlines dual-market certification for domestic manufacturers. Ruijin Hospital and Zhongshan Hospital anchor complex peripheral bypass volumes.
Pearl River Delta
Guangzhou specialist hospitals generate niche demand for biological grafts in pediatric cardiac centers and infection-prone cases. Provincial centralized procurement pilots in Jiangsu and Zhejiang reward manufacturers with domestic production scale. Sun Yat-sen University hospitals anchor tissue-engineered construct evaluation.
Sichuan-Chongqing
Chengdu's tier-two facilities upgrade vascular surgery capabilities for lower-acuity venous procedures shifting from traditional hospital workflows. NMPA clinical trial mandates extend time-to-market for novel graft architectures. West China Hospital anchors complex reconstruction training infrastructure.
Shandong Peninsula
Qingdao and Jinan municipal networks expand dialysis access graft volumes for end-stage renal disease prevalence. Cleanroom capacity scaling strains mid-tier manufacturers seeking ISO 14644 Class 7 compliance. Provincial procurement offices negotiate multi-year polyester and ePTFE supply agreements.
China Vascular Grafts Market Key Industry Players
Concentration sits with multinational integrated graft-textile operations sustaining premium positioning through proprietary polymer architectures and established surgeon training infrastructure. Domestic manufacturers scale cost-optimized polyester production while navigating NMPA regulatory tightening. Three archetypes define competitive positioning: integrated multinationals with captive polymer synthesis, domestic specialists leveraging regulatory familiarity, and hybrid-platform innovators bridging synthetic durability with biological integration. Capacity expansion and strategic partnerships dominate competitive moves as players secure cleanroom certification and clinical evidence portfolios.
Among multinational suppliers, W.L. Gore & Associates and Medtronic plc occupy positions exemplifying premium-tier integrated operations through proprietary expanded polytetrafluoroethylene and graft-textile capabilities. Shanghai Suokang Medical Implants represents the domestic specialist archetype, anchoring cost-optimized production within NMPA regulatory pathways. These three entities illustrate the competitive tension between import-dependent advanced architectures and scaled domestic manufacturing.
| Leading Market Players |
|---|
| W.L. Gore & Associates |
| Terumo Corporation |
| Getinge AB |
| Medtronic plc |
| LeMaitre Vascular |
| C.R. Bard |
| Cook |
| Shanghai Suokang Medical Implants |
| Becton Dickinson & Co |
| Others |
Cost & Logistics Intelligence
Medical-grade PET resin lead times stretching 90-120 days compress working capital cycles for domestic graft manufacturers while amplifying pricing power for multinational chemical suppliers with captive polymer synthesis. This inventory tension concentrates procurement leverage among tier-three hospitals in Beijing and Shanghai that negotiate multi-year supply agreements.
Pricing Analysis
The customization-premium spread between configured-to-order fenestrated grafts and standard polyester configurations widens as Beijing's municipal hospital networks demand patient-specific aortic arch reconstructions. Pricing stratifies across premium, standard, and economy tiers anchored by NMPA Class III certification status, brand heritage, and surgical training bundling. Cost compression in standard-diameter polyester grafts is intensifying because provincial centralized procurement pilots in Jiangsu and Zhejiang reward volume scale. Dialysis access programs exhibit highest price sensitivity; complex aortic reconstruction centers demonstrate lowest.
Supply Chain Analysis
Inventory lead-time volatility in medical-grade ePTFE resin draws from concentrated polymer feedstock production in the United States, Germany, and Japan. Raw material dependencies center on high-purity PET chips, expanded PTFE membranes, and biological scaffold matrices. Single-source vulnerability concentrates in specialized ePTFE node-fibril microstructures where W.L. Gore maintains proprietary process control. Distribution runs through tier-three hospital procurement committees consolidating around full-line vascular solution providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against catheter-based endovenous ablation platforms that displace synthetic graft demand in venous insufficiency protocols. Incumbents must navigate this structural threat while securing polymer supply and regulatory evidence portfolios.
For Market Incumbents: Fortify backward integration into medical-grade PET synthesis to reduce import dependency exposure. Secure NMPA Class III registration expansions for hybrid graft architectures before technical review guidelines tighten. Anchor procurement relationships with tier-three hospital networks through bundled endovascular device contracts that raise switching costs against emerging domestic competitors.
For New Entrants and Emerging Players: Anchor in tier-two vascular surgery upgrades across Chengdu and Wuhan where established suppliers lack direct procurement presence. Target biological graft niches in pediatric cardiac centers where price resistance softens and tissue-engineering differentiation commands premium positioning. Pursue hospital system partnerships offering graft surveillance and post-operative monitoring services as bundled go-to-market entry.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across tissue-engineered hybrid platforms as NMPA preclinical evidence requirements escalate. Long-term viability favors manufacturers with demonstrated scaffold degradation kinetics in large-animal models and established cleanroom certification. Acquisition target archetype: domestic specialists with scaled polyester production and pending Class III registrations. Signal to watch: NMPA technical review guideline finalization for cell-seeded constructs.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Expansion | Accelerates market access for novel graft architectures before regulatory barriers escalate. |
| Backward Integration into Polymer Synthesis | Reduces import dependency for medical-grade PET and ePTFE resin feedstocks. |
| Hospital System Partnership | Secures multi-year procurement contracts with tier-three Beijing and Shanghai facilities. |
| Hybrid Graft Platform Development | Addresses unmet small-diameter bypass needs where pure synthetics fail. |
| Provincial Centralized Procurement Adaptation | Aligns cost-optimized logistics with Jiangsu and Zhejiang volume-based purchasing pilots. |
Research Approach
A spread of perspectives from vascular surgeons, hospital procurement committee directors, biomedical engineers, and NMPA regulatory consultants converged on the working assumptions underlying this analysis. Primary interviews with GPO contracts managers and tier-three hospital purchasing officers combined with secondary validation against NMPA registration databases, hospital procurement records, and GB standards documentation. Bottom-up graft volume modeling triangulated against top-down market sizing across synthetic, biological, and endovenous product categories.
Segmentation dimensions modeled include product type, material composition, end-user facility tier, and application indication across the projection horizon. CAGRs derived from procedure volume trajectories, reimbursement pathway evolution, and technology substitution curves. Forecast inputs incorporated dialysis access expansion rates, catheter-based delivery technique dissemination, and NMPA regulatory timeline compression.
Material uncertainties — NMPA technical review guideline revisions, polymer feedstock supply disruptions, and endovenous platform substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these industry-specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Self-Expanding Stents Market