
 Antiglare Glass Market | 2026-2036
Antiglare Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Antiglare Glass Market Intelligence
Direct sales channels to major automotive and electronics original equipment manufacturers (OEMs) are reconfiguring the market's traditional reliance on regional distributors. Corning Inc. leverages its deep OEM relationships in the electronics sector to secure long-term supply contracts. Saint-Gobain dominates the European automotive glass supply chain through its established logistics network. Schott AG specializes in high-performance glass for specialty electronics and medical displays, often using a direct-to-customer model.
Antiglare glass is a type of specialty glass engineered to diffuse reflected light, minimizing unwanted glare. This is typically achieved through acid etching or the application of a micro-structured coating that creates a matte surface. The electronics end-user segment, particularly for displays and monitors, commands the highest value due to stringent performance requirements. Coated glass types are gaining share over traditional etched glass in automotive applications, driven by the need for higher optical clarity and durability.
Product specifications are shaped by multiple regulatory frameworks. In the United States, NHTSA guidelines for driver distraction influence display glare characteristics, while in Europe, CE marking is mandatory for electronic products incorporating antiglare screens. Future material selection will hinge on balancing the cost of advanced coating technologies against evolving OEM requirements for optical performance and energy efficiency.
Market Dynamics
The market's central dynamic is the escalating demand from the automotive sector for display glass that meets stringent cockpit safety and user experience standards. This shift is elevating performance requirements beyond those of traditional consumer electronics.
Growth Catalysts
- Automotive Display Proliferation:The integration of large, high-resolution screens for digital cockpits, infotainment, and advanced driver-assistance systems (ADAS) directly fuels demand for effective glare reduction.
- Driver Safety Regulations:Guidelines from bodies like the US NHTSA concerning driver distraction are compelling automotive OEMs to adopt antiglare solutions to ensure display legibility in all ambient lighting conditions.
- Emerging Applications in Medical Devices:The need for clear, readable displays on diagnostic and surgical equipment, often used under intense operating room lighting, is creating a high-margin growth vector for specialty antiglare glass.
Market Restraints
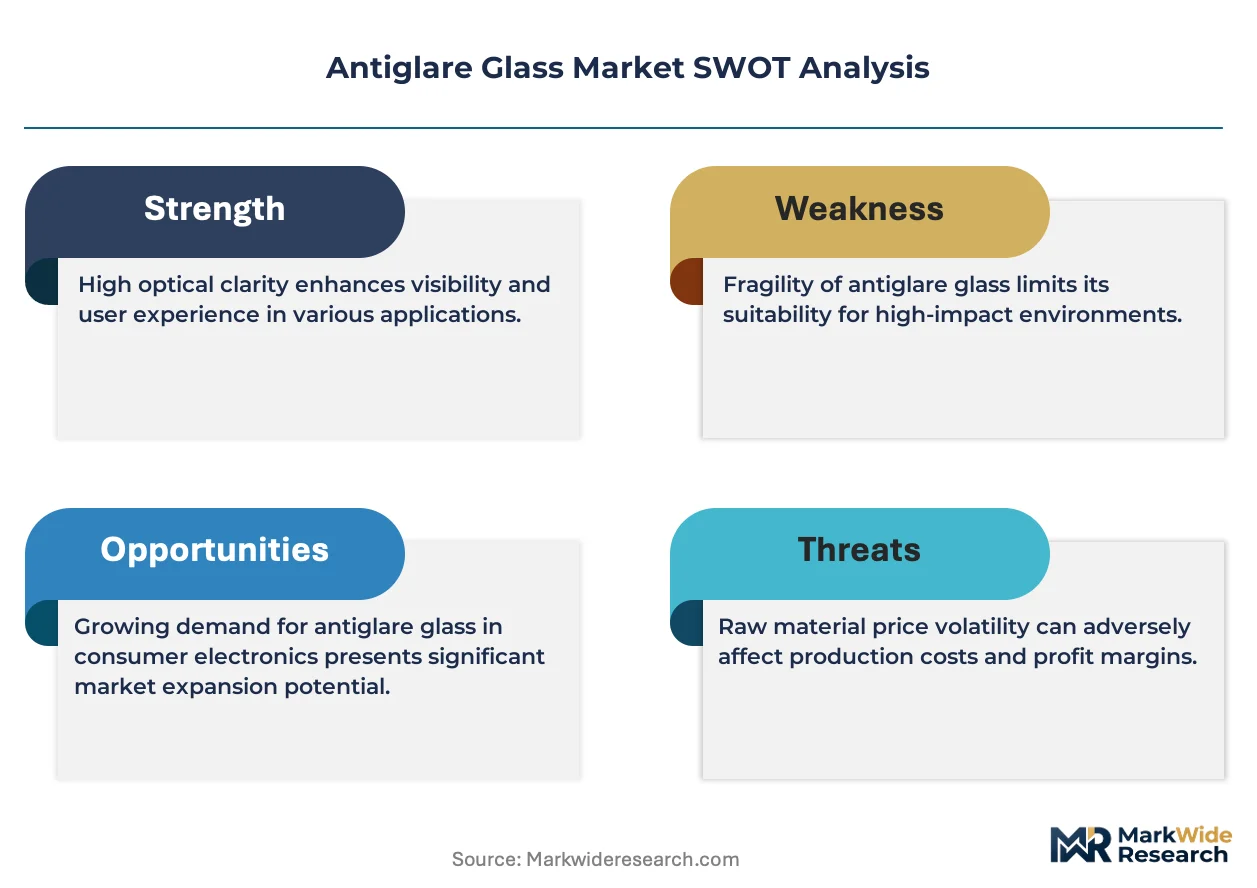
- High Production Costs:The capital-intensive nature of acid etching and vacuum deposition coating processes, combined with the cost of high-purity raw materials, presents a significant barrier to entry and constrains margins.
- Optical Performance Trade-offs:A key technical challenge is balancing antiglare effectiveness (haze) with optical clarity, a trade-off magnified by high-resolution 4K and 8K displays.
- Substitution by Polymer Films:Lower-cost antiglare polymer films, while offering inferior durability and optical quality, represent a persistent substitution threat for cost-sensitive consumer electronics and aftermarket automotive applications.
Strategic Opportunities
- Smart Architectural Glass:Integrating antiglare properties into architectural smart glass creates a new market for dynamic glare control, improving occupant comfort and energy efficiency.
- Aerospace and Defense Displays:Cockpit displays in aviation and ruggedized screens in defense applications demand extreme durability and readability under challenging conditions, representing a high-value niche for advanced antiglare technologies.
- Anti-Reflective/Antiglare Hybrids:Developing hybrid coatings that combine the light-diffusing properties of antiglare surfaces with the light-transmission benefits of anti-reflective coatings can address the most demanding optical performance requirements.
Industry Challenges
- Complex OEM Qualification Cycles:Suppliers face long qualification cycles with automotive and electronics OEMs, requiring extensive testing and customization for each new product platform.
- Yield Rate Management:Achieving consistently high manufacturing yields for large-format, defect-free antiglare glass is a major operational challenge, with microscopic imperfections leading to costly rejection by quality-sensitive customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiglare Glass Market |
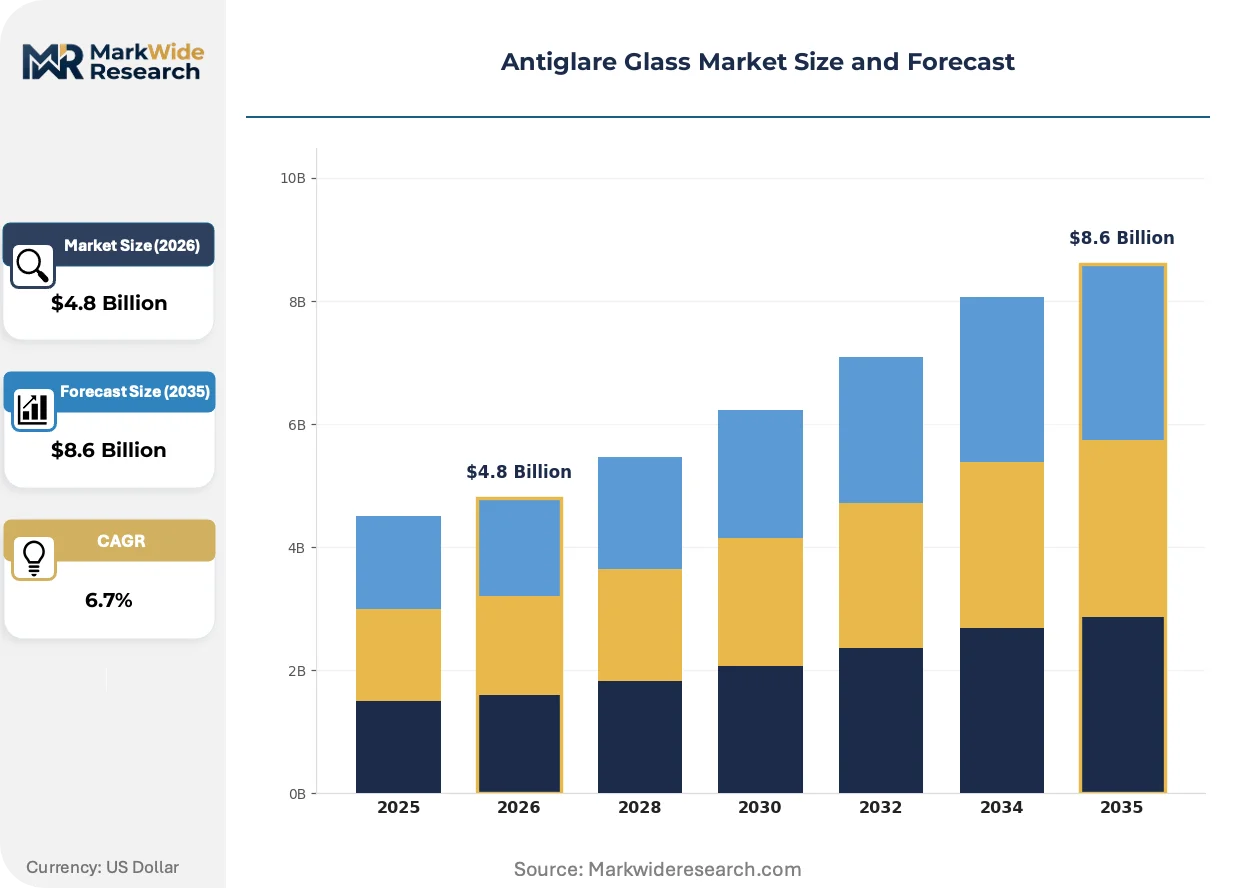
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Acrylic Glass End User: Automotive, Residential, Commercial, Electronics Application: Windows, Displays, Tablets, Monitors Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | AGC Inc, Corning Inc, Guardian Glass, PPG Industries, Saint-Gobain, Schott AG, Nippon Sheet Glass, Xinyi Glass Holdings, WPM Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiglare Glass Market Strategic Shifts & Innovations
Performance requirements are converging around multi-functional surfaces where antiglare is one of several integrated properties. This evolution is driven by user experience demands in automotive cockpits and premium electronics, moving beyond simple glare reduction to a holistic surface solution.
Advanced multi-layer coatings now integrate antiglare functionality with anti-reflective, anti-smudge, and hydrophobic properties. High-end automotive and consumer electronics OEMs are rapidly adopting these complex surfaces to enhance both durability and user interaction. This integration of functions into a single, engineered surface treatment is collapsing the traditional separation between distinct coating layers and the base glass itself.
Europe's CE marking framework, particularly for products falling under the Low Voltage and EMC Directives, indirectly influences antiglare specifications. These rules imply that displays must maintain sufficient legibility, indirectly setting performance floors for antiglare solutions. The consumer electronics segment is most affected, pushing manufacturers toward standardized, high-performance antiglare screens for products intended for the EU market.
A shift toward direct sourcing by large OEMs is altering supply chain dynamics. Automotive and technology companies are bypassing distributors to engage directly with glass finishers, gaining control over specifications, quality, and cost. This pattern is evident in Germany's automotive sector and South Korea's electronics industry.
Antiglare Glass Market Segmentation
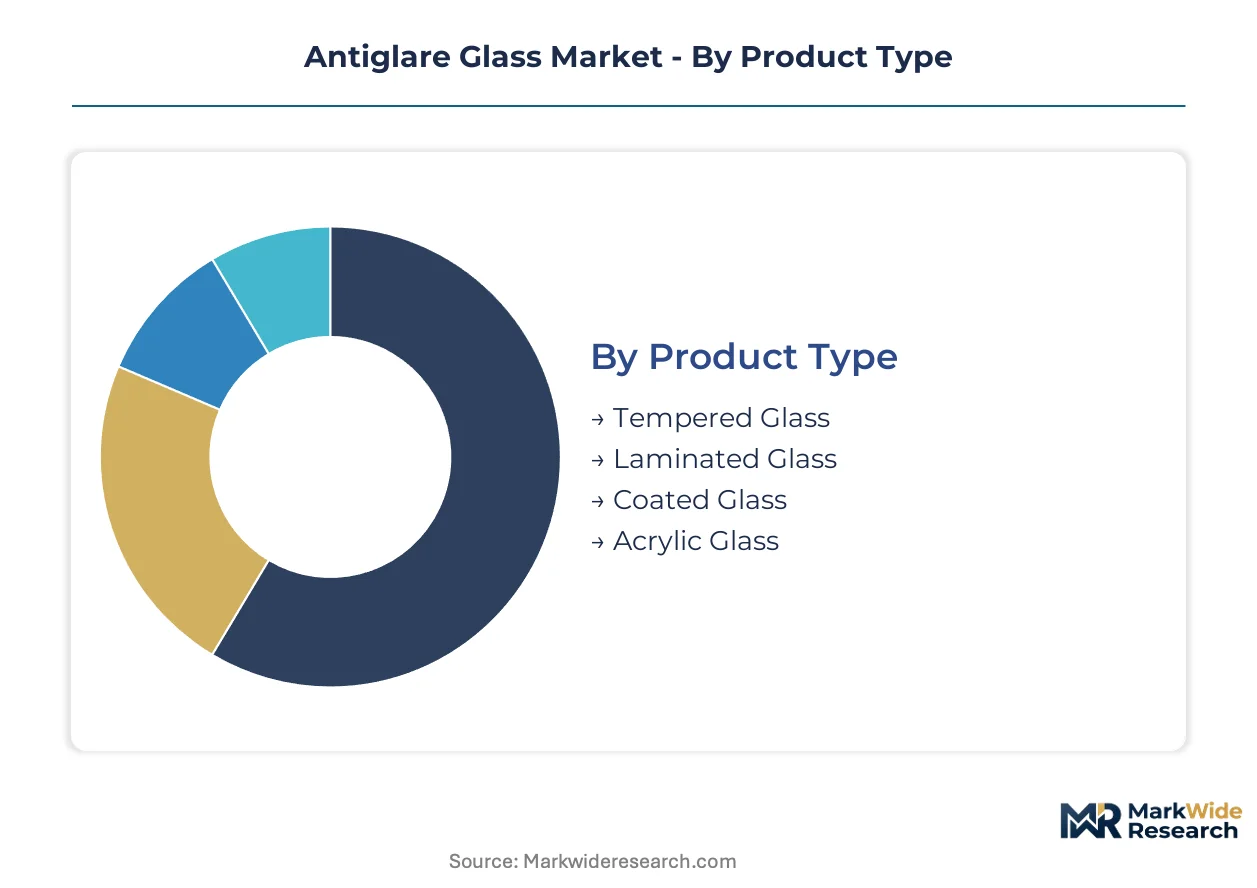
Understanding the market's segmentation is critical for identifying specific demand pockets and technological requirements within the antiglare glass industry. Each segment presents unique challenges and opportunities, influencing product development and strategic market entry for manufacturers.
Product Type:
The antiglare glass market's product type spectrum ranges from basic protective layers to advanced optical solutions, each designed for specific performance requirements.
- Coated Glass:Achieves antiglare through micro-structured coatings, offering superior optical clarity and durability compared to traditional methods. Demand is concentrating in high-end automotive applications due to stringent performance requirements and the need for integrated functionalities.
- Tempered Glass:Undergoes thermal or chemical treatment to increase strength and safety, often serving as a robust substrate for advanced antiglare treatments. Automotive digital cockpits and large-format displays increasingly require its enhanced mechanical properties.
- Laminated Glass:Consists of multiple glass layers bonded by an interlayer, enhancing safety and sound insulation for architectural and specialized automotive uses.
- Acrylic Glass:A lightweight, shatter-resistant plastic alternative, primarily used in cost-sensitive consumer electronics or less demanding display applications where optical performance is secondary.
The dominant share belongs to Tempered Glass due to its widespread use as a base, while Coated Glass is closing the gap fastest in terms of value contribution.
End User:
Application diversity defines the end-user landscape, with each sector demanding tailored antiglare properties for its specific operational environment.
- Automotive:Integrates antiglare glass into digital cockpits, infotainment systems, and advanced driver-assistance system (ADAS) displays to enhance driver safety and user experience. Demand is concentrated in Germany's automotive production centers.
- Electronics:Utilizes antiglare solutions for displays, monitors, and touchscreens, particularly in South Korea and Taiwan, requiring high optical clarity and durability.
- Residential:Incorporates antiglare glass into smart home displays, mirrors, and windows for improved visual comfort and aesthetic appeal within living spaces.
- Commercial:Employs antiglare screens for public information displays, digital signage, and architectural glazing to reduce reflections and enhance visibility in business settings.
The automotive sector represents the fastest-growing end-user segment, driven by escalating demand for advanced cockpit displays.
Application:
Functional requirements dictate the specific antiglare properties needed across various applications, from large-format surfaces to portable devices.
- Displays:Encompasses a broad range of interactive and informational screens, including those in digital cockpits and medical equipment, where antiglare properties are critical for legibility. Performance requirements are particularly stringent for high-resolution 4K and 8K displays.
- Monitors:Primarily used in professional and consumer computing environments, these applications demand antiglare features to reduce eye strain and improve visual comfort during prolonged use. Stringent performance standards are set by professional users.
- Windows:Refers to architectural and vehicle windows where antiglare coatings can enhance visibility and reduce solar heat gain for occupants.
- Tablets:Portable electronic devices that integrate antiglare glass to improve outdoor readability and protect screens from reflections in various environments.
Displays and Monitors collectively account for the majority of antiglare glass consumption, reflecting their central role in visual information delivery.
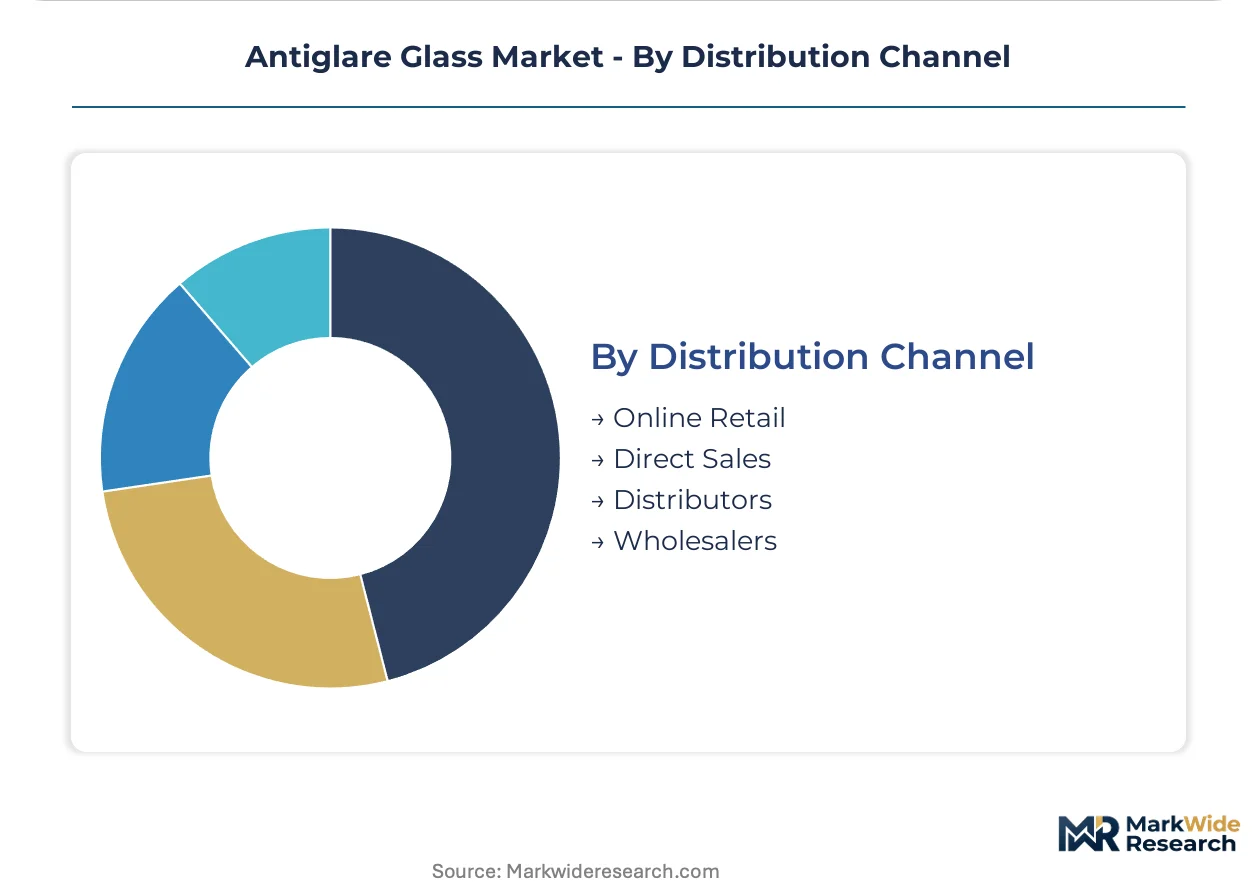
Distribution Channel:
Supply chain dynamics for antiglare glass are undergoing reconfiguration, with procurement patterns shifting across various distribution channels.
- Direct Sales:Involves direct engagement between antiglare glass manufacturers and major automotive and electronics original equipment manufacturers, facilitating customized solutions and long-term supply contracts. Corning Inc. leverages this model for electronics.
- Distributors:Traditionally served as intermediaries, providing regional market access and logistical support, but their role is being reconfigured by OEMs seeking direct sourcing. Saint-Gobain utilizes its established logistics network for European automotive supply.
- Online Retail:Facilitates the sale of antiglare screen protectors and aftermarket solutions directly to consumers, offering convenience and broad product selection.
- Wholesalers:Aggregate products from multiple manufacturers for bulk resale to smaller businesses and regional integrators, primarily for less specialized applications.
Direct Sales are gaining momentum as large OEMs prioritize control over specifications and quality, challenging traditional distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA guidelines in the United States and CE marking in Europe are compelling global automotive and electronics manufacturers to integrate advanced antiglare glass. These regulatory pressures, coupled with incentives for local manufacturing, drive demand across key production hubs. This fosters innovation and deployment of sophisticated display solutions.
United States
The United States market is driven by escalating demand for advanced automotive digital cockpits and ADAS displays. NHTSA guidelines on driver distraction compel vehicle manufacturers to adopt high-performance antiglare solutions. Michigan's automotive manufacturing cluster integrates these specialized glass types into next-generation vehicle platforms.
Germany
Germany exhibits strong demand for antiglare glass in its premium automotive and high-precision industrial electronics sectors. KBA regulations for vehicle components and CE marking influence display legibility standards. Bavaria's automotive and machinery manufacturing clusters integrate sophisticated antiglare solutions.
South Korea
South Korea's electronics manufacturing prowess fuels demand for antiglare glass in consumer displays and advanced automotive components. National display technology initiatives and MFDS standards drive performance requirements. The Seoul Capital Area's vast electronics manufacturing base implements cutting-edge antiglare solutions.
Taiwan
Taiwan's robust high-tech electronics and display panel production drives substantial demand for specialized antiglare glass. ITRI initiatives promote research and development in advanced display materials. The Hsinchu Science Park, a hub for semiconductors and displays, integrates these advanced glass technologies.
China
China represents a massive market for antiglare glass, driven by its vast consumer electronics sector and rapidly expanding EV production. GB standards for display safety and dual carbon goals encourage energy-efficient solutions. The Yangtze River Delta integrates antiglare glass into diverse applications, including smart architectural glass.
Antiglare Glass Market Key Industry Players
On the supply side, the industry is moderately concentrated among established glass manufacturers but also features specialized coating providers and material science innovators. Global glass giants leverage extensive manufacturing capabilities, while niche players focus on advanced optical solutions for specific applications. Strategic archetypes include integrated glass producers, dedicated coating specialists, and polymer film manufacturers. These entities engage in strategic partnerships with OEMs, pursue portfolio diversification into multi-functional surfaces, and expand production capacity for coated glass.
Among integrated glass producers, Corning Inc. represents a significant player, leveraging deep OEM relationships in the electronics sector for long-term supply contracts. Saint-Gobain, a European-based glass giant, occupies a strong position within the European automotive glass supply chain, supported by its established logistics network. Schott AG, a German-based specialist, exemplifies high-performance glass for specialty electronics and medical displays, often utilizing a direct-to-customer model. These companies anchor different segments of the antiglare glass market, from large-volume electronics to niche, high-performance applications.
| Leading Market Players |
|---|
| AGC Inc |
| Corning Inc |
| Guardian Glass |
| PPG Industries |
| Saint-Gobain |
| Schott AG |
| Nippon Sheet Glass |
| Xinyi Glass Holdings |
| WPM Glass |
| Others |
Cost & Logistics Intelligence
High capacity utilization within advanced coating facilities in South Korea and Germany drives supplier behavior and influences pricing postures for antiglare glass. This operational intensity reflects strong demand from automotive and electronics OEMs.
Pricing Analysis
Volume-based pricing structures dominate the antiglare glass market, reflecting the scale of OEM procurement. Price differentiation stems from the specific optical performance requirements and the certification level needed for automotive safety standards. Pricing pressure stems from the capital-intensive nature of production processes and the emergence of lower-cost polymer film alternatives. Consumer electronics manufacturers exhibit higher price sensitivity compared to premium automotive OEMs.
Supply Chain Analysis
Major integrated glass manufacturers like Corning Inc. and Saint-Gobain concentrate significant production capacity for antiglare glass. Geographic supply concentration occurs in Taiwan, South Korea, and Germany, reflecting electronics and automotive hubs. Production relies on high-purity silica and specialized coating chemicals, creating single-source vulnerability for OEMs. Distribution runs through direct sales channels to large automotive and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antiglare glass market is experiencing a platform-economics inflection as multi-functional surfaces become standard. This shift is driven by the integration of antiglare with anti-reflective and anti-smudge properties in automotive cockpits.
For Market Incumbents:Build technological moats through continuous R&D in advanced coating technologies. Incumbents must deepen vertical integration into specialized raw material sourcing to mitigate supply chain disruptions. This defends against emerging polymer film alternatives and protects margins. Investing in long-term OEM qualification cycles further locks in market share against new entrants.
For New Entrants and Emerging Players:Build out niche capabilities in high-performance hybrid coatings for specialty applications like medical devices or aerospace displays. The medical device segment offers a penetrable white space due to its stringent performance requirements and higher margin potential. Focus on a value-based pricing model combined with rapid prototyping for customized solutions. This go-to-market angle bypasses established OEM relationships in mass-market automotive.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the high-performance coated glass sub-segment, driven by complex vacuum deposition processes. This market presents long-term viability over the next decade due to sustained automotive display proliferation and stringent safety regulations. Target mid-cap specialists with proprietary coating technologies or strong regional OEM relationships. The signal to watch is the adoption rate of multi-functional displays in new vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Coating R&D | Developing next-generation hybrid antiglare and anti-reflective surfaces enhances optical performance for premium automotive displays. |
| Expand Direct OEM Engagement | Securing long-term supply contracts with major electronics manufacturers in South Korea stabilizes revenue streams and market share. |
| Optimize Yield Rates for Large-Format Glass | Improving manufacturing efficiency for large digital cockpit displays reduces production costs and ensures consistent quality for automotive clients. |
| Diversify into Specialty Medical Applications | Targeting high-margin medical device displays creates new growth vectors beyond the competitive consumer electronics segment. |
| Pursue Regional Capacity Expansion | Establishing new production facilities in Germany supports localized supply chains for European automotive OEMs, meeting regional demand. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted for the antiglare glass market. Primary interviews involved automotive OEM display engineers, electronics product managers, and glass finishing plant managers. These insights cross-referenced secondary data from regulatory filings, industry association reports, and trade publications. Bottom-up and top-down triangulation validated market sizing and growth projections.
The calibration approach involved segmenting the market by product type, end-user, application, and distribution channel across the analysis window. Optical performance tier was modeled as an industry-specific dimension. Compound annual growth rates were derived from historical data and projected technological adoption. Key forecast inputs included automotive production forecasts and consumer electronics shipment volumes.
Stress conditions across raw material price volatility and OEM qualification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Cross-checking against industry-specific economic indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Mason Jars Market
Glass
Global Vacuum Insulated Glass Market
Glass
Laboratory Glass Container Market
Glass
Decorative Glass Market
Glass
Glass Reactors Market
Glass
Silica Sand for Glass Making Market
Glass
Global Self-Cleaning Glass Market
Glass
Glass Lined Equipment Market
Glass
Global Ultra-Thin Glass Market
Glass
Insulating Glass Market
Glass
Flexible Glass Market
Glass
Low-E Glass Market
Glass
Europe Sapphire Glass Market
Glass
3D Glass Market
Glass
Global Glassware Market
Glass
North America Architectural Flat Glass Market