
 North America Architectural Flat Glass Market | 2026-2036
North America Architectural Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
North America Architectural Flat Glass Market Analysis
Canada is fragmenting as a production hub for architectural flat glass serving cross-border commercial projects. AGC Inc. leverages its float glass technology leadership to supply major curtain wall programs across Toronto and Vancouver. Cardinal Glass Industries, Inc. anchors its position through captive fabrication networks concentrated in the Upper Midwest. Şişecam competes via specialized coated products targeting LEED-certified developments in Chicago and Montreal.
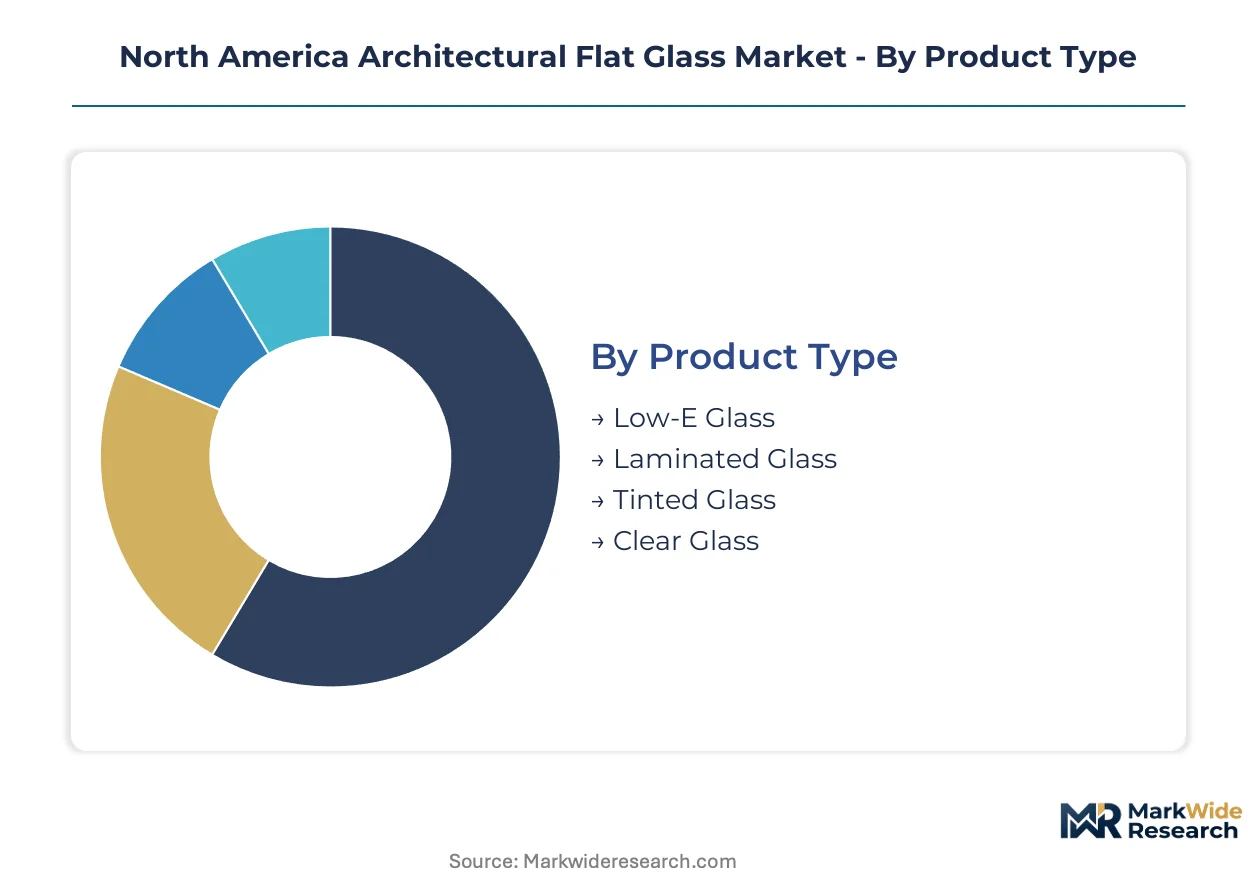
Architectural flat glass comprises soda-lime silica panels manufactured through float, rolled, or drawn processes, typically ranging from 2.5 mm to 25 mm in thickness, engineered for thermal control, safety, and daylighting in building envelopes. Low-E glass dominates specification volumes as energy code stringency tightens across North American jurisdictions. Laminated glass captures premium positioning in hurricane zones and acoustic-sensitive applications, while clear glass retains commodity status in cost-driven residential replacement cycles.
Fenestration standards under NFRC certification and ASHRAE 90.1 energy mandates shape product performance baselines across the United States, while Canada's National Energy Code for Buildings drives parallel efficiency requirements in provincial adoption. EPA ENERGY STAR labeling and state-level stretch codes in Massachusetts and Washington further segment demand by performance tier. Stakeholders must calibrate capacity investments against evolving code harmonization between federal and provincial authorities.
Market Dynamics
Energy code stringency across California, New York, and Massachusetts is forcing specification upgrades from commodity clear glass to high-performance Low-E and triple-glazed units, compressing lead times for certified fabricators and reshaping capacity allocation across the value chain.
Growth Catalysts
- ASHRAE 90.1 stringency:The 2022 standard mandates lower U-factors across climate zones 4-7, accelerating replacement cycles in commercial retrofits across the northern United States.
- Curtain wall specification:High-rise commercial construction in Toronto and Vancouver is pulling disproportionate volumes of laminated and coated glass for seismic and thermal performance.
- Massachusetts stretch code:Municipal opt-ins exceeding base IECC requirements create tiered demand for Net-Ready glazing in multifamily developments.
Market Restraints
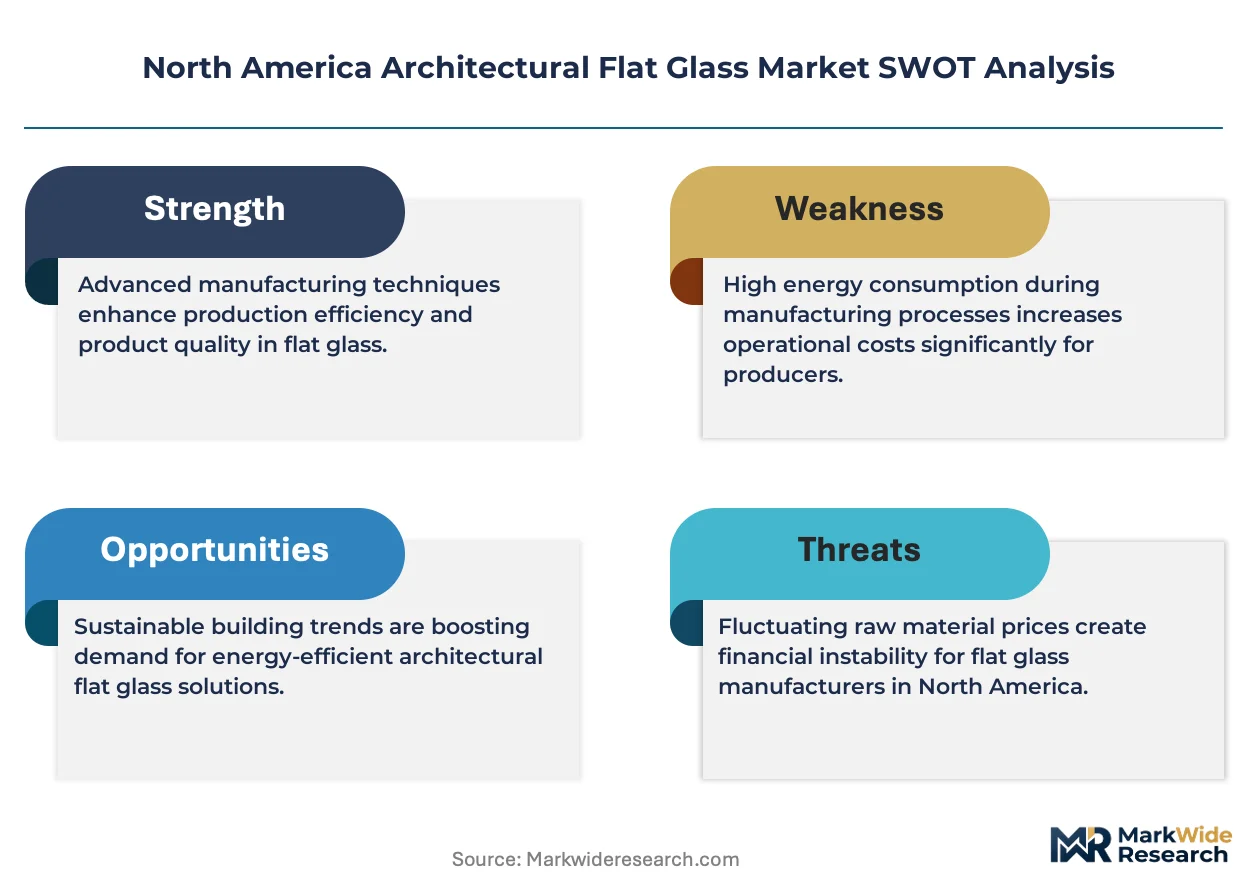
- Natural gas cost volatility:Float glass production depends on natural gas for melting furnaces; price spikes in Alberta and Texas directly compress operating margins.
- Float line concentration:North American primary glass production clusters along the Great Lakes and Gulf Coast, creating hurricane and logistics vulnerability for downstream fabricators.
- Silica sand quality degradation:High-purity deposits in Wisconsin and Ohio face permitting constraints, threatening batch consistency for optical-grade architectural products.
Strategic Opportunities
- Secondary glazing retrofits:Historic building preservation codes in Quebec and Boston create specialized demand for thin-profile Low-E retrofits that preserve facade aesthetics.
- IRA commercial credits:The Inflation Reduction Act's 179D deduction for energy-efficient building upgrades accelerates depreciation schedules for high-performance glazing investments.
- Smart glass convergence:Integration of electrochromic interlayers with conventional laminated safety glass opens premium positioning in corporate headquarters and healthcare facilities.
Industry Challenges
- IGU sealant technician shortage:Insulated glass unit fabrication requires skilled applicators for dual-seal warm-edge systems; training pipelines in the Midwest and Southeast remain underdeveloped.
- NFRC certification timelines:New product qualification for complex coating stacks extends 14-18 months, delaying market entry for innovative thermal performance configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Architectural Flat Glass Market |
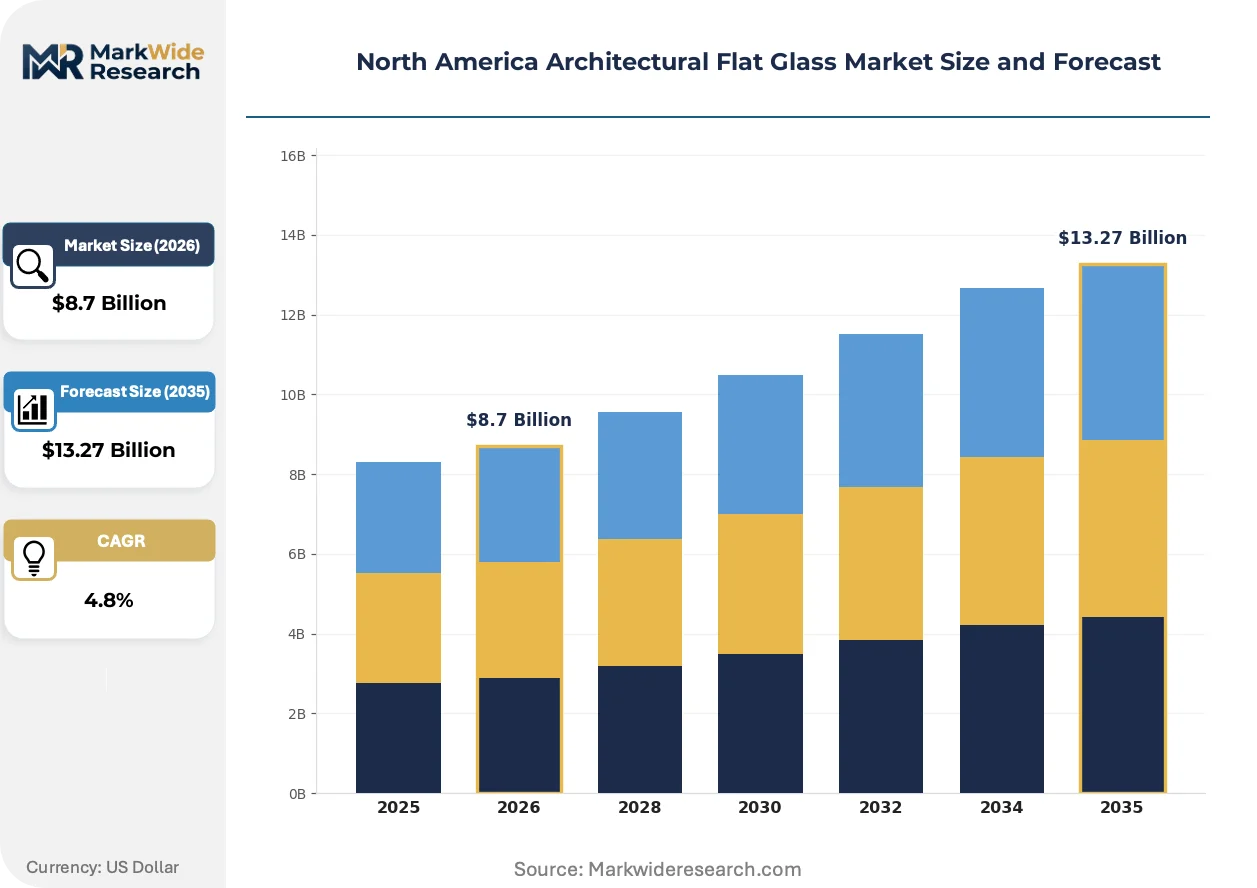
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-E Glass, Laminated Glass, Tinted Glass, Clear Glass Application: Commercial Buildings, Residential Buildings, Facades, Windows End User: Architects, Contractors, Developers, Homeowners Installation Type: New Construction, Retrofit, Renovation, Replacement |
| Companies Covered | Nippon Sheet Glass Co., Ltd., Şişecam, AGC Inc., SAGE Electrochromics, Cardinal Glass Industries, Inc., Saint-Gobain, Vitro Architectural Glass, Viracon, Guardian Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Architectural Flat Glass Market Emerging Trajectories
Digital specification tools and dynamic glazing technologies are compressing traditional procurement cycles while enabling real-time performance modeling that was previously impossible without physical mockups.
Electrochromic glazing is virtualizing the daylighting control function that static shading systems previously provided. Corporate headquarters developers in Seattle and San Francisco are specifying these systems at 40% premium over conventional Low-E. The technology is virtualizing the need for external louvers and interior blinds, collapsing two trade packages into one specification.
Washington state's Clean Buildings Performance Standard imposes energy use intensity caps on commercial structures over 50,000 square feet. Building owners must achieve 15% improvement by 2026 or face penalties. Large office portfolios in downtown Seattle and Bellevue are responding with aggressive glazing replacement programs targeting thermal bridging and solar heat gain coefficient reduction.
General contractors are consolidating glazing procurement under design-build envelopes rather than traditional bid-spec workflows. This compresses fabricator involvement to earlier project phases and shifts risk allocation toward performance guarantees. The pattern is most visible in Texas and Florida medical campus expansions where speed-to-occupancy drives consolidated subcontractor selection.
North America Architectural Flat Glass Market Segmentation
Architectural flat glass demand fragments across performance tiers, project types, and specification channels. Each dimension carries distinct margin profiles and code compliance requirements that reshape competitive positioning across the value chain.
Product Type:
Cost tier differentiation separates commodity offerings from premium coated and safety-rated alternatives.
- Low-E Glass:Microscopically thin metallic coatings reduce thermal transmittance while preserving visible light transmission. California Title 24 and New York Local Law 97 are forcing specification upgrades across commercial mid-rise and high-rise envelopes in Los Angeles and Manhattan.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for impact resistance and acoustic dampening. Hurricane codes in Florida and seismic requirements in Vancouver are pulling disproportionate volumes into curtain wall and skylight applications.
- Tinted Glass:Bulk colorants in the glass melt reduce solar heat gain coefficient for glare-sensitive facades.
- Clear Glass:Unmodified soda-lime silica retains commodity positioning in cost-driven residential replacement cycles across the US Sun Belt.
Low-E glass commands the established base. The steepest expansion runs through laminated safety products.
Application:
Project scale and code stringency concentrate volume in commercial envelopes while residential replacement provides steady baseline demand.
- Commercial Buildings:Office towers, retail centers, and hospitality structures specify high-performance glazing for ASHRAE 90.1 compliance. Toronto and Seattle high-rise construction is pulling triple-glazed and electrochromic configurations for thermal bridging control.
- Facades:Unitized curtain wall systems integrate glass, framing, and anchorage as prefabricated assemblies. Vancouver and Chicago developers are consolidating procurement under design-build contracts that compress fabricator involvement to early design phases.
- Residential Buildings:Single-family and multifamily construction drives volume for standard-performance units in Texas and Florida markets.
- Windows:Fenestration replacement cycles in the US Northeast and Midwest sustain demand for dual-pane and thin-triple retrofits.
Commercial envelopes anchor volume concentration. Facade-integrated systems are climbing the fastest as procurement consolidates.
End User:
Specification authority varies across the project delivery chain, with architects controlling early-phase performance targets and contractors managing final procurement.
- Architects:Design professionals set thermal and optical performance baselines through specification documents. LEED-certified developments in Boston and Montreal are prioritizing embodied carbon disclosure and regional material sourcing in glazing selections.
- Developers:Project sponsors balance first cost against operational energy savings and tenant retention metrics. Washington state's Clean Buildings Performance Standard is forcing large office portfolio owners in Seattle toward aggressive glazing replacement programs.
- Contractors:General and specialty trades execute procurement and installation with warranty obligations for thermal performance and air infiltration.
- Homeowners:End consumers in residential replacement markets respond to utility rebate programs and ENERGY STAR labeling for window upgrades.
Architects control upstream specification. Developers are gaining share fastest as owner-operators internalize lifecycle cost analysis.
Installation Type:
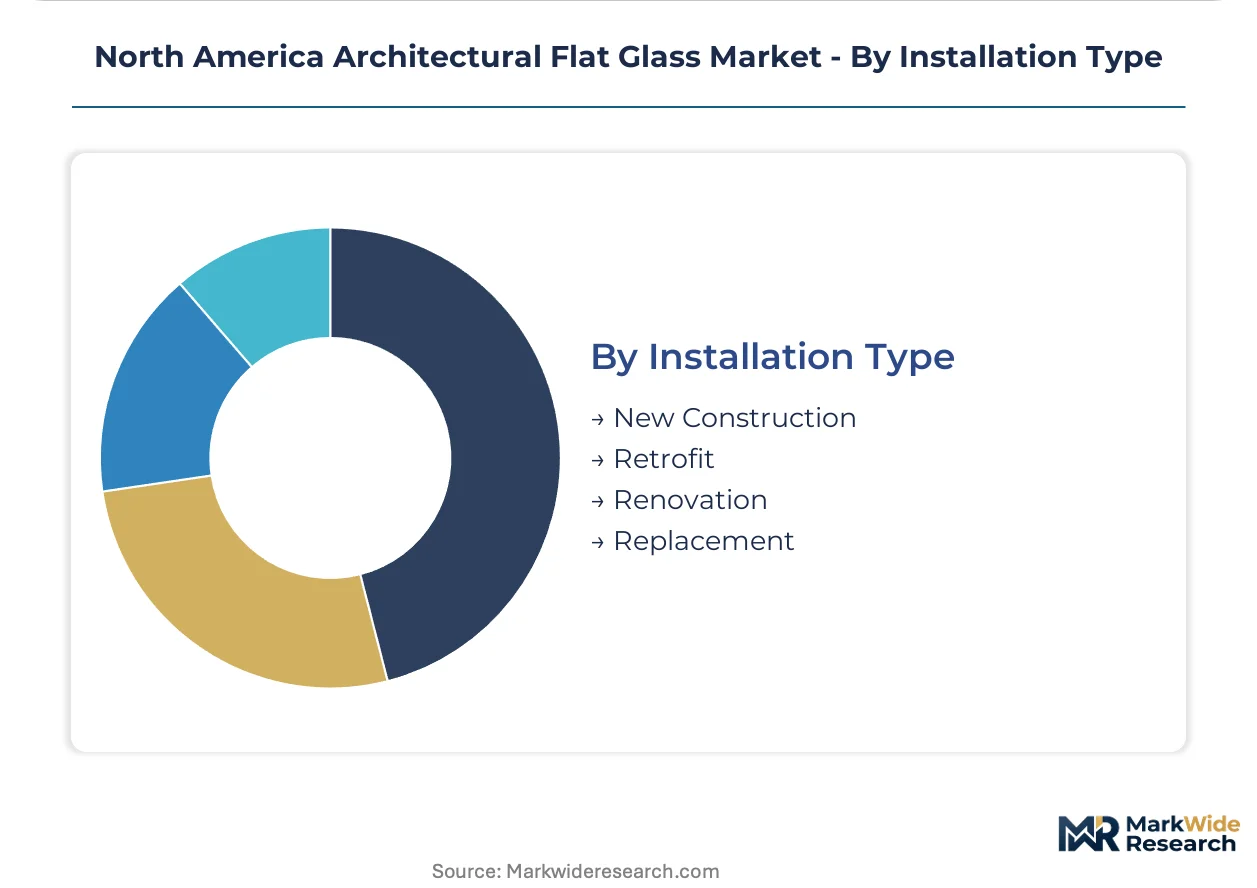
Project timing relative to building lifecycle determines access constraints, performance targets, and regulatory triggers.
- New Construction:Ground-up development enables integrated envelope design with optimized thermal bridging details. Texas and Florida medical campus expansions are consolidating glazing procurement under speed-to-occupancy schedules.
- Retrofit:Secondary glazing and thin-profile Low-E overlays address historic preservation codes in Quebec and Boston without facade alteration.
- Renovation:Major system replacement in occupied buildings requires phased installation and temporary enclosure management.
- Replacement:Like-for-like window swaps in residential and small commercial structures follow insurance claims or end-of-service-life triggers.
New construction commands the established base. Retrofit applications are expanding most quickly as energy codes tighten on existing stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA ENERGY STAR labeling and state-level stretch codes anchor demand calibration across the United States, while Canada's National Energy Code for Buildings drives parallel efficiency requirements in provincial adoption.
United States
California Title 24 and New York Local Law 97 force specification upgrades from commodity clear glass to high-performance Low-E and triple-glazed units. ASHRAE 90.1 mandates lower U-factors across climate zones 4-7, accelerating replacement cycles in commercial retrofits. Los Angeles and Manhattan high-rise construction pulls disproportionate volumes of laminated and coated glass for seismic and thermal performance.
Canada
Toronto and Vancouver high-rise commercial construction strengthens demand for curtain wall programs. The National Energy Code for Buildings drives efficiency requirements in provincial adoption, with Quebec and British Columbia leading implementation. Montreal and Calgary developers consolidate procurement under design-build contracts that compress fabricator involvement to early design phases.
Mexico
Industrial park development near the US border sustains demand for standard-performance glazing in manufacturing facilities. Mexican building codes gradually align with ASHRAE standards for cross-border commercial projects. Monterrey and Tijuana clusters serve maquiladora construction with regionally sourced fabricated units.
North America Architectural Flat Glass Market Vendor Landscape
Integrated primary producers and specialized fabricators split the market between captive float capacity and downstream customization. Three strategic archetypes dominate: multinational float glass operators with coating capabilities, regional fabrication specialists with captive distribution networks, and electrochromic technology developers targeting premium commercial segments. Competitive moves concentrate on capacity expansion in the Upper Midwest and strategic partnerships for smart glass integration.
Among multinational operators, AGC Inc., Şişecam, and Cardinal Glass Industries, Inc. exemplify distinct strategic positions. AGC Inc. leverages float technology leadership for cross-border commercial projects. Şişecam competes via specialized coated products targeting LEED-certified developments. Cardinal Glass Industries, Inc. anchors its position through captive fabrication networks concentrated in the Upper Midwest.
| Leading Market Players |
|---|
| Nippon Sheet Glass Co., Ltd. |
| Şişecam |
| AGC Inc. |
| SAGE Electrochromics |
| Cardinal Glass Industries, Inc. |
| Saint-Gobain |
| Vitro Architectural Glass |
| Viracon |
| Guardian Industries |
| Others |
Supply Flow & Price Mechanics
The Great Lakes rail corridor's freight cost volatility compresses margins for Midwest fabricators while amplifying price spreads between Gulf Coast float capacity and Northeast premium glazing markets, concentrating pricing power among integrated producers with captive logistics.
Pricing Analysis
Geographic price spreads between Texas float glass and Boston finished units exceed 35% on delivered cost basis. Pricing stratifies across performance-certified, standard-compliant, and commodity tiers, with NFRC certification and Low-E coating stack complexity as primary differentiation drivers. Pricing pressure stems from natural gas cost volatility in Alberta and Texas furnace operations. Residential replacement buyers in the Sun Belt exhibit highest price sensitivity, while Seattle and Manhattan commercial developers prioritize thermal performance over unit cost.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates cross-border project cost uncertainty for Toronto and Vancouver curtain wall programs. Primary float capacity concentrates in the United States, Canada, and Mexico, with silica sand drawn from Wisconsin and Ohio deposits. The supply chain rests on high-purity soda ash, natural gas, and specialized coating chemicals as critical inputs. Single-source vulnerability runs through Great Lakes hurricane exposure and permitting constraints on optical-grade sand. Distribution runs through captive fabrication networks and regional glazing contractors with performance warranty obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory moat story. ASHRAE 90.1 and state stretch code entrenchment create switching costs that lock developers into certified fabricator relationships across multi-year project pipelines.
For Market Incumbents: Harden defensive positioning through captive coating capacity additions in the Upper Midwest and accelerated NFRC pre-certification of next-generation thermal stacks. Electrochromic technology developers and vertically integrated Chinese entrants represent the primary competitive threats. Backward integration into silica sand processing secures batch consistency for optical-grade products.
For New Entrants and Emerging Players: Secondary glazing retrofits in Boston and Quebec historic districts represent the most penetrable entry point, with thin-profile Low-E overlays bypassing primary float capital requirements. Smart glass integration partnerships with Seattle and San Francisco corporate headquarters developers offer a technology-leapfrog go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional fabrication specialists with established NFRC certification pipelines and design-build contractor relationships. Long-term viability hinges on energy code harmonization momentum across the analysis window. The signal to watch is Massachusetts and Washington stretch code adoption velocity as a proxy for premium glazing demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Capacity Expansion | Captures ASHRAE 90.1 specification upgrades across climate zones 4-7. |
| Electrochromic Technology Licensing | Opens premium positioning in Seattle and San Francisco corporate headquarters. |
| NFRC Pre-Certification Investment | Compresses 14-18 month qualification timelines for innovative thermal configurations. |
| Design-Build Partnership Consolidation | Locks fabricator involvement into early-phase Texas and Florida medical campus projects. |
| Silica Sand Backward Integration | Secures batch consistency against Wisconsin and Ohio permitting constraints. |
Methodological Framework
Desk research of customs trade filings, EPA ENERGY STAR certification databases, and ASHRAE standard documentation preceded structured interviews with curtain wall specification engineers, IGU fabrication plant managers, glazing contractor procurement leads, and commercial developer project directors. Primary fieldwork combined telephone and in-person interviews across Toronto, Chicago, and Seattle markets with secondary validation against NFRC product directory data and provincial energy code adoption records. Bottom-up volume estimates from fabricator capacity utilization triangulated against top-down construction spend forecasts.
Assumptions held fixed include ASHRAE 90.1 stringency trajectory and state-level stretch code adoption schedules, while natural gas pricing and silica sand permitting timelines varied across sensitivity scenarios. The analytical framework modeled segmentation across product performance tier, installation type, and end-user specification authority, with regional climate zone overlays capturing thermal performance requirement variation. CAGRs derived from regression analysis against commercial construction permit data and replacement cycle triggers. Industry-specific inputs included curtain wall square footage per high-rise project and Low-E coating penetration rates by jurisdiction.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate investment, mortgage rate environments, or federal infrastructure appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding code harmonization momentum and furnace fuel cost normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
United States Flat Glass Market
Glass
Advanced Glass Market
Glass
Solar Reflective Glass Market
Glass
Tempered Glass Market
Glass
East Africa Flat Glass Market
Glass
Antibacterial Glass Market
Glass
Glass Forming Machine Market
Glass
Float Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Global Energy Efficient Glass Market
Glass
India Flat Glass Market
Glass
Tinted Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Global Glassware Market
Glass
Asia Pacific Flexible Glass Market
Glass
Glass Vials Market