
 India Metal Treatment Chemical Market | 2026-2036
India Metal Treatment Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
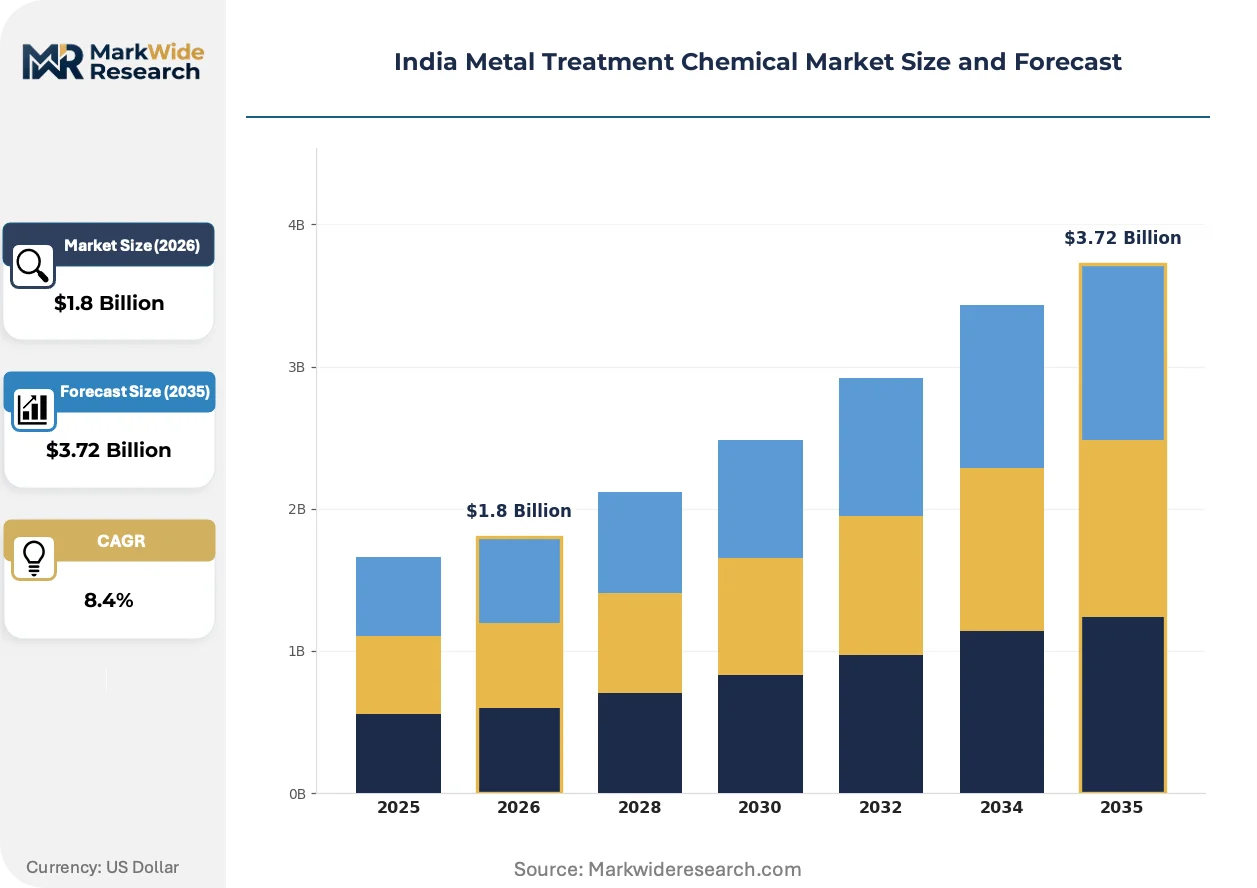
India Metal Treatment Chemical Market Outlook
Galvanized coatings is consolidating share against conventional phosphate treatments in India's metal finishing sector as cost and environmental pressures mount. Henkel Adhesives Technologies leverages its global formulation expertise to anchor premium positions in automotive pretreatment lines. BASF India competes through backward integration into raw material supply, sustaining margin control across rust inhibitor portfolios. Chemtex Speciality dominates regional distribution networks in western India, extending channel reach into mid-tier fabricators.
India metal treatment chemicals encompass formulated solutions including passivation agents, rust inhibitors, cleaners, and degreasers designed to modify surface properties of ferrous and non-ferrous substrates through chemical conversion, coating deposition, or contaminant removal. These formulations typically operate within specified pH ranges and concentration parameters to ensure adhesion promotion, corrosion resistance, or cleanliness standards required for subsequent manufacturing stages. Application segmentation shows automotive manufacturing occupying the largest volume position due to paint-shop pretreatment intensity, while aerospace commands premium pricing through stringent NADCAP-aligned qualification requirements. End-user segmentation reveals OEMs and Tier-1 suppliers capturing the dominant value pool, with maintenance providers representing a faster-growing but fragmented demand layer as aftermarket service intervals compress.
BIS standards govern product quality benchmarks for industrial chemical formulations sold in India, while the PLI scheme for specialty chemicals shapes investment location decisions among domestic producers. CEA electrical equipment directives and state-level pollution control mandates further constrain effluent profiles from metal treatment operations, pushing reformulation toward lower-zinc and trivalent chromium chemistries. Stakeholders must monitor evolving BIS notification schedules and state PCB enforcement intensity to anticipate compliance-driven product substitution cycles.
Market Dynamics
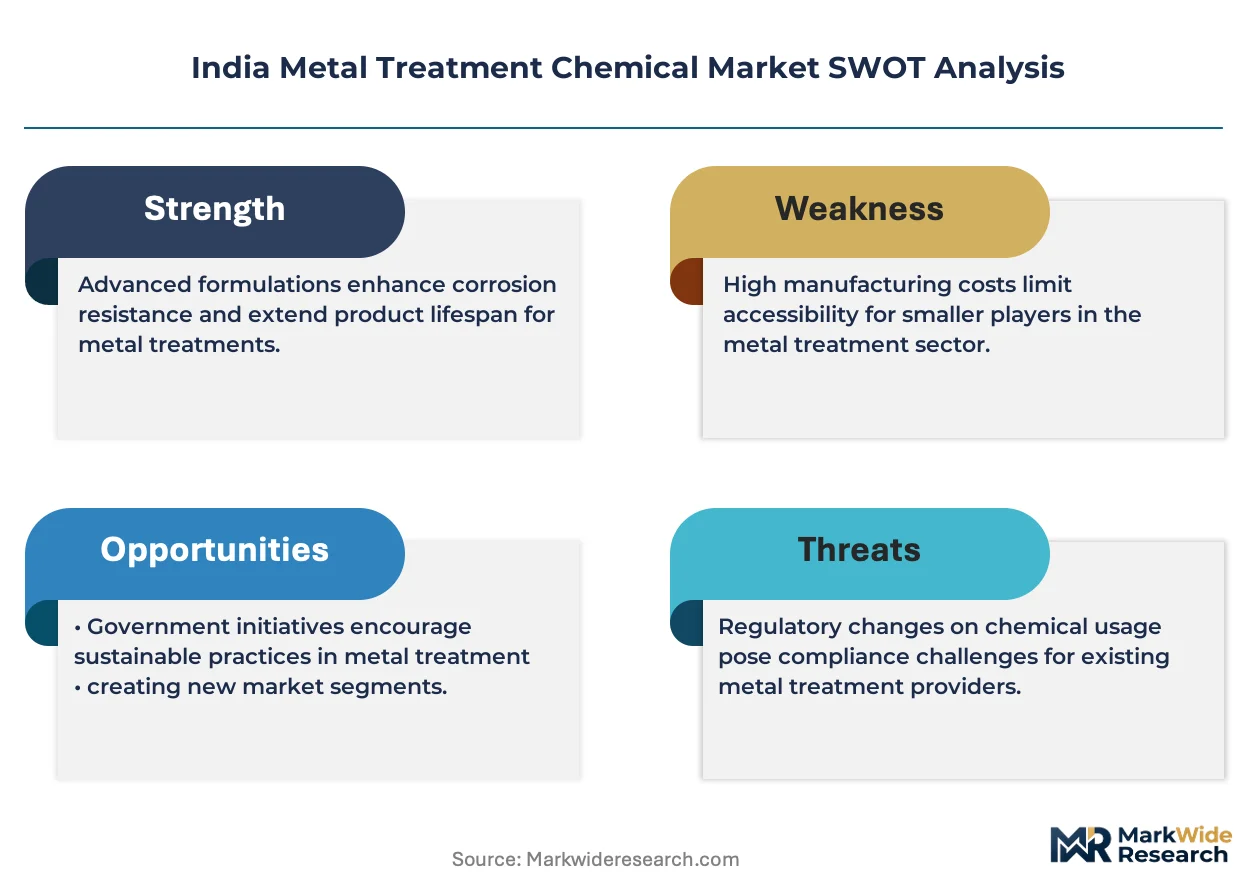
India's metal treatment chemical sector is reconfiguring around the tension between BIS-mandated quality escalation and the cost pressures facing mid-tier fabricators in Maharashtra and Gujarat clusters.
Growth Catalysts
- PLI scheme for specialty chemicals:Production-linked incentives are drawing domestic capacity expansion into rust inhibitor and passivation agent manufacturing, reducing import dependence for automotive OEMs.
- Automotive paint-shop intensity:Rising vehicle output from Chennai and Pune assembly plants is scaling pretreatment chemical consumption per unit.
- CEA electrical equipment directives:Stricter corrosion protection standards for transformers and switchgear are mandating upgraded metal treatment protocols across power infrastructure procurement.
Market Restraints
- Zinc price volatility:Galvanizing and phosphate coating formulations face margin compression from London Metal Exchange zinc fluctuations, squeezing smaller compounders.
- Chromium chemistry substitution costs:State pollution control board mandates on hexavalent chromium are forcing costly reformulation of conversion coatings without immediate price recovery mechanisms.
- Import dependence for specialty additives:Western India distributors rely on Chinese and German suppliers for corrosion inhibitor intermediates, exposing lead times to shipping lane disruptions.
Strategic Opportunities
- Tamil Nadu aerospace cluster:NADCAP-aligned qualification requirements for defense and aviation MRO facilities represent premium pricing potential for qualified passivation chemistry suppliers.
- Trivalent chromium conversion coatings:Environmental compliance tailwinds from BIS notification schedules are creating first-mover advantage for domestic formulators with approved trivalent systems.
- Direct-to-fabricator digital platforms:Mid-tier metalworkers in Rajkot and Coimbatore are bypassing traditional distributor markups through B2B chemical procurement portals.
Industry Challenges
- NADCAP auditor scarcity:Aerospace chemical qualification timelines stretch 18-24 months due to limited accredited certification bodies operating in India.
- Effluent treatment capex burdens:Zero liquid discharge mandates from Gujarat and Maharashtra state PCBs require six-figure rupee investments in wastewater recovery systems for small-scale applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Metal Treatment Chemical Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passivation Agents, Rust Inhibitors, Cleaners, Degreasers Application: Aerospace, Automotive Manufacturing, Construction, Industrial Machinery End User: OEMs, Tier-1 Suppliers, Maintenance Providers, Fabricators Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | BASF India, Henkel Adhesives Technologies, Metalguard Pvt, Chemtex Speciality, CMP, Dimetrics, Chemetall GmbH, Quaker Chemical Corporation, Houghton International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Metal Treatment Chemical Market Strategic Shifts
Formulation chemistry and compliance architecture are diverging sharply as environmental mandates outpace legacy process capabilities, forcing simultaneous investment in new chemistries and treatment infrastructure.
Silane-based thin-film pretreatments are overtaking iron phosphate and zinc phosphate conversion coatings in automotive body-in-white operations. Maruti Suzuki and Tata Motors paint shops have accelerated silane adoption to reduce sludge generation and energy consumption in pretreatment tunnels. This chemistry is overtaking conventional phosphate lines because it eliminates the need for heated process tanks and reduces wastewater treatment loads by approximately half.
BIS notification schedules for industrial chemicals are tightening heavy metal content thresholds in metal treatment formulations sold domestically. The Bureau of Indian Standards has advanced draft standards limiting hexavalent chromium in conversion coatings, forcing reformulation cycles among domestic compounders. Automotive OEMs in Pune and Gurugram are responding by qualifying trivalent chromium and zirconium-based alternatives ahead of mandatory compliance dates.
Maintenance chemical procurement is consolidating around annual service contracts bundling chemical supply, bath analysis, and waste handling. Fleet operators and heavy machinery dealers in mining and construction verticals are displacing spot purchases of rust inhibitors and degreasers with integrated surface treatment programs. This pattern is most visible in Rajasthan and Odisha mining belts where equipment uptime penalties have compressed service intervals.
India Metal Treatment Chemical Market Segmentation
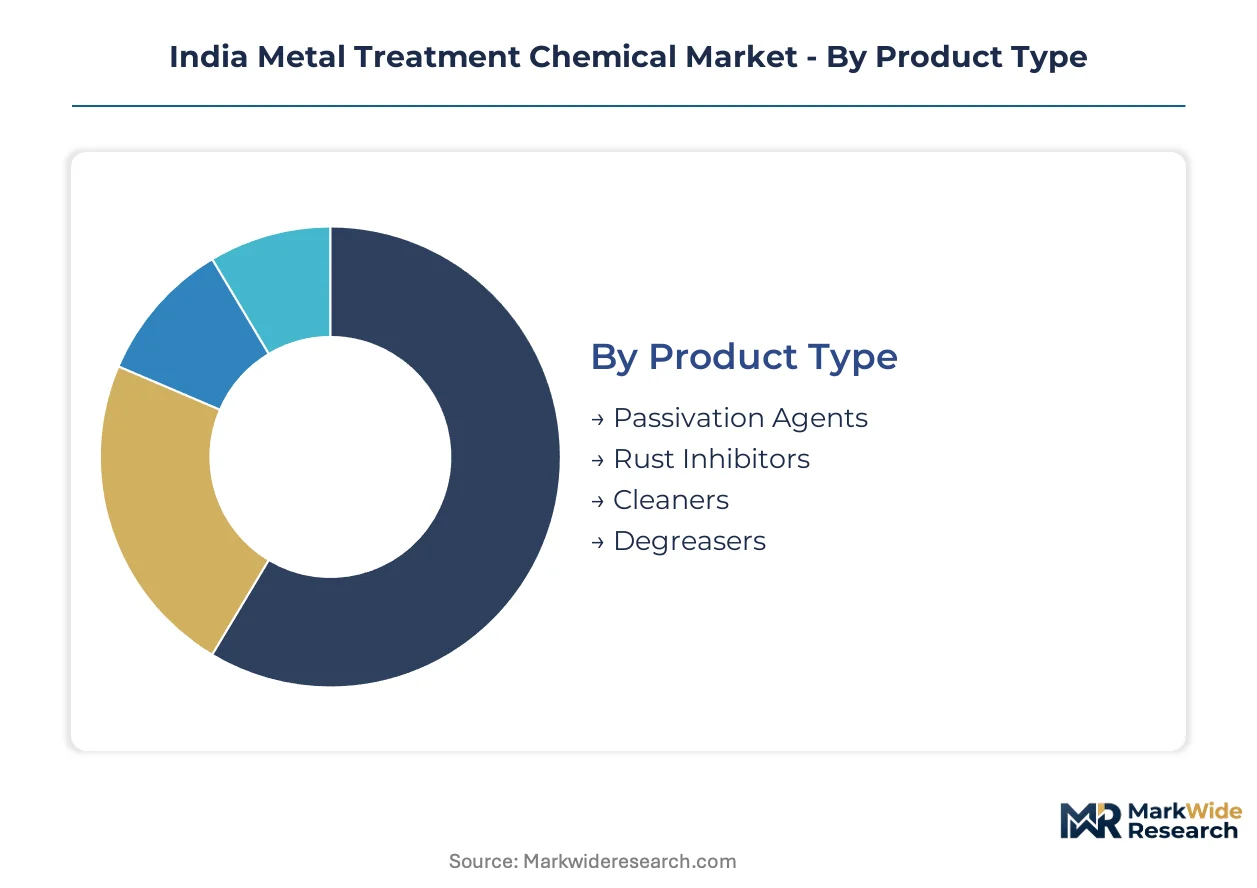
Metal treatment chemicals serve divergent technical requirements across India's industrial base, from precision aerospace finishing to high-volume automotive pretreatment. Segmentation reveals how formulation complexity, regulatory intensity, and procurement scale reshape competitive positioning for domestic compounders and distributors.
Product Type:
Standalone surface modification chemistries operate independently of coating systems, while embedded pretreatment formulations integrate directly into multi-stage finishing lines.
- Passivation Agents:Chromium-based and zirconium conversion coatings create protective oxide layers on aluminum and zinc substrates. Demand concentrates in Pune automotive clusters where OEMs qualify trivalent systems ahead of BIS hexavalent restrictions.
- Rust Inhibitors:Film-forming compounds containing organic amines or petroleum sulfonates deposit moisture barriers on ferrous metals. Maharashtra fabricators in Nashik and Aurangabad drive procurement for in-process protection of steel components.
- Cleaners:Alkaline and acidic formulations remove oils and oxides prior to coating application.
- Degreasers:Solvent-based and aqueous systems eliminate machining fluids from metal surfaces.
Passivation agents lead volumes today; rust inhibitors are gaining share fastest.
Application:
Process intensity varies sharply—automotive operations consume chemicals continuously in conveyorized systems, while construction applications deploy treatments sporadically at fabrication yards.
- Automotive Manufacturing:Body-in-white pretreatment lines consume iron phosphate, zinc phosphate, and silane thin-film chemistries in heated immersion stages. Chennai and Pune assembly plants scale consumption per vehicle as paint-shop specifications tighten.
- Aerospace:NADCAP-qualified passivation and anodizing chemistries serve defense MRO facilities and aviation component suppliers. Tamil Nadu's Hosur and Bangalore aerospace clusters command premium pricing for chemistry qualification documentation.
- Construction:Structural steel galvanizing and coating preparation at fabrication yards.
- Industrial Machinery:Equipment manufacturing and rebuild operations requiring corrosion protection.
Automotive manufacturing dominates absolute consumption; aerospace delivers the steepest margin expansion trajectory.
End User:
Procurement sophistication separates large-scale integrated manufacturers from fragmented maintenance operations.
- OEMs:Maruti Suzuki, Tata Motors, and Mahindra operate captive pretreatment facilities with direct chemical supply agreements. These buyers specify formulation performance and audit supplier quality systems against BIS standards.
- Tier-1 Suppliers:Component manufacturers such as Motherson and Bharat Forge purchase pretreatment chemicals for surface preparation before coating operations. Their procurement consolidates around annual contracts bundling chemical supply and bath analysis services.
- Maintenance Providers:Mining fleet operators and construction equipment dealers procure rust inhibitors and degreasers for field service intervals.
- Fabricators:Small and mid-tier metalworkers in Rajkot and Coimbatore source chemicals through distributor networks or emerging B2B platforms.
OEMs anchor the value pool today; maintenance providers are expanding most quickly as service intervals compress.
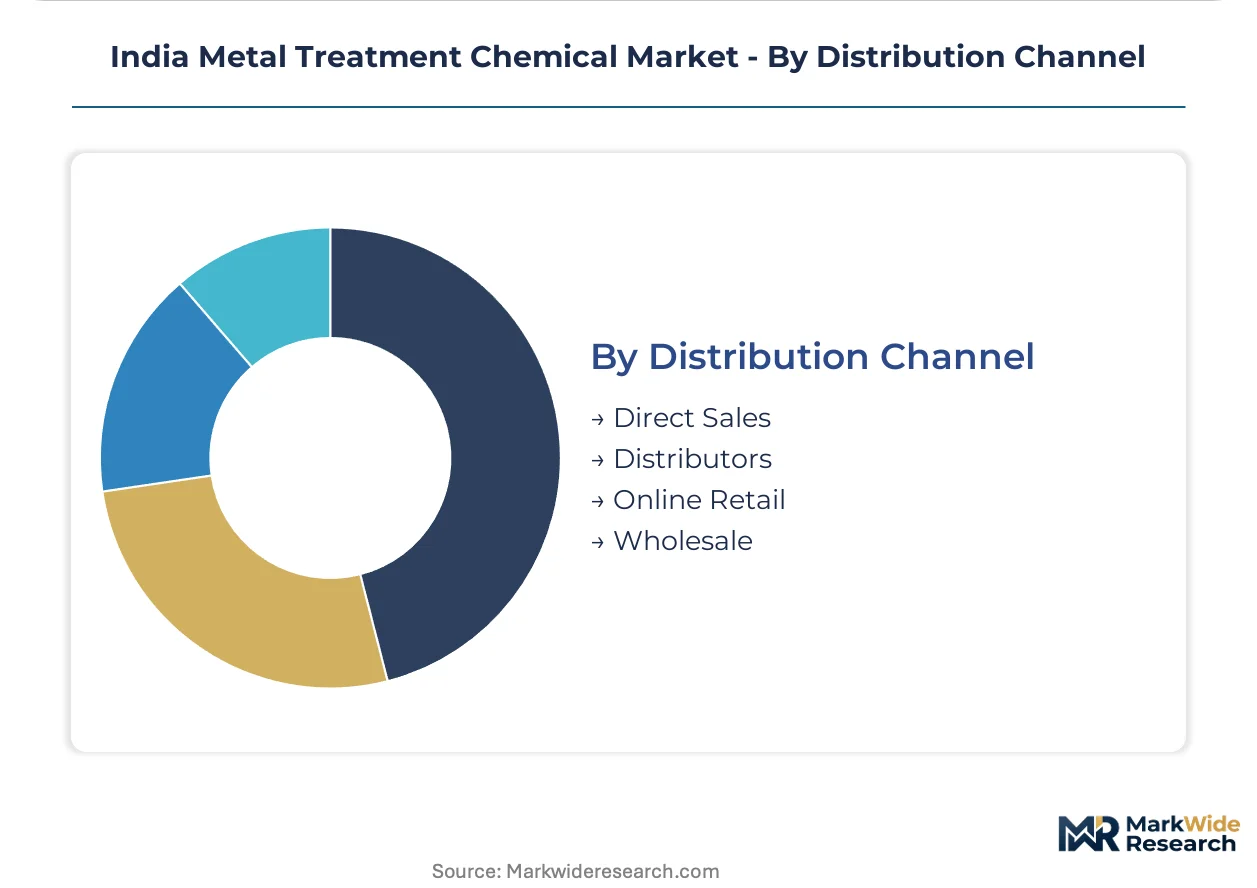
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic concentration of demand.
- Distributors:Regional chemical distributors such as Chemtex Speciality maintain inventory positions in Gujarat and Maharashtra to serve mid-tier fabricators with short lead times. These intermediaries provide formulation guidance and logistics coordination.
- Direct Sales:Large compounders including Henkel and BASF India deploy technical sales teams to automotive OEMs and Tier-1 suppliers. Direct relationships enable custom formulation development and just-in-time delivery to pretreatment lines.
- Online Retail:Emerging B2B procurement platforms target small fabricators seeking price transparency.
- Wholesale:Bulk supply arrangements for large-volume consumers with storage infrastructure.
Distributors capture the broadest reach today; direct sales channels are climbing the fastest as OEM consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat industrial corridors concentrate India's metal treatment chemical procurement, with automotive OEMs and precision fabricators driving formulation demand across western India.
Maharashtra
Pune and Nashik automotive clusters consume phosphate pretreatment chemistries at scale as Maruti Suzuki and Tata Motors expand paint-shop capacity. BIS certification requirements for industrial chemicals govern supplier qualification protocols across OEM procurement. Tier-1 suppliers in Chakan and Ranjangaon industrial belts are consolidating annual chemical service contracts bundling passivation agents and bath analysis.
Gujarat
State pollution control board mandates on effluent discharge are forcing zero liquid discharge investments at metal finishing facilities in Ahmedabad and Vadodara. The PLI scheme for specialty chemicals incentivizes domestic rust inhibitor manufacturing capacity near Mundra port logistics. Rajkot fabrication hubs are migrating toward B2B procurement platforms for degreaser and cleaner purchases.
Tamil Nadu
Hosur and Chennai aerospace MRO facilities command NADCAP-aligned passivation chemistry documentation for defense component suppliers. CEA electrical equipment directives mandate upgraded corrosion protection for transformer manufacturers in Sriperumbudur. Automotive assembly plants in Oragadam are qualifying silane-based thin-film pretreatments to reduce wastewater treatment loads.
Karnataka
Bangalore precision engineering clusters source zirconium conversion coatings for aluminum component finishing ahead of hexavalent chromium restrictions. The state's electronics manufacturing policy attracts metal treatment chemical distributors serving PCB fabrication facilities. Mysuru and Tumkur industrial areas are witnessing maintenance chemical procurement consolidation around integrated service programs.
Haryana
Gurugram automotive supplier parks require trivalent chromium systems as BIS notification schedules advance draft standards limiting hexavalent content. Manesar component manufacturers are backward integrating into captive pretreatment lines to secure supply continuity. Faridabad metal fabrication units face margin pressure from zinc price volatility affecting galvanizing operations.
India Metal Treatment Chemical Market Competitive Environment
Global majors compete with regional champions across formulation expertise and distribution reach in India's metal treatment chemical sector. The vendor base stratifies into three tiers: multinational compounders with captive R&D, domestic manufacturers with backward integration into raw materials, and regional distributors with channel density in western India. Two dominant competitive moves define current positioning: technical sales teams embedding at automotive OEM pretreatment lines, and digital platforms disintermediating traditional distributor markups for mid-tier fabricators.
Among Germany-based chemical conglomerates, BASF India and Henkel Adhesives Technologies exemplify the multinational archetype through direct supply relationships with integrated automotive manufacturers. Chemtex Speciality occupies a position within the regional distribution tier, anchoring channel presence across Gujarat and Maharashtra industrial belts. These three entities represent distinct strategic postures—global formulation depth, technical service integration, and geographic density—without implying specific market share claims or operational details beyond their observable industrial positioning.
| Leading Market Players |
|---|
| BASF India |
| Henkel Adhesives Technologies |
| Metalguard Pvt |
| Chemtex Speciality |
| CMP |
| Dimetrics |
| Chemetall GmbH |
| Quaker Chemical Corporation |
| Houghton International Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between NADCAP-aligned aerospace chemistry and commodity-grade fabricator supply splits pricing power and sourcing geography simultaneously. Premium formulations command technical service bundling and direct OEM relationships, while standard grades flow through distributor networks serving price-sensitive mid-tier metalworkers in western India.
Pricing Analysis
Input-cost pass-through from London Metal Exchange zinc volatility squeezes margin buffers for galvanizing and phosphate coating compounders. Three-tier pricing structure across premium, standard, and economy levels separates NADCAP-qualified aerospace chemistry from automotive pretreatment formulations and commodity rust inhibitors. Cost compression in standard-grade segments is intensifying because mid-tier fabricators in Rajkot and Coimbatore migrate toward B2B procurement portals. Maintenance providers and small fabricators exhibit highest price sensitivity; aerospace OEMs and Tier-1 automotive suppliers demonstrate lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for specialty chemicals are redirecting rust inhibitor and passivation agent sourcing toward Maharashtra and Gujarat manufacturing zones. Geographic supply concentration centers on Germany and China for corrosion inhibitor intermediates, with India expanding captive production of trivalent chromium conversion coatings. Raw material dependencies rest on zinc metal, organic amine compounds, and petroleum sulfonate feedstocks. Single-source vulnerability from Chinese additive suppliers exposes western India distributors to shipping lane disruptions. Distribution runs through regional chemical distributors with inventory positions in Ahmedabad and Pune, supplemented by direct technical sales teams at automotive OEM pretreatment lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's metal treatment chemical sector functions as a regulatory compounder where BIS notification schedules on hexavalent chromium content are forcing reformulation investment cycles and supplier requalification across automotive and aerospace value chains.
For Market Incumbents: Anchor market position through backward integration into trivalent chromium raw material supply and NADCAP certification infrastructure investment. Silane-based thin-film chemistry from Henkel and BASF India threatens phosphate coating incumbents with sludge reduction advantages. Capacity addition in Tamil Nadu aerospace corridors and captive pretreatment line partnerships with Maruti Suzuki and Tata Motors defend margin buffers against commodity-grade price erosion. For New Entrants and Emerging Players: Digital-first formulation platforms offer a technology-first wedge into Rajkot and Coimbatore fabricator procurement through price-transparent B2B marketplaces. Tamil Nadu aerospace MRO facilities represent the most penetrable white-space target given 18-24 month NADCAP qualification timelines limiting incumbent responsiveness. Direct-to-fabricator digital platforms with bundled bath analysis and waste handling services provide the strongest go-to-market angle against traditional distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where state pollution control board mandates on zero liquid discharge force six-figure rupee effluent treatment investments that fragment small-scale applicator viability. Long-term viability favors domestic compounders with approved trivalent chromium systems and backward integration into specialty additive manufacturing. Acquisition target archetype: regional distributors with Gujarat and Maharashtra channel density and emerging BIS certification capabilities. Watch BIS notification implementation dates as inflection indicators for forced substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trivalent Chromium Feedstocks | Captive supply of BIS-compliant conversion coating raw materials secures margin control against import volatility. |
| NADCAP Qualification Infrastructure Investment | Accredited chemistry documentation unlocks premium pricing from Tamil Nadu aerospace MRO facilities. |
| Direct-to-Fabricator Digital Platform Launch | B2B procurement portals disintermediate traditional distributor markups in Rajkot and Coimbatore metalworking clusters. |
| Silane Thin-Film Chemistry Scale-Up | Energy-efficient pretreatment formulations reduce wastewater loads for Maruti Suzuki and Tata Motors paint-shop operations. |
| Annual Service Contract Bundling | Integrated chemical supply and bath analysis programs capture maintenance provider demand in Rajasthan mining belts. |
Study Parameters
Bottom-up automotive and aerospace pretreatment modeling reconciled against top-down specialty chemical production tracking forms the analytical core. Primary interviews with plant managers at Maharashtra and Gujarat metal finishing facilities, procurement leads at Tier-1 automotive suppliers, technical R&D directors at domestic compounders, and distribution channel partners in western India informed demand segmentation. Secondary validation drew from BIS notification schedules, state pollution control board mandates, customs and trade data on corrosion inhibitor imports, and SEC filings of multinational chemical conglomerates. Triangulation against automotive production databases and aerospace MRO facility expansion records anchored volume estimates.
Historical trendline analysis of pretreatment chemical intensity per vehicle and per square meter of fabricated metal established baseline consumption patterns. Segmentation dimensions modeled include formulation chemistry type, end-use industry vertical, certification grade tier, and regional production hub clustering. CAGRs were derived from regression analysis of automotive assembly plant capacity additions and BIS-driven substitution cycles. Industry-specific forecast inputs incorporated PLI scheme disbursement timelines and NADCAP auditor availability constraints.
The model holds under steady BIS implementation schedules and stable zinc price corridors; deviation in notification acceleration or raw material cost spikes would shift substitution timelines and margin trajectories. Forecasts reflect documented assumptions on automotive paint-shop specification evolution and aerospace defense procurement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Phenylethyl Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Inorganic Chemicals Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Diphosphate Market
Chemicals
Global Construction Chemical Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Oxybenzone Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
United Kingdom Methanol Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Penoxsulam Market