
 Glass Reactors Market | 2026-2036
Glass Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Reactors Market Foresight
Asset-light leasing models for pharmaceutical-grade glass reactor systems is narrowing the competitive field to firms with balance-sheet depth. GMM Pfaudler Ltd. leverages its integrated borosilicate glass manufacturing to control input quality from melt to finished vessel. De Dietrich Process Systems anchors European demand through enamel-coated and glass-lined hybrid designs for corrosive chemistries. Corning Incorporated competes via advanced flow reactor technology that extends traditional batch glass reactor capabilities into continuous processing.
Glass reactors are cylindrical vessels constructed from borosilicate glass 3.3, typically rated for temperatures between -80°C and +200°C and pressures up to 6 bar, designed for observation, mixing, and controlled reaction of chemical, pharmaceutical, and biological processes. Jacketed configurations dominate installed base value due to their thermal control precision in exothermic synthesis, while continuous flow technology represents the fastest-expanding segment as manufacturers replace batch bottlenecks with modular scale-up architectures. Pharmaceutical manufacturers constitute the deepest margin pool, particularly for triple-layer and automated systems that validate under FDA 21 CFR Part 11 protocols.
FDA cGMP guidelines and EMA's Annex 15 qualification requirements shape validation protocols for biopharmaceutical glass reactor deployments, while India's CDSCO manufacturing license rules tighten material certification for imported systems. China's NMPA Good Manufacturing Practice revisions for chemical APIs are accelerating domestic replacement of legacy stainless steel with glass-lined and all-glass reactor trains. Stakeholders must monitor evolving ESG disclosure rules under the EU CSRD, which will soon require lifecycle carbon documentation for process equipment procurement decisions.
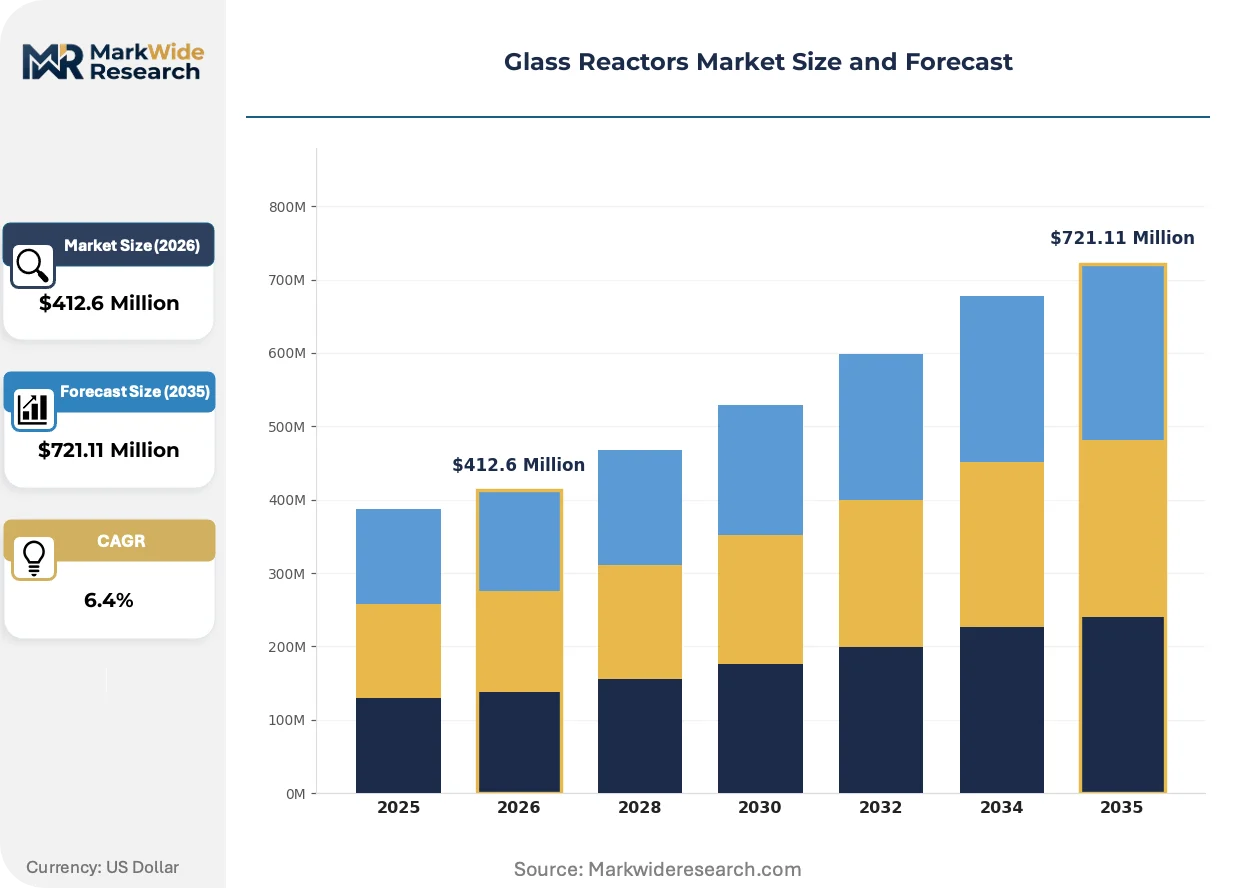
Market Dynamics
Continuous flow chemistry adoption is compressing batch reactor economics across pharmaceutical and fine chemical manufacturing, forcing incumbent glass reactor suppliers to rearchitect modular product lines around plug-and-play scale-up architectures.
Growth Catalysts
- India's PLI scheme for pharmaceutical intermediates:Domestic chemical manufacturers are expanding pilot-scale borosilicate glass reactor installations to capture incentive-linked production quotas for API precursors.
- FDA 21 CFR Part 11 validation protocols:Biopharmaceutical manufacturers require triple-layer automated glass reactor systems with electronic batch records, deepening specification floors for new equipment purchases.
- Exothermic synthesis thermal precision:Jacketed glass reactor configurations dominate high-value installations where temperature control within ±0.5°C prevents runaway reactions in specialty chemical production.
Market Restraints
- Borosilicate glass 3.3 supply concentration:German and Czech specialty glass manufacturers control premium-grade melt capacity, exposing buyers to 12-16 week lead times during furnace maintenance cycles.
- Stainless steel substitution in commodity APIs:China's NMPA GMP revisions accelerate domestic replacement of glass-lined trains with 316L stainless steel for non-corrosive intermediate steps.
- ECHA REACH traceability certification costs:European buyers face 8-15% procurement premiums for borosilicate reactors with certified batch documentation from melt to finished vessel.
Strategic Opportunities
- Asset-light leasing models:Balance-sheet-heavy firms can capture pharmaceutical-grade glass reactor demand from CMOs and early-stage biotechs avoiding capital deployment.
- EU CSRD lifecycle carbon documentation:Equipment suppliers with verified Scope 3 emissions data gain preferential positioning in European process equipment procurement decisions.
- Corrosive chemistry hybrid designs:Enamel-coated glass-lined reactor technology converges with all-glass observation capabilities for fluorination and chlorination processes.
Industry Challenges
- Continuous flow reactor engineering talent scarcity:Modular scale-up architecture design requires rare cross-training in chemical engineering and precision glassblowing fabrication.
- FDA cGMP qualification timeline compression:Installation qualification and operational qualification protocols for biopharmaceutical deployments extend project durations by 4-7 months.
- Legacy batch-to-continuous integration complexity:Pharmaceutical manufacturers face control system revalidation burdens when retrofitting existing facilities with flow chemistry modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Reactors Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Double Layer, Triple Layer, Jacketed Technology: Batch, Continuous, Semi-Batch, Automated Application: Chemical Synthesis, Biopharmaceuticals, Food Processing, Polymerization End User: Pharmaceutical Manufacturers, Research Laboratories, Specialty Chemicals, Academic Institutions |
| Companies Covered | GMM Pfaudler Ltd., De Dietrich Process Systems, Corning Incorporated, Büchi AG, Parr Instrument Company, Ace Glass Incorporated, Syrris Ltd., Radleys, IKA Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Reactors Market Shifts & Advancements
Modular reactor architecture is displacing fixed-installation designs across contract manufacturing, while regulatory documentation requirements and thermal management precision reshape competitive differentiation.
Hybrid glass-enamel reactor technology is hybridizing observation windows with acid-resistant linings for halogenation processes. Specialty chemical manufacturers in Germany and Switzerland adopt these configurations at pilot-to-demo scale. The technology is hybridizing traditional batch vessel economics with continuous processing throughput claims.
EMA's Annex 15 qualification requirements now mandate documented material traceability for all product-contact surfaces in biopharmaceutical manufacturing. European CMOs face audit failures where glass reactor certification gaps exist. Multi-port jacketed systems with certified borosilicate 3.3 documentation command procurement preference in EU GMP inspections.
Contract research organizations in Maharashtra's Mumbai-Pune corridor now specify rental-inclusive service agreements rather than capital purchase for pilot-scale installations. Equipment lessors capture margin through maintenance bundling and rapid swap-out guarantees. This model concentrates most visibly among Indian pharmaceutical intermediate producers managing PLI scheme volume ramp uncertainty.
Glass Reactors Market Segmentation
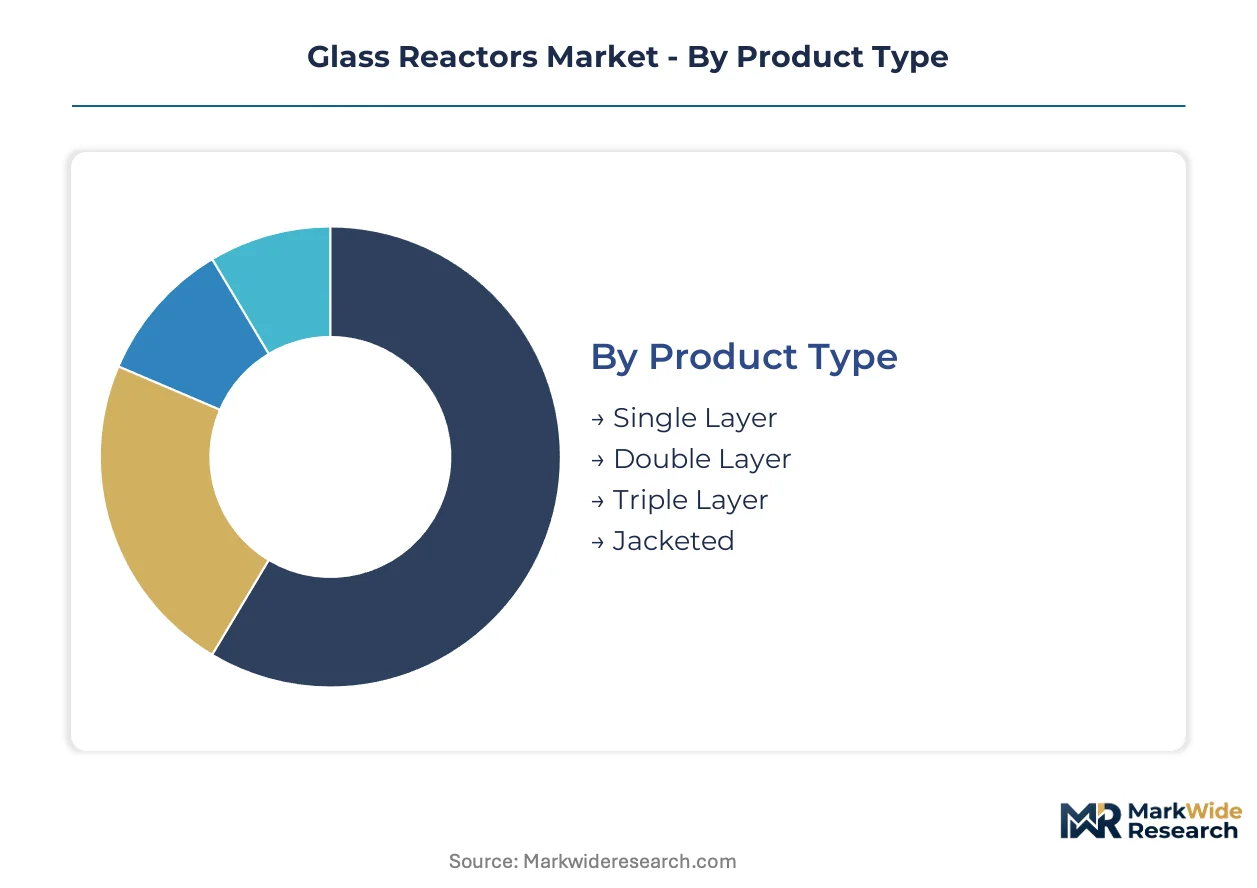
Glass reactor purchasing decisions split across thermal control architecture, process modality, and validation requirements. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape vendor positioning.
Product Type:
Cost tier determines thermal precision capability and capital deployment thresholds for chemical and pharmaceutical operations.
- Jacketed:External thermal fluid circulation enables temperature control within ±0.5°C for exothermic synthesis. Pharmaceutical manufacturers in Maharashtra's Mumbai-Pune corridor specify these for API intermediate production under India's PLI scheme.
- Triple Layer:Vacuum-insulated construction with separate heating/cooling circuits supports FDA 21 CFR Part 11 validation protocols. Biopharmaceutical CMOs absorb 40-60% procurement premiums for automated batch records and material traceability documentation.
- Double Layer:Standard jacket configuration serves pilot-scale installations where thermal uniformity matters but validation requirements remain moderate.
- Single Layer:Basic observation vessels suit educational settings and non-critical mixing operations without temperature control demands.
Jacketed configurations hold installed capacity. Triple Layer is rotating up the share rankings.
Technology:
Process modality separates batch economics from continuous throughput architectures in pharmaceutical and fine chemical manufacturing.
- Batch:Dominant installed base for multi-product flexibility and established qualification protocols. Specialty chemical manufacturers retain these for campaign-based production of corrosive intermediates.
- Continuous:Modular flow reactor trains compress scale-up timelines from months to weeks. The technology is climbing the fastest as manufacturers replace fixed vessels with plug-and-play architecture.
- Automated:Electronic batch recording and sensor integration satisfy EMA Annex 15 qualification mandates for European biopharmaceutical deployments.
- Semi-Batch:Hybrid feeding strategies for reactions requiring controlled reagent addition rates in polymerization processes.
Batch retains volume leadership. Continuous is gaining share fastest among new capacity additions.
Application:
End-use chemistry dictates material compatibility requirements and regulatory scrutiny intensity across pharmaceutical and industrial segments.
- Biopharmaceuticals:Cell culture media preparation and viral vector production demand triple-layer systems with certified borosilicate 3.3 traceability. EMA and FDA cGMP inspections drive specification floors.
- Chemical Synthesis:Halogenation and nitration processes push demand toward enamel-coated glass-lined hybrids. German and Swiss specialty chemical manufacturers adopt these at pilot-to-demo scale.
- Polymerization:Controlled radical reactions require precise thermal management in jacketed configurations for molecular weight distribution control.
- Food Processing:Flavor extraction and enzyme reactions use single and double-layer vessels with sanitary fittings under FSSAI compliance in India.
Biopharmaceuticals command margin premiums. Chemical Synthesis maintains volume concentration.
End User:
Customer type shapes procurement modality between capital purchase, leasing, and service-bundled arrangements.
- Pharmaceutical Manufacturers:Integrated drug developers and CMOs drive demand for validated triple-layer automated systems. India's CDSCO manufacturing license rules tighten material certification for imported reactor trains.
- Research Laboratories:Contract research organizations in Maharashtra's chemical corridor now specify rental-inclusive service agreements rather than capital purchase for pilot-scale flexibility.
- Specialty Chemicals:Fluorination and chlorination process specialists specify hybrid glass-enamel configurations for acid resistance combined with observation capability.
- Academic Institutions:Teaching and basic research applications prioritize single-layer vessels for cost containment and visual demonstration purposes.
Pharmaceutical Manufacturers dominate capital deployment. Research Laboratories are expanding fastest through asset-light leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass reactor trade flows reflect divergent manufacturing strategies across major chemical and pharmaceutical economies. Import dependency for borosilicate 3.3 melt capacity shapes procurement timelines in regions without captive glass production.
Germany
Specialty chemical manufacturers in Baden-Württemberg and North Rhine-Westphalia drive demand for enamel-coated glass-lined hybrid systems. ECHA REACH compliance mandates certified traceability documentation from melt to finished vessel, adding procurement premiums for validated batches. The Basel-Ludwigshafen chemical corridor concentrates pilot-scale installations for fluorination processes.
India
Domestic pharmaceutical intermediate producers are expanding borosilicate glass reactor capacity under the PLI scheme's incentive-linked production quotas. CDSCO manufacturing license rules tighten material certification requirements for imported reactor trains. Maharashtra's Mumbai-Pune corridor clusters contract research organizations specifying rental-inclusive service agreements for pilot-scale flexibility.
United States
Biopharmaceutical manufacturers in Massachusetts and North Carolina require triple-layer automated systems with FDA 21 CFR Part 11 validation protocols. Electronic batch recording and sensor integration deepen specification floors for new equipment purchases. The Research Triangle and Greater Boston anchor demand for GMP-qualified installations in viral vector production.
China
NMPA Good Manufacturing Practice revisions for chemical APIs accelerate domestic replacement of legacy stainless steel with glass-lined and all-glass reactor trains. Yangtze River Delta pharmaceutical manufacturers absorb lead time volatility for premium-grade borosilicate imports. Shanghai and Suzhou chemical parks concentrate capacity additions for contract manufacturing organizations.
Switzerland
Swissmedic oversight and EMA alignment drive qualification requirements for biopharmaceutical glass reactor deployments in the Basel region. Specialty chemical manufacturers adopt pilot-to-demo scale hybrid configurations for halogenation processes. The country's precision engineering base supports modular continuous flow reactor integration with traditional batch infrastructure.
Glass Reactors Market Competitive Landscape
On the supply side, the industry is consolidating around integrated borosilicate manufacturers and modular system architects. Three strategic archetypes dominate: captive glass melt operators controlling input quality from furnace to finished vessel; hybrid enamel-glass specialists serving corrosive chemistry niches; and continuous flow technology pioneers extending batch capabilities into plug-and-play scale-up architectures. Competitive moves center on backward integration into specialty glass production and technology licensing partnerships for modular reactor trains.
Among integrated manufacturers, GMM Pfaudler Ltd. and De Dietrich Process Systems exemplify archetypes spanning captive material control and hybrid coating expertise. Corning Incorporated occupies a position bridging precision glass science with advanced flow reactor architectures. These three anchors represent distinct competitive vectors: Indian-originated integrated production, European enamel-glass hybrid engineering, and US-based materials science innovation.
| Leading Market Players |
|---|
| GMM Pfaudler Ltd. |
| De Dietrich Process Systems |
| Corning Incorporated |
| Büchi AG |
| Parr Instrument Company |
| Ace Glass Incorporated |
| Syrris Ltd. |
| Radleys |
| IKA Works |
| Others |
Supply & Pricing Matrix
Furnace maintenance cycles at German and Czech specialty glass manufacturers create undercapacity conditions that extend lead times and harden supplier pricing power. Pharmaceutical manufacturers absorb procurement premiums for certified traceability documentation while contract research organizations shift toward asset-light leasing to bypass capital deployment thresholds.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and volume scale, with EMA Annex 15 qualified systems commanding substantial premiums over pilot-scale configurations. Pricing pressure stems from stainless steel substitution in commodity API steps, particularly where China's NMPA GMP revisions accelerate domestic replacement. Contract research organizations exhibit highest price sensitivity, while integrated biopharmaceutical manufacturers prioritize validation documentation over unit economics.
Supply Chain Analysis
Contract manufacturing concentration among Maharashtra-based CROs and Yangtze River Delta pharmaceutical producers shapes downstream demand patterns. Geographic supply concentrates in Germany, Czech Republic, and India for borosilicate 3.3 melt capacity and finished vessel fabrication. Raw material dependencies include specialty glass sands, platinum-rhodium alloy components, and precision thermal control instrumentation. Single-source vulnerability around European furnace capacity creates structural risk during maintenance windows. Distribution runs through direct equipment sales for validated systems and rental-service bundling for pilot-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass reactor procurement is shifting toward platform-economics models where modular continuous flow architectures interoperate with legacy batch infrastructure, creating winner-take-most dynamics for system architects controlling scale-up pathways.
For Market Incumbents: Entrench defensive positions through backward integration into borosilicate melt capacity and certification investment for EMA Annex 15 compliance. GMM Pfaudler's captive glass production and De Dietrich's enamel-coating expertise demonstrate how upstream control neutralizes substitute threats from stainless steel migration in Chinese API manufacturing. For New Entrants and Emerging Players: Southeast Asian pharmaceutical corridors offer underpenetrated white-space for rental-inclusive service models. Target Indonesian and Vietnamese contract manufacturers with asset-light pilot-scale offerings, leveraging India's proven leasing architecture as a go-to-market template for early-stage biotechs avoiding capital deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular continuous flow sub-segments as plug-and-play architectures reduce fabrication labor content. Five-to-ten year viability favors acquisition targets with verified Scope 3 emissions documentation for EU CSRD positioning. Monitor ECHA REACH enforcement intensity as an inflection indicator for premium-grade borosilicate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melt Capacity | GMM Pfaudler's captive furnace control neutralizes German-Czech supply concentration risks. |
| Modular Continuous Flow Platform Launch | Corning's plug-and-play scale-up architectures compress pharmaceutical campaign transition timelines. |
| EMA Annex 15 Certification Investment | De Dietrich's qualified documentation secures preferential positioning in European GMP inspections. |
| Asset-Light Leasing Service Model | Maharashtra CRO rental agreements capture margin through maintenance bundling and rapid swap-out guarantees. |
| Hybrid Glass-Enamel Technology Development | Specialty chemical manufacturers in Basel-Ludwigshafen corridor adopt pilot-scale configurations for fluorination processes. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical plant engineers, CRO procurement leads, specialty glass R&D directors, and aftermarket service heads, then refined through secondary validation. Primary fieldwork combined structured interviews with equipment specification committees at Maharashtra chemical corridor facilities and technical directors at German enamel-coating specialists. Secondary sources included CDSCO manufacturing license filings, ECHA REACH registration databases, SEC 10-K equipment disclosure sections, and customs trade data for borosilicate glass vessel imports. Bottom-up capacity installation tracking and top-down pharmaceutical capital expenditure analysis were triangulated to constrain estimate variance.
Demand-supply balance modeling across the analysis window incorporated pharmaceutical intermediate production quotas under India's PLI scheme, NMPA GMP revision implementation timelines, and biopharmaceutical viral vector capacity expansion announcements. Segmentation dimensions included thermal control architecture, process modality, validation tier, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and replacement demand elasticity rather than extrapolation of historical shipments. Industry-specific forecast inputs captured EMA Annex 15 audit failure rates and continuous flow engineering talent scarcity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese stainless steel reactor manufacturers or modular flow technology entrants would shift outcomes. Quarterly review of ECHA REACH enforcement actions, CDSCO import certification rule changes, and pharmaceutical PLI scheme volume allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Silica Sol Market
Glass
North America Glass Insulators Market
Glass
Global Laminated Glass Market
Glass
Glass Recycling Market
Glass
Glass Substrate Market
Glass
Coated Solar Control Glass Market
Glass
Borosilicate Glass Market
Glass
Mexico Flat Glass Market
Glass
Cellular Glass Market
Glass
Glass Forming Machine Market
Glass
Global Energy Efficient Glass Market
Glass
Insulated Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Silica Sand for Glass Making Market
Glass
Screen-Printing Glass Market
Glass
Silica Market