
 Global Pine Chemicals Market | 2026-2036
Global Pine Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pine Chemicals Market Foresight
Multi-source procurement of crude tall oil and gum rosin is expanding as buyers reduce dependency on single-origin pine supply. Ingevity Corporation anchors its position through captive access to Kraft pulping byproducts across the southeastern United States. Kraton Corporation competes on specialized tackifier derivatives for adhesive formulators. Harima Chemicals Group leverages integrated distillation capabilities in Japan to sustain rosin ester output.
Pine chemicals encompass turpentine, rosin, pine oil, and tall oil fractions extracted via solvent extraction or steam distillation of pine oleoresin and Kraft black liquor, serving primarily as renewable feedstocks for adhesives, coatings, and surfactant synthesis. Rosin derivatives dominate value capture due to entrenched demand in printing ink binders and pressure-sensitive adhesives, while tall oil fatty acids are displacing petrochemical alternatives in alkyd resin production. The adhesives application segment leads volume absorption, though personal care-grade pine oil commands premium pricing through refined distillation standards.
EPA bio-preferred program criteria and REACH substance restrictions in Europe are elevating certification burdens for imported rosin derivatives. FDA food-contact regulations govern tall oil usage in food processing applications, constraining supplier qualification pools. Stakeholders must monitor feedstock competition from biochemical platforms and pulp mill capacity cycles to secure long-term oleoresin supply.
Market Dynamics
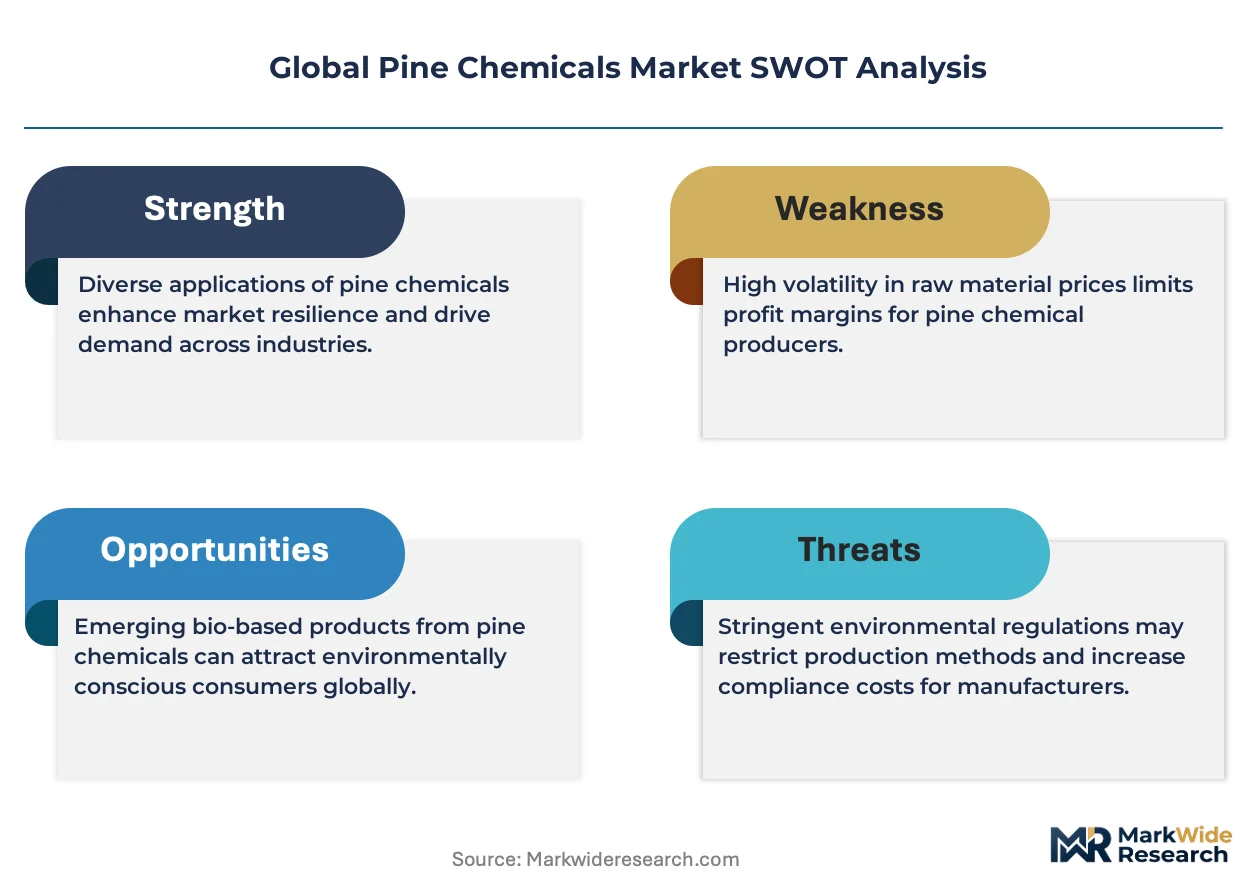
Kraft pulp mill capacity cycles now dictate crude tall oil availability, forcing chemical processors to hedge feedstock exposure through multi-year offtake agreements with integrated papermakers.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening specifications on petrochemical-derived tackifiers are redirecting adhesive formulators toward rosin ester alternatives.
- Brazilian planted pine expansion:Araucaria and Pinus elliotii plantations in Paraná and Santa Catarina states are supplying expanding South American distillation clusters with predictable oleoresin flows.
- Alkyd resin reformulation:Tall oil fatty acids are capturing volume in architectural coatings as manufacturers phase out phthalate-based plasticizers.
Market Restraints
- Crude tall oil supply concentration:Integrated pulp-chemical conglomerates in Scandinavia and the southeastern United States control over two-thirds of merchant CTO availability.
- Seasonal gum rosin collection:Tapping operations in China and Indonesia face climate-dependent yield swings that destabilize derivative pricing.
- Biochemical platform competition:Fermentation-derived terpenes from sugarcane feedstocks are encroaching on turpentine's traditional solvent and fragrance applications.
Strategic Opportunities
- Indian personal care expansion:FSSAI cosmetic-grade certifications for refined pine oil are unlocking premium positioning in ayurvedic and natural product formulations.
- EU Green Deal bioeconomy funding:Horizon Europe grants for renewable feedstock valorization are subsidizing tall oil biorefinery investments in Finland and Sweden.
- Digital B2B marketplaces:Specialized chemical platforms are disintermediating traditional rosin brokers, compressing procurement cycles for mid-volume adhesive compounders.
Industry Challenges
- Distillation technician scarcity:Fractionation facilities require skilled operators capable of managing rosin ester color stability and acid number specifications.
- Multi-jurisdiction certification timelines:FDA food-contact notifications, REACH dossier updates, and BIS import registrations create 18-24 month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pine Chemicals Market |
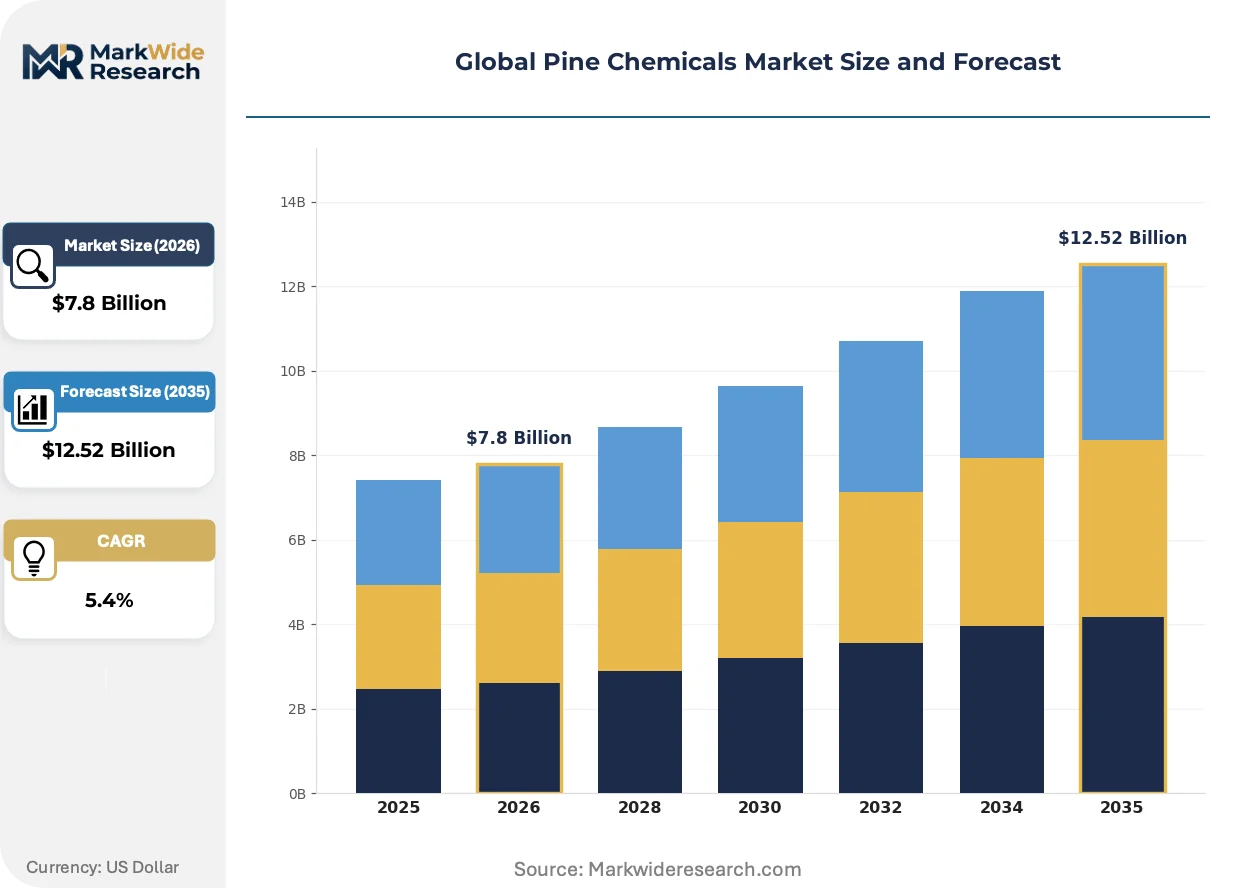
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turpentine, Rosin, Pine Oil, Tall Oil Application: Adhesives, Coatings, Inks, Personal Care End Use Industry: Construction, Automotive, Pulp & Paper, Food Processing Distribution Channel: Direct Sales, Distributors, Online Retail, Export |
| Companies Covered | Harima Chemicals Group, Inc., Forchem Oyj, Kraton Corporation, Florachem, DRT, Ingevity Corporation, Arakawa Chemical Industries, Ltd., Georgia-Pacific Chemicals, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pine Chemicals Market Shifts & Advancements
Continuous extraction technologies and regulatory bio-preferentiality are compressing the traditional boundaries between papermaking byproduct recovery and dedicated oleoresin agriculture.
Supercritical CO2 extraction systems are absorbing market share from conventional steam distillation in gum rosin processing. Specialty adhesive manufacturers in Germany and Japan are retrofitting facilities to handle these lower-temperature fractions. The technology is absorbing premium positioning by preserving heat-sensitive terpene profiles that conventional methods degrade.
EPA bio-preferred program criteria are elevating certification burdens for imported rosin derivatives entering US federal procurement channels. Manufacturers must now document renewable content percentages through third-party ASTM D6866 testing. Adhesive formulators serving defense and infrastructure contracts are restructuring supply chains to maintain compliant feedstock pools.
Long-term offtake contracting is displacing spot market purchasing among large-volume tall oil fatty acid consumers. Alkyd resin producers in Italy and the Netherlands are locking in five-year supply agreements directly with Scandinavian pulp mills. This behavior is most visible in architectural coatings, where raw material cost predictability outweighs short-term price optimization.
Global Pine Chemicals Market Segmentation
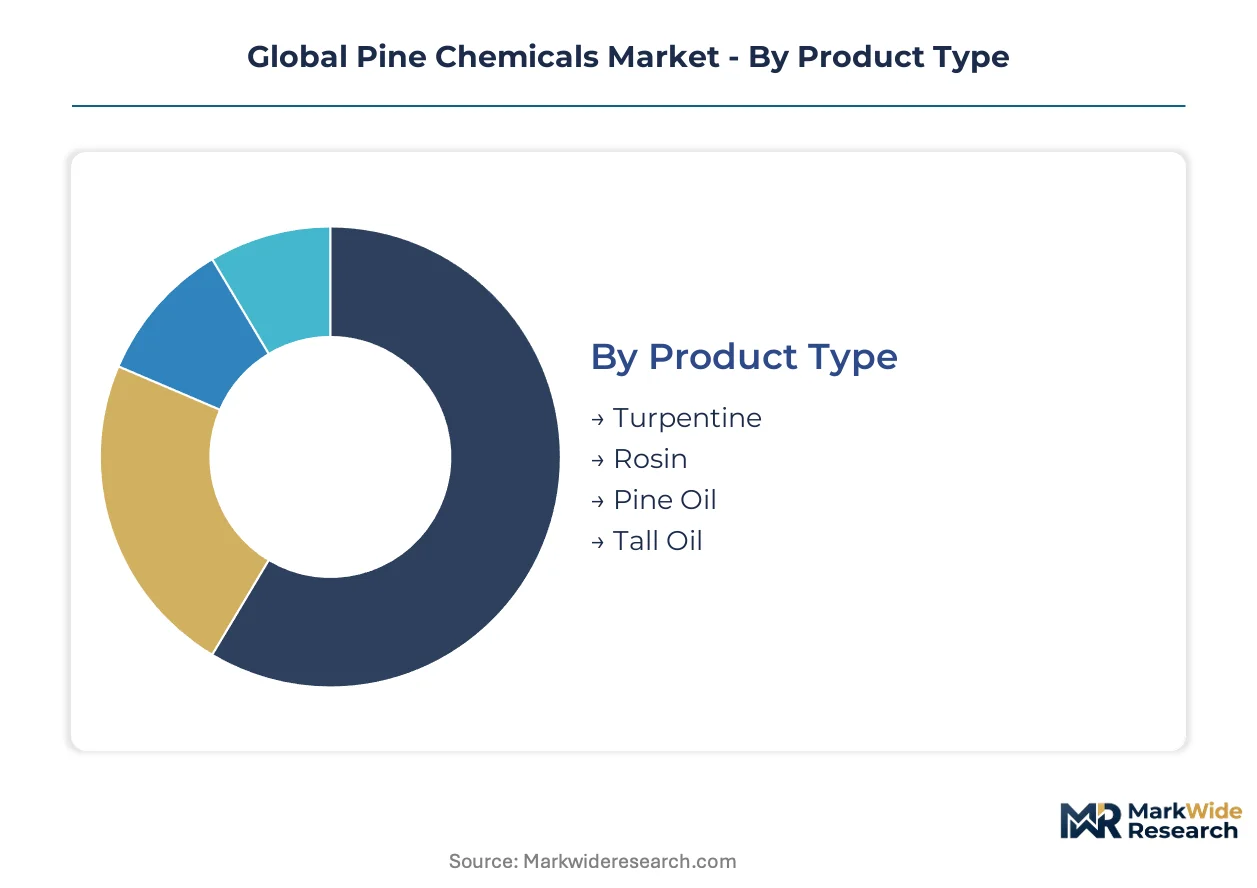
Pine chemicals fragment across four distinct taxonomies, each revealing divergent margin structures and procurement patterns. Understanding how product specifications, application requirements, and channel economics intersect determines where value capture concentrates.
Product Type:
Reformulation cycles across adhesives and coatings are driving substitution between oleoresin-derived and Kraft byproduct-sourced fractions, reshaping procurement priorities by chemistry.
- Turpentine:A volatile terpene fraction extracted via steam distillation of pine oleoresin, serving as feedstock for synthetic camphor, pinene derivatives, and fragrance intermediates. Italian and German adhesive manufacturers are absorbing expanded volumes for low-VOC solvent systems as REACH restrictions tighten on petroleum-based alternatives.
- Rosin:The solid resinous residue from oleoresin distillation, comprising abietic acid and pimaric acid fractions that dominate printing ink binders and pressure-sensitive adhesive tackifiers. Chinese gum rosin faces supply volatility from climate-dependent tapping seasons, while Brazilian planted pine offers more predictable harvest cycles.
- Pine Oil:A refined terpene alcohol mixture with antimicrobial and wetting properties, commanding premium pricing through FSSAI cosmetic-grade certifications in Indian ayurvedic formulations.
- Tall Oil:A byproduct of Kraft pulping containing fatty acids and rosin acids, displacing petrochemical feedstocks in alkyd resin production for architectural coatings.
Volume placements concentrate in Rosin; the faster expansion belongs to Tall Oil.
Application:
End-user certification requirements fragment demand by performance tier, with food-contact and skin-contact specifications creating distinct procurement pools.
- Adhesives:Pressure-sensitive and hot-melt formulations consume rosin esters and terpene resins as primary tackifiers, with German automotive suppliers leading reformulation away from petroleum-derived alternatives under ECHA substance restrictions.
- Coatings:Alkyd resin producers in the Netherlands and Italy are locking in long-term tall oil fatty acid contracts to secure cost predictability for architectural and industrial paint lines.
- Inks:Publication gravure and flexographic printing rely on rosin-modified phenolic resins for solvent release and gloss retention.
- Personal Care:Refined pine oil fractions meet antimicrobial and fragrance specifications in natural product formulations, with Indian FSSAI certifications unlocking premium positioning.
Adhesives commands the dominant volume position; Coatings is climbing the fastest as alkyd resin reformulation accelerates.
End Use Industry:
Downstream capital expenditure cycles and regulatory exposure determine which industries sustain premium pricing for certified grades.
- Construction:Sealants, flooring adhesives, and waterproofing membranes absorb rosin esters and tall oil derivatives, with Brazilian infrastructure projects driving South American demand concentration.
- Automotive:Interior adhesives and underbody coatings require low-emission, heat-stable tackifier specifications that rosin derivatives satisfy under EPA bio-preferred procurement criteria.
- Pulp & Paper:Integrated mills generate captive crude tall oil supplies, with Scandinavian producers dominating merchant availability.
- Food Processing:Tall oil fatty acids serve as defoamers and lubricants in FDA-regulated applications, constraining supplier qualification to notified substances.
Pulp & Paper anchors supply-side concentration; Construction is gaining share fastest on Brazilian planted pine expansion.
Distribution Channel:
Contracting behavior diverges by volume scale, with large consumers bypassing intermediaries while specialty formulators retain distributor relationships for technical service.
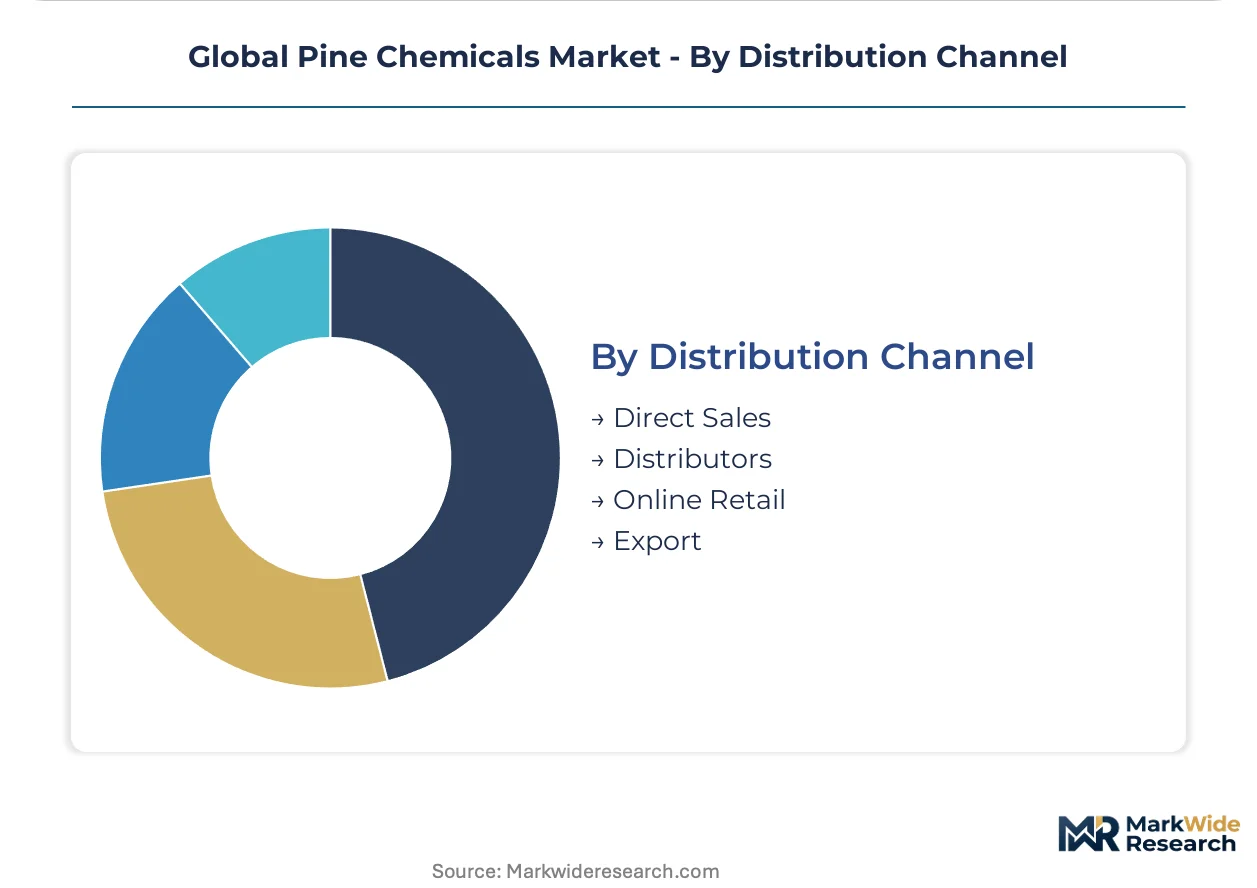
- Direct Sales:Alkyd resin and adhesive compounders with annual offtake above threshold volumes negotiate multi-year agreements directly with Scandinavian pulp mills and Brazilian distillation clusters.
- Distributors:Regional chemical distributors stock rosin esters and pine oil grades for mid-volume buyers requiring blended technical support and logistics coordination.
- Online Retail:Digital B2B platforms are compressing procurement cycles for specialty adhesive formulators seeking spot purchases of certified grades.
- Export:Cross-border shipments of crude tall oil and gum rosin flow through Rotterdam and Singapore trading hubs to chemical processing clusters.
Direct Sales captures the largest volume commitment; Online Retail is expanding most quickly as digital platforms disintermediate traditional rosin brokers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Planted pine forests in Brazil's southern states anchor the fastest-expanding oleoresin supply base, while Kraft pulp mill clustering in Scandinavia and the southeastern United States dictates crude tall oil availability for derivative processors worldwide.
United States
Kraft pulping operations across Georgia, Alabama, and the Carolinas generate captive crude tall oil streams that chemical processors convert into tall oil fatty acids and rosin derivatives. EPA bio-preferred procurement standards now govern federal adhesive and coating contracts, forcing formulators to document renewable content through ASTM D6866 testing. The southeastern forest products corridor sustains integrated chemical manufacturing clusters near Savannah and Charleston.
Brazil
Araucaria and Pinus elliotii plantations in Paraná and Santa Catarina states supply expanding distillation capacity with predictable oleoresin harvest cycles independent of climate-dependent gum tapping. ANVISA pharmaceutical-grade certifications for refined pine oil fractions are opening export channels to Mercosur neighbors. Curitiba and Joinville anchor South America's fastest-growing rosin ester and turpentine derivative production bases.
China
Seasonal gum rosin collection from Masson pine forests in Guangxi and Yunnan provinces faces yield volatility from drought and frost events that destabilize global derivative pricing. GB standards for industrial-grade rosin derivatives are tightening purity specifications for export-bound material. The Pearl River Delta chemical processing zone concentrates distillation and esterification capacity serving domestic adhesive and coatings manufacturers.
Germany
Automotive adhesive formulators in Baden-Württemberg and Bavaria are reformulating pressure-sensitive and hot-melt systems under ECHA substance restrictions targeting petroleum-derived tackifiers. REACH dossier updates for rosin ester imports now require 18-24 month pre-registration timelines. The Rhine-Ruhr industrial corridor hosts specialty chemical distributors stocking certified grades for mid-volume compounders.
India
FSSAI cosmetic-grade certifications for refined pine oil are unlocking premium positioning in ayurvedic and natural personal care formulations manufactured in Maharashtra and Gujarat. BIS import registrations for industrial rosin derivatives create compliance bottlenecks for Chinese and Indonesian suppliers. Mumbai and Ahmedabad chemical trading hubs are absorbing expanded volumes of certified pine oil for fragrance and antimicrobial applications.
Global Pine Chemicals Market Competitive Landscape
Long-term offtake contracting dominates the current landscape as processors secure feedstock predictability against pulp mill capacity cycles. Market structure concentrates around integrated pulp-chemical conglomerates controlling merchant crude tall oil availability, mid-scale distillation specialists serving regional adhesive formulators, and technology licensors of supercritical extraction systems. Strategic archetypes include captive feedstock holders, toll distillation operators, and certification-focused specialty compounders. Competitive moves center on multi-year supply agreements with Scandinavian and Brazilian producers, plus retrofit investments in low-temperature fractionation capabilities.
Among North American integrated operators, Ingevity Corporation and Georgia-Pacific Chemicals exemplify the captive feedstock archetype through Kraft pulping byproduct access. Kraton Corporation occupies a position within the specialty tackifier tier serving adhesive formulators with differentiated rosin ester derivatives. These three anchors illustrate how feedstock security, regional distillation presence, and application-specific certification capabilities determine competitive positioning across procurement cycles.
| Leading Market Players |
|---|
| Harima Chemicals Group, Inc. |
| Forchem Oyj |
| Kraton Corporation |
| Florachem |
| DRT |
| Ingevity Corporation |
| Arakawa Chemical Industries, Ltd. |
| Georgia-Pacific Chemicals |
| Eastman Chemical Company |
| Others |
Supply & Pricing Matrix
EPA bio-preferred procurement standards gate qualified supply pools for federal adhesive and coating contracts while stratifying premium access to certified tall oil fatty acid and rosin ester grades. Formulators lacking ASTM D6866 documentation face exclusion from defense and infrastructure procurement channels, compressing margin capture to compliant producers.
Pricing Analysis
Technical service bundling separates full-service distributors from unbundled spot brokers in rosin derivative procurement. Three-tier pricing structure across pharmaceutical-grade, industrial-certified, and commodity unrefined levels tracks FSSAI, REACH, and FDA notification status. Cost compression in standard industrial grades intensifies as Chinese gum rosin volatility feeds through to derivative markets. Mid-volume adhesive compounders exhibit highest price sensitivity, while automotive OEMs under ECHA mandates absorb premium certified grades.
Supply Chain Analysis
Crude tall oil reclamation from Kraft black liquor creates closed-loop material flows at integrated Scandinavian and southeastern United States pulp mills. Merchant availability draws from Finland, Sweden, and the United States, with Brazilian planted pine expanding oleoresin distillation capacity. Feedstock competition from sugarcane fermentation platforms threatens turpentine solvent applications. Long-term offtake contracting dominates downstream procurement as alkyd resin producers seek cost predictability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kraft pulp mill capacity cycles constrain merchant crude tall oil availability, propping pricing power for integrated producers with captive feedstock access.
For Market Incumbents: Deepen captive supply security through multi-year offtake agreements with Scandinavian and Brazilian pulp operators. Expand supercritical CO2 extraction capacity to capture premium positioning in heat-sensitive terpene fractions. Fermentation-derived terpene substitutes threaten traditional turpentine applications. For New Entrants and Emerging Players: Mid-volume specialty adhesive compounders in Germany and Japan present accessible entry points through digital B2B procurement platforms. Indian FSSAI-certified pine oil for ayurvedic personal care offers faster certification timelines than FDA food-contact pathways. Lead with toll distillation partnerships to bypass capital-intensive fractionation investments. For Investors and Strategic Acquirers: Five-year supply agreement announcements from Italian and Dutch alkyd resin producers signal feedstock security premiums. Target integrated pulp-chemical operators with merchant crude tall oil exposure and established REACH dossiers. Monitor Brazilian planted pine harvest yield reports as leading inflection indicators for oleoresin supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in crude tall oil access against Scandinavian pulp mill capacity cycles. |
| Backward Integration | Captures planted pine oleoresin supply in Paraná and Santa Catarina states. |
| Green Manufacturing Transition | Supercritical CO2 retrofit preserves terpene profiles for REACH-compliant adhesive grades. |
| Capacity Expansion | Adds rosin ester output to serve German automotive reformulation under ECHA restrictions. |
| Joint Venture | Combines Kraft pulping byproduct access with regional distillation expertise. |
Research Methodology
Trade databases, SEC filings, and ECHA registration dossiers formed the secondary backbone, supplemented by customs records tracking crude tall oil and gum rosin flows through Rotterdam and Singapore hubs. Primary interviews with Kraft pulp mill procurement directors, adhesive formulator technical leads, and rosin broker operators validated supply concentration assumptions. Bottom-up tall oil fatty acid volume estimates triangulated against top-down alkyd resin production forecasts.
Bottom-up modeling tracked product-grade splits across turpentine, rosin, pine oil, and tall oil fractions, while top-down validation anchored to end-use industry consumption patterns in construction, automotive, and personal care. CAGRs derived from segmented growth differentials across adhesive, coating, ink, and personal care applications. Pulp mill capacity utilization rates and Brazilian plantation harvest cycles served as industry-specific forecast inputs.
Revisions become necessary when pulp mill closure announcements, Brazilian drought conditions, or fermentation-terpene cost parity events materialize across the analysis window. Forecasts reflect assumptions about sustained EPA bio-preferred enforcement and REACH substance restriction timelines. Practitioners should monitor Scandinavian pulp mill operating rates and Chinese gum rosin tapping yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ruthenium Tetroxide Market
Chemicals
Ferric Oxide Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Benzhydrol Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Uranyl Carbonate Market
Chemicals
Calcium Borate Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Superplasticizer Market
Chemicals
Guaiazulene Market
Chemicals
India Ethoxylates Market
Chemicals
Diethylenetriamine (DETA) Market