
 Glass Lined Equipment Market | 2026-2036
Glass Lined Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Lined Equipment Market Analytics
Fluoropolymer-lined steel is rebalancing toward borosilicate glass-enameled substrates as sulfuric acid concentration thresholds rise past PTFE degradation points. GMM Pfaudler Ltd. leverages captive enameling furnaces across Western India to anchor regional supply security. Thaletec GmbH competes through DIN-certified reactor geometries that dominate European fine chemical installations. DE Dietrich Process Systems extends its QVF glass lineage into modular skid-mounted units for multipurpose pharmaceutical plants.
Glass lined equipment denotes carbon or stainless steel substrates fused with a borosilicate glass enamel layer, typically 0.8–2.0 mm thick, manufactured through wet spraying followed by firing at 800–900°C to achieve chemical inertness against pH 0–14 media. This construction serves as the primary containment boundary for corrosive synthesis, crystallization, and storage operations across process industries. Reactors command the largest installed base among product types, though vessels for pharmaceutical aseptic processing represent the fastest-growing margin pool as USP Class VI compliance tightens. Chemical end users sustain the highest volume absorption, while predictive maintenance strategies are displacing scheduled shutdown models among asset-intensive operators seeking to minimize unplanned vessel re-enameling costs.
ASME Section VIII Division 1 governs pressure-boundary design in North American jurisdictions, while the EU Pressure Equipment Directive 2014/68/EU mandates CE conformity assessment for reactor systems above specified hazard thresholds. India's BIS IS 4682 standard enforces thermal shock resistance protocols for enamel coatings deployed in domestic caustic process environments. Process licensors and EPC contractors must monitor evolving MEE emission norms in China and dual carbon compliance trajectories that are redirecting capital toward longer-service-life glass lined assets over disposable polymer alternatives.
Market Dynamics
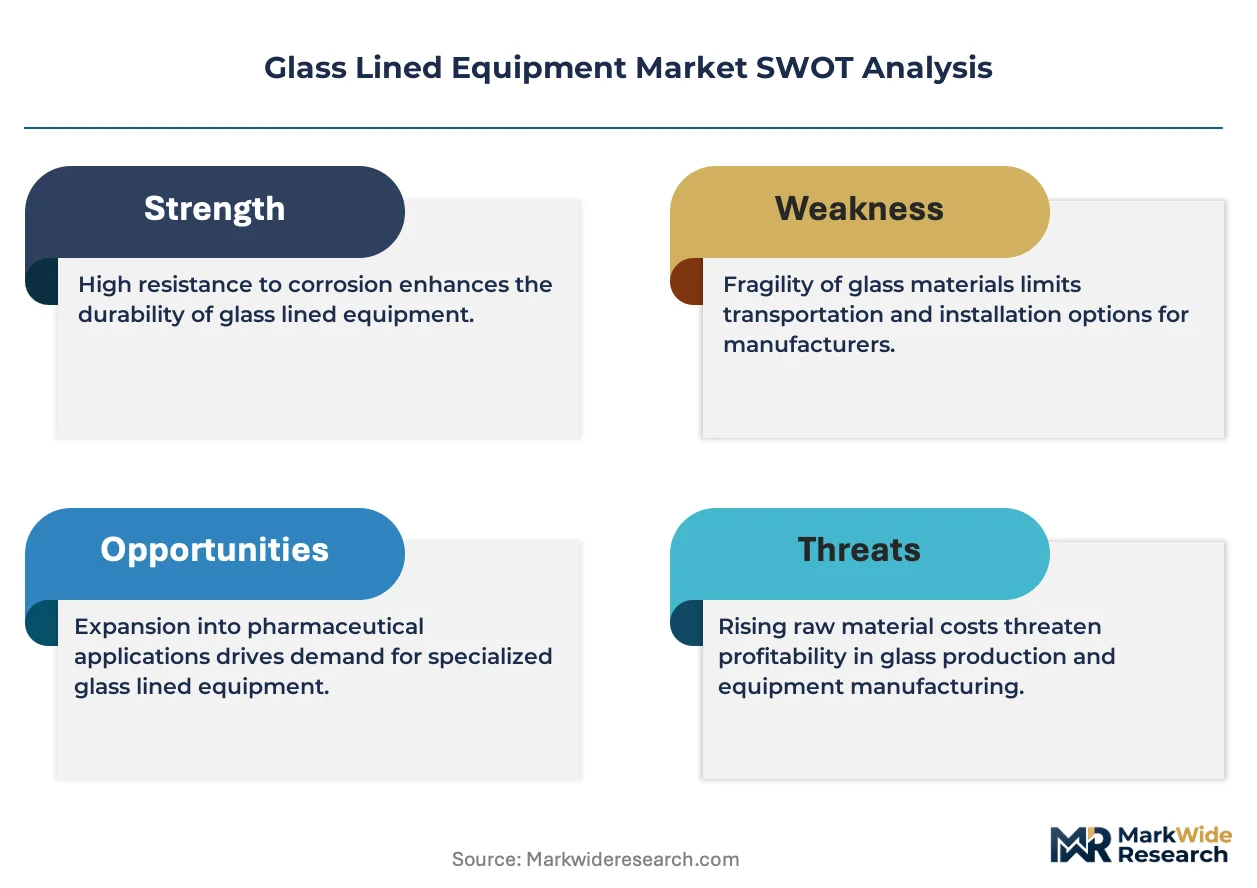
PTFE-lined equipment degradation under high-concentration sulfuric acid is redirecting capital toward borosilicate-enameled reactor systems across specialty chemical corridors.
Growth Catalysts
- CDSCO Process Validation Mandates:Indian pharmaceutical manufacturers are expanding glass lined reactor fleets to meet domestic regulatory compliance for active pharmaceutical ingredient synthesis.
- Corrosive Chemical Output Intensification:Gujarat's chemical corridor is driving demand clusters for enameled containment systems handling pH 0–14 process media.
- Dual Carbon Compliance Trajectories:China's emission reduction frameworks are redirecting capital toward longer-service-life glass lined assets over disposable polymer alternatives.
Market Restraints
- Enamel Furnace Supply Concentration:Western India hosts limited captive enameling capacity, creating regional supply security vulnerabilities for domestic reactor demand.
- Re-enameling Cost Volatility:Unplanned vessel re-enameling expenses under scheduled shutdown models strain asset-intensive operator budgets.
- PTFE Substitution Threat:Fluoropolymer-lined steel retains cost advantages in low-concentration acid applications below degradation thresholds.
Strategic Opportunities
- Modular Skid-Mounted Systems:Multipurpose pharmaceutical plants are adopting standardized reactor geometries for rapid process reconfiguration.
- Predictive Maintenance Convergence:Asset-intensive operators are integrating IoT sensor networks with glass lined vessel integrity monitoring to compress unplanned downtime.
- USP Class VI Compliance Tailwind:Aseptic pharmaceutical processing vessels face tightening material certification standards that favor borosilicate enamel over polymer linings.
Industry Challenges
- Specialized Welding Certification Gap:Qualified technicians for glass-to-metal fusion repair remain scarce across emerging chemical manufacturing hubs.
- Multi-Jurisdictional Pressure Boundary Compliance:EPC contractors must reconcile ASME Section VIII Division 1, EU Pressure Equipment Directive 2014/68/EU, and BIS IS 4682 thermal shock protocols for export-bound reactor systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Lined Equipment Market |
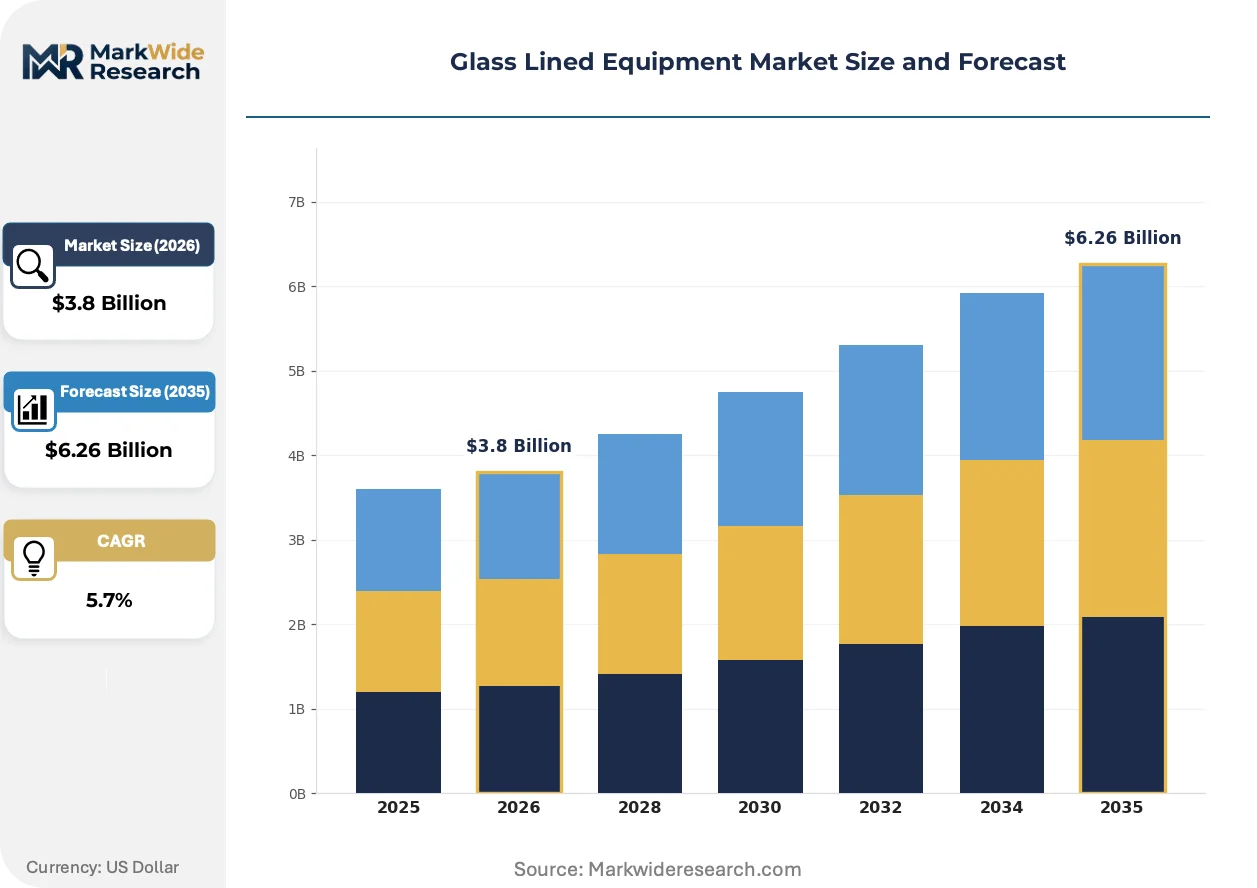
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactors, Tanks, Vessels, Pipelines End User: Chemical, Pharmaceutical, Oil & Gas, Food & Beverage Installation Type: Onshore, Offshore, Industrial, Commercial Maintenance Strategy: Preventive, Predictive, Corrective, Scheduled |
| Companies Covered | Asahi Glassplant Inc., Standard Glass Lining Technology, GMM Pfaudler Ltd., Ablaze Glass Works Pvt. Ltd., Sachin Industries Ltd., DE Dietrich Process Systems, Thaletec GmbH, Zibo Taiji Industrial Enamel, HLE Glascoat Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Lined Equipment Market Evolving Landscape
Equipment architecture is fragmenting between standardized modular platforms for multipurpose plants and bespoke geometries for dedicated fine chemical synthesis.
Modular skid-mounted glass lined reactor systems are modularizing process containment for pharmaceutical manufacturers seeking rapid product changeover capabilities. Contract development and manufacturing organizations are adopting these standardized units to compress facility validation timelines. This architecture is modularizing capital deployment patterns, enabling smaller batch producers to access enameled containment without permanent infrastructure commitment.
REACH chemical safety registrations and EU F-Gas Regulation phase-down schedules are tightening material specifications for process equipment in European fine chemical installations. Enameled reactor systems gain preference as fluoropolymer-lined alternatives face substance restriction scrutiny. German and Swiss fine chemical producers are accelerating DIN-certified vessel procurement to preempt compliance-driven supply disruption.
After-sales service unbundling is fragmenting traditional full-service contracts into discrete inspection, re-enameling, and digital monitoring components. Asset owners in India's chemical corridor are selectively procuring predictive maintenance subscriptions while retaining third-party repair relationships. This pattern is most visible among mid-scale specialty chemical producers balancing operational control against vendor dependency.
Glass Lined Equipment Market Segmentation
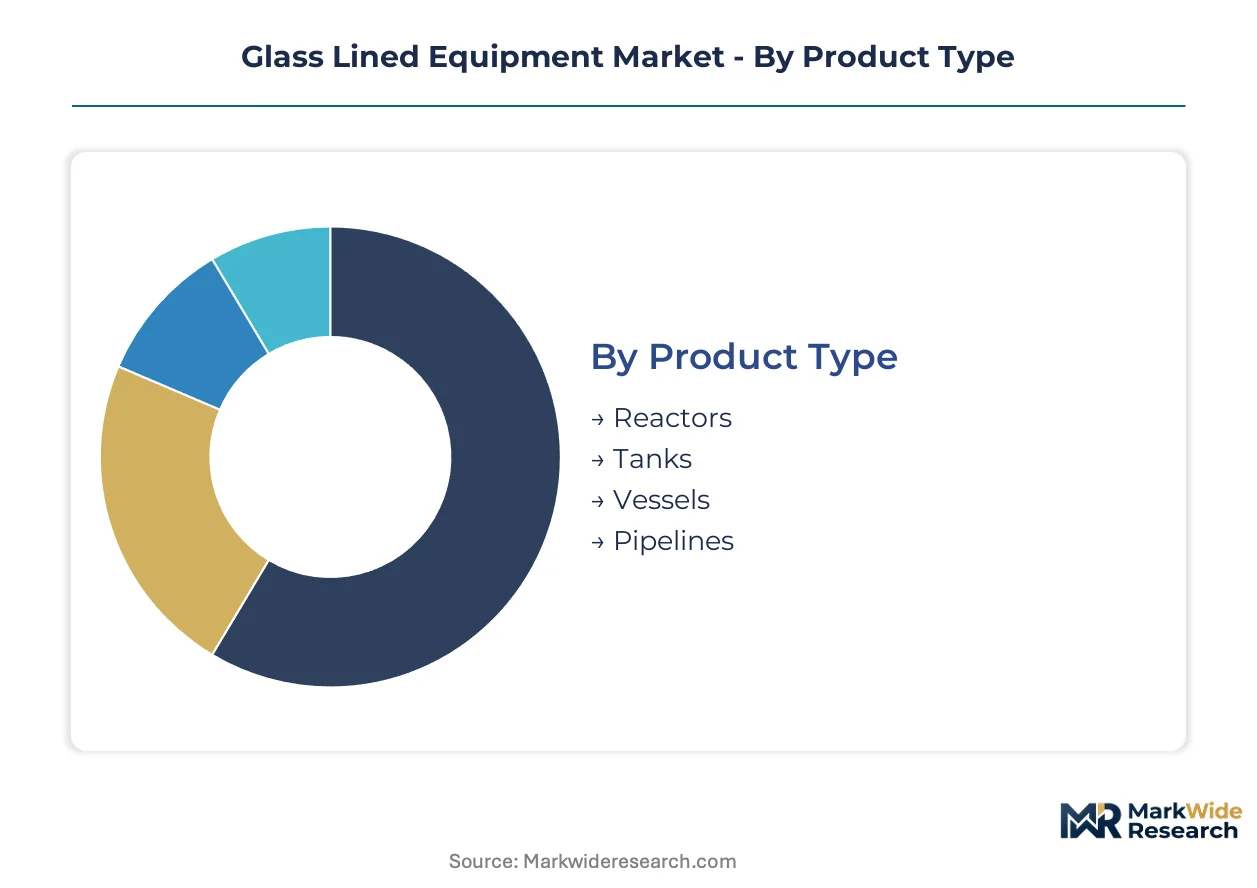
Glass lined equipment segmentation reveals how supply-side specialization aligns with process intensity across end-use verticals. Product architecture, maintenance economics, and installation constraints collectively determine procurement patterns for enameled containment systems.
Product Type:
Supply concentration in reactor manufacturing dominates Western India's captive enameling infrastructure, with furnace capacity allocation favoring high-margin pharmaceutical-grade units over commodity tanks.
- Reactors:Cylindrical vessels with agitation systems and jacketed heat transfer surfaces, typically rated for pressures up to 10 bar. Gujarat's specialty chemical corridor absorbs the majority of domestic reactor output as sulfuric acid concentration thresholds rise past PTFE degradation points.
- Vessels:Static containment units for storage and crystallization operations, ranging from 100 to 50,000 liter nominal capacity. Aseptic pharmaceutical processing applications in India are tightening USP Class VI material certification standards that favor borosilicate enamel construction.
- Tanks:Large-volume atmospheric or low-pressure storage for intermediate process fluids. Chemical end users in corrosive synthesis applications specify DIN-certified geometries for extended service life.
- Pipelines:Enameled piping systems for corrosive fluid transport between process units. Modular skid-mounted pharmaceutical plants are standardizing pipeline configurations to compress facility validation timelines.
Reactors absorb the bulk of installed capacity; vessels are expanding most quickly under tightening pharmaceutical material certification standards.
End User:
Cost tier differentiation separates asset-intensive chemical operators seeking extended service life from pharmaceutical manufacturers prioritizing rapid process reconfiguration capabilities.
- Chemical:Specialty and commodity chemical producers handling pH 0–14 process media. India's MEE emission norms and dual carbon compliance trajectories are redirecting capital toward longer-service-life glass lined assets over disposable polymer alternatives in Gujarat's chemical corridor.
- Pharmaceutical:API manufacturers and CDMOs requiring aseptic containment boundaries. CDSCO process validation mandates are expanding glass lined reactor fleets for domestic active pharmaceutical ingredient synthesis.
- Oil & Gas:Downstream refineries and petrochemical complexes with corrosive hydrocarbon processing needs. Corrosion resistance specifications favor enameled systems in sulfur-rich feedstock handling.
- Food & Beverage:Processors requiring inert surfaces for acidified product handling. Food-grade enamel certifications constrain supplier qualification to specialized coating facilities.
Chemical end users command the largest volume absorption; pharmaceutical applications are climbing the fastest under tightening domestic regulatory compliance requirements.
Installation Type:
Geographic deployment patterns reflect regional industrial clustering, with onshore chemical corridor concentration driving furnace capacity allocation decisions in Western India.
- Industrial:Permanent process plant installations with dedicated utility infrastructure. Asset-intensive operators are integrating IoT sensor networks with glass lined vessel integrity monitoring to compress unplanned downtime.
- Onshore:Land-based facilities with conventional foundation and structural support systems. Gujarat's specialty chemical output intensification is clustering demand for enameled containment in onshore process configurations.
- Commercial:Multi-purpose facilities with shared utility systems and flexible process routing. Contract development and manufacturing organizations are adopting modular skid-mounted units to enable rapid product changeover.
- Offshore:Marine platform and subsea applications with space-constrained layouts. Corrosion resistance requirements in salt-laden environments favor glass lined systems for chemical injection packages.
Industrial installations hold the majority of existing asset base; commercial configurations are gaining share fastest among CDMOs seeking operational flexibility.
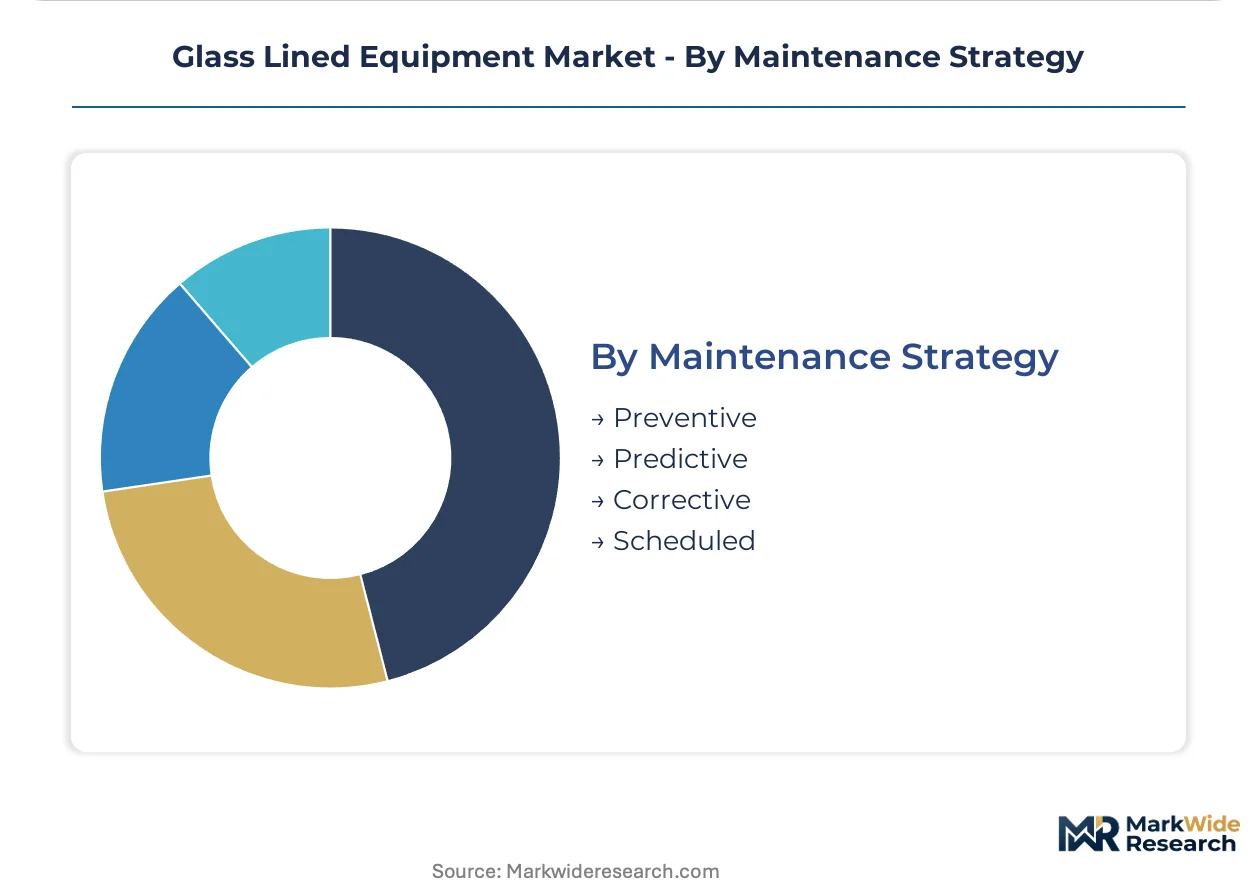
Maintenance Strategy:
Customer type stratification separates predictive maintenance adopters from scheduled shutdown operators, with mid-scale specialty chemical producers selectively procuring digital monitoring subscriptions.
- Predictive:Condition-based intervention triggered by real-time integrity monitoring. After-sales service unbundling is fragmenting traditional full-service contracts into discrete inspection and digital monitoring components for asset owners in India's chemical corridor.
- Preventive:Time-based inspection and re-coaling cycles to preempt coating degradation. Unplanned vessel re-enameling expenses under rigid preventive schedules strain operator budgets.
- Scheduled:Planned shutdown windows for comprehensive vessel refurbishment. Qualified technicians for glass-to-metal fusion repair remain scarce across emerging chemical manufacturing hubs.
- Corrective:Reactive repair following coating failure or process contamination events. Re-enameling cost volatility under emergency response models drives total cost of ownership premiums.
Scheduled maintenance retains the largest installed service contract base; predictive strategies are expanding most quickly among asset-intensive operators minimizing unplanned vessel re-enameling costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters concentrate in chemical manufacturing corridors where corrosive process intensification meets tightening containment regulations. India's western industrial belt and Germany's fine chemical regions anchor reactor procurement volumes. China's dual carbon mandates reshape capital allocation toward extended-service-life assets.
India
CDSCO process validation mandates for active pharmaceutical ingredient synthesis expand glass lined reactor fleets across domestic pharmaceutical manufacturers. BIS IS 4682 thermal shock resistance protocols enforce enamel coating standards for caustic process environments. Gujarat's chemical corridor absorbs the majority of domestic reactor output as specialty chemical producers intensify sulfuric acid handling operations.
Germany
Fine chemical producers accelerate DIN-certified vessel procurement to preempt REACH substance restriction disruption. ECHA chemical safety registrations and EU F-Gas Regulation phase-down schedules tighten material specifications for process equipment. The country's industrial heartland clusters pharmaceutical-grade enameling demand as fluoropolymer alternatives face regulatory scrutiny.
China
MEE emission norms and dual carbon compliance trajectories redirect capital toward longer-service-life glass lined assets over disposable polymer alternatives. SAMR equipment safety standards govern pressure vessel conformity assessment for corrosive synthesis operations. Shandong Peninsula chemical producers intensify borosilicate-enameled system deployment under environmental enforcement tightening.
United States
ASME Section VIII Division 1 pressure-boundary design standards govern reactor system certification for corrosive pharmaceutical and chemical synthesis. FDA current good manufacturing practice requirements tighten material traceability for aseptic processing containment. Gulf Coast petrochemical corridors specify enameled systems for sulfur-rich feedstock handling as refinery complexity rises.
Switzerland
Swissmedic pharmaceutical manufacturing standards and EU MDR device regulation convergence tighten material certification for aseptic containment boundaries. Fine chemical installations in the country's pharmaceutical manufacturing belt specify modular skid-mounted reactor geometries for rapid process reconfiguration. Basel-region CDMOs compress facility validation timelines through standardized enameled containment procurement.
Glass Lined Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive enameling capacity concentrating among Western India-based integrated producers. The vendor base organizes around three archetypes: integrated furnace operators controlling substrate-to-coating value chains, modular system integrators specializing in pharmaceutical-grade skid configurations, and regional fabricators serving chemical corridor maintenance demand. Competitive moves center on furnace capacity expansion in high-growth corridors and strategic partnerships with process licensors for export-bound reactor certification.
Among Western India-based integrated producers, GMM Pfaudler Ltd. anchors regional supply security through captive enameling infrastructure. DE Dietrich Process Systems GmbH exemplifies the European specialist tier with modular system capabilities extending into pharmaceutical-grade configurations. Thaletec GmbH occupies a position within the DIN-certified precision segment serving fine chemical installations. These three represent distinct competitive vectors: geographic supply concentration, modular platform development, and regulatory-specialized certification expertise.
| Leading Market Players |
|---|
| Asahi Glassplant Inc. |
| Standard Glass Lining Technology |
| GMM Pfaudler Ltd. |
| Ablaze Glass Works Pvt. Ltd. |
| Sachin Industries Ltd. |
| DE Dietrich Process Systems |
| Thaletec GmbH |
| Zibo Taiji Industrial Enamel |
| HLE Glascoat Limited |
| Others |
Value Network & Pricing Analysis
Asset-intensive chemical operators in Gujarat's specialty chemical corridor anchor volume procurement, locking in project-based contract pricing for reactor systems while pharmaceutical CDMOs absorb premium-tier modular configurations.
Pricing Analysis
Volume absorption concentrates in DIN-certified reactor systems for chemical end users, while pharmaceutical-grade vessels with USP Class VI compliance capture margin premiums. Price differentiation hinges on certification tier and after-sales service bundling, with unbundled inspection subscriptions compressing upfront capital outlays. Cost compression in standard-grade tanks intensifies as regional fabricators compete on re-enameling turnaround speed. Mid-scale specialty chemical producers exhibit highest price sensitivity, whereas API manufacturers prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
CE marking and BIS IS 4682 certification gating restricts qualified supplier pools to furnace operators with demonstrated thermal shock protocol compliance. Captive enameling capacity concentrates in India, Germany, and China, drawing from borosilicate glass feedstock and specialized steel substrate suppliers. Single-source vulnerability around qualified glass-to-metal fusion technicians constrains repair throughput during demand spikes. Distribution runs through EPC contractor channels for industrial installations and direct OEM relationships for modular pharmaceutical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive enameling furnace control separates sustainable margin positions from commodity fabrication exposure.
For Market Incumbents: To counter PTFE-lined equipment cost advantages in low-concentration acid applications, fortify position through backward integration into borosilicate glass feedstock supply and expand captive furnace capacity in Western India's chemical corridor. Anchor regional supply security by qualifying secondary repair technician pipelines under BIS IS 4682 protocols. For New Entrants and Emerging Players: Modular skid-mounted system demand among contract development and manufacturing organizations offers the most penetrable entry vector. Target pharmaceutical aseptic processing applications with standardized reactor geometries that compress facility validation timelines. Differentiate through predictive maintenance subscription bundling rather than capital equipment pricing alone. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated furnace operators with established CDSCO compliance track records in India. Long-term viability rests on enameled containment durability advantages over polymer alternatives under tightening emission frameworks. Watch for MEE enforcement acceleration in China as inflection signal for capital reallocation toward extended-service-life assets.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Furnace Capacity Expansion | GMM Pfaudler's Western India infrastructure anchors regional supply security against import dependency. |
| Modular Skid-Mounted System Development | DE Dietrich's QVF lineage enables rapid pharmaceutical facility reconfiguration under CDSCO mandates. |
| Predictive Maintenance Platform Integration | IoT sensor networks compress unplanned downtime for asset-intensive chemical operators in Gujarat. |
| DIN-Certified Geometry Specialization | Thaletec's precision positioning preempts REACH-driven fluoropolymer substitution in European fine chemicals. |
| Re-Enameling Service Unbundling | Discrete inspection subscriptions reduce vendor dependency for mid-scale specialty chemical producers. |
Research Methodology
SEC 10-K filings, CDSCO regulatory submissions, and ACC/Cefic chemical industry reports formed the secondary backbone, cross-referenced with primary interviews across plant engineers at specialty chemical facilities, procurement leads at pharmaceutical CDMOs, EPC contractors specifying pressure equipment, and aftermarket service heads managing vessel integrity programs. Bottom-up demand modeling triangulated against top-down production capacity assessments across captive enameling infrastructure.
Historical trendline analysis of reactor fleet expansion patterns and vessel replacement cycles informed projection frameworks across the analysis window, with segmentation modeling covering product architecture, end-use vertical intensity, installation type constraints, and maintenance strategy adoption curves. CAGRs derived from volume-weighted average of segment trajectories, incorporating dual carbon compliance trajectory assumptions and USP Class VI certification timeline inputs.
Revisions become necessary when regulatory enforcement intensity shifts materially alter capital allocation timelines or when furnace capacity expansion announcements change regional supply concentration assumptions. A model refresh is warranted upon material change in MEE emission norm implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Soda Feldspar Market
Glass
GCC Flat Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
United States Flat Glass Market
Glass
Global Self-Cleaning Glass Market
Glass
Glass Product Market
Glass
Glass Mat Thermoplastic Market
Glass
Glass Block Market
Glass
North America Industrial Silica Sand Market
Glass
Foam Glass Market
Glass
Glass Recycling Market
Glass
Low-E Glass Market
Glass
Low Temperature Laminated Glass Market
Glass
Global Scratch Resistant Glass Market
Glass
Glass Alternative Materials Market
Glass
Global Vitrification Market