
 Global Self-Cleaning Glass Market | 2026-2036
Global Self-Cleaning Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self-Cleaning Glass Market Foresight
Aftermarket coating services is tilting margin pools away from commodity flat-glass production toward value-added surface engineering. Saint-Gobain leverages its integrated R&D footprint across France and Germany to dominate photocatalytic formulations. Nippon Sheet Glass anchors Asian supply chains through dedicated hydrophilic production lines in Japan. Guardian Industries competes on manufacturing scale across multiple North American float-glass facilities.
Self-cleaning glass incorporates photocatalytic titanium dioxide or hydrophobic nano-silica surface layers, typically applied via chemical vapor deposition or magnetron sputtering, that decompose organic contaminants or repel water to reduce maintenance cycles on exposed glazing. Photocatalytic glass leads volume given its dual-action decomposition and sheeting behavior, while nano-coated glass represents the fastest-growing technology segment as spray-applied formulations lower retrofit barriers. Hydrophobic glass occupies premium niche positions in transportation vehicles where abrasion resistance commands price premiums.
EPA emissions guidelines for architectural materials, REACH substance restrictions on persistent coatings, and China's GB standards for building energy efficiency collectively shape product certification requirements and market access conditions across major demand centers. The EU Green Deal's embodied-carbon thresholds for construction materials are tightening specification criteria for imported glazing. Stakeholders must monitor divergence between regional nano-material registration protocols to avoid compliance fragmentation in cross-border project bids.
Market Dynamics
Aftermarket coating services are redirecting margin pools from commodity flat-glass production toward value-added surface engineering, as photocatalytic and hydrophilic formulations command specification premiums in high-rise commercial facades.
Growth Catalysts
- REACH substance restrictions:European ECHA mandates on persistent coatings are accelerating substitution toward compliant photocatalytic titanium dioxide formulations, tightening performance standards while expanding addressable applications.
- China's tier-one urban construction:Rapid building activity in Shanghai, Beijing, and Shenzhen combines with acute pollution concerns to drive specification of self-cleaning glazing in commercial and residential towers.
- Nano-silica spray application:Magnetron sputtering advances are lowering retrofit barriers for existing building stock, opening incremental demand channels beyond new construction.
Market Restraints
- Titanium dioxide feedstock concentration:Photocatalytic coating supply chains depend on specialized TiO2 nanoparticle production concentrated in select Asian chemical clusters, exposing buyers to input volatility.
- EU Green Deal embodied-carbon thresholds:Import tightening for construction materials is creating compliance friction for glazing sourced outside European manufacturing footprints.
- Performance degradation in high-abrasion environments:Hydrophilic surface layers exhibit accelerated wear in transportation applications, limiting addressable mobility segments despite premium pricing tolerance.
Strategic Opportunities
- India's building energy efficiency mandates:BIS certification expansion and state-level green building codes are creating first-mover positioning for low-maintenance glazing in commercial real estate development.
- Solar panel integration:Photocatalytic self-cleaning coatings applied to photovoltaic glass surfaces are converging with renewable energy deployment, opening dual-function product architectures.
- EPA emissions guidelines for architectural materials:Federal procurement standards are tilting public building specifications toward certified low-maintenance glazing systems.
Industry Challenges
- Nano-material registration protocol divergence:Cross-border project bids face compliance fragmentation as EU REACH, US EPA TSCA, and China GB standards maintain non-harmonized substance notification requirements.
- Float-glass furnace reconfiguration capex:In-house CVD coating integration demands significant capital redeployment from legacy commodity production lines.
- Photocatalytic performance certification timelines:Third-party validation of decomposition rates and sheeting behavior extends product qualification cycles for new formulation launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self-Cleaning Glass Market |
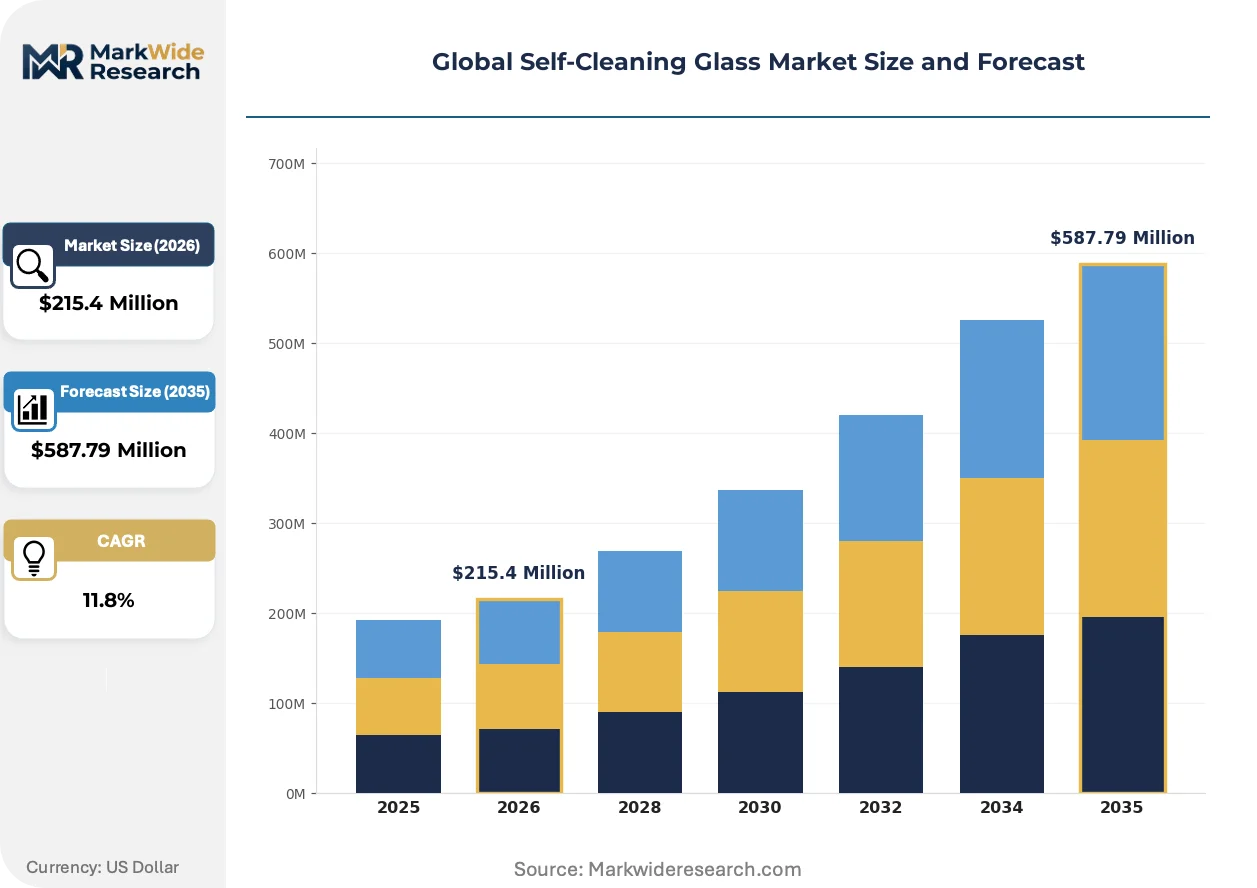
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $587.79 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photocatalytic Glass, Hydrophobic Glass, Hydrophilic Glass, Nano-Coated Glass Technology: Titanium Dioxide, Silicon Dioxide, Zinc Oxide, Silver Nanoparticles Application: Commercial Buildings, Residential Complexes, Transportation Vehicles, Agricultural Structures End User: Construction Companies, Vehicle Manufacturers, Greenhouse Operators, Infrastructure Developers |
| Companies Covered | AGC Inc., PPG Industries, Saint-Gobain, Cardinal Glass Industries, SCHOTT AG, Nippon Sheet Glass, Pilkington, Vitro Architectural Glass, Guardian Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self-Cleaning Glass Market Shifts & Advancements
Process digitization across coating deposition and quality assurance is compressing development cycles while enabling real-time performance monitoring in installed glazing systems.
Magnetron sputtering control systems is digitizing nano-layer thickness precision, allowing architectural glass fabricators to guarantee photocatalytic performance specifications with batch-level traceability. Major facade contractors in Germany and Japan are mandating digital coating logs as standard deliverables. This transparency requirement is compressing supplier qualification timelines while raising barriers for non-integrated coating service providers.
EU Green Deal embodied-carbon thresholds are tightening specification criteria for imported glazing, forcing non-European manufacturers to establish local float-glass production or forfeit public project eligibility. ECHA is harmonizing nano-material registration with CSRD disclosure requirements. Building developers in France and the Netherlands are prioritizing suppliers with verified lifecycle carbon data.
Building maintenance procurement is unbundling glazing lifecycle contracts from traditional facilities management agreements, creating direct specification relationships between coating technology providers and asset owners. Institutional real estate investors in the United States and United Kingdom are demanding predictive maintenance data streams. This disintermediation favors surface engineering specialists over commodity glass distributors.
Global Self-Cleaning Glass Market Segmentation
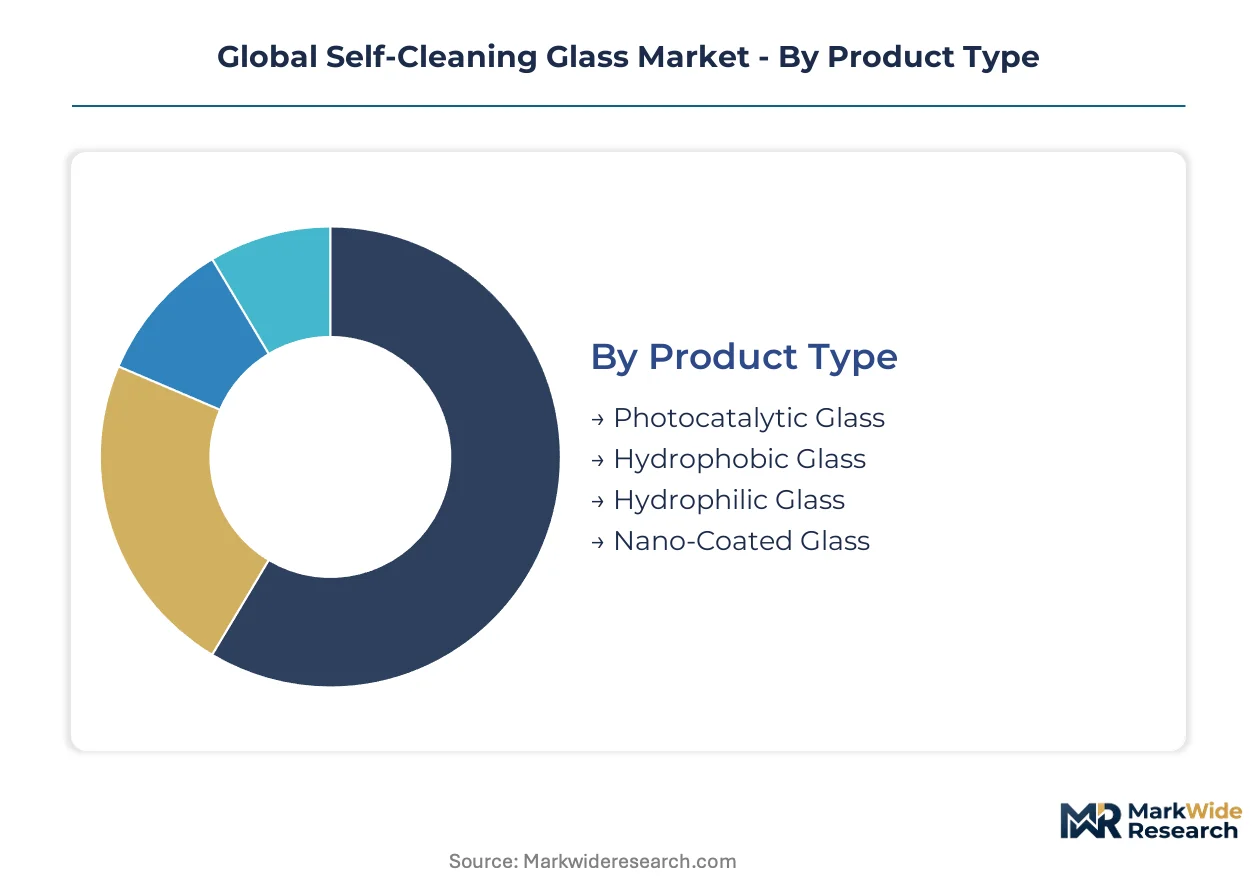
Self-cleaning glass markets fragment across four distinct dimensions that shape procurement patterns and margin capture. Product type determines coating chemistry and performance durability. Technology selection drives raw material sourcing and regulatory compliance pathways. Application context dictates abrasion tolerance requirements and specification standards. End-user category influences contract structure and lifecycle service bundling.
Product Type:
Cost tier separates commodity glazing from premium surface-engineered variants with certified performance guarantees.
- Photocatalytic Glass:Titanium dioxide nanoparticle layers decompose organic contaminants under UV exposure while creating hydrophilic sheeting behavior. Demand concentrates in United States and German commercial high-rises where facade maintenance access costs drive specification. REACH-compliant TiO2 formulations command price premiums over legacy coatings.
- Nano-Coated Glass:Spray-applied silica formulations enable retrofit application to existing building stock without furnace reprocessing. China's tier-one cities are adopting this technology fastest as urban renewal projects outpace new construction permits. Magnetron sputtering advances compress application costs while maintaining optical clarity.
- Hydrophobic Glass:Silane-based nano-silica repels water through high contact angles, suited to transportation applications where abrasion resistance is critical.
- Hydrophilic Glass:Non-photocatalytic water-sheeting variants serve cost-sensitive residential markets with reduced organic decomposition capability.
Photocatalytic glass holds installed capacity. Nano-coated glass is rotating up the share rankings.
Technology:
Raw material chemistry determines coating activation mechanism and environmental persistence profile.
- Titanium Dioxide:Anatase crystal structure delivers optimal photocatalytic activity under solar UV spectrum. ECHA registration requirements for nano-TiO2 tighten supply qualification in European projects. Japanese chemical producers dominate high-purity nanoparticle supply.
- Silicon Dioxide:Hydrophobic and hydrophilic variants derived from organosilane precursors offer broader substrate compatibility. Spray application systems in India and Southeast Asia are adopting SiO2 formulations for cost-sensitive commercial retrofits.
- Zinc Oxide:Alternative photocatalyst with narrower activation spectrum but lower material cost base.
- Silver Nanoparticles:Antimicrobial surface properties supplement self-cleaning function in healthcare and food processing facility glazing.
Titanium dioxide anchors production volumes. Silicon dioxide is gaining application breadth.
Application:
Volume concentration varies sharply by installation height, pollution exposure, and maintenance access economics.
- Commercial Buildings:Curtain wall and skylight specifications in high-rise towers generate the largest addressable volume. Japan's seismic-resistant building codes and Germany's energy efficiency mandates create dual compliance requirements for facade glazing. Predictive maintenance contracts now specify coating performance guarantees.
- Transportation Vehicles:Rail carriage and automotive glazing demand abrasion-resistant hydrophobic formulations. High surface wear rates limit photocatalytic technology penetration despite premium pricing tolerance in luxury vehicle segments.
- Residential Complexes:Mid-rise apartment construction in China's tier-two cities adopts standard hydrophilic coatings for balcony and window applications.
- Agricultural Structures:Greenhouse glazing in the Netherlands and Spain integrates photocatalytic coatings to maintain light transmission under organic dust accumulation.
Commercial buildings command specification authority. Transportation vehicles are expanding addressable use cases.
End User:
Customer type determines procurement sophistication, contract duration, and service bundling expectations.
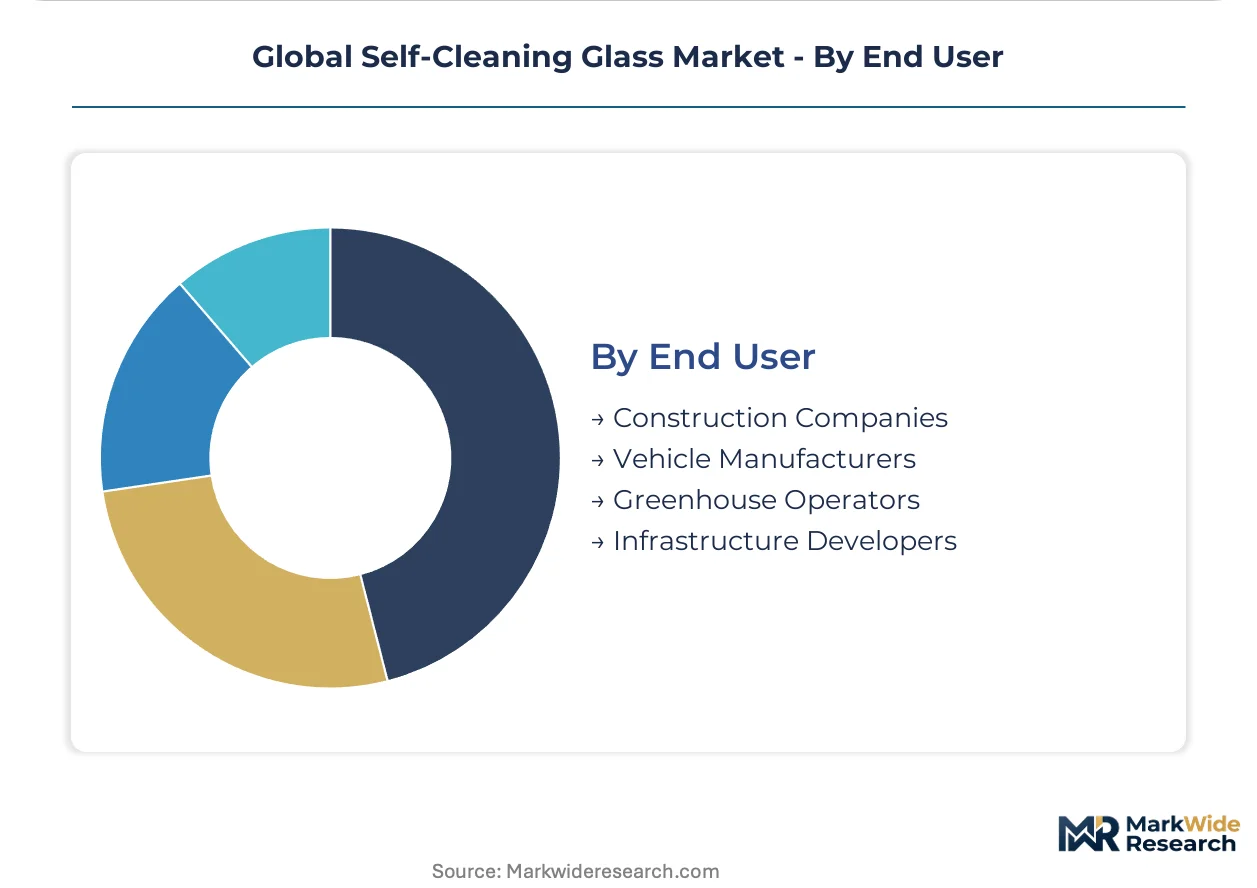
- Construction Companies:General contractors in the United States and United Kingdom are unbundling glazing lifecycle contracts from traditional facilities management agreements. Direct specification relationships with coating technology providers compress distributor margins.
- Infrastructure Developers:Public-private partnership projects in France and the Netherlands prioritize suppliers with verified lifecycle carbon data under EU Green Deal thresholds.
- Vehicle Manufacturers:OEM procurement teams specify hydrophobic coatings for premium vehicle lines with extended surface performance warranties.
- Greenhouse Operators:Agricultural end-users in Spain and Italy evaluate coatings on light transmission maintenance rather than aesthetic cleanliness metrics.
Construction companies hold procurement volume. Infrastructure developers are tightening qualification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's tier-one cities show the highest price elasticity for retrofit nano-coatings, while German commercial developers absorb premium photocatalytic specifications without volume trade-offs. United States infrastructure procurement sits between these poles, with federal standards filtering cost sensitivity.
United States
Commercial high-rise construction in Manhattan and Chicago drives specification of low-maintenance glazing for curtain wall systems. EPA emissions guidelines for architectural materials now mandate certified coatings in federal building projects. Float-glass production clusters in Ohio and Pennsylvania are integrating chemical vapor deposition lines to serve domestic facade demand.
Germany
Energy efficiency mandates under the EU Green Deal tighten embodied-carbon thresholds for imported glazing, favoring local supply chains. ECHA REACH compliance requirements for nano-TiO2 accelerate substitution toward registered photocatalytic formulations. The Rhine-Ruhr industrial corridor hosts integrated R&D facilities linking glass fabrication to coating chemistry development.
China
Rapid urban construction in Shanghai, Beijing, and Shenzhen combines with acute pollution exposure to drive demand for self-cleaning variants. GB standards for building energy efficiency mandate performance certification for facade materials in public projects. Yangtze River Delta manufacturing zones concentrate magnetron sputtering capacity for nano-silica spray applications.
Japan
Seismic-resistant building codes create dual compliance requirements for commercial facade glazing in Tokyo and Osaka. METI industrial standards govern photocatalytic performance testing for architectural materials. Kansai region production lines specialize in hydrophilic coating formulations for high-rise residential towers.
India
BIS certification expansion and state-level green building codes in Maharashtra and Gujarat create first-mover positioning for low-maintenance glazing. Central government procurement guidelines increasingly reference lifecycle maintenance cost reductions. Mumbai-Pune industrial corridor fabricators are adopting spray-applied coating systems for commercial retrofit projects.
Global Self-Cleaning Glass Market Competitive Landscape
Capability concentration sits with integrated chemical-glass conglomerates; scale advantage sits with multi-facility flat-glass producers with coating integration. The market structures around three tiers: multinational material science groups with captive nano-particle supply, regional fabricators with licensed coating technology, and specialized surface engineering service providers. Dominant competitive moves include magnetron sputtering line expansion for retrofit service capacity and strategic partnerships between glass producers and TiO2 nanoparticle suppliers to secure feedstock qualification.
Among Asia-Pacific headquartered glass groups, AGC Inc., Nippon Sheet Glass, and Pilkington occupy positions spanning integrated photocatalytic development to hydrophilic production specialization. AGC Inc. exemplifies the chemical-glass conglomerate archetype with cross-border R&D coordination. Nippon Sheet Glass anchors regional supply chain positioning through dedicated coating line investments. Pilkington represents European-heritage technical glass capability now operating within broader building materials portfolios.
| Leading Market Players |
|---|
| AGC Inc. |
| PPG Industries |
| Saint-Gobain |
| Cardinal Glass Industries |
| SCHOTT AG |
| Nippon Sheet Glass |
| Pilkington |
| Vitro Architectural Glass |
| Guardian Industries |
| Others |
Supply & Pricing Matrix
Japanese chemical producers' dominance in high-purity titanium dioxide nanoparticle supply concentrates margin capture upstream, while coating service providers and architectural fabricators compete for downstream value pools in specification-driven commercial glazing markets.
Pricing Analysis
Aftermarket coating service contracts drive lifetime value capture beyond initial glass sales. Three-tier pricing structure across certified photocatalytic, standard hydrophilic, and economy nano-coated levels separates performance-guaranteed installations from commodity retrofits. Cost compression in spray-applied silica tiers is intensifying because magnetron sputtering equipment costs are declining. Greenhouse operators in Spain and Italy exhibit highest price sensitivity, while German commercial developers absorb REACH-compliant photocatalytic premiums without volume trade-offs.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for imported glazing components. Manufacturing gravity centers on China, Japan, and Germany for coating deposition equipment and formulated nanoparticles. Feedstock supply draws from specialized TiO2 chemical clusters in East Asia and organosilane precursor production in Germany. Single-source vulnerability persists in magnetron sputtering target supply. Distribution runs through facade contractors and specialized coating applicators rather than commodity glass distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial construction cyclicality positions this market for recovery as urban development permits accelerate in tier-one Chinese cities and European green building mandates tighten specification windows.
For Market Incumbents: Entrench specification relationships through predictive maintenance data platforms that institutional real estate investors now demand. Secure captive nanoparticle supply via strategic partnerships with Japanese chemical producers to defend against feedstock volatility. Invest in magnetron sputtering line expansion for retrofit service capacity before spray-applied coating barriers fall further.
For New Entrants and Emerging Players: Build out spray-applied nano-silica service capabilities targeting India's commercial retrofit segment, where BIS certification expansion creates first-mover positioning without furnace reconfiguration capital requirements. Partner with regional glass fabricators in the Mumbai-Pune corridor rather than competing on float-glass production scale.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed coating technology specialists holding digital performance monitoring platforms. Five-to-ten year viability hinges on convergence with photovoltaic glass and embodied-carbon compliance data capabilities. Monitor divergence between EU REACH, US EPA TSCA, and China GB nano-material registration protocols as inflection indicator for cross-border project eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Sputtering Line Expansion | Enables retrofit service capture in China's tier-one urban renewal projects. |
| Backward Integration into Nanoparticle Supply | Secures TiO2 feedstock qualification against ECHA REACH tightening. |
| Photovoltaic Glass Coating Partnership | Captures dual-function demand as solar deployment accelerates. |
| Predictive Maintenance Platform Development | Meets institutional investor data requirements in US and UK markets. |
| EU Manufacturing Footprint Establishment | Preserves public project eligibility under Green Deal embodied-carbon thresholds. |
Research Methodology
Operator-level perspectives from facade contractors, coating applicators, glass fabrication plant managers, and institutional real estate asset managers anchored the qualitative base. Primary interview findings combined with secondary validation from customs trade data, SEC filings of publicly traded glass producers, ECHA substance registration databases, and national building permit records. Bottom-up capacity and demand estimates triangulated against top-down construction spending projections across the analysis window.
Scenario-bracketing framed volume and value outputs across the modeling period, with segmentation dimensions including coating chemistry type, deposition technology, application context, and end-user procurement sophistication. CAGRs derived from installed base growth, replacement cycle analysis, and specification rate penetration modeling. Forecast inputs incorporated magnetron sputtering cost curves and REACH registration timeline assumptions for nano-TiO2 formulations.
Practitioners should monitor nano-material registration protocol divergence, float-glass furnace reconfiguration capex cycles, and third-party photocatalytic performance certification timelines for early signals. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Polishing Powder Market
Glass
North America Flat Glass Market
Glass
Insulating Glass Market
Glass
Glass Like Carbon Market
Glass
Birefringent Crystals Market
Glass
Global Anti-Reflective Glass Market
Glass
Glazing Gel Market
Glass
Optical Glass Market
Glass
Paper Glass Maker Market
Glass
Europe Sapphire Glass Market
Glass
Porous Glass Market
Glass
UAE Silica Sand Market
Glass
Technical Glass Market
Glass
Foam Glass Market
Glass
Glass Product Market
Glass
Advanced Glass Market