
 Laboratory Glass Container Market | 2026-2036
Laboratory Glass Container Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Glass Container Market Analysis
The EU Green Deal is rebalancing procurement priorities across European pharmaceutical laboratories, pushing buyers toward reusable and recyclable borosilicate glass formats. CORNING leverages its fused silica expertise to supply high-purity containers for cell culture applications. DWK Life Sciences anchors its position through extensive European distribution networks for research-grade glassware. Thermo Fisher Scientific competes by integrating container production with its broader laboratory workflow portfolio.
Laboratory glass containers are precision-formed vessels manufactured primarily from borosilicate glass, a thermally stable material containing approximately 80% silica and 13% boron oxide, engineered to withstand thermal shock and chemical corrosion in controlled experimental environments. These containers serve as essential interfaces for sample containment, reaction observation, and sterile storage across quantitative and qualitative analytical protocols. Vials command premium margins within the product type category due to their critical role in pharmaceutical serialization and cold-chain logistics. Borosilicate glass dominates the material landscape owing to its thermal durability and regulatory acceptance for parenteral drug contact. Demand within the diagnostics end-user segment is expanding fastest as decentralized testing networks multiply across healthcare systems.
The FDA enforces strict USP Type I glass standards for pharmaceutical packaging, compelling manufacturers to certify chemical durability and extractable profiles before market authorization. The EPA oversees hazardous waste containment protocols that mandate specific glass thickness and closure integrity for laboratory disposal streams. ISO 719 and ISO 720 standards govern hydrolytic resistance classification, creating tiered product hierarchies that filter market access. Stakeholders must monitor evolving biologic drug formulations that demand novel surface treatments and dimensional tolerances.
Market Dynamics
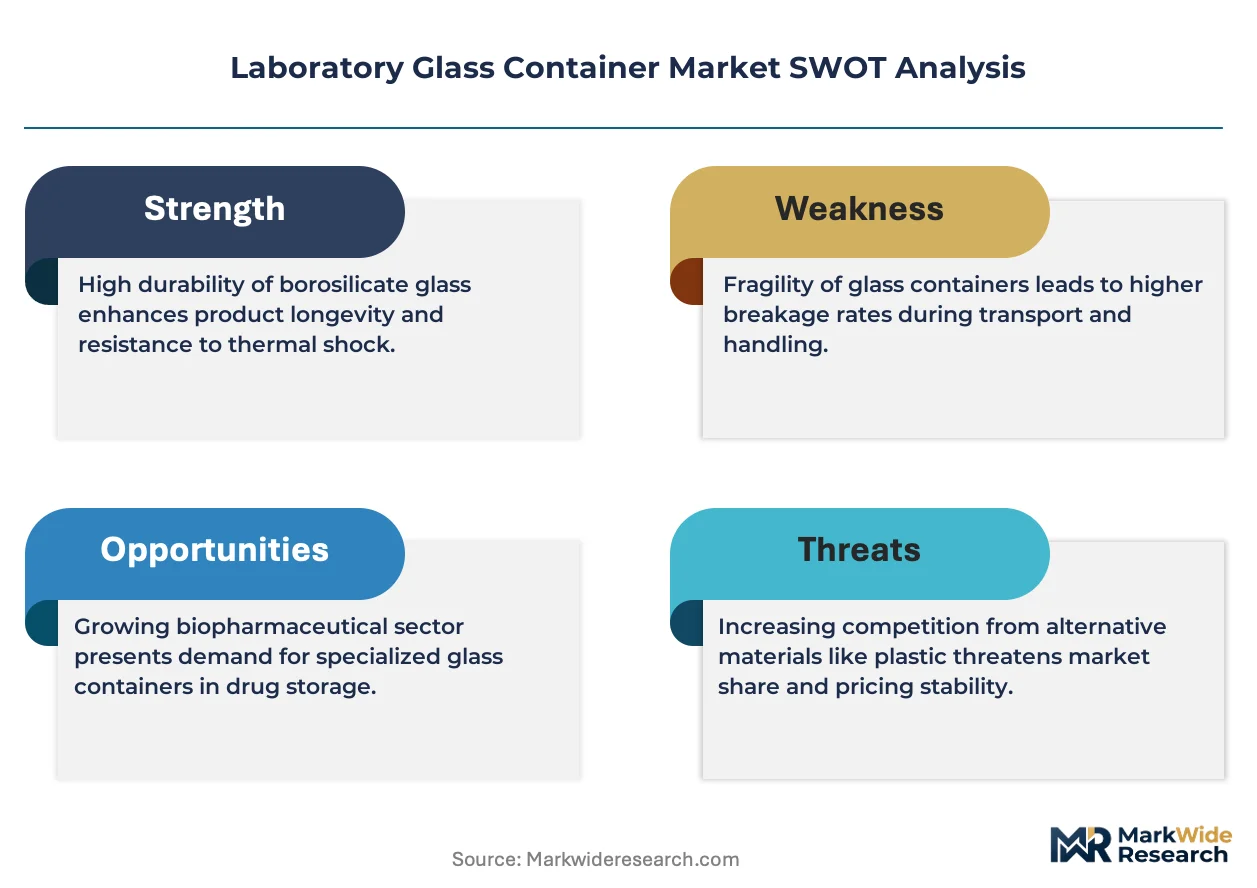
EU Green Deal sustainability mandates are forcing pharmaceutical laboratories to requalify their entire glass container supply chains around recyclability metrics and carbon footprint thresholds, compressing procurement timelines while elevating technical specifications.
Growth Catalysts
- Biologics cold-chain expansion:Cell and gene therapy developers in Germany's Rhine-Main corridor are scaling borosilicate vial volumes for temperature-sensitive drug stability.
- REACH chemical compliance:ECHA substance restrictions on plastic alternatives are redirecting diagnostic manufacturers toward hydrolytic-resistant glass formats for sample integrity.
- Decentralized testing networks:Point-of-care diagnostic facilities across European healthcare systems are multiplying demand for pre-sterilized, single-use glass containers.
Market Restraints
- Boron raw material concentration:Turkey and the United States control over 70% of global boron reserves, creating supply vulnerability for European glass manufacturers.
- Energy cost volatility:Natural gas prices for glass furnace operations in Germany have destabilized production economics for mid-tier suppliers.
- Plastic polymer substitution:Cyclic olefin polymers from Japanese chemical producers are capturing low-risk diagnostic applications through reduced breakage rates.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Czechia offer untapped furnace capacity for serving Central European pharmaceutical clusters with reduced logistics costs.
- Surface treatment innovation:Siliconization and barrier coating technologies are opening parenteral drug categories previously reserved for polymer containers.
- EU CSRD disclosure requirements:Corporate sustainability reporting mandates are creating first-mover advantage for glass suppliers with verified circular economy credentials.
Industry Challenges
- Specialized furnace engineering talent:Europe's aging workforce of borosilicate glass technicians is constraining capacity expansion timelines for precision-formed containers.
- Multi-jurisdiction certification complexity:Simultaneous USP Type I, EP 3.2.1, and ISO 720 compliance testing extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Glass Container Market |
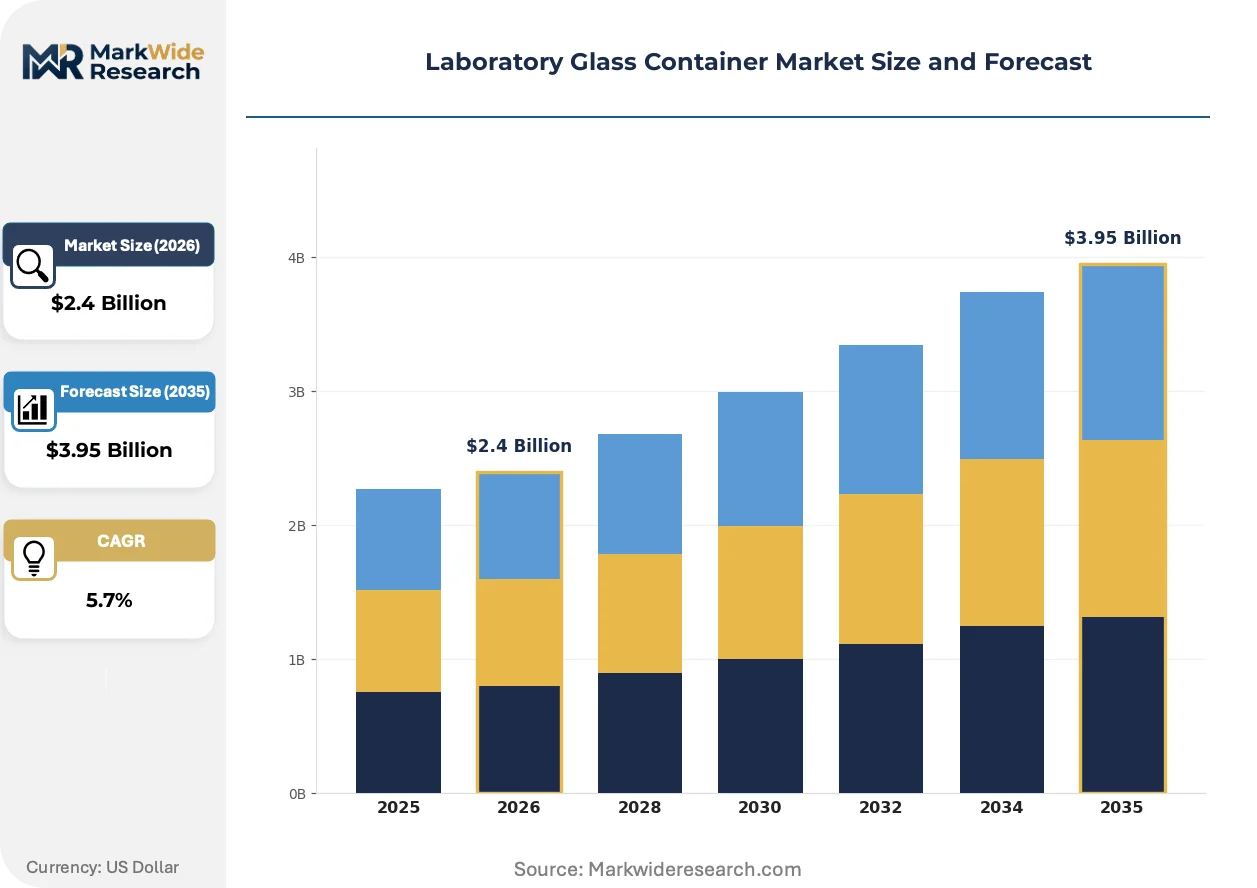
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beakers, Flasks, Vials, Test Tubes Material: Borosilicate Glass, Soda-Lime Glass, Quartz Glass, Glass Ceramics End User: Pharmaceuticals, Biotechnology, Academic Research, Diagnostics Application: Chemical Analysis, Sample Storage, Education, Quality Assurance |
| Companies Covered | CORNING, DWK Life Sciences, Thermo Fisher Scientific, Borosil Scientific, Bellco Glass, Gerresheimer, Merck, Glassco Laboratory Equipments, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Glass Container Market Emerging Trajectories
Digital traceability systems and advanced surface engineering are converging to transform how laboratory glass containers are specified, verified, and integrated into automated pharmaceutical workflows across European manufacturing networks.
Pre-sterilized, ready-to-use (RTU) container formats are consolidating supplier relationships around integrated filling-line compatibility. Major fill-finish contractors in Switzerland and Germany are specifying RTU vials to eliminate in-house washing and depyrogenation steps. This format standardization is consolidating procurement decisions toward vendors with validated sterile supply chains.
EU MDR medical device regulations are tightening extractables and leachables documentation requirements for primary packaging materials. Pharmaceutical sponsors must now submit comprehensive chemical characterization data for glass containers in combination product filings. High-risk parenteral applications are responding by demanding enhanced USP Type I certification with elemental impurity profiling.
Consolidated procurement through group purchasing organizations is displacing direct supplier relationships among mid-sized European research institutions. University hospital networks in France and the Netherlands are centralizing glassware acquisition through specialized laboratory distribution platforms. This channel rationalization is most visible in academic research segments previously served by fragmented local distributors.
Laboratory Glass Container Market Segmentation
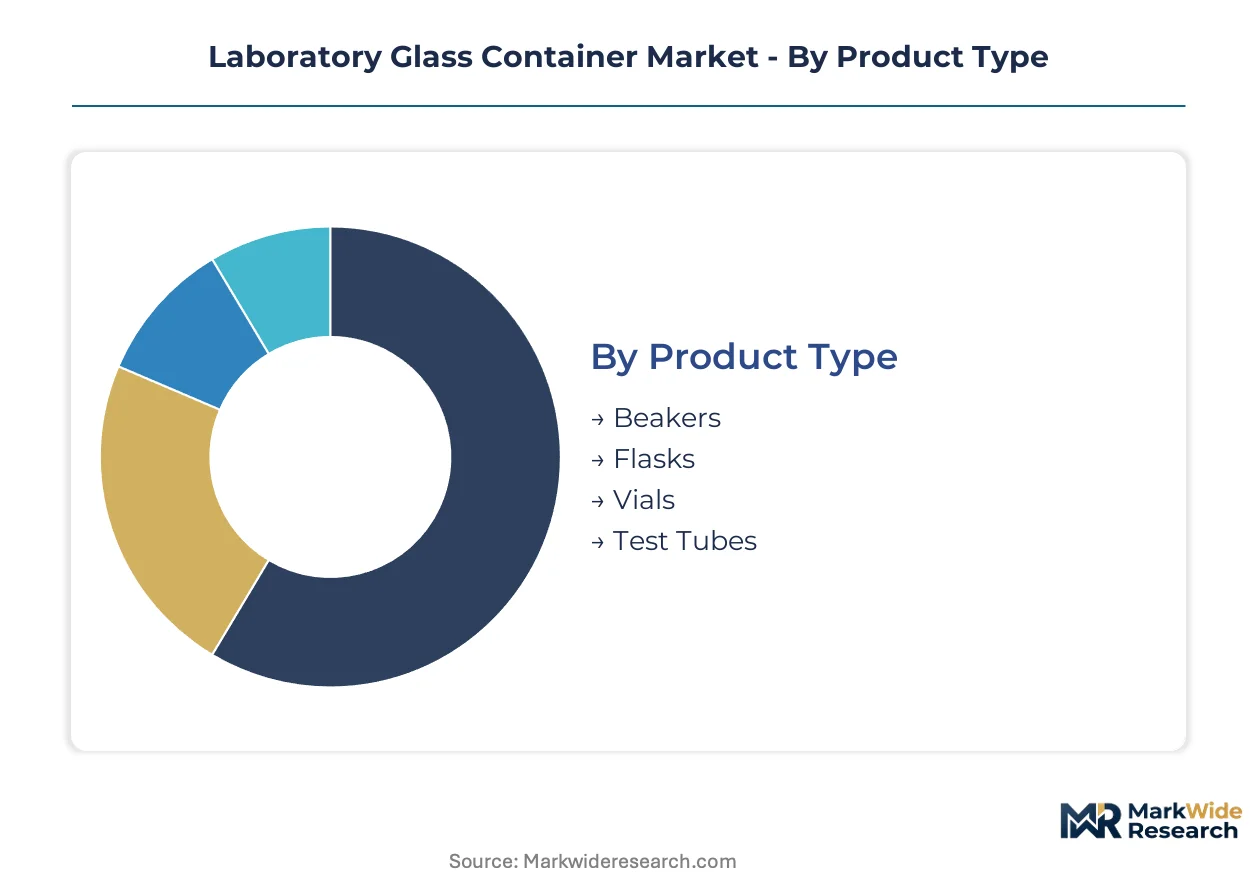
Laboratory glass container purchasing decisions pivot on thermal tolerance specifications, chemical compatibility matrices, and regulatory certification tiers. Pharmaceutical serialization requirements and diagnostic automation protocols create divergent technical demands across segment boundaries.
Product Type:
Dimensional precision and closure integrity specifications vary sharply across vessel geometries, with pharmaceutical cold-chain applications demanding the tightest tolerances.
- Vials:Small-volume cylindrical vessels engineered for parenteral drug containment and serialization compliance. Germany's Rhine-Main pharmaceutical corridor is scaling borosilicate vial procurement for cell therapy stability requirements under EMA cold-chain guidelines.
- Flasks:Erlenmeyer and volumetric configurations with standardized neck dimensions for stirrer and stopper compatibility. Academic research networks in France and the Netherlands are consolidating flask procurement through centralized laboratory distribution platforms.
- Beakers:Cylindrical vessels with pour spouts and graduated volume markings for mixing and heating operations.
- Test Tubes:Narrow cylindrical formats for qualitative analysis and culture propagation in high-throughput screening workflows.
Vials lead on scale; test tubes lead on momentum.
Material:
Raw material selection traces directly to thermal shock resistance requirements and hydrolytic durability classifications under ISO 719 and ISO 720.
- Borosilicate Glass:Silica-boron oxide composition delivering thermal shock resistance and USP Type I certification for parenteral contact. REACH chemical compliance mandates from ECHA are redirecting diagnostic manufacturers toward this hydrolytic-resistant format.
- Quartz Glass:Ultrahigh-purity silicon dioxide for UV transmission and extreme temperature applications. Semiconductor fabrication facilities in Dresden and Leuven specify fused quartz for wafer processing contamination control.
- Soda-Lime Glass:Cost-efficient sodium-calcium-silicate formulation for educational and non-reactive storage applications.
- Glass Ceramics:Controlled crystallization products combining glass formability with ceramic mechanical properties.
Borosilicate glass commands the revenue base; quartz glass is climbing the fastest.
End User:
Procurement sophistication escalates from educational volume purchasing to pharmaceutical qualification protocols with extractables documentation.
- Pharmaceuticals:Fill-finish contractors and drug sponsors requiring USP Type I certification with elemental impurity profiling. Swiss and German fill-finish operations are specifying ready-to-use formats to eliminate in-house depyrogenation.
- Diagnostics:Decentralized testing networks and centralized laboratories demanding pre-sterilized single-use containers. Point-of-care expansion across European healthcare systems is multiplying demand for standardized borosilicate formats.
- Biotechnology:Cell culture and gene therapy developers requiring high-purity vessels with validated surface treatments.
- Academic Research:University and institutional laboratories procuring through group purchasing organizations with cost-optimized specifications.
Pharmaceuticals lead on scale; diagnostics lead on momentum.
Application:
Functional requirements diverge between reactive chemical environments and passive storage conditions with distinct regulatory documentation burdens.
- Sample Storage:Containment protocols for biological and chemical specimen integrity across temperature ranges. EU MDR medical device regulations are tightening extractables and leachables documentation for primary packaging in combination product filings.
- Chemical Analysis:Reaction vessels and titration containers requiring inert surfaces and precise volumetric calibration. Quality control laboratories in Frankfurt and Heidelberg specify borosilicate for corrosive reagent compatibility.
- Quality Assurance:Validation and reference standard containment with chain-of-custody traceability requirements.
- Education:Introductory laboratory instruction with standardized geometries and cost-minimized specifications.
Sample storage leads on scale; chemical analysis leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass manufacturing traces its industrial lineage to early 20th-century German chemical laboratories, where thermal shock resistance first became essential for synthetic chemistry. This German foundation established technical standards that now govern pharmaceutical packaging worldwide.
Germany
Rhine-Main pharmaceutical clusters around Frankfurt and Heidelberg are scaling borosilicate vial procurement for cell therapy cold-chain stability under EMA guidelines. The EU Green Deal is forcing requalification of entire glass supply chains around recyclability metrics. DWK Life Sciences anchors its European distribution networks from manufacturing positions in the region.
United States
FDA enforcement of USP Type I glass standards compels manufacturers to certify chemical durability before pharmaceutical market authorization. The EPA mandates specific glass thickness and closure integrity for laboratory hazardous waste containment. CORNING leverages fused silica expertise from its New York base to supply high-purity containers for cell culture applications.
Switzerland
Swissmedic regulations govern extractables documentation for primary packaging in combination product filings. Major fill-finish contractors are specifying ready-to-use vial formats to eliminate in-house depyrogenation steps. The Basel-Zurich corridor concentrates precision glass demand from biologics manufacturers serving European markets.
China
NMPA oversight of pharmaceutical packaging materials is tightening hydrolytic resistance classification requirements under GB standards. Domestic borosilicate producers are expanding furnace capacity to serve diagnostic manufacturers redirecting from plastic alternatives. Shanghai and Jiangsu province clusters concentrate cell culture vessel demand from expanding biotech R&D facilities.
India
CDSCO pharmaceutical packaging regulations are converging with USP Type I standards for export-oriented drug manufacturers. Borosil Scientific and Glassco Laboratory Equipments anchor domestic production from Mumbai and Delhi-NCR manufacturing bases. REACH chemical compliance from European buyers is redirecting diagnostic manufacturers toward hydrolytic-resistant glass formats.
Laboratory Glass Container Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions in laboratory glass containers. Integrated manufacturers owning furnace assets face competition from specialists outsourcing precision forming to certified foundries. Three archetypes dominate: diversified laboratory conglomerates with workflow integration, pure-play glassware specialists with European distribution depth, and materials science multinationals with fused silica expertise. Competitive moves concentrate on sterile supply chain validation and surface treatment technology licensing.
Among diversified laboratory conglomerates, Thermo Fisher Scientific exemplifies workflow-integrated positioning through captive container production. DWK Life Sciences occupies the European distribution specialist tier with extensive research-grade glassware networks. CORNING represents the materials science archetype, translating fused silica capabilities into high-purity pharmaceutical applications.
| Leading Market Players |
|---|
| CORNING |
| DWK Life Sciences |
| Thermo Fisher Scientific |
| Borosil Scientific |
| Bellco Glass |
| Gerresheimer |
| Merck |
| Glassco Laboratory Equipments |
| Eppendorf |
| Others |
Supply Flow & Price Mechanics
Boron trioxide spot indices from Turkey and the United States cascade through European furnace economics into three distinct pricing tiers for laboratory glass containers, compressing margins for mid-tier suppliers while amplifying premium capture for certified pharmaceutical-grade producers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-certified, research-grade, and educational-economy levels dominates procurement contracts. Price differentiation hinges on USP Type I certification status and volume scale commitments from fill-finish contractors. Pricing pressure stems from natural gas volatility destabilizing German furnace operations. Academic research networks exhibit highest price sensitivity; Swiss biologics manufacturers show lowest.
Supply Chain Analysis
EMA and FDA qualification gating creates 18-24 month certification timelines that filter supplier access to pharmaceutical procurement channels. Manufacturing concentrates in Germany, Switzerland, and the United States for precision-formed containers. Raw material sourcing draws from Turkish boron mines, Ukrainian soda ash, and German silica sands. Single-source vulnerability sits with Turkish boron concentrate dominance. Distribution runs through specialized laboratory supply platforms and direct fill-finish contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Eastern European furnace capacity in Poland and Czechia versus German energy and labor costs, exploiting the EU Green Deal's carbon-border adjustments to reposition production economics.
For Market Incumbents: Acquire Eastern European furnace assets to escape German energy cost volatility while maintaining EU market access. Secure captive boron concentrate offtake from Turkish suppliers to defend against raw material squeeze. Invest in siliconization coating capabilities to capture parenteral drug categories from polymer substitution threats. For New Entrants and Emerging Players: Surface treatment technology-first wedge opens ready-to-use vial segments previously locked by sterile supply chain validation barriers. Target diagnostic decentralized testing networks in France and the Netherlands through group purchasing organization channel partnerships. Pursue toll manufacturing arrangements with certified foundries to bypass 18-24 month qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European glassware specialists possessing validated sterile supply chains but lacking scale capital. Five-to-ten year viability hinges on EU CSRD circular economy credential verification creating acquisition premiums. Watch for REACH chemical compliance expansion triggering diagnostic plastic-to-glass conversion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Concentrate | Turkish mining offtake agreements secure raw material margin control against supply volatility. |
| Surface Treatment Technology Licensing | Siliconization patents from CORNING enable parenteral drug category expansion beyond polymer limits. |
| Eastern European Manufacturing Footprint | Polish and Czechia furnace capacity reduces logistics costs to Central European pharmaceutical clusters. |
| Ready-to-Use Format Standardization | RTU vial compatibility with Swiss and German fill-finish lines eliminates customer depyrogenation capital. |
| EU CSRD Circular Economy Certification | Verified recyclability credentials create first-mover procurement advantage under Green Deal mandates. |
Methodological Framework
Coverage spans Germany, Switzerland, the United States, and China, with primary inputs from each region combining interviews with pharmaceutical packaging engineers, diagnostic procurement managers, glass furnace operations directors, and regulatory affairs specialists. Secondary validation draws from EMA submission databases, FDA packaging guidance documents, ISO standard revision records, and REACH chemical restriction notices. Bottom-up vessel volume estimates triangulate against top-down pharmaceutical production value allocations.
Rate-of-change decomposition separates volume growth from value expansion across material grade tiers, product type geometries, and end-user qualification requirements over the projection horizon. Segmentation modeling incorporates pharmaceutical serialization compliance levels, diagnostic automation compatibility, and regional regulatory cluster stringency. CAGRs derive from fitted trend extrapolation against historical furnace capacity utilization and biologics cold-chain expansion trajectories. Forecast inputs include boron concentrate trade flows and EU carbon border adjustment implementation schedules.
The model holds under stable EMA and FDA qualification timelines; deviation in REACH chemical restriction acceleration or Turkish export policy shifts would revise capacity expansion assumptions. A model refresh is warranted upon material change in EU Green Deal packaging sustainability enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Flat Glass Market
Glass
Metallic Glass Market
Glass
Glass Tableware Market
Glass
Spherical Silica Market
Glass
Double Glazing Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Glass Prepreg Market
Glass
Silica Sand Market
Glass
Recycled Glass Aggregates Market
Glass
Patterned Glass Market
Glass
Glass Recycling Market
Glass
Glass Manufacturing Market
Glass
Glass Polishing Powder Market
Glass
Coated Glass Market
Glass
Technical Glass Market
Glass
Glass Lens Market