
 Glass Mason Jars Market | 2026-2036
Glass Mason Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Mason Jars Market Foresight
REACH compliance is expanding the cost-of-entry calculus for imported glassware into European markets. Ball Corporation leverages its North American manufacturing footprint to sustain domestic supply chain control. Owens-Illinois anchors its position through massive furnace operations that dominate industrial-scale output. Ardagh Group differentiates via specialized decoration capabilities that serve premium cosmetic and gift segments.
Glass mason jars are cylindrical food-grade containers with threaded necks designed for vacuum-sealed preservation, typically manufactured from soda-lime glass in 4-32 ounce capacities using IS machine or press-and-blow forming. Their primary purpose is anaerobic food storage through home canning, commercial pickling, and extended-shelf-life packaging. Wide mouth variants command the strongest growth trajectory as consumers prioritize accessibility for thick preserves and freezer storage. Decorative packaging applications concentrate margin pools through embossed and colored glass finishes that support cosmetic brand differentiation.
FDA food-contact standards govern US jar safety, while ECHA REACH restrictions limit heavy metal content in European-sold glass. The EU Green Deal's packaging reuse targets are pressuring single-use alternatives and reinforcing refillable glass demand. Stakeholders must monitor how evolving extended producer responsibility frameworks reshape cost allocation between manufacturers and retailers.
Market Dynamics
EU Green Deal packaging reuse targets are forcing glass jar manufacturers to redesign for multi-cycle durability while ECHA REACH compliance tightens material traceability, compressing margins for importers and favoring regional furnace operators with captive supply chains.
Growth Catalysts
- Home canning resurgence:Small-batch food artisans in Germany's Rhine-Ruhr cluster and Austria's artisan cooperatives are driving container demand for vacuum-sealed preserves and fermented products.
- REACH compliance expansion:ECHA restrictions on heavy metal content in soda-lime glass are reinforcing demand for certified European furnace output over imported alternatives.
- Wide mouth innovation:Threaded neck redesigns enabling freezer storage accessibility are expanding use cases beyond traditional water-bath canning into meal prep and bulk ingredient storage.
Market Restraints
- Natural gas price volatility:Glass furnace operations depend on natural gas feedstock, with energy input costs representing the dominant share of production economics and creating margin compression during supply shocks.
- Central European supply concentration:Massive furnace capacity clusters in Germany and Czech Republic create geographic vulnerability to single-point disruption from energy infrastructure or logistics constraints.
- Lightweight plastic substitution:Polyethylene terephthalate and polypropylene containers compete for shelf-stable food applications where vacuum sealing is not required, particularly in commercial food service channels.
Strategic Opportunities
- Decorative packaging premiumization:Embossed and colored glass finishes for cosmetic and gift segments command margin pools through brand differentiation in France's perfume packaging corridor and Italy's design-led consumer goods sector.
- Extended producer responsibility frameworks:EU Packaging and Packaging Waste Regulation deposit-return schemes are creating circular economy infrastructure that rewards refillable glass formats with preferential cost allocation.
- IS machine automation convergence:Integration of machine vision quality control with press-and-blow forming is expanding into smaller batch production runs previously uneconomical for industrial-scale equipment.
Industry Challenges
- Specialized furnace operator scarcity:IS machine technicians and glass chemistry specialists with expertise in soda-lime thermal profile management are concentrated among aging workforce cohorts in traditional manufacturing regions.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact validation and ECHA REACH substance dossier preparation extend product launch cycles for exporters serving transatlantic distribution.
- Legacy decoration integration:Specialized embossing and colorant application equipment from prior generation manufacturing lines requires retrofit compatibility assessment with automated forming systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Mason Jars Market |
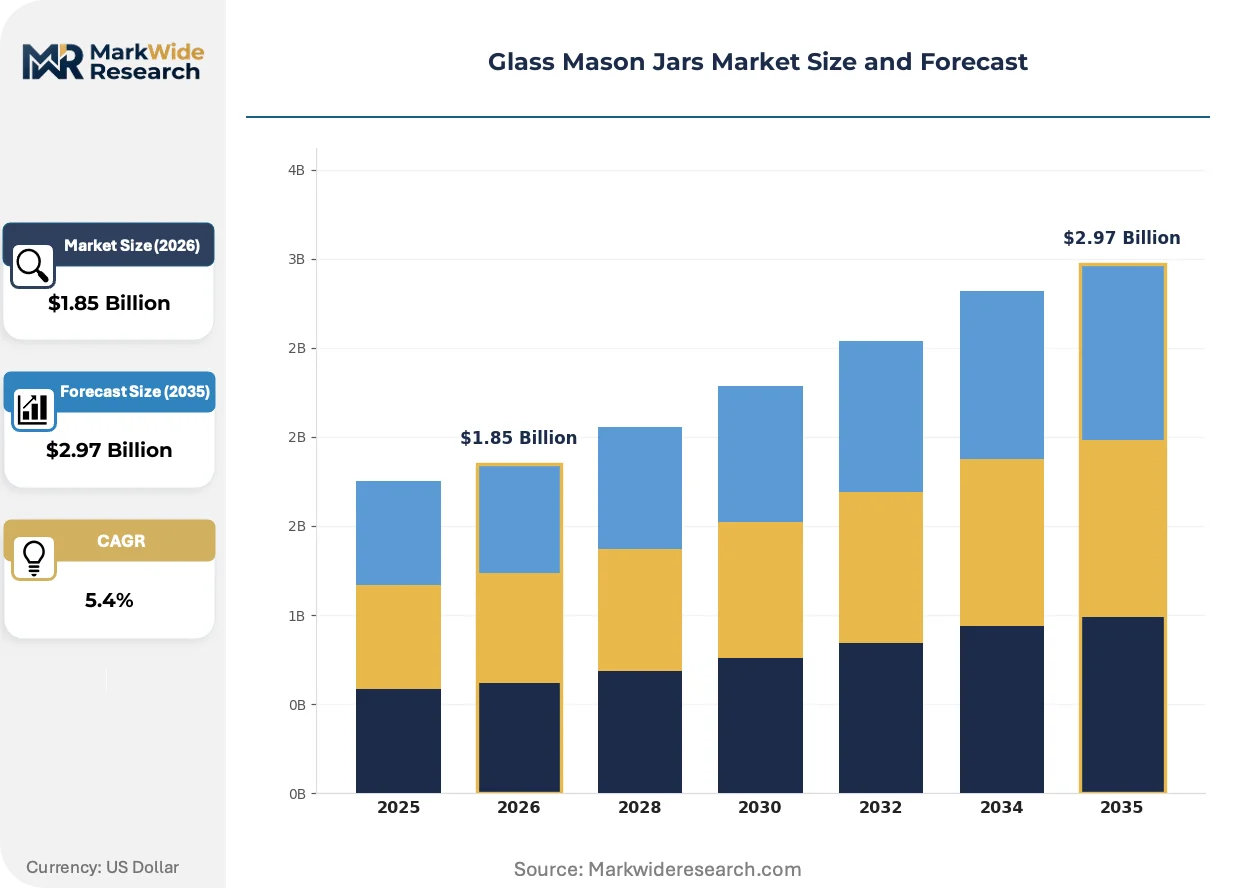
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Mouth, Wide Mouth, Embossed, Colored Glass, Straight-Sided, Bail Application: Food Preservation, Beverage Storage, Decorative Packaging, DIY Crafts, Cosmetic Storage, Herb Keeping End User: Home Consumers, Food Service Providers, Artisans, Retailers, Cosmetic Brands, Event Planners Distribution Channel: Supermarkets, Specialty Stores, E-commerce, Craft Stores, Wholesale Suppliers, Direct Sales |
| Companies Covered | Ball Corporation, Owens-Illinois, Ardagh Group, Verallia, Newell Brands, Anchor Hocking, Libbey, Bormioli Luigi, Kilner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Mason Jars Market Shifts & Advancements
Glass mason jar production is experiencing material science advancement alongside regulatory-driven circularity mandates, with automation and buyer behavior shifts converging to reshape competitive positioning across European and North American supply bases.
Recycled cullet integration is expanding into premium jar specifications as furnace operators achieve higher post-consumer glass content without compromising clarity or thermal shock resistance. Cosmetic brands in France and artisan food producers in Italy are adopting these certified recycled-content containers for sustainability messaging. The technology is expanding into price-sensitive segments previously restricted to virgin material formulations.
EU Green Deal packaging reuse targets are mandating minimum recycled content thresholds and establishing harmonized extended producer responsibility cost allocation across member states. Glass jar manufacturers must redesign thread geometries and wall thickness for multi-cycle durability under mechanical washing systems. Central European producers with integrated cullet processing capabilities are capturing preferential positioning under these frameworks.
Direct-to-artisan distribution models are displacing traditional wholesale grocery supply chains for small-batch producers. German kitchenware cooperatives and Netherlands-based specialty retailers are building curated jar assortments with origin-transparent sourcing credentials. This channel rotation is most visible in urban food entrepreneurship clusters where packaging provenance supports brand storytelling.
Glass Mason Jars Market Segmentation
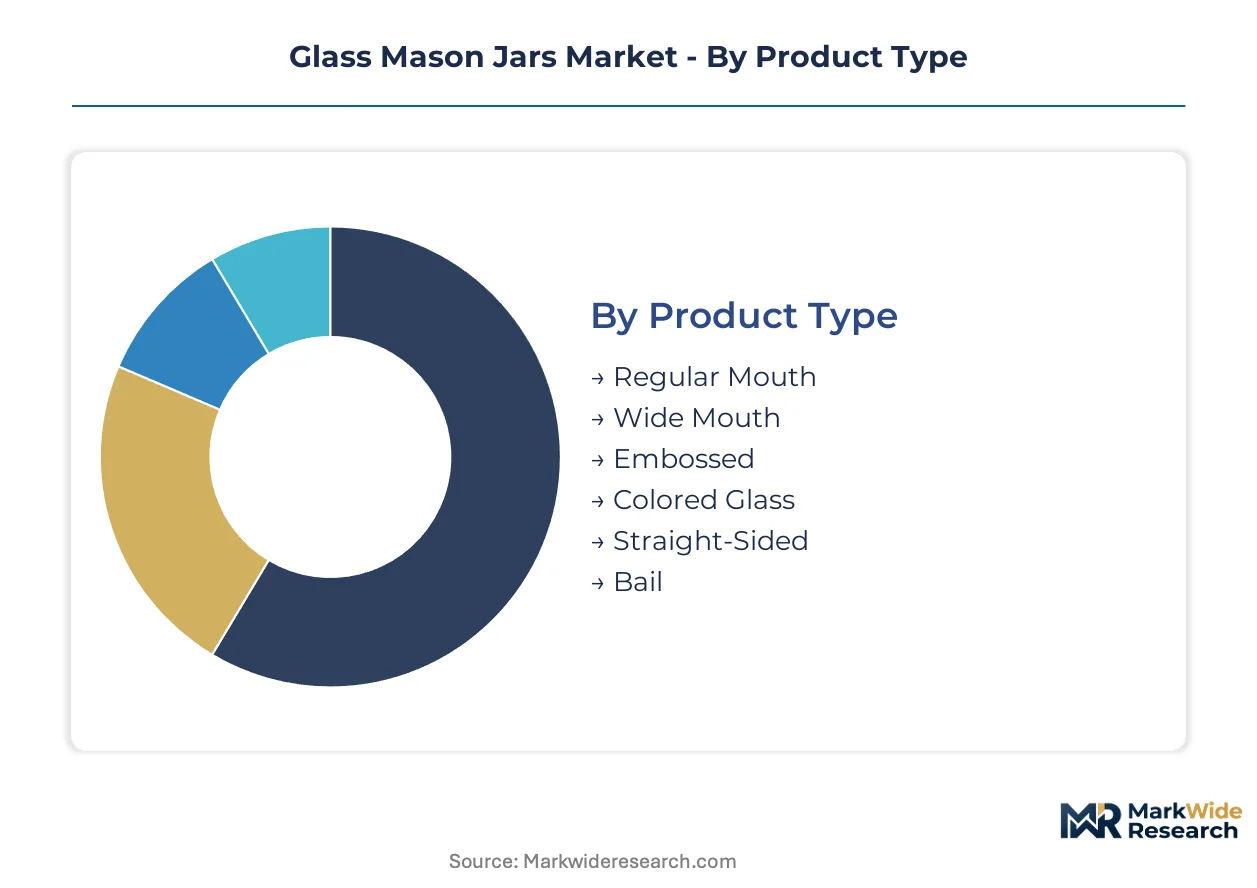
Glass mason jar manufacturers configure production lines around dimensional tolerances and thermal shock specifications that vary sharply across use cases. Segmentation reveals where furnace capacity allocation yields margin premiums versus commodity volume plays.
Product Type:
Customization intensity spans from commodity threaded standards to specialty decorative finishes requiring dedicated colorant chemistry and embossing dies.
- Wide Mouth:Threaded neck diameters exceeding 86mm accommodate frozen foods and thick preserves without thermal fracture. German artisan cooperatives in the Rhine-Ruhr cluster specify these for sauerkraut and kimchi fermentation where accessibility drives repeat purchase.
- Regular Mouth:Standard 70mm neck finish dominates water-bath canning for acidic preserves. Czech furnace operators optimize IS machine throughput around this specification, achieving lowest unit cost through minimal changeover downtime.
- Embossed:Raised surface patterns require specialized mold engraving and extended cooling profiles. Cosmetic brands in France's perfume packaging corridor commission custom embossing for gift-market differentiation.
- Colored Glass:Cobalt, amber, and green tinting demands precise metal oxide dosing in batch mixing. UV-blocking variants serve herb preservation and light-sensitive cosmetic formulations.
- Straight-Sided:Uniform wall geometry maximizes label adhesion and shelf-stacking efficiency. Commercial pickle processors specify these for automated filling line compatibility.
- Bail:Wire closure mechanisms with glass lids target vintage aesthetic segments. Italian design-led retailers stock these for wedding favor and hospitality amenity applications.
Leading the category by volume: Regular Mouth. Growing fastest: Wide Mouth.
Application:
Functional requirements diverge between anaerobic sealing demands and atmospheric storage where decoration drives value.
- Food Preservation:Vacuum-sealed anaerobic storage for shelf-stable fruits, vegetables, and meats. FDA food-contact validation and thermal shock resistance specifications govern jar selection for home canning enthusiasts.
- Beverage Storage:Kombucha, kefir, and cold-brew coffee fermentation requiring pressure-rated seals. Austria's artisan beverage startups specify thick-walled variants for carbonation tolerance.
- Decorative Packaging:Premium gift and cosmetic presentations where glass clarity and embossing quality command price multiples. France's luxury goods houses source certified recycled-content jars for sustainability credentials.
- DIY Crafts:Unfilled containers for candle making, terrarium assembly, and wedding decorations. Netherlands specialty retailers curate origin-transparent assortments for urban craft entrepreneurs.
- Cosmetic Storage:Creams, balms, and scrubs requiring inert glass contact surfaces. REACH-compliant heavy metal limits restrict sourcing to certified European furnace output.
- Herb Keeping:Airtight storage for dried botanicals and spices. UV-amber tinting blocks photochemical degradation in Mediterranean climate conditions.
Dominating volume: Food Preservation. Steepest expansion trajectory: Decorative Packaging.
End User:
Procurement scale and specification complexity separate institutional buyers from fragmented consumer demand.
- Home Consumers:Individual and household purchasers selecting jars through retail and e-commerce channels. German kitchenware cooperatives provide canning education that drives accessory attachment purchases.
- Food Service Providers:Restaurants, cafeterias, and catering operations sourcing bulk quantities for ingredient storage and service presentation. Centralized procurement favors standardized Regular Mouth specifications.
- Artisans:Small-batch producers of preserves, sauces, and fermented goods. Italy's food entrepreneurship clusters prioritize provenance-transparent packaging for brand storytelling.
- Retailers:Private-label and house-brand merchandisers specifying custom embossing and label geometries. Direct-to-artisan distribution models are displacing traditional wholesale grocery supply chains.
- Cosmetic Brands:Skincare and fragrance houses requiring decoration capabilities and batch consistency. France's perfume packaging corridor concentrates demand for premium finishes.
- Event Planners:Hospitality and wedding coordinators sourcing themed containers for favors and table settings. Seasonal demand spikes align with European wedding seasonality.
Highest volume concentration: Home Consumers. Gaining share fastest: Artisans.
Distribution Channel:
Channel selection determines margin capture versus reach tradeoffs and inventory velocity requirements.
- E-commerce:Direct-to-consumer platforms enabling origin-transparent sourcing credentials and educational content. German urban food entrepreneurs discover specialized jar assortments through curated online marketplaces.
- Specialty Stores:Kitchenware and home goods retailers with trained staff providing canning guidance. Austria's artisan cooperatives maintain physical presence for hands-on product evaluation.
- Supermarkets:Mass-market grocery chains stocking commodity Regular Mouth and Wide Mouth variants. Price competition compresses margins for undifferentiated specifications.
- Craft Stores:Hobby and DIY retailers serving candle makers and wedding planners. Seasonal inventory cycles match project-based purchasing patterns.
- Wholesale Suppliers:Industrial distributors serving food processors and food service accounts. Volume commitments secure preferential furnace allocation during capacity constraints.
- Direct Sales:Manufacturer-owned channels bypassing retail markup for institutional buyers. Extended producer responsibility frameworks create circular economy infrastructure rewards for refillable formats.
Channel leader by throughput: Supermarkets. Expanding most quickly: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones attract furnace operators with tax holidays and energy cost subsidies, concentrating Central European glass container capacity near German border markets. These zones anchor regional supply chains serving artisan food clusters across the EU.
Germany
Rhine-Ruhr artisan cooperatives drive vacuum-sealed jar procurement for sauerkraut and kimchi fermentation. ECHA REACH compliance mandates heavy metal traceability in soda-lime glass, favoring domestic furnace output over imports. North Rhine-Westphalia hosts massive IS machine operations supplying Central European food processors.
France
Perfume packaging corridors in Grasse and Paris commission embossed glass for cosmetic gift differentiation. ANSM cosmetic contact regulations align with ECHA substance restrictions, streamlining dual-market certification. Île-de-France luxury goods houses source certified recycled-content jars for sustainability credentials.
Italy
Design-led retailers in Milan and Bologna curate provenance-transparent assortments for urban food entrepreneurs. EU Green Deal packaging reuse targets pressure thread geometry redesigns for multi-cycle durability. Emilia-Romagna's food entrepreneurship clusters prioritize origin credentials in packaging procurement.
United States
Home canning enthusiasts in Appalachian and Pacific Northwest regions sustain seasonal demand spikes. FDA food-contact standards govern jar safety specifications for acidic preserve storage. Ohio and Indiana furnace corridors anchor North American soda-lime glass production.
Czech Republic
Glass furnace clusters near Prague optimize IS machine throughput for Regular Mouth specifications. National environmental regulations align with EU Packaging and Packaging Waste Regulation circularity mandates. Bohemian glassmaking heritage supports specialized decoration capabilities for premium segments.
Glass Mason Jars Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium decoration and compliance-advantaged positions. The vendor base separates into consolidated furnace operators with captive energy contracts and fragmented artisan-scale decorators serving niche cosmetic channels. Three archetypes dominate: industrial-scale container manufacturers, premium decoration specialists, and private-label house-brand suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as energy volatility reshapes location decisions.
Within the industrial-scale tier, Ball Corporation exemplifies North American supply chain control through domestic manufacturing footprints. Owens-Illinois occupies a position anchored by massive furnace operations serving volume-driven food preservation segments. Ardagh Group represents the premium decoration specialist archetype, with capabilities concentrated in European cosmetic and gift packaging corridors.
| Leading Market Players |
|---|
| Ball Corporation |
| Owens-Illinois |
| Ardagh Group |
| Verallia |
| Newell Brands |
| Anchor Hocking |
| Libbey |
| Bormioli Luigi |
| Kilner |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging reuse targets gate qualified supply and premium-tier pricing access, as furnace operators achieving certified recycled-content thresholds capture preferential positioning under extended producer responsibility frameworks while importers face compressed margins from REACH compliance costs.
Pricing Analysis
Lead-time-driven pricing separates urgent procurement premiums from spot inventory discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with REACH-compliant European furnace output commanding brand premiums over imported alternatives. Cost compression in commodity Regular Mouth specifications is intensifying because Czech operators optimize IS machine throughput for undifferentiated volume. Food service providers exhibit highest price sensitivity, while cosmetic brands in France's perfume packaging corridor show least sensitivity to decoration premiums.
Supply Chain Analysis
Single-source vulnerability sits with Central European natural gas feedstock for glass furnace operations. Manufacturing gravity centers on Germany, Czech Republic, and Poland, where massive furnace clusters draw from silica sand, soda ash, and limestone inputs. Supply chain risk hinges on energy infrastructure disruption given geographic concentration near German border markets. Distribution runs through wholesale suppliers serving food processors, direct-to-artisan channels displacing traditional grocery supply chains, and e-commerce platforms enabling origin-transparent sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with specialized IS machine technician scarcity propping pricing for qualified furnace output.
For Market Incumbents: Hedge energy cost exposure through captive natural gas contracts or renewable furnace feedstock transitions. Defend against lightweight plastic substitution by embedding multi-cycle durability into thread geometry designs. Prioritize vertical integration into cullet processing capabilities to capture circular economy infrastructure rewards. For New Entrants and Emerging Players: Capture white-space in decorative packaging for cosmetic and gift segments where embossing capabilities command margin premiums. Target Italy's design-led retailers and France's luxury goods houses with provenance-transparent sourcing credentials. Pursue direct-to-artisan distribution partnerships bypassing consolidated wholesale channels. For Investors and Strategic Acquirers: ECHA REACH substance dossier preparation backlogs are the leading indicator that certified European furnace capacity will face sustained demand premiums. Long-term viability favors operators with integrated decoration capabilities and circular economy compliance infrastructure. Monitor EU Packaging and Packaging Waste Regulation deposit-return scheme implementation pace as inflection signal for refillable glass format economics.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Cullet Integration | Certified post-consumer glass content meets EU Green Deal thresholds without clarity compromise. |
| IS Machine Automation Convergence | Machine vision quality control expands economical batch production for artisan segments. |
| Direct-to-Artisan Distribution | Curated online marketplaces displace wholesale grocery channels for small-batch producers. |
| Multi-Cycle Durability Redesign | Thread geometry and wall thickness adaptations satisfy mechanical washing system requirements. |
| Extended Producer Responsibility Alignment | Deposit-return scheme participation secures preferential cost allocation for refillable formats. |
Research Methodology
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with furnace operations managers, procurement leads at food processors, decoration equipment specialists, and retail category buyers. Triangulation across bottom-up production capacity assessments and top-down demand segmentation validated volume estimates. Glass container industry reports and ECHA regulatory guidance provided compliance cost benchmarks.
Bottom-up modeling aggregated individual furnace capacity, utilization rates, and product mix assumptions across the projection horizon. Top-down analysis calibrated aggregate market size against end-use consumption patterns in food preservation, beverage storage, and decorative packaging segments. Segmentation dimensions included product type, application, end user, and distribution channel. CAGRs derived from regression analysis of historical production trends against regulatory mandate timelines and energy cost trajectories.
The model holds under stable natural gas supply conditions and gradual REACH compliance phase-in; deviation in energy infrastructure disruption or accelerated ECHA enforcement would shift capacity allocation and pricing trajectories. Forecasts reflect documented assumptions about circular economy infrastructure development pace and artisan segment growth sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Middle-East and Africa Flat Glass Market
Glass
India Flat Glass Market
Glass
Solar Control Glass Market
Glass
Porous Glass Market
Glass
Silica Sand Market
Glass
Global Silicone Structural Glazing Market
Glass
Glass Reactors Market
Glass
Glass Vials Market
Glass
Latin America Flat Glass Market
Glass
Silica Sol Market
Glass
Decorative Glass Market
Glass
Solar PV Glass Market
Glass
Glass Manufacturing Market
Glass
Global Glass Flake Coatings Market
Glass
Shatterproof Glass Market
Glass
Silica Market