
 Polymer Blends Alloys Market | 2026-2036
Polymer Blends Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Blends Alloys Market Analytics
The EU Green Deal's material circularity targets is consolidating demand for recyclable polymer alloys across European automotive supply chains. SABIC leverages its vertically integrated feedstock position to dominate high-heat polycarbonate blends for electric vehicle battery housings. BASF SE anchors its competitive position through specialized compatibilizer chemistry that enables post-consumer recycled content integration.
Polymer blends alloys combine two or more distinct polymers through melt-mixing or reactive extrusion to achieve synergistic properties unattainable by single-resin systems, typically formulated with compatibilizers at 2-10 wt% to stabilize phase morphology. These materials primarily serve industries requiring tailored combinations of impact resistance, chemical resistance, and processability in a single engineering thermoplastic platform. Thermoplastic blends occupy the dominant volume position due to their reprocessability advantage in automotive and electrical applications, while plastic composites command premium positioning where fiber reinforcement delivers structural performance. Injection molding technology leads processing share for complex automotive components, though extrusion sustains growth in packaging sheet and profile applications where line speeds and gauge control drive economics.
REACH in Europe, EPA regulations in the United States, and China's MEE emission standards collectively restrict halogenated flame retardants and mandate recyclability disclosures, forcing reformulation of legacy PVC blends and ABS-PC grades. ECHA's SCIP database requirements for articles containing SVHCs above 0.1% now extend to polymer alloy components in finished goods, creating compliance complexity for compounders serving EU-bound OEMs. Stakeholders must monitor evolving extended producer responsibility frameworks and assess compatibilizer technologies that enable closed-loop recycling without property degradation.
Market Dynamics
Automotive lightweighting mandates and electric vehicle battery thermal management requirements are restructuring polymer alloy procurement priorities across Tier-1 supplier networks. Compatibilizer chemistry advances now enable post-industrial recycled feedstock integration at commercial scale, forcing compounders to reconfigure formulation capabilities.
Growth Catalysts
- EU Green Deal material circularity targets:European OEMs now specify minimum recycled content thresholds for interior and under-hood components, redirecting compounder R&D toward closed-loop compatible alloy systems.
- Injection molding process intensification:Automotive suppliers in Germany and South Korea are adopting multi-material molding cells that demand precisely tailored melt-flow characteristics from polymer blends.
- China's dual carbon goals:Domestic EV manufacturers face binding carbon intensity reduction schedules that favor lightweight thermoplastic alloys over metal alternatives in structural battery components.
Market Restraints
- Styrene and acrylonitrile feedstock volatility:ABS-PC blend margins compress unpredictably when benzene derivative markets tighten, squeezing compounders without backward integration into monomer production.
- Compatibilizer supply concentration:Functionalized polymer additive production clusters in Germany and the United States, creating single-source vulnerability for Asian compounders.
- Halogenated flame retardant phase-out timelines:REACH SVHC restrictions and EPA Significant New Use Rules force rapid reformulation of legacy grades with uncertain phosphorus-nitrogen substitute performance.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for advanced chemistry cell manufacturing create adjacent demand for battery housing alloys among domestic compounders.
- Reactive extrusion-digital twin convergence:Real-time rheology monitoring integrated with predictive morphology modeling enables first-pass qualification of custom alloys without iterative lab trials.
- Japan METI carbon footprint labeling:Mandatory scope 3 disclosure for automotive materials rewards alloy suppliers with verified recycled content and renewable energy processing.
Industry Challenges
- Multi-phase morphology control expertise:The scarcity of polymer physicists capable of predicting compatibilizer efficacy across variable shear histories limits compounder product development velocity.
- ECHA SCIP database compliance:Article-level SVHC tracking requirements for EU-bound components impose data architecture costs that smaller compounders struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Blends Alloys Market |
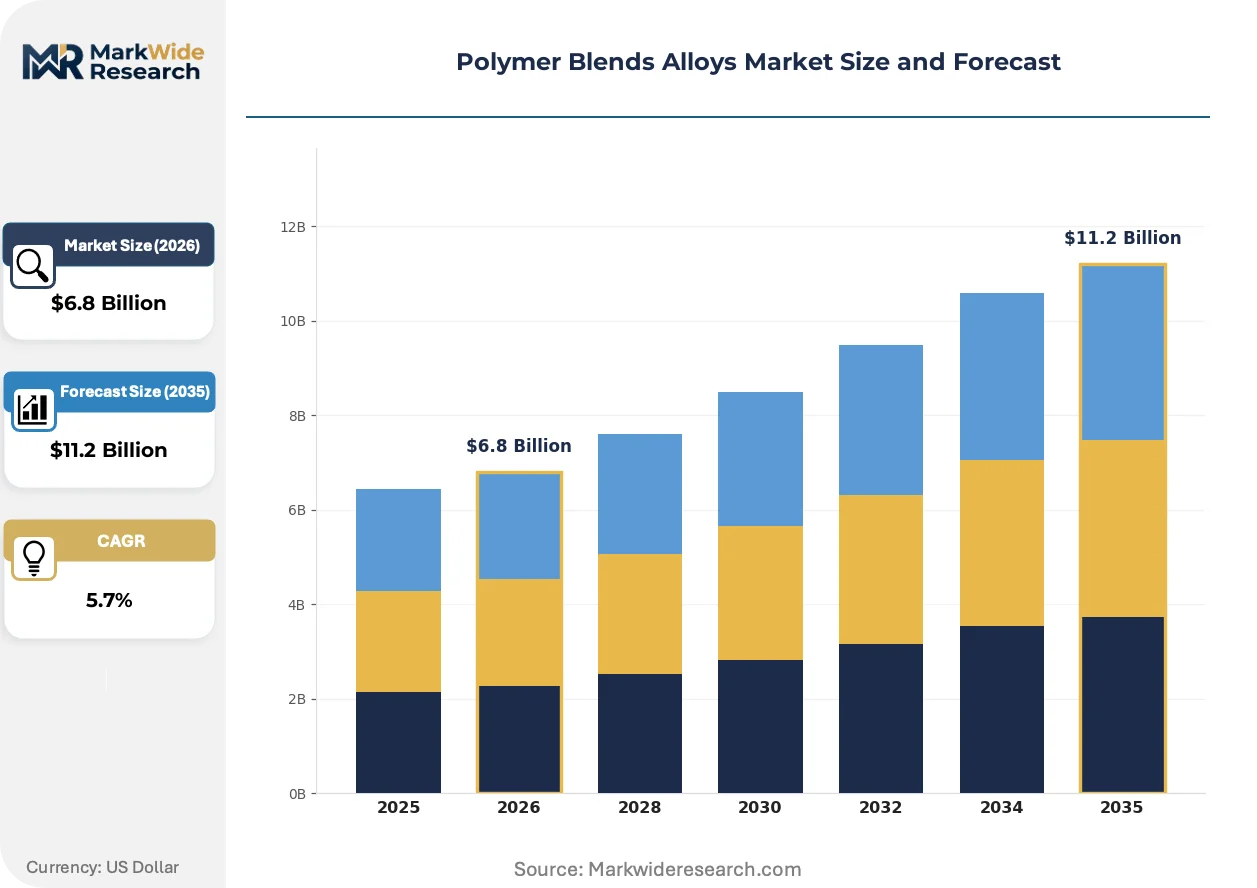
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Blends, Thermoset Alloys, Plastic Composites, PVC Blends Application: Automotive Components, Electrical Insulation, Consumer Goods, Packaging Materials End User: Manufacturers, Retailers, Distributors, OEMs Technology: Extrusion, Injection Molding, Blow Molding, 3D Printing |
| Companies Covered | SABIC, LyondellBasell, BASF SE, Covestro AG, Mitsubishi Engineering-Plastics Corporation, CHIMEI, Daicel Polymer Ltd., Celanese Corporation, LG Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Blends Alloys Market Evolving Landscape
Bio-based monomer feedstocks and reactive processing technologies are converging to enable performance-parity sustainable alloys. Digital manufacturing integration now permits lot-size-one customization previously uneconomical at commercial scale.
Reactive extrusion with in-situ compatibilization is converging with continuous rheological monitoring to produce alloys with tunable phase morphology without batch-to-batch variation. Automotive battery housing manufacturers in South Korea and Germany are piloting these systems for rapid alloy qualification cycles. The technology is compressing development timelines from months to weeks for custom thermal management grades.
REACH SCIP database obligations now extend to polymer alloy components in finished automotive articles, forcing compounders to restructure formulation documentation and supply chain data architectures. ECHA enforcement actions against incomplete SVHC disclosures have accelerated software procurement among European compounders. Battery housing and interior trim suppliers face the steepest compliance cost escalation.
Buyer concentration among consolidated Tier-1 automotive suppliers has compressed switching costs and intensified price transparency. Hyundai-Kia supplier networks in South Korea now mandate open-book cost modeling for polymer alloy procurement, displacing historical arm's-length negotiations. German automotive supply chains exhibit similar contractual evolution, with BASF and SABIC adapting account management structures accordingly.
Polymer Blends Alloys Market Segmentation
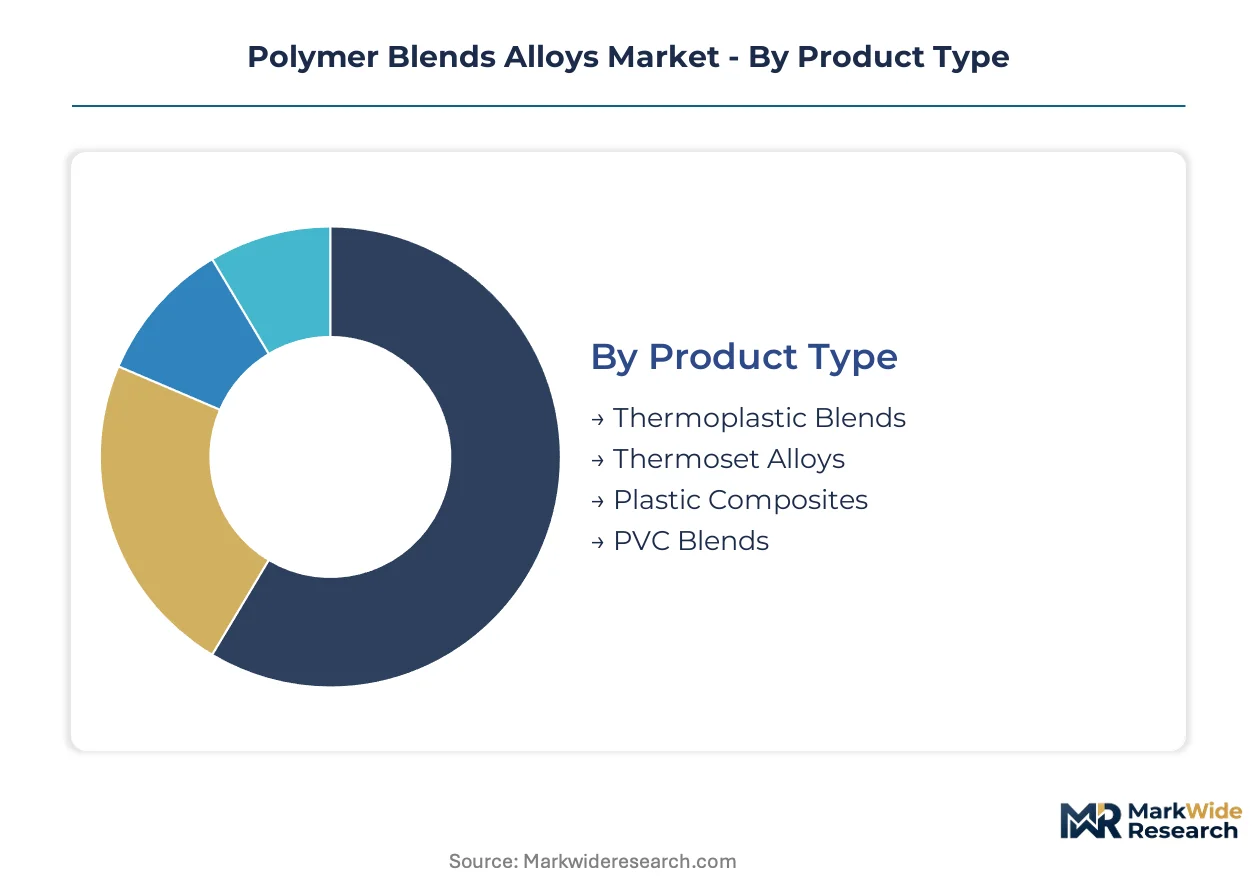
Polymer blend formulations vary sharply in thermal performance and reprocessability, creating distinct procurement criteria across automotive battery housings, electrical enclosures, and consumer durables. Buyers prioritize melt-flow characteristics, flame retardancy ratings, and post-consumer recycled content compatibility when selecting alloy grades.
Product Type:
Cost tier separates commodity compounders from specialty suppliers serving electric vehicle thermal management applications.
- Thermoplastic Blends:Melt-mixable engineering polymers formulated with 2-10 wt% compatibilizers to stabilize phase morphology across polycarbonate, polyamide, and polyester matrices. Procurement concentrates among South Korean Hyundai-Kia suppliers seeking reprocessability for battery housing and interior trim components under tightening carbon footprint disclosure mandates.
- Plastic Composites:Fiber-reinforced alloy systems combining thermoplastic matrices with glass or carbon fiber loadings for structural performance. Demand clusters in German automotive lightweighting programs where multi-material injection molding cells require precisely tailored stiffness-to-weight ratios for under-hood applications.
- Thermoset Alloys:Crosslinked polymer systems delivering dimensional stability at elevated temperatures through irreversible curing chemistry.
- PVC Blends:Legacy chlorinated formulations facing forced reformulation as REACH SVHC restrictions and EPA Significant New Use Rules accelerate halogenated flame retardant phase-out timelines.
Thermoplastic blends lead volumes today; plastic composites are gaining share fastest.
Application:
Volume concentration tracks directly with automotive platform electrification schedules and electrical infrastructure build-out rates.
- Automotive Components:Battery housings, thermal management modules, and lightweight structural elements requiring combined impact resistance, chemical resistance, and processability. German and Japanese OEM procurement is restructuring Tier-1 supplier networks around high-heat polycarbonate blends and post-industrial recycled feedstock integration capabilities.
- Electrical Insulation:Connectors, switch housings, and cable jacketing demanding dielectric stability and flame retardancy without halogenated additives. China's GB standards and EU RoHS compliance are redirecting compounder R&D toward phosphorus-nitrogen substitute systems.
- Consumer Goods:Durable housings and appliance components where aesthetic surface finish and colorability drive specification.
- Packaging Materials:Sheet and profile applications where extrusion line speeds and gauge control determine economic viability.
Automotive components anchor current procurement volumes; electrical insulation exhibits the steepest expansion trajectory.
End User:
Supply chain position determines technical specification authority and formulation customization requirements.
- OEMs:Original equipment manufacturers in automotive and electrical sectors setting material specifications with binding recycled content thresholds and SVHC disclosure requirements. European OEMs under EU Green Deal circularity targets now mandate closed-loop compatible alloy systems with verified post-consumer content.
- Manufacturers:Tier-1 and Tier-2 component fabricators balancing mold-flow optimization against raw material cost volatility in benzene derivative markets.
- Distributors:Inventory-positioning intermediaries serving fragmented processing operations with standard grade availability and technical support.
- Retailers:End-product assemblers with limited formulation influence but growing sustainability specification pressure from private-label commitments.
OEMs command specification authority today; manufacturers are consolidating procurement influence fastest.
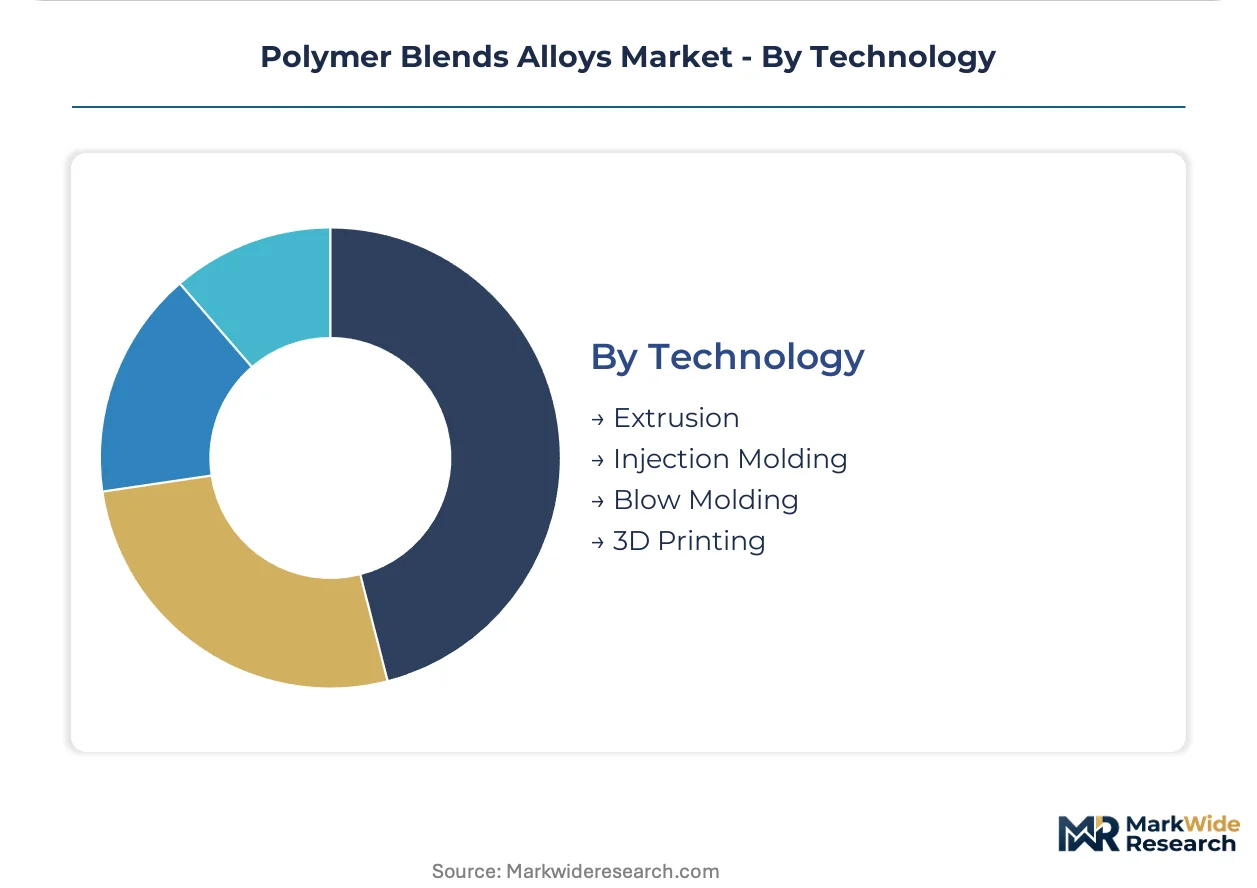
Technology:
Processing method selection constrains allowable melt rheology ranges and dictates compatibilizer chemistry requirements.
- Injection Molding:High-shear processing enabling complex automotive component geometries with multi-material molding cells. German and South Korean suppliers are piloting reactive extrusion-digital twin convergence for rapid alloy qualification without iterative lab trials.
- Extrusion:Continuous processing for packaging sheet and profile applications where real-time rheology monitoring integrates with predictive morphology modeling.
- Blow Molding:Hollow part formation for fluid containment and structural hollow profiles requiring specific melt strength characteristics.
- 3D Printing:Additive manufacturing of polymer alloys with tailored phase morphology for lot-size-one customization previously uneconomical at commercial scale.
Injection molding dominates processing share today; 3D printing is climbing the fastest among emerging technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered engineering thermoplastics commercialization during the 1960s, establishing polymer alloy compounding expertise that subsequently diffused to Japan and South Korea. This historical foundation shapes today's regional procurement patterns and regulatory frameworks.
Germany
Automotive lightweighting mandates from KBA drive specification of high-heat polycarbonate blends for electric vehicle battery housings. REACH compliance and ECHA SCIP database requirements force reformulation of legacy grades with full SVHC traceability. The Rhine-Ruhr industrial corridor hosts concentrated compatibilizer production and Tier-1 supplier development centers.
China
Domestic EV manufacturers under MIIT dual carbon goals specify thermoplastic alloys for structural battery components replacing metal alternatives. GB standards and MEE emission standards restrict halogenated flame retardants across electrical insulation applications. The Yangtze River Delta clusters polymer compounding capacity serving BYD and CATL supplier networks.
Japan
METI carbon footprint labeling mandates scope 3 disclosure for automotive materials, rewarding suppliers with verified recycled content. Polyamide-polyphenylene ether blends anchor thermal management procurement for next-generation battery platforms. The Nagoya-Toyota industrial corridor concentrates reactive extrusion technology development for rapid alloy qualification.
South Korea
Hyundai-Kia supplier networks mandate open-book cost modeling for polymer alloy procurement, displacing historical arm's-length negotiations. MFDS chemical safety regulations align with REACH SVHC thresholds for EU-bound component exports. The Busan-Ulsan petrochemical complex integrates backward into acrylonitrile and styrene monomer production.
United States
EPA Significant New Use Rules accelerate halogenated flame retardant phase-out timelines across electrical enclosure applications. NHTSA fuel economy standards sustain automotive lightweighting demand for glass-filled polyamide blends. The Gulf Coast petrochemical corridor supplies benzene derivatives to compounders serving Detroit automotive supply chains.
Polymer Blends Alloys Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compatibilizer chemistry sophistication and heat-resistance performance tiers. The vendor base organizes around three strategic archetypes: petrochemical majors with captive monomer supply, specialized compounders with reactive extrusion expertise, and regional distributors with formulation customization capabilities. Dominant competitive moves include M&A to secure compatibilizer technology and capacity expansion targeting electric vehicle battery housing grades.
Within the petrochemical-major tier, SABIC and BASF SE exemplify vertically integrated positioning with in-house production of polycarbonate and polyamide feedstocks. Covestro AG anchors the specialty-materials vector through European compounding assets. These three Germany- and Saudi Arabia-originated entities represent divergent geographic footprints while occupying comparable specification authority in high-heat automotive applications.
| Leading Market Players |
|---|
| SABIC |
| LyondellBasell |
| BASF SE |
| Covestro AG |
| Mitsubishi Engineering-Plastics Corporation |
| CHIMEI |
| Daicel Polymer Ltd. |
| Celanese Corporation |
| LG Chemical |
| Others |
Value Network & Pricing Analysis
Styrene and acrylonitrile feedstock costs cascade from benzene derivative markets through three distinct pricing tiers for ABS-PC blends, with South Korean petrochemical complexes leveraging backward integration into monomer production to compress margins for non-integrated compounders serving Hyundai-Kia networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specialty high-heat polycarbonate blends for EV battery housings from commodity-grade ABS-PC formulations and legacy PVC compounds facing forced halogenated flame retardant reformulation. Price differentiation hinges on heat-resistance certification tiers and volume scale commitments, with German automotive OEMs commanding lowest unit costs through consolidated procurement while smaller electrical enclosure fabricators absorb 15-20% premiums for sub-tonnage orders. Cost compression in standard-grade ABS-PC is intensifying because benzene derivative volatility squeezes compounders without captive monomer supply. Tier-1 automotive suppliers exhibit lowest price sensitivity due to specification lock-in, whereas packaging sheet processors demonstrate highest elasticity and rapid grade substitution.
Supply Chain Analysis
Container freight rates from the Rhine-Ruhr industrial corridor to South Korean port complexes add 8-12% landed cost premiums for European compatibilizer imports, reshaping procurement geography for Asian compounders. Supply concentrates in Germany, Saudi Arabia, and South Korea for polycarbonate and polyamide feedstocks, with the Busan-Ulsan petrochemical complex and SABIC's Jubail operations anchoring global resin supply. Raw material dependencies rest on benzene derivatives, functionalized polymer additives, and glass fiber reinforcements. Single-source vulnerability concentrates in German and US compatibilizer production, creating procurement risk for Asian compounders lacking alternative qualified suppliers. Distribution runs through consolidated Tier-1 automotive supplier networks with open-book cost modeling, displacing traditional distributor intermediaries in high-volume automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in high-heat battery housing grades where specification authority rewards compatibilizer chemistry sophistication, while cost-down pressure on commodity ABS-PC blends forces operational excellence investments.
For Market Incumbents: Anticipate accelerated benzene derivative volatility by securing long-term offtake agreements with Saudi and South Korean monomer producers, and defend specification authority in EV thermal management applications through reactive extrusion-digital twin capability investments that compress customer qualification cycles from months to weeks. For New Entrants and Emerging Players: Begin with India's PLI-scheme adjacent battery component market where domestic compounders lack high-heat polycarbonate blend expertise, and penetrate through reactive processing technology licensing partnerships with established automotive Tier-1s seeking rapid localization under carbon disclosure mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where ECHA SCIP database compliance costs exceed smaller European compounders' data architecture absorption capacity, favoring acquisition targets with verified recycled content integration capabilities and renewable energy processing footprints that satisfy Japan METI carbon footprint labeling requirements; watch for inflection when EU Green Deal recycled content thresholds tighten beyond current formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | South Korean and Saudi producers secure feedstock cost stability against benzene derivative volatility squeezing non-integrated compounders. |
| Reactive Extrusion-Digital Twin Convergence | German and South Korean suppliers compress alloy qualification timelines from months to weeks for custom EV battery housing grades. |
| Post-Consumer Recycled Content Integration | BASF's compatibilizer chemistry enables closed-loop recycling compliance with EU Green Deal circularity targets for European OEM procurement. |
| Long-Term Supply Agreement with Tier-1 Automotive | Open-book cost modeling contracts with Hyundai-Kia networks displace arm's-length negotiations and lock in volume commitments. |
| Green Manufacturing Transition | Renewable energy processing investments satisfy Japan METI carbon footprint labeling and European scope 3 disclosure mandates. |
Research Methodology
Direct dialogue with polymer compounding plant managers, Tier-1 automotive procurement leads, compatibilizer R&D directors, and distribution channel partners grounded qualitative insights, validated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemical majors, and ECHA SVHC disclosure databases. Bottom-up alloy grade demand modeling triangulated against top-down automotive production and electrical infrastructure build-out projections.
Segment-level value and volume trajectories across the analysis window reflect structured forecasting frameworks incorporating product type, application, end-user supply chain position, and processing technology dimensions. CAGRs were derived from regression analysis against automotive electrification schedules, regulatory compliance timelines, and feedstock cost assumptions. Industry-specific inputs included KBA lightweighting mandate implementation rates, MIIT dual carbon goal binding schedules, and REACH SVHC restriction phase-out calendars.
Caveats apply where styrene-acrylonitrile feedstock volatility, ECHA enforcement intensity on SCIP database completeness, or unexpected phosphorus-nitrogen flame retardant performance failures could materially shift the outlook; forecasts reflect documented assumptions about regulatory timelines and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Forgings Market
Advanced Alloys
Green Steel Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Global Metal Injection Molding Market