
 Decorative Glass Market | 2026-2036
Decorative Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Glass Market Analysis
REACH compliance is restructuring the cost-of-entry calculus for European decorative glass suppliers by mandating full chemical disclosure across coating and etching chemistries. Guardian Industries leverages captive float-glass capacity to sustain margin control across laminated and tempered product lines. AGC Inc. anchors its competitive position through deep R&D investment in advanced coating technologies for architectural applications. Compagnie de Saint-Gobain dominates premium specification channels through its integrated distribution network spanning fabrication and installation services.
Decorative glass encompasses flat or formed glass substrates that undergo secondary processing—thermal tempering, interlayer lamination, acid etching, ceramic frit printing, or vacuum deposition coating—to achieve aesthetic, safety, or performance functions in built environments and consumer products. Its primary commercial purpose centers on transmitting light while controlling solar gain, ensuring structural safety upon breakage, and enabling architectural expression through color, texture, and pattern. Tempered glass leads volume deployment in high-rise facades where thermal stress resistance and post-breakage fragmentation standards govern specification, while coating technology commands the fastest growth trajectory as low-emissivity and anti-reflective films penetrate both commercial retrofit and premium residential segments. Laminated glass occupies the highest margin pool given interlayer material complexity and specialized autoclave processing requirements that limit commoditization.
The EU Green Deal and REACH frameworks in Europe, alongside the EPA's National Emission Standards for Hazardous Air Pollutants in the United States, collectively tighten scrutiny on melting furnace emissions and coating solvent content, redirecting capital toward electric melting pilots and water-based deposition systems. China's GB standards for building energy efficiency mandate minimum thermal performance thresholds that accelerate coated glass substitution across new commercial construction. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity in incompatible process technologies.
Market Dynamics
Electric melting furnace pilots and low-carbon silica sourcing mandates under the EU Green Deal are redirecting capital away from conventional natural-gas-based float-glass production, compressing the investment horizon for legacy capacity upgrades.
Growth Catalysts
- Commercial tower construction:Megacity development in China sustains large-format tempered and laminated glass orders for high-rise facades and interior partitions.
- REACH chemical disclosure:Full supply-chain transparency requirements across coating and etching chemistries are restructuring competitive entry barriers for European suppliers.
- Laminated interlayer innovation:Advanced polyvinyl butyral and ionoplast interlayers enable structural safety performance that commands specification in premium architectural channels.
Market Restraints
- Silica sand supply concentration:High-purity silica deposits concentrate in limited geographies, exposing float-glass producers to input cost volatility and geopolitical sourcing risk.
- Autoclave processing bottlenecks:Laminated glass manufacturing requires specialized pressure vessel capacity that limits production scale-up and geographic flexibility.
- Flat glass substitution:Advanced polymer panels and translucent concrete systems compete for non-structural daylighting applications in cost-sensitive segments.
Strategic Opportunities
- Saudi luxury hospitality:Giga-project construction across the Middle East expands procurement of decorative facades and ornamental interior glass beyond traditional European supply sources.
- Photovoltaic integration:Building-integrated solar glass converges energy generation with architectural glazing functions, opening new specification channels for coated substrates.
- Digital ceramic printing:High-resolution frit deposition technology enables mass customization of pattern and color without traditional screen-making delays.
Industry Challenges
- Electrical furnace engineering talent:Scarcity of process engineers experienced in all-electric melting transitions complicates pilot-to-production scaling for low-carbon glass lines.
- Multi-jurisdiction certification lag:Divergent thermal performance testing protocols between China's GB standards and European harmonized norms extend product approval timelines for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Glass Market |
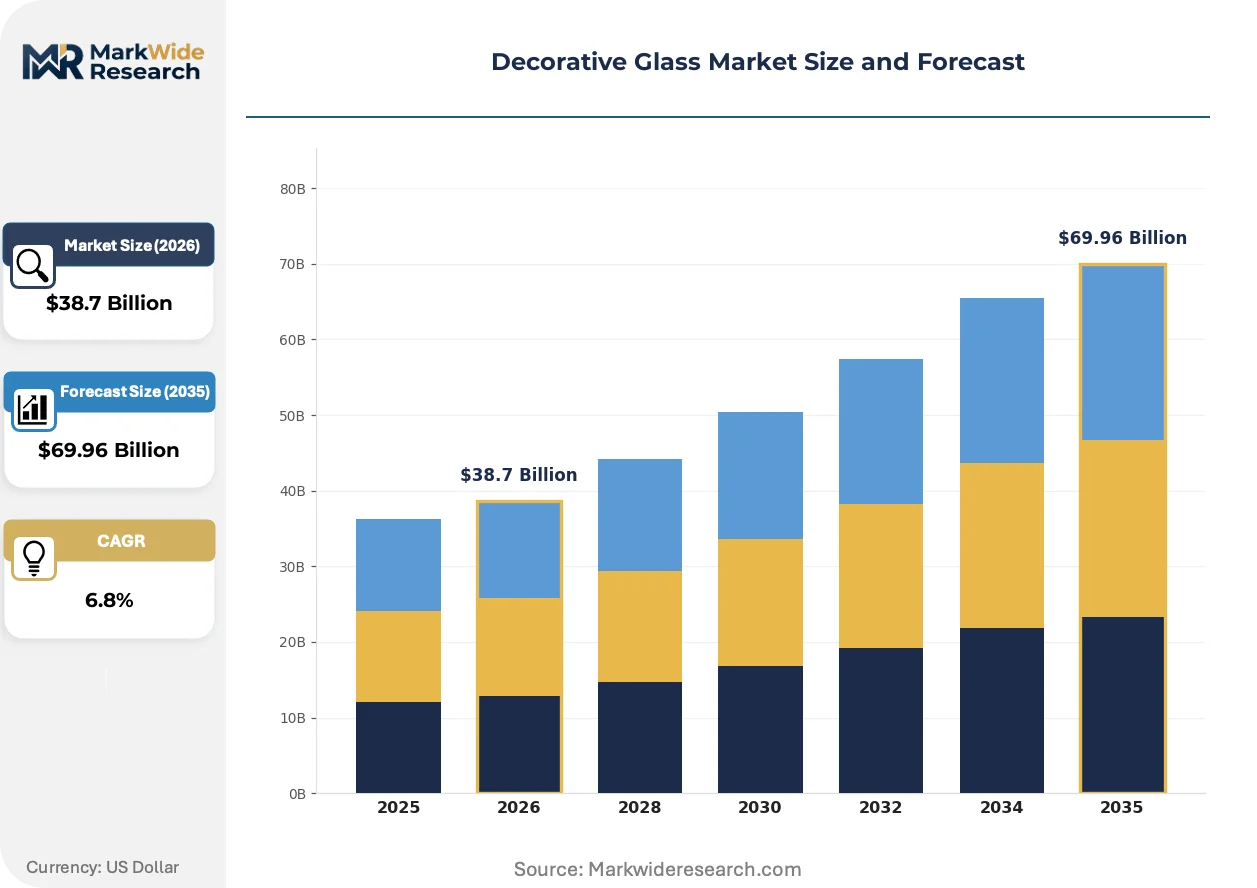
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Annealed Glass, Patterned Glass Application: Architectural, Automotive, Furniture, Art End User: Residential, Commercial, Hospitality, Retail Technology: Coating, Etching, Printing, Sandblasting |
| Companies Covered | Cardinal Glass Industries, Guardian Industries, AGC Inc., Asahi India Glass Ltd, Vitro Architectural Glass, Compagnie de Saint-Gobain, Pilkington, Sisecam Group, Bendheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Glass Market Emerging Trajectories
Vacuum deposition and digital printing technologies are collapsing the traditional separation between commodity float glass and high-value architectural specification products.
Photocatalytic self-cleaning coatings are integrating titanium dioxide nanolayers that decompose organic surface contaminants under UV exposure. Luxury residential developers in Dubai and Riyadh specify these surfaces for tower facades where maintenance access is constrained. The technology is integrating aesthetic performance with operational cost reduction, compressing the traditional trade-off between visual clarity and cleaning expenditure.
China's GB standards for building energy efficiency mandate minimum thermal transmittance values that accelerate low-emissivity coated glass substitution across new commercial construction. Provincial enforcement varies, with Shanghai and Shenzhen adopting stricter local amendments than national baselines. Northern European suppliers with existing magnetron sputtering expertise face compliance adaptation costs to match Chinese testing protocols.
Architectural specification is fragmenting from consolidated general-contractor procurement toward direct fabricator-to-developer relationships. Boutique hospitality and trophy office projects in London and New York increasingly source through design-assist contracts that embed glass specialists early in schematic design. This channel shift compresses the traditional distributor margin stack while rewarding technical consultation capabilities over inventory holding scale.
Decorative Glass Market Segmentation
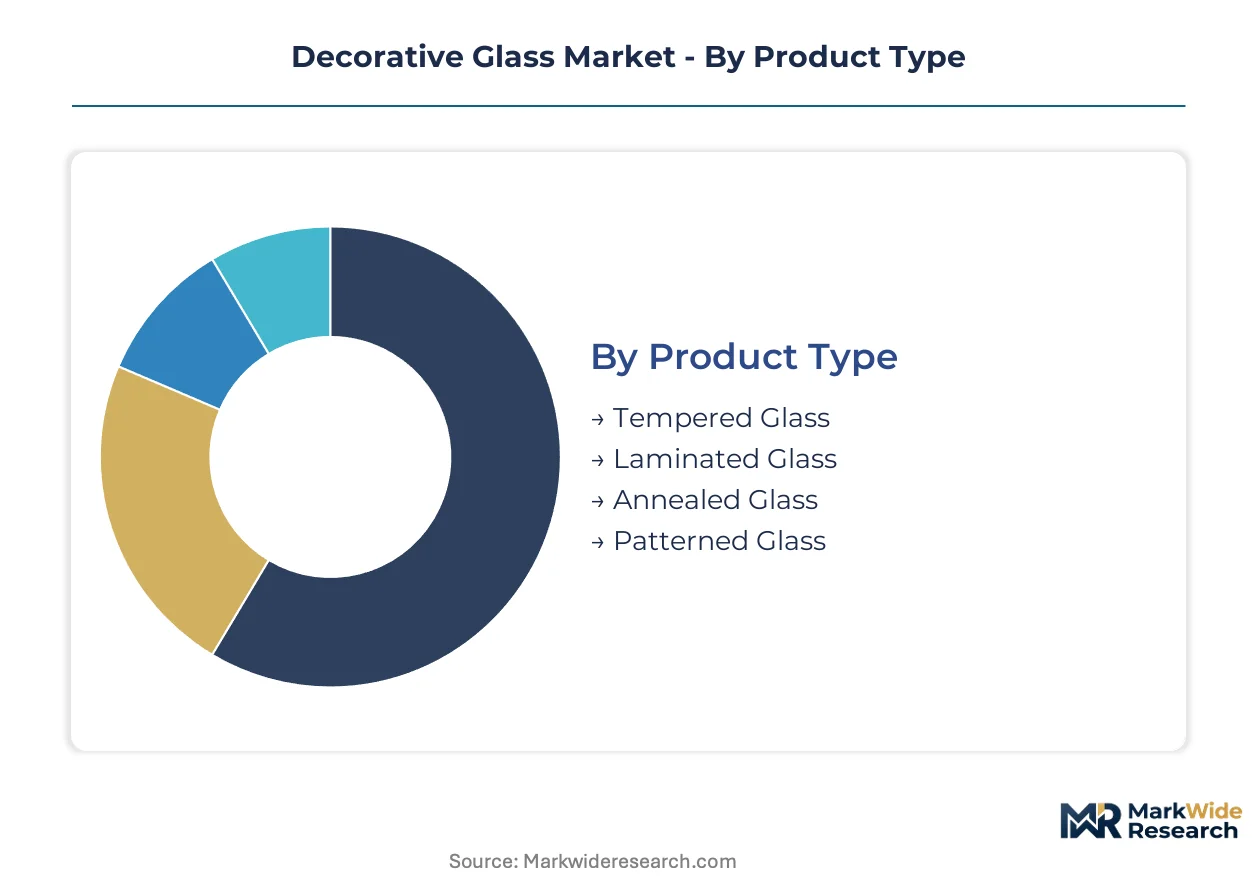
Decorative glass procurement decisions hinge on performance specifications, installation complexity, and lifecycle cost trade-offs. Segmentation reveals how thermal safety requirements, aesthetic customization depth, and end-use durability standards reshape supplier positioning across distinct value pools.
Product Type:
Tempered and laminated variants dominate embedded architectural systems where structural safety codes mandate specific breakage behaviors, while annealed and patterned grades serve more discretionary decorative applications.
- Tempered Glass:Thermal or chemical strengthening creates surface compression that yields granular fragmentation upon breakage, satisfying high-rise facade codes in Shanghai and Dubai megatowers. Demand concentrates in commercial curtain wall specifications where thermal stress resistance and post-breakage safety standards are non-negotiable.
- Laminated Glass:Polyvinyl butyral or ionoplast interlayers bond multiple glass plies to retain post-breakage integrity, commanding premium positioning in overhead glazing and hurricane-resistant applications. Saudi giga-projects specify laminated units for ornamental interior partitions where acoustic dampening and security performance justify extended lead times.
- Annealed Glass:Slowly cooled flat glass retains workability for secondary cutting and edge finishing before tempering or lamination, serving as feedstock for custom fabrication shops.
- Patterned Glass:Rolled or cast surface textures diffuse light transmission for privacy screens and decorative partitions in retail and residential bathrooms.
Tempered glass leads volumes today; laminated glass is gaining share fastest.
Application:
Cost tier differentiation separates specification-heavy built environments from volume-driven consumer products, with architectural and automotive commanding fundamentally different margin structures.
- Architectural:Curtain walls, skylights, and interior partitions in commercial towers and luxury hospitality drive large-format tempered and coated glass procurement. China's GB energy efficiency standards accelerate low-emissivity substitution in new commercial construction across Shenzhen and Beijing.
- Automotive:Windshield and sunroof applications require laminated safety glass with optical clarity specifications that limit supplier qualification to tier-one glass manufacturers with magnetron sputtering capacity.
- Furniture:Tabletops, shelving, and display cases utilize tempered or annealed glass with lower performance thresholds, exposing suppliers to import competition from Southeast Asian fabrication centers.
- Art:Kiln-formed, stained, and leaded glass for decorative installations represents fragmented artisan production with limited scalable manufacturing.
Architectural application dominates revenue contribution; automotive maintains the steepest specification barriers.
End User:
Customer type determines procurement channel structure, with hospitality and retail favoring direct fabricator relationships over distributor-mediated residential volumes.
- Commercial:Office developers specify performance-coated glass through design-assist contracts that embed technical consultation early in schematic phases. London and New York trophy projects compress traditional distributor margins by sourcing direct from specialized fabricators.
- Hospitality:Luxury hotel operators in Riyadh and Dubai prioritize photocatalytic self-cleaning coatings and digital ceramic printing for tower facades where maintenance access constraints elevate operational cost considerations.
- Residential:Single-family and multi-family construction drives standardized tempered and insulated glass units through regional distributor networks with inventory holding scale.
- Retail:Flagship storefronts and shopping mall atriums demand custom-patterned and back-painted glass for brand expression, with shorter runs and higher changeover frequency.
Commercial end use anchors volume demand; hospitality commands the highest value per square meter.
Technology:
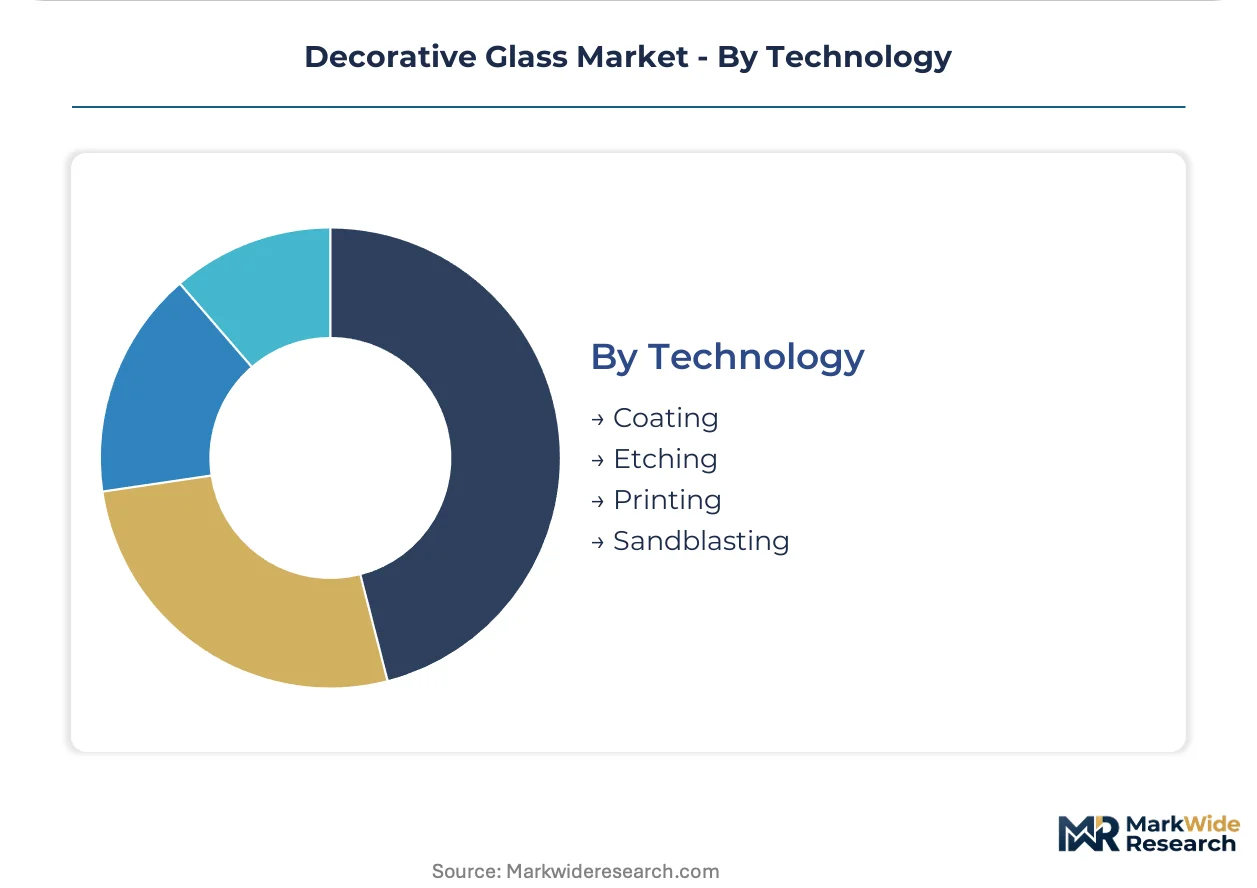
Maturity gradients separate established coating and etching methods from emerging digital processes that collapse customization cost curves.
- Coating:Magnetron sputtering deposits metal oxide layers for solar control and low-emissivity performance, requiring capital-intensive vacuum deposition equipment that limits supplier entry. EU Green Deal embodied carbon requirements redirect R&D toward water-based deposition chemistries.
- Printing:Digital ceramic frit deposition enables mass customization of pattern and color without screen-making delays, compressing lead times for boutique hospitality projects.
- Etching:Acid or abrasive surface treatment creates matte finishes and light-diffusing textures for privacy applications in healthcare and corporate interiors.
- Sandblasting:Mechanical surface roughening produces consistent frosting effects for decorative partitions, with lower capital requirements than chemical etching lines.
Coating technology leads installed capacity; digital printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glass furnace engineers and coating specialists concentrate in Germany's industrial heartland, China's coastal manufacturing belts, and the UAE's emerging technical training hubs. Their expertise anchors regional production capabilities and technology transfer pathways across distinct regulatory environments.
China
Megacity commercial tower development in Shenzhen and Beijing sustains large-format tempered and laminated glass procurement for high-rise facades. GB standards for building energy efficiency mandate minimum thermal transmittance thresholds that accelerate low-emissivity coated glass substitution. The Yangtze River Delta manufacturing cluster houses magnetron sputtering capacity serving both domestic specification and export markets.
Germany
Automotive OEM glass demand from Stuttgart and Munich anchors precision coating and optical clarity requirements. REACH chemical disclosure mandates restructure competitive entry barriers by requiring full supply-chain transparency across coating and etching chemistries. The North Rhine-Westphalia industrial corridor concentrates float-glass heritage and emerging electric melting pilot investments.
United States
Commercial retrofit activity in New York and Chicago drives low-emissivity replacement cycles in aging office stock. EPA National Emission Standards for Hazardous Air Pollutants tighten scrutiny on melting furnace emissions and coating solvent content. The Great Lakes region retains legacy float-glass capacity facing capital redirection toward water-based deposition systems.
Saudi Arabia
Giga-project construction across Riyadh and NEOM expands procurement of decorative facades and ornamental interior glass beyond traditional European supply sources. SFDA and local building codes establish performance benchmarks for structural safety and thermal performance. The Eastern Province industrial zone is attracting foreign fabricator joint ventures to shorten lead times for luxury hospitality specifications.
United Arab Emirates
Luxury hotel construction in Dubai prioritizes photocatalytic self-cleaning coatings and digital ceramic printing for tower facades where maintenance access constraints elevate operational cost considerations. MOHAP technical regulations govern material safety certifications for interior applications. Dubai's Jebel Ali industrial zone hosts regional distribution hubs serving Gulf Cooperation Council specification channels.
Decorative Glass Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value pool segments, creating a tiered structure where scale advantages in raw glass production coexist with customization capabilities in downstream fabrication. The vendor base spans captive float-glass producers, independent coating specialists, and integrated design-assist fabricators. Three archetypes dominate: multinational material conglomerates with captive sand-to-glass supply chains, regional fabricators with deep local specification relationships, and technology-focused coating licensors. Competitive moves concentrate on electric melting capacity pilots and direct-to-developer channel bypass of traditional distributors.
Among multinational material conglomerates, Compagnie de Saint-Gobain and Guardian Industries exemplify the integrated archetype spanning raw glass production through installation services. AGC Inc. occupies a position within the technology-intensive coating tier, its name signaling Japanese industrial heritage and advanced deposition expertise. These three entities anchor distinct competitive vectors: Saint-Gobain through specification channel control, Guardian through captive float-glass margin retention, and AGC through R&D-intensive architectural coating platforms.
| Leading Market Players |
|---|
| Cardinal Glass Industries |
| Guardian Industries |
| AGC Inc. |
| Asahi India Glass Ltd |
| Vitro Architectural Glass |
| Compagnie de Saint-Gobain |
| Pilkington |
| Sisecam Group |
| Bendheim |
| Others |
Supply Flow & Price Mechanics
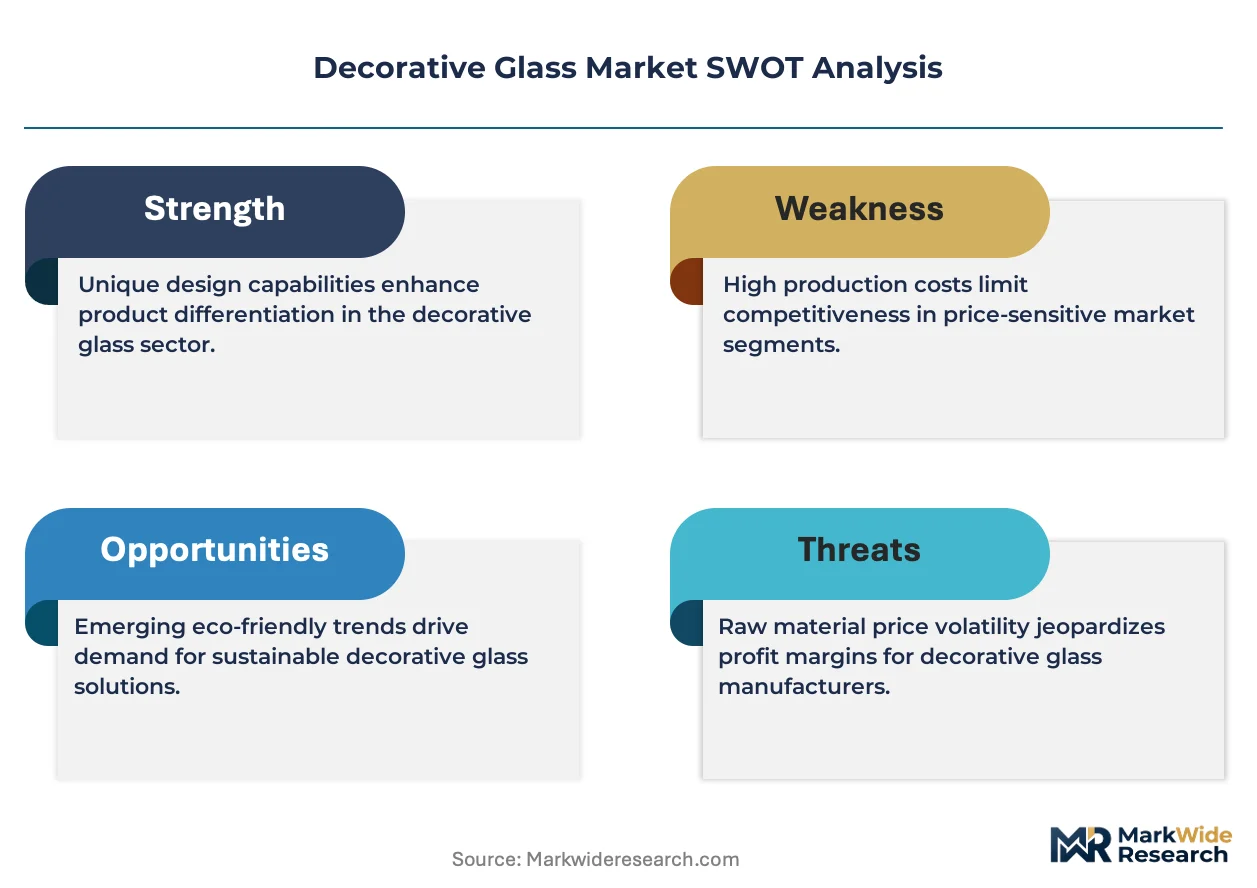
High-purity silica sand spot indices cascade through float-glass production economics, compressing margins for unintegrated fabricators while rewarding captive mining operations with cost buffers against coating and lamination pricing tiers.
Pricing Analysis
Project-based bundled contracts dominate architectural specification, separating design-assist consultation from commodity glass supply. Price differentiation rests on magnetron sputtering certification tiers and autoclave lamination complexity, with premium ionoplast interlayers commanding substantial uplifts over standard PVB. Cost compression in standard tempered segments is intensifying due to Chinese overcapacity exports, while hospitality developers show lowest price sensitivity for photocatalytic self-cleaning facades.
Supply Chain Analysis
CE marking and GB standard dual-certification gates entry into cross-border specification channels, filtering supplier pools before commercial consideration. Float-glass production concentrates in China, Germany, and the United States, drawing from high-purity silica deposits in Australia, Egypt, and the American Midwest. Single-source vulnerability concentrates in specialized autoclave vessels for laminated glass. Distribution runs through design-assist fabricators for trophy projects and regional distributors for residential volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in coating technology premiums and electric melting cost curves, with low-carbon silica sourcing and water-based deposition chemistries driving sustainable cost-down trajectories.
For Market Incumbents: Lock in specification channel control through captive float-glass capacity and direct-to-developer design-assist contracts that bypass traditional distributor margin stacks. Deepen backward integration into high-purity silica mining to buffer input cost volatility, while accelerating magnetron sputtering R&D to defend against polymer panel substitution in daylighting applications. For New Entrants and Emerging Players: Digital ceramic printing technology offers a technology-first wedge into boutique hospitality and retail flagship segments where mass customization commands premium positioning. Target Saudi giga-project procurement channels for ornamental interior glass, leveraging shorter lead times against European supply sources through Jebel Ali regional hub partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with coating technology licensors and electric melting pilot operators positioned for EU Green Deal compliance premiums. Five-to-ten year viability favors fabricators with dual GB-EU certification capabilities. Watch for GB standard enforcement divergence between Shanghai and provincial markets as inflection indicator for Chinese demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Capacity Pilot | EU Green Deal compliance secures specification access in carbon-regulated European markets. |
| Backward Integration into Silica Mining | Captive high-purity sand supply buffers coating margin compression from input volatility. |
| Dual GB-EU Certification Investment | Cross-border testing protocol alignment unlocks Chinese megacity and European trophy projects simultaneously. |
| Digital Ceramic Printing Scale-Up | Mass customization capability captures boutique hospitality procurement shifting from screen-based frit production. |
| Design-Assist Channel Development | Direct fabricator-to-developer relationships compress distributor margins while embedding technical consultation early. |
Methodological Framework
Coverage spans China, Germany, the United States, Saudi Arabia, and the United Arab Emirates, with primary inputs from each market's specification community. Primary interviews with glass fabricator technical directors, architectural specification consultants, hospitality procurement officers, and coating equipment engineers combined with secondary validation from customs trade data, SEC filings of listed glass manufacturers, GB standard enforcement notices, and EU ECHA substance registration databases. Bottom-up project pipeline tracking and top-down production capacity analysis provided triangulation anchors.
Granularity-level modeling distinguished tempered, laminated, annealed, and patterned glass by product type; architectural, automotive, furniture, and art by application; coating, printing, etching, and sandblasting by technology; and commercial, hospitality, residential, and retail by end user across the projection horizon. CAGRs derived from volume-weighted average of segment growth rates, with industry-specific inputs including megacity commercial tower completion schedules, Saudi giga-project procurement timelines, and EU electric melting pilot conversion rates.
The model holds under steady regulatory enforcement trajectories; deviation in GB standard provincial adoption speed or REACH substance restriction scope would shift coating technology substitution curves. Forecasts reflect documented assumptions on silica sand supply concentration and autoclave capacity expansion. A model refresh is warranted upon material change in EU Green Deal embodied carbon threshold implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
3D Glass Substrate Market
Glass
Glass Lined Equipment Market
Glass
Glass Block Market
Glass
Low-E Glass Market
Glass
Soda Feldspar Market
Glass
Global Laminated Glass Market
Glass
Fiberglass Window Market
Glass
Insulated Glass Market
Glass
Advanced Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Double Glazing Glass Market
Glass
Glass Grade Dolomite Market
Glass
Impact Resistant Glass Market
Glass
Global Vitrification Market
Glass
Flexible Glass Market
Glass
GCC Flat Glass Market