
 Europe Laboratory Hoods and Enclosure Market | 2026-2036
Europe Laboratory Hoods and Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Laboratory Hoods and Enclosure Market Foresight
Smart airflow monitoring and IoT-enabled filter diagnostics is rewriting how laboratory hoods are engineered, shifting hardware margins toward predictive service contracts. WALDNER Holding GmbH & Co. KG leverages its Swabian manufacturing base to sustain premium positioning in customized enclosure systems for GMP facilities. Köttermann GmbH anchors its competitive stance through deep specialization in steel-lab furniture integration, while Esco Lifesciences Group differentiates via biological safety cabinet leadership across European cell therapy production sites.
Laboratory hoods and enclosures are ventilated containment devices engineered to capture and exhaust hazardous vapors, particulates, or biological agents through controlled face velocities typically ranging from 0.3 to 0.5 m/s, with construction in epoxy-coated steel, stainless steel, or polypropylene depending on chemical compatibility requirements. Their primary purpose is protecting personnel and maintaining experimental integrity in environments handling toxic, corrosive, or infectious materials. Fume hoods dominate installed base value across chemical handling applications, while biological safety cabinets command margin premiums driven by cell and gene therapy manufacturing scale-up in pharmaceutical companies. Ventilated workstations are gaining share in academic laboratories where flexible reconfiguration outweighs dedicated containment needs.
EMA's Annex 1 revision on sterile manufacturing and the EU Green Deal's energy efficiency mandates are reshaping procurement specifications toward lower exhaust volume designs with heat recovery. ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing material transitions in hood liners and gaskets, compressing supplier lead times for compliant alternatives. Stakeholders must weigh capital replacement cycles against evolving MDR traceability requirements for devices used in diagnostic and therapeutic production environments.
Market Dynamics
EMA's Annex 1 revision on sterile manufacturing is compressing replacement cycles for legacy containment infrastructure across European pharmaceutical production facilities, forcing capital allocation toward validated systems with enhanced environmental monitoring capabilities.
Growth Catalysts
- REACH chemical handling mandates:ECHA restrictions on per- and polyfluoroalkyl substances are accelerating hood liner replacement programs in German and French chemical research facilities.
- Cell therapy manufacturing scale-up:Pharmaceutical companies in Basel and Frankfurt corridors are installing Class II biological safety cabinets at unprecedented density for commercial gene therapy production.
- EU Green Deal energy efficiency targets:Heat recovery ventilation and variable air volume systems are becoming procurement prerequisites in Netherlands and Danish academic construction projects.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet pricing fluctuations are compressing margins for custom enclosure fabricators serving GMP facilities.
- Specialized blower motor concentration:German and Italian motor suppliers control critical components for high-performance fume hoods, creating single-source vulnerability.
- Perfluorinated material substitution timeline:ECHA REACH compliance deadlines for gasket and seal materials are outrunning qualified alternative certification cycles.
Strategic Opportunities
- Central and Eastern European laboratory build-outs:Poland and Czech Republic biotech clusters are greenfield construction markets lacking incumbent supplier relationships.
- Predictive maintenance service contracts:IoT sensor integration enables recurring revenue models displacing transactional equipment sales in Swiss pharmaceutical headquarters.
- EU CSRD reporting alignment:Sustainability disclosure mandates are creating specification advantages for suppliers with embodied carbon documentation in Nordic public procurement.
Industry Challenges
- Containment validation specialist scarcity:Qualified engineers for IQ/OQ/PQ documentation are concentrated in Germany and Switzerland, constraining deployment timelines elsewhere.
- Legacy building HVAC integration:Retrofitting VAV controls into 1980s-era laboratory infrastructure in UK universities requires structural modification beyond equipment replacement scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Laboratory Hoods and Enclosure Market |
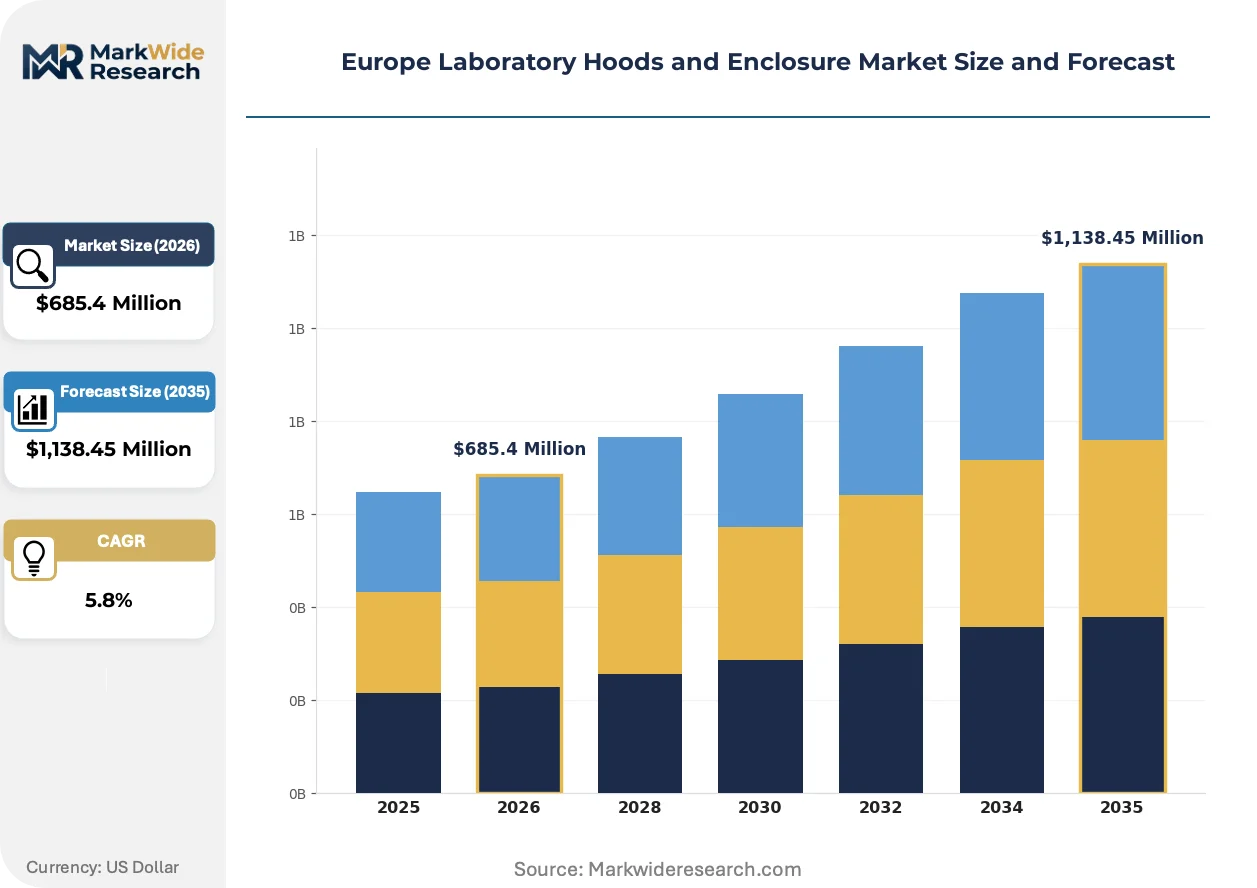
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fume Hoods, Biological Safety Cabinets, Ventilated Workstations, Enclosure Systems End User: Pharmaceutical Companies, Research Institutions, Healthcare Facilities, Academic Laboratories Application: Chemical Handling, Biological Research, Sample Preparation, Environmental Testing Installation Type: Walk-in, Wall-mounted, Portable, Ceiling-mounted |
| Companies Covered | Thermo Fisher Scientific Inc., WALDNER Holding GmbH & Co. KG, Köttermann GmbH, Bigneat Ltd., Esco Lifesciences Group, Monmouth Scientific Limited, Kewaunee International Group, Nuaire, Labconco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Laboratory Hoods and Enclosure Market Shifts & Advancements
Smart airflow architectures are displacing static containment designs across European pharmaceutical and academic installations, shifting competitive advantage from fabrication scale toward embedded sensor analytics and predictive service capabilities.
Computational fluid dynamics simulation software is digitizing hood design validation before physical prototyping, compressing development cycles for custom pharmaceutical containment systems. Swiss and German engineering firms are embedding these tools into client specification workflows, reducing field failure rates for specialized high-containment applications. This capability gap is separating premium enclosure suppliers from commodity fabricators across the European market.
The EU F-Gas Regulation phase-down is accelerating adoption of hydrocarbon-based refrigeration in biological safety cabinets, displacing traditional HFC cooling systems in temperature-controlled containment applications. German laboratory equipment distributors are prioritizing compliant inventory positions ahead of 2027 quota restrictions. Cell therapy manufacturers in the United Kingdom and Netherlands face accelerated replacement timelines for existing installed base units.
Pharmaceutical procurement teams are consolidating vendor relationships around full-lifecycle service accountability, displacing discrete equipment purchasing in favor of performance-guaranteed containment contracts. Academic buyers in France and Belgium retain transactional models, creating a bifurcated channel structure. This divergence is forcing suppliers to maintain dual commercial capabilities across European territories.
Europe Laboratory Hoods and Enclosure Market Segmentation
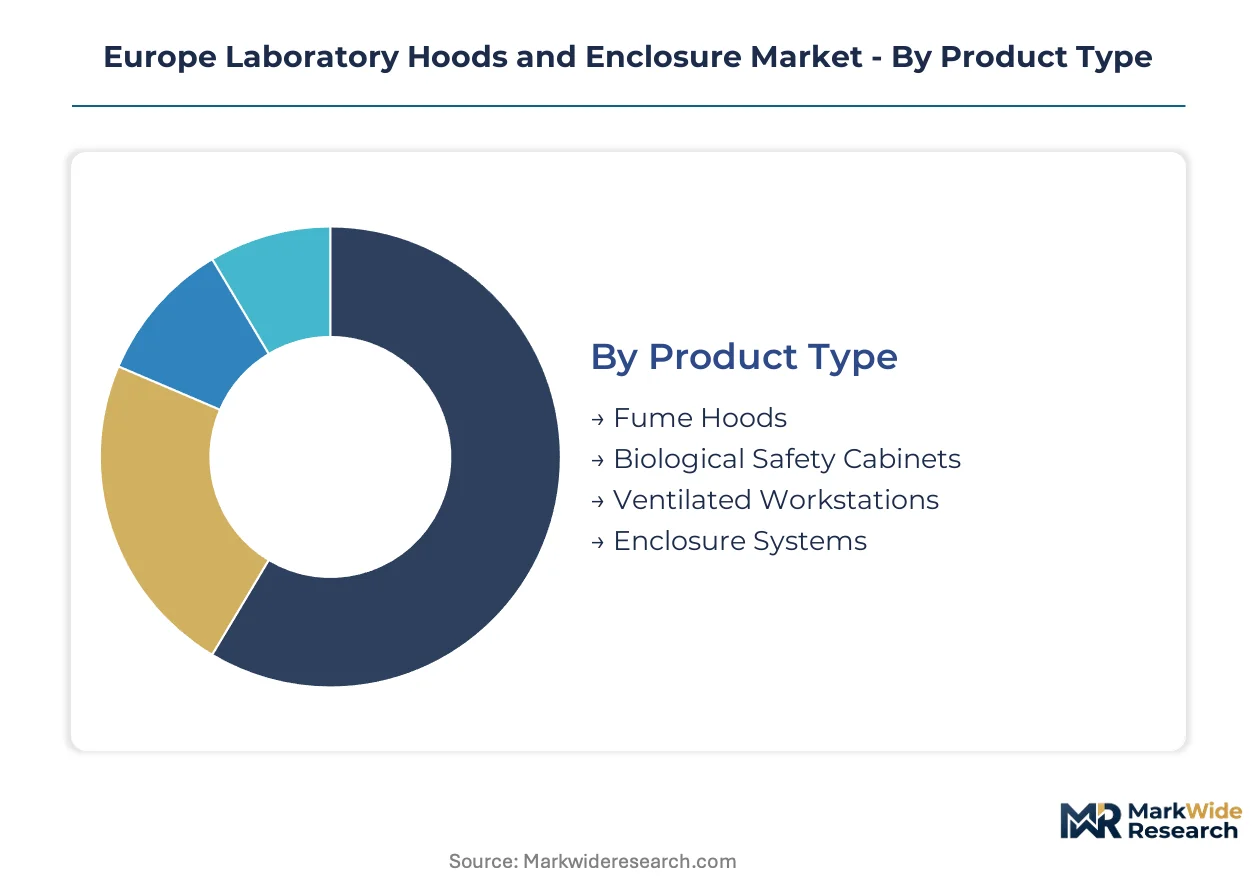
Product architecture in European laboratory containment splits across chemical exhaust, biological isolation, and flexible workstation formats. Each segment carries distinct certification burdens, energy profiles, and replacement cycles that shape supplier positioning and procurement negotiation leverage across pharmaceutical and academic channels.
Product Type:
Cost tier stratification separates commodity fume handling from premium biological containment systems with validated performance guarantees.
- Fume Hoods:Epoxy-coated steel or polypropylene construction with face velocity controls between 0.3-0.5 m/s dominates chemical research infrastructure across Germany's Rhine-Main corridor. ECHA REACH compliance deadlines are accelerating liner replacement programs in legacy French and Belgian installations.
- Biological Safety Cabinets:HEPA-filtered laminar airflow systems with Class II certification command margin premiums driven by cell therapy manufacturing scale-up in Basel and Frankfurt pharmaceutical clusters. Swissmedic validation requirements extend procurement cycles but lock in multi-year service relationships.
- Ventilated Workstations:Flexible ducted enclosures serve academic laboratories in Netherlands and Denmark where reconfiguration frequency outweighs dedicated containment needs.
- Enclosure Systems:Custom-fabricated walk-in containment suites integrate with GMP facility infrastructure for high-potency pharmaceutical compound handling.
Fume hoods command the established base. The steepest expansion runs through biological safety cabinets.
End User:
Customer type determines specification rigor, with pharmaceutical procurement teams demanding lifecycle accountability absent in academic purchasing.
- Pharmaceutical Companies:EMA Annex 1 sterile manufacturing mandates are compressing replacement cycles for containment infrastructure across production facilities in Germany, Switzerland, and Ireland. Performance-guaranteed service contracts are displacing transactional equipment purchasing.
- Research Institutions:Public funding cycles in France and Belgium sustain capital equipment procurement with shorter validation horizons than commercial manufacturing.
- Healthcare Facilities:Diagnostic laboratories in United Kingdom NHS trusts face MDR traceability requirements for devices used in therapeutic production environments.
- Academic Laboratories:EU Green Deal energy efficiency targets are steering Netherlands and Danish university construction toward heat recovery ventilation and variable air volume prerequisites.
Pharmaceutical companies anchor premium revenue. Academic laboratories are gaining share fastest in unit volume terms.
Application:
Functional use case dictates airflow architecture, material compatibility, and regulatory scrutiny intensity across European installations.
- Chemical Handling:Corrosive vapor capture applications in German and French chemical research facilities face ECHA REACH restrictions on per- and polyfluoroalkyl substances in hood liners and gaskets.
- Biological Research:Cell and gene therapy production in Basel corridor facilities drives Class II biological safety cabinet density at unprecedented scale.
- Sample Preparation:Pre-analytical containment workstations serve clinical diagnostic workflows in United Kingdom and Netherlands healthcare networks.
- Environmental Testing:Particulate isolation for soil and water analysis concentrates in regulatory agency and contract laboratory settings.
Chemical handling retains the largest installed footprint. Biological research exhibits the steepest upward trajectory.
Installation Type:
Physical mounting configuration determines HVAC integration complexity, structural modification scope, and mobility flexibility.
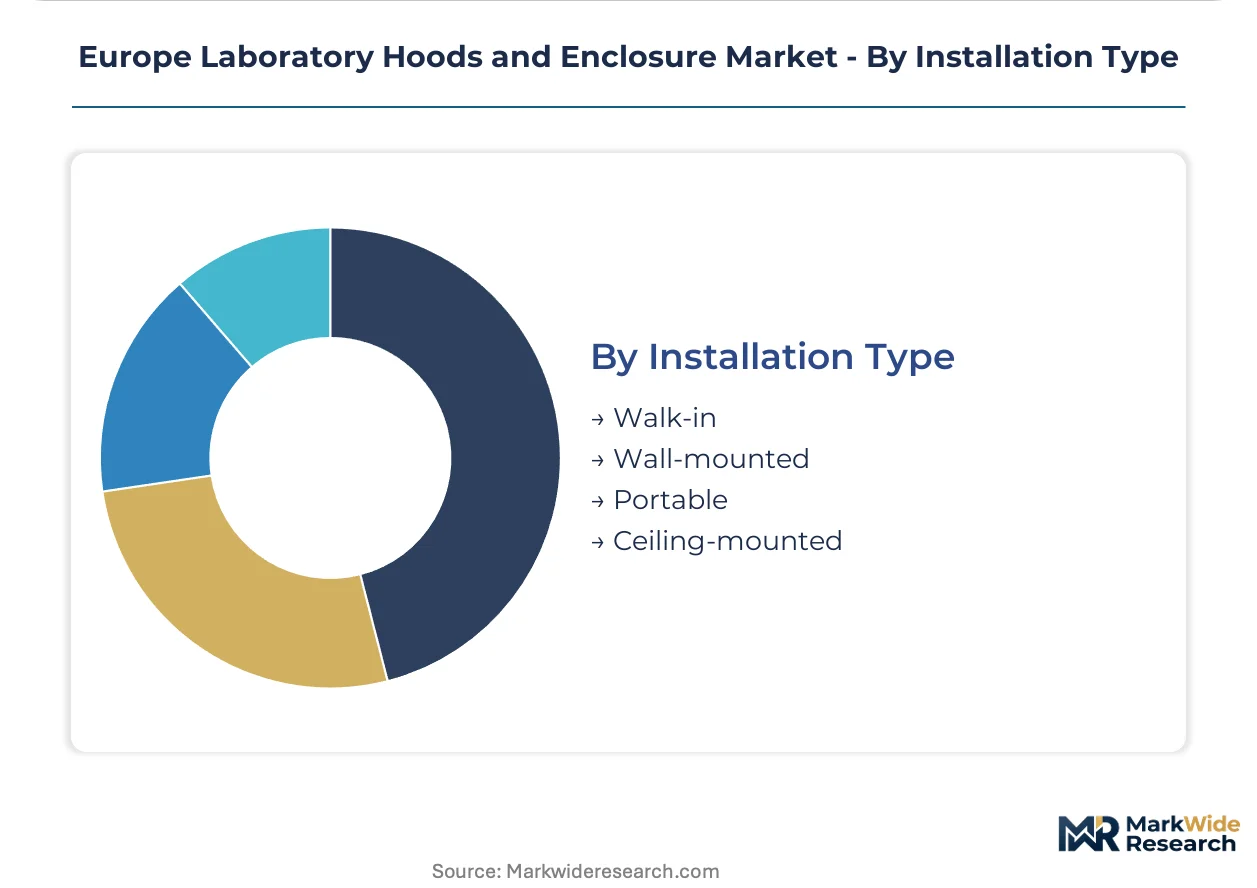
- Walk-in:Full personnel access enclosures for large equipment or multiple simultaneous operations dominate pharmaceutical pilot plant construction in Switzerland and Germany.
- Wall-mounted:Standard fume hood format across European chemical research infrastructure with supply and exhaust ducting integrated into building services.
- Portable:Ductless filtration units with carbon or HEPA media serve temporary or reconfigurable academic laboratory layouts in France and Belgium.
- Ceiling-mounted:Canopy enclosures for large apparatus capture applications in environmental testing and industrial hygiene settings.
Wall-mounted systems command the established base. Portable configurations are climbing the fastest among installation formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers supply containment systems across the Rhine-Main corridor into Swiss pharmaceutical hubs and French chemical research clusters, establishing a north-south trade corridor that channels premium fabrication capacity toward Basel and Frankfurt demand centers.
Germany
EMA Annex 1 sterile manufacturing mandates are accelerating replacement cycles for legacy containment infrastructure across pharmaceutical production facilities. ECHA REACH restrictions on per- and polyfluoroalkyl substances are compressing supplier lead times for compliant hood liner materials. The Frankfurt-to-Basel corridor concentrates cell therapy manufacturing scale-up, driving unprecedented density of Class II biological safety cabinet installations.
Switzerland
Swissmedic validation requirements extend procurement cycles for containment systems while locking in multi-year service relationships with premium suppliers. The EU F-Gas Regulation phase-down is accelerating adoption of hydrocarbon-based refrigeration in biological safety cabinets ahead of 2027 quota restrictions. Basel pharmaceutical clusters are installing containment infrastructure at commercial gene therapy production scale.
France
ANSM oversight of sterile manufacturing facilities is tightening containment validation protocols across pharmaceutical production sites. Public funding cycles sustain capital equipment procurement for academic laboratories with shorter validation horizons than commercial manufacturing. The Paris-Saclay research cluster and Lyon biotech corridor are expanding containment infrastructure for chemical and biological research applications.
United Kingdom
NHS diagnostic laboratories face MDR traceability requirements for devices used in therapeutic production environments. Retrofitting variable air volume controls into 1980s-era university laboratory infrastructure requires structural modification beyond equipment replacement scope. The Cambridge-London-Oxford golden triangle concentrates cell therapy research driving biological safety cabinet demand.
Netherlands
EU Green Deal energy efficiency targets are steering university construction toward heat recovery ventilation and variable air volume prerequisites. Academic procurement teams prioritize flexible reconfiguration over dedicated containment needs, favoring ventilated workstation formats. The Leiden-Delft-Eindhoven biotech triangle is expanding pilot-scale containment infrastructure for cell and gene therapy development.
Europe Laboratory Hoods and Enclosure Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where premium fabrication capabilities separate validated pharmaceutical suppliers from commodity academic vendors. The vendor base clusters around three strategic archetypes: Swabian manufacturing specialists with GMP customization depth, steel-lab furniture integrators leveraging construction relationships, and biological safety cabinet specialists capturing cell therapy manufacturing premiums. M&A activity concentrates on sensor analytics capabilities for predictive service contracts, while geographic expansion targets Central and Eastern European greenfield construction markets.
Among German-based fabricators, WALDNER Holding GmbH & Co. KG and Köttermann GmbH exemplify the premium customization tier serving pharmaceutical GMP facilities, while Esco Lifesciences Group anchors the biological safety cabinet specialization vector. These three occupy positions that reflect divergent competitive strategies: manufacturing-base proximity for customized enclosure systems, deep steel-lab furniture integration for construction-channel control, and biological containment leadership for cell therapy production scale-up.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| WALDNER Holding GmbH & Co. KG |
| Köttermann GmbH |
| Bigneat Ltd. |
| Esco Lifesciences Group |
| Monmouth Scientific Limited |
| Kewaunee International Group |
| Nuaire |
| Labconco |
| Others |
Supply & Pricing Matrix
Grade 316L stainless steel input volatility determines both three-tier pricing spreads across premium GMP, standard research, and economy academic tiers and supply chain configuration toward German and Italian motor supplier concentration. Buyers face compressed negotiation leverage where single-source blower dependencies intersect with REACH-compliant material substitution timelines.
Pricing Analysis
Current-generation IoT-enabled biological safety cabinets with predictive diagnostics command premium positioning against prior-generation static airflow fume hoods and emerging next-generation AI-optimized containment systems still in validation. Pricing stratifies across premium certified pharmaceutical tiers, standard research-grade specifications, and economy academic configurations driven by validation depth and customization scope. Cost compression in the standard tier intensifies as REACH-compliant liner materials extend lead times and inflate input costs. Academic laboratories exhibit highest price sensitivity due to public funding cycles, while pharmaceutical procurement teams prioritize lifecycle service accountability over unit cost.
Supply Chain Analysis
Export-control scrutiny on precision blower motor technology restricts component flows from German and Italian suppliers to non-EU assembly operations, fragmenting sourcing flexibility. Manufacturing gravity centers on Germany's Swabian fabrication corridor, Switzerland's Basel pharmaceutical equipment cluster, and Italy's electromechanical component base. Supply chains draw from specialized steel mills for 316L sheet, HEPA filtration media suppliers, and hydrocarbon refrigeration component manufacturers. Single-source vulnerability around high-performance blower motors creates structural risk exposure. Distribution runs through laboratory construction channel partners and direct pharmaceutical procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Annex 1 sterile manufacturing mandates are compressing replacement cycles and accelerating service contract transitions, creating high-growth disruption as predictive IoT architectures displace static containment hardware.
For Market Incumbents: Build switching-cost moats through embedded sensor analytics and multi-year predictive maintenance contracts that lock in pharmaceutical accounts. Pursue backward integration into HEPA filtration media production to reduce supplier dependency exposure. Esco Lifesciences Group and WALDNER Holding demonstrate how certification depth and GMP customization capabilities defend against emerging Asian biological safety cabinet entrants. For New Entrants and Emerging Players: Central and Eastern European greenfield laboratory construction offers white-space penetration where incumbent relationships remain unformed. Poland and Czech Republic biotech clusters lack established supplier networks and prioritize cost-efficient ventilated workstation formats over premium biological containment. Target academic procurement channels in Netherlands and Denmark where EU Green Deal energy efficiency specifications favor flexible reconfigurable systems with shorter validation horizons. For Investors and Strategic Acquirers: EMA Annex 1 implementation reshapes the acquisition landscape toward sensor analytics capabilities and IQ/OQ/PQ documentation expertise as premium valuation drivers. Five-to-ten-year viability favors suppliers with demonstrated Swissmedic and EMA validation track records over commodity fabricators. Target acquisition archetypes include IoT-enabled predictive maintenance platforms and Central European distribution networks. Monitor ECHA REACH perfluorinated material substitution progress as inflection signal for compliant supplier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Platform Integration | WALDNER and Köttermann embed predictive diagnostics to capture recurring service revenue from Basel pharmaceutical clusters. |
| REACH-Compliant Material Certification | Suppliers with validated perfluorinated alternatives secure procurement preference as ECHA deadlines compress. |
| Central European Distribution Expansion | Greenfield laboratory construction in Poland and Czech Republic lacks incumbent relationships, enabling channel establishment. |
| Hydrocarbon Refrigeration Transition | EU F-Gas Regulation phase-down forces biological safety cabinet replacement cycles ahead of quota restrictions. |
| Academic Energy Efficiency Positioning | Heat recovery ventilation and VAV system bundling aligns with Netherlands and Denmark EU Green Deal procurement mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical facility engineering directors, academic laboratory procurement managers, GMP validation specialists, and containment system distributors. Secondary validation drew from EMA Annex 1 guidance documents, ECHA REACH substance restriction databases, Swissmedic certification registries, and EU Green Deal energy efficiency directives. Bottom-up unit deployment estimates triangulated against top-down facility construction pipeline data.
Calibration anchored installed base replacement cycles against EMA sterile manufacturing mandates and ECHA compliance timelines. Segmentation modeling spanned product architecture, end-user procurement behavior, application contamination risk tiers, and installation HVAC integration complexity. CAGRs were derived from facility construction forecasts and containment density assumptions across the projection horizon. Industry-specific inputs included cell therapy manufacturing scale-up trajectories and hydrocarbon refrigeration adoption curves.
Macroeconomic conditions sit as an overlay; deviation in steel commodity pricing, pharmaceutical capital expenditure cycles, or academic public funding levels would shift the trajectory. Forecasts reflect documented assumptions around regulatory implementation schedules and technology substitution rates. Material shifts in ECHA perfluorinated material restriction timelines or EU F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Automated Plate Readers Market