
 Companion Animal Drugs Market | 2026-2036
Companion Animal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Drugs Market Analysis
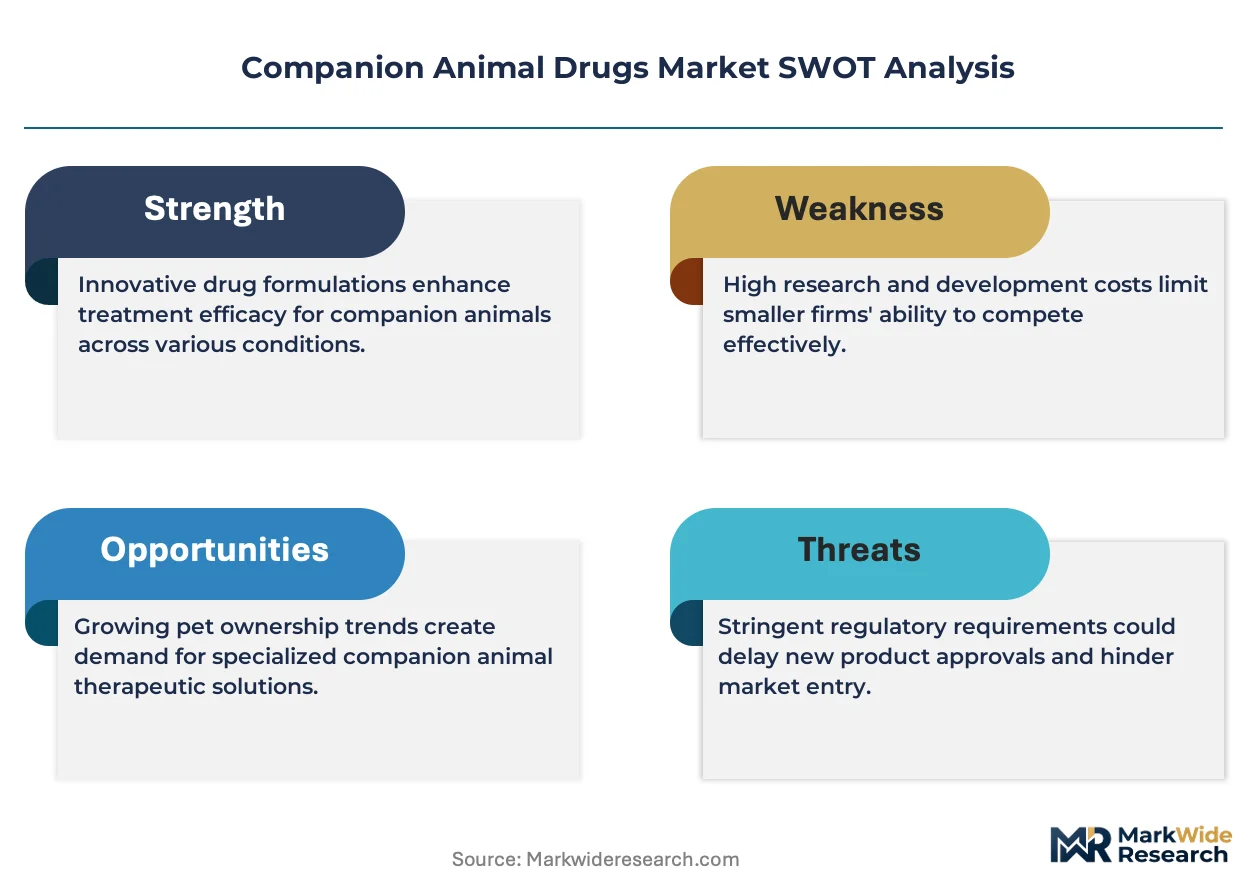
Specialty veterinary practices are collapsing the historical distance between companion animal and human pharmaceutical standards. Zoetis leverages its vertically integrated biologics platform to dominate the vaccine segment across North American and European channels. Boehringer Ingelheim Animal Health anchors its position through sustained R&D intensity in parasiticide formulations for both small and large companion species. Merck Animal Health differentiates via manufacturing scale that supports multi-species production lines with minimal changeover costs.
Companion animal drugs comprise pharmaceutical and biologic agents formulated specifically for dogs, cats, horses, and other non-food animals, typically manufactured under cGMP conditions with species-specific pharmacokinetic profiling and palatability engineering to ensure therapeutic compliance. These products serve to prevent infectious disease, manage chronic conditions, and control pain in animals kept primarily for companionship rather than agricultural production. Parasiticides occupy the largest revenue pool within product type segmentation due to recurring monthly dosing requirements and broad species applicability. Injectable administration routes command premium positioning in clinical settings where compliance assurance outweighs convenience factors, while oral formulations sustain volume leadership through direct-to-consumer channels. Dermatological conditions represent a therapy area where margin expansion accelerates as novel monoclonal antibody therapies displace corticosteroid-first protocols.
The FDA Center for Veterinary Medicine and the EMA Committee for Medicinal Products for Veterinary Use shape market access through divergent approval timelines and residue limit standards that force manufacturers to maintain parallel regulatory dossiers. The USDA Animal and Plant Health Inspection Service regulates certain biologic products, creating overlapping jurisdiction that complicates launch sequencing for combination vaccines. Stakeholders must monitor how the EU Green Deal's pharmaceutical discharge limits reshape manufacturing location decisions and whether FDA accelerated approval pathways for unmet veterinary needs expand beyond the current oncology pilot program.
Market Dynamics
Pet humanization in the United States compresses development cycles for chronic disease therapeutics as owners demand human-equivalent efficacy standards and insured reimbursement parity for dogs and cats.
Growth Catalysts
- FDA Center for Veterinary Medicine oncology pilot:Accelerated approval pathways for unmet veterinary needs compress time-to-market for novel biologics targeting lymphoma and osteosarcoma in companion species.
- Parasiticide monthly dosing protocols:Recurring revenue streams from heartworm and flea-tick preventatives sustain prescription volume through direct-to-consumer subscription channels.
- Monoclonal antibody engineering:Canine atopic dermatitis therapies are displacing corticosteroid-first protocols and capturing premium positioning in specialty veterinary clinics.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for veterinary parasiticides clusters in Chinese chemical parks, exposing formulators to export license volatility and environmental compliance disruptions.
- EMA residue limit divergence:Parallel dossier requirements for EU and US markets force manufacturers to maintain dual manufacturing specifications, inflating regulatory compliance overhead.
- Generic substitution pressure:Off-patent small-molecule antibiotics and NSAIDs face commoditization as compounding pharmacies exploit regulatory arbitrage between 503A and 503B facilities.
Strategic Opportunities
- Underpenetrated feline therapeutics:Drug development historically prioritized canine indications, leaving chronic kidney disease and hyperthyroidism in cats underserved relative to disease prevalence.
- EU Green Deal pharmaceutical discharge limits:Manufacturing location decisions are rotating toward zero-liquid-discharge facilities in Portugal and Ireland to preempt environmental compliance penalties.
- Telemedicine prescription integration:Veterinary telehealth platforms are creating new channels for chronic disease medication management and refill compliance monitoring.
Industry Challenges
- Veterinary pharmacology talent scarcity:Species-specific pharmacokinetic modeling requires cross-trained professionals fluent in both human drug development and comparative medicine, a skill combination concentrated in academic centers.
- cGMP facility retooling costs:Multi-species production lines demand rapid changeover capabilities between canine tablets and feline liquids, requiring capital-intensive flexible manufacturing suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Drugs Market |
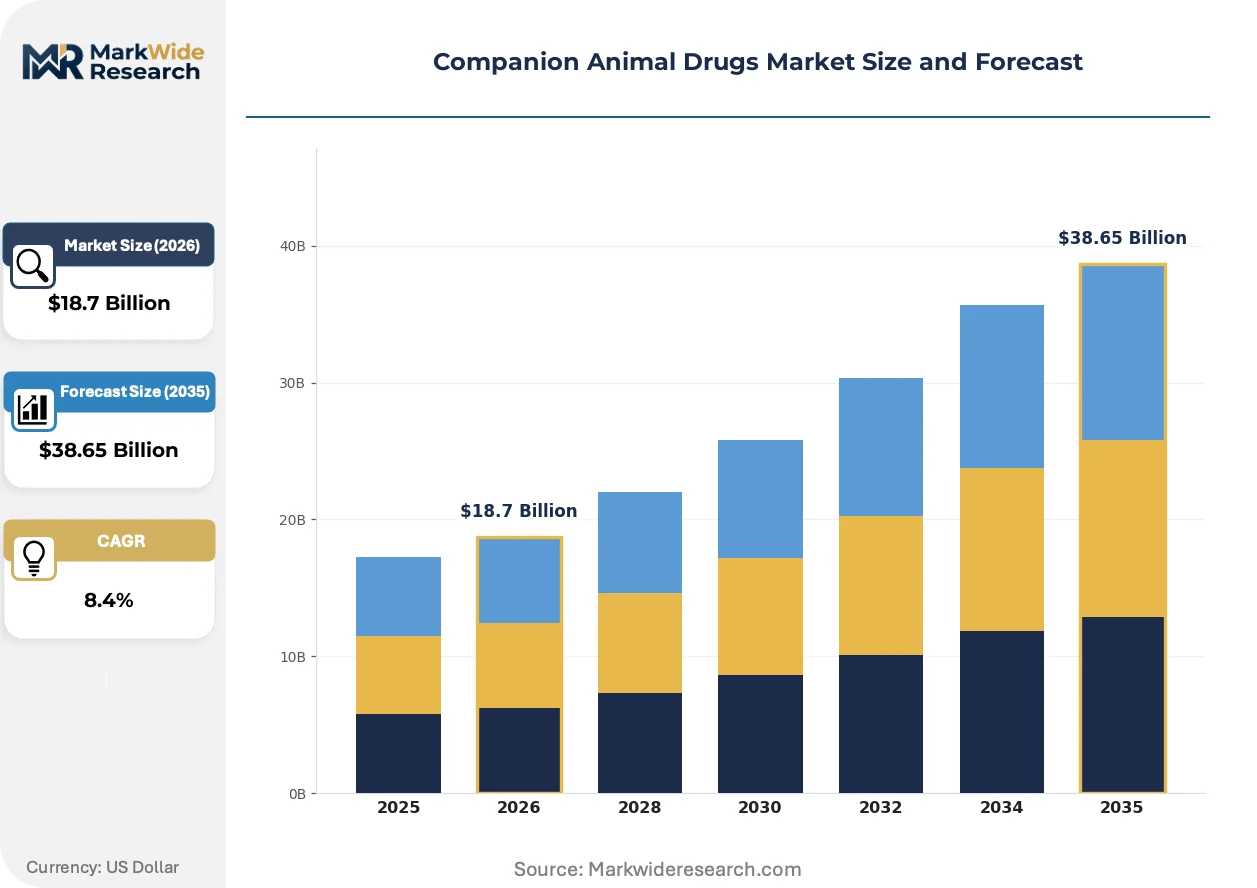
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parasiticides, Vaccines, Anti-inflammatories, Antibiotics End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Online Pharmacies Therapy Area: Infectious Diseases, Orthopedic Disorders, Dermatological Conditions, Behavioral Disorders Administration Route: Oral, Topical, Injectable, Transdermal |
| Companies Covered | Zoetis, Boehringer Ingelheim Animal Health, Elanco Animal Health, Merck Animal Health, Virbac, Dechra Pharmaceuticals, Ceva Santé Animale, Bayer Animal Health, IDEXX Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Drugs Market Emerging Trajectories
Biologics manufacturing and regulatory science are converging to collapse the historical gap between human and veterinary pharmaceutical standards, with monoclonal antibodies and gene therapies now entering companion animal pipelines.
Monoclonal antibody therapies for allergic and inflammatory conditions are supplanting long-term corticosteroid administration in canine dermatology and otology. Specialty veterinary practices in the United States and Germany are adopting these biologics as first-line protocols for atopic dermatitis. The shift is compressing margins for generic steroid manufacturers while expanding the addressable market for injectable maintenance therapies.
REACH and the EU Green Deal pharmaceutical discharge limits are forcing API sourcing decisions toward zero-liquid-discharge manufacturing clusters in Portugal and Ireland. Environmental compliance costs are reshaping supplier qualification criteria for European veterinary formulators. Manufacturers are responding by consolidating active ingredient procurement through vertically integrated European chemical parks with pre-certified waste treatment infrastructure.
Pet owner purchasing behavior is fragmenting across insured clinic visits and direct-to-consumer online pharmacies. Chewy and Amazon Veterinary are disintermediating traditional veterinary dispensing by offering automated refill subscriptions for chronic medications. This channel shift is most visible in the United States, where pet insurance penetration exceeds twenty percent and owners expect price transparency comparable to human healthcare marketplaces.
Companion Animal Drugs Market Segmentation
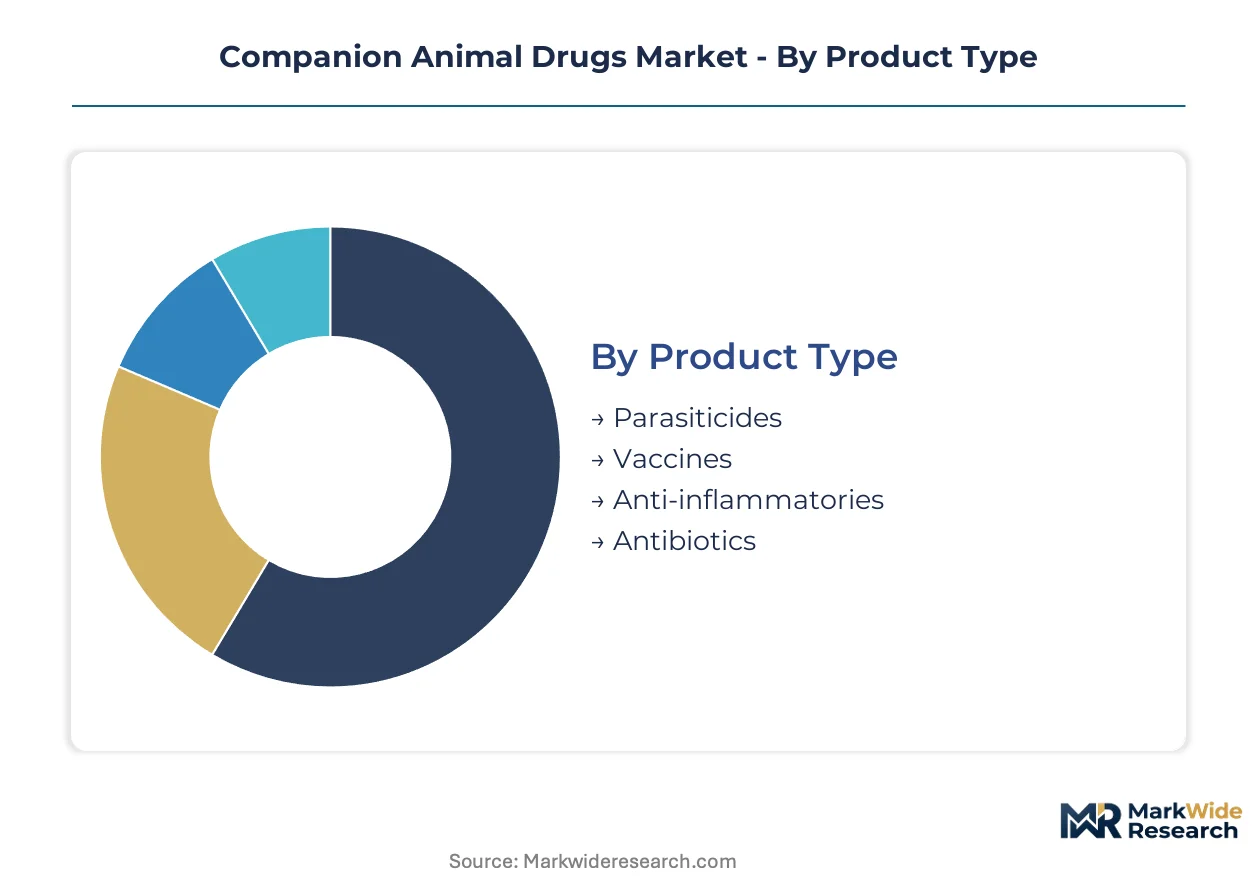
Segmentation in companion animal pharmaceuticals reveals how regulatory pathways, clinical settings, and species-specific pharmacokinetics fragment manufacturing priorities. Product type and administration route decisions cascade through formulation chemistry, shelf-life requirements, and dispensing channel economics.
Product Type:
FDA Center for Veterinary Medicine and EMA Committee for Medicinal Products for Veterinary Use impose divergent residue limits and approval timelines that reshape product-specific investment priorities across formulation categories.
- Parasiticides:Monthly-dose heartworm preventatives and flea-tick combinations rely on isoxazoline and macrocyclic lactone chemistry with extended plasma half-lives. Veterinary clinics in the United States drive prescription volume through insured wellness plans that bundle parasiticides with annual examinations.
- Vaccines:USDA Animal and Plant Health Inspection Service regulates companion animal biologics under virus-serum-toxin authority distinct from FDA pharmaceutical oversight. Canine core vaccines sustain volume leadership through mandatory rabies protocols, while feline non-core vaccines face slower adoption due to duration-of-immunity controversies.
- Anti-inflammatories:NSAID formulations for osteoarthritis management require species-specific COX selectivity profiling to avoid renal toxicity in cats.
- Antibiotics:Veterinary-specific fluoroquinolone and cephalosporin restrictions limit prescription autonomy to veterinarians with valid client-patient relationships.
Established volume favors parasiticides; emerging adoption favors vaccines with extended duration claims.
End User:
Channel economics stratify around prescription control, reimbursement infrastructure, and compliance monitoring capabilities.
- Veterinary Clinics:Primary care and specialty practices capture insured wellness visits and chronic disease management through in-house dispensing. The United States concentration of pet insurance products above twenty percent penetration sustains premium pricing for clinic-dispensed therapeutics.
- Animal Hospitals:Emergency and referral centers command injectable administration routes where compliance assurance outweighs convenience factors. These facilities manage complex cases requiring IV fluid compatibility and perioperative analgesic protocols.
- Pet Owners:Direct purchasing concentrates in over-the-counter parasiticide categories with established safety margins.
- Online Pharmacies:Automated refill subscriptions for chronic medications disintermediate traditional veterinary dispensing through price transparency platforms.
Prescription control favors veterinary clinics; price transparency favors online pharmacies.
Therapy Area:
Disease prevalence and margin structure vary sharply between acute infectious protocols and chronic condition management.
- Infectious Diseases:Vaccine-preventable viral pathogens and bacterial zoonoses drive regulatory prioritization through public health linkages. Rabies vaccination mandates sustain baseline demand regardless of economic cycles.
- Orthopedic Disorders:NSAID and monoclonal antibody therapies for osteoarthritis capture premium positioning as canine lifespans extend. Specialty practices in Germany and the United States adopt biologic alternatives to corticosteroid-first protocols.
- Dermatological Conditions:Canine atopic dermatitis represents the fastest-expanding biologics opportunity as IL-31 pathway inhibitors displace long-term steroid administration.
- Behavioral Disorders:Psychopharmacology for separation anxiety and cognitive dysfunction syndrome remains underpenetrated relative to diagnosed prevalence.
Preventive protocols favor infectious diseases; margin expansion favors dermatological conditions.
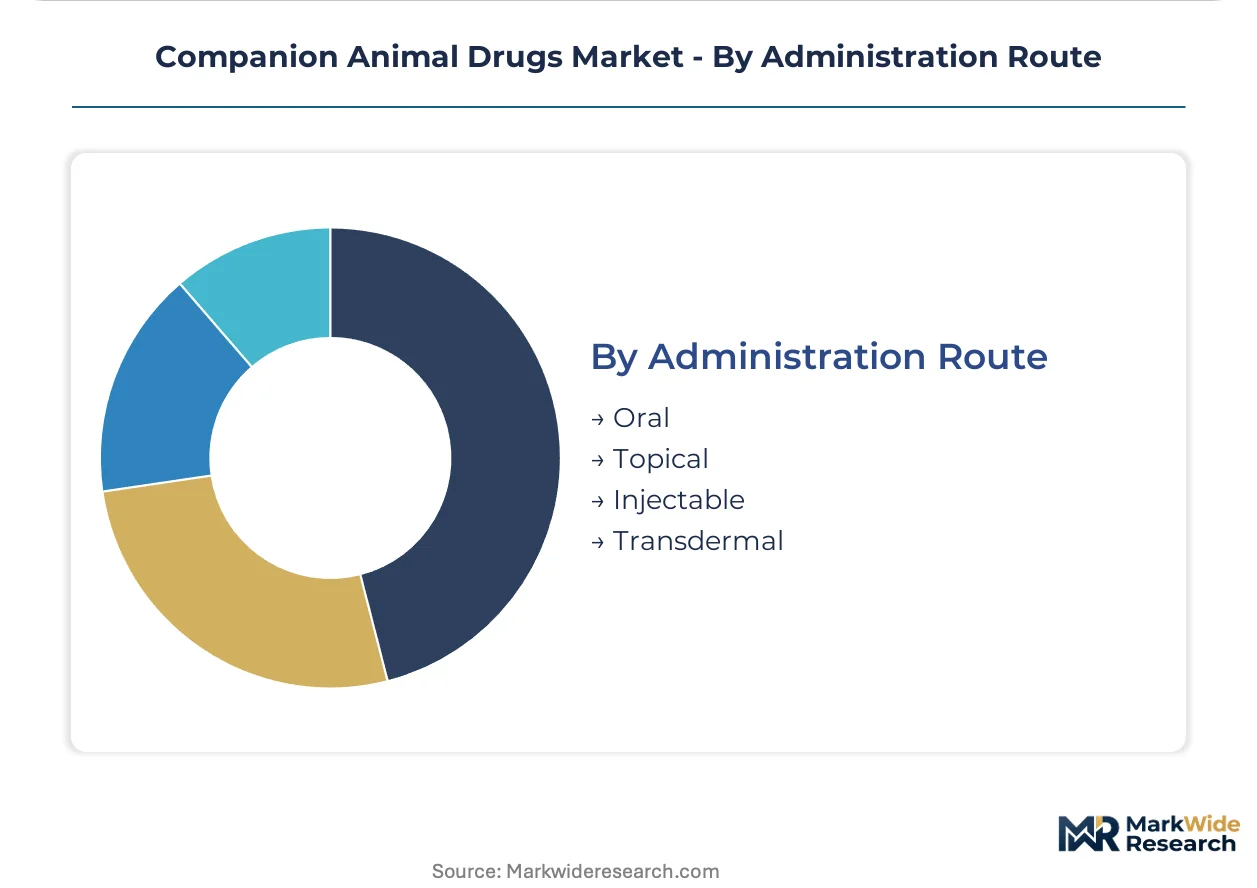
Administration Route:
Formulation engineering and compliance psychology determine route selection across species and clinical settings.
- Oral:Palatability-engineered tablets and flavored liquids dominate feline therapeutics where restraint stress limits alternative routes. Direct-to-consumer channels sustain volume leadership through owner-administered chronic medications.
- Topical:Transdermal parasiticide formulations combine convenience with reduced systemic exposure concerns. Monthly spot-on applications sustain subscription revenue through automatic refill programs.
- Injectable:Depot formulations and monoclonal antibody therapies command premium pricing in clinical settings where therapeutic assurance outweighs convenience factors.
- Transdermal:Gel formulations for behavioral and hormonal therapies exploit feline skin permeability characteristics.
Owner convenience favors oral and topical routes; therapeutic assurance favors injectable administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical exports supply veterinary formulators across Canada, Mexico, and European Union markets, establishing transatlantic trade corridors for active ingredients and finished dosage forms.
United States
Insured veterinary visits exceeding twenty percent penetration sustain premium drug consumption through clinic-dispensed parasiticides and monoclonal antibody therapies. FDA Center for Veterinary Medicine oncology pilot programs accelerate biologic approvals for lymphoma indications. Kansas City and Research Triangle Park clusters host contract manufacturing organizations producing species-specific formulations.
Germany
Specialty veterinary practices in Bavaria and North Rhine-Westphalia adopt biologic-first protocols for canine atopic dermatitis. EMA Committee for Medicinal Products for Veterinary Use residue limit standards shape parallel dossier requirements for EU market access. Leipzig-Halle chemical park concentrates zero-liquid-discharge API manufacturing for export to Western European formulators.
United Kingdom
London and Southeast England referral centers command injectable administration routes for complex orthopedic and oncological cases. Veterinary Medicines Directorate post-Brexit regulatory divergence necessitates separate UK-specific approval pathways. Cambridge biotech corridor attracts monoclonal antibody engineering talent from continental European academic centers.
France
ANSM oversight of veterinary pharmacovigilance reinforces stringent adverse event reporting for novel biologics. Lyon and Auvergne-Rhône-Alpes region host production facilities for transdermal feline behavioral therapies. Parisian specialty clinics drive adoption of IL-31 pathway inhibitors displacing corticosteroid protocols.
Japan
PMDA accelerated review pathways for unmet veterinary needs compress development timelines for feline chronic kidney disease therapeutics. Tokyo-Osaka corridor concentrates pet insurance products sustaining premium pricing for clinic-dispensed medications. Kansai region manufacturing bases supply oral palatability-engineered formulations across East Asian markets.
Companion Animal Drugs Market Vendor Landscape
Player mix skews toward integrated pharmaceutical conglomerates with human health heritage, creating tiered competitive structure where biologics capabilities separate premium positioning from commodity parasiticide segments. Strategic archetypes include vertically integrated biologics platforms, parasiticide-focused R&D intensive operations, and manufacturing-scale multi-species producers. Dominant competitive moves encompass portfolio diversification into monoclonal antibody therapies and geographic expansion through zero-liquid-discharge manufacturing clusters in Portugal and Ireland.
Within the integrated pharmaceutical tier, Zoetis and Boehringer Ingelheim Animal Health exemplify archetypes leveraging human health infrastructure for veterinary biologics development. Merck Animal Health occupies a position emphasizing manufacturing scale advantages across multi-species production lines. These three entities represent the concentration of biologics engineering capabilities and regulatory science expertise that now collapses historical gaps between human and veterinary pharmaceutical standards.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Merck Animal Health |
| Virbac |
| Dechra Pharmaceuticals |
| Ceva Santé Animale |
| Bayer Animal Health |
| IDEXX Laboratories |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for macrocyclic lactone APIs lock in supply access and price visibility for veterinary formulators navigating Chinese export license volatility. These contracts tether procurement costs to environmental compliance benchmarks while insulating manufacturers from spot market fluctuations in isoxazoline chemistry.
Pricing Analysis
Next-generation monoclonal antibody therapies for canine atopic dermatitis command premium positioning against prior-generation corticosteroid protocols. Three-tier pricing structure across premium biologics, standard NSAIDs, and economy generic parasiticides stratifies by therapeutic innovation level and reimbursement infrastructure. Pricing pressure stems from direct-to-consumer online pharmacies disintermediating clinic dispensing channels. Insured veterinary clinics exhibit lowest price sensitivity; uninsured pet owners purchasing over-the-counter preventatives show highest elasticity.
Supply Chain Analysis
API manufacturing concentration in Jiangsu and Zhejiang chemical parks creates chokepoint exposure for isoxazoline and macrocyclic lactone supply security. Active pharmaceutical ingredient production draws from Chinese chemical parks, Indian contract manufacturers, and European zero-liquid-discharge facilities. Single-source vulnerability intensifies as REACH compliance costs consolidate supplier bases. Distribution runs through veterinary clinic dispensing, animal hospital procurement, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion animal drug manufacturers face substitution defense imperatives as compounding pharmacies exploit regulatory arbitrage between 503A and 503B facilities to capture chronic medication volumes.
For Market Incumbents: Fortify formulation patent estates through species-specific pharmacokinetic extensions that delay generic entry. Secure backward integration into zero-liquid-discharge API manufacturing in Portugal and Ireland to preempt EU Green Deal compliance penalties. Channel control through insured clinic dispensing networks remains the critical defensive lever against online pharmacy disintermediation. For New Entrants and Emerging Players: Lead with underpenetrated feline chronic kidney disease therapeutics where development pipelines historically prioritized canine indications. Target telemedicine-integrated prescription platforms as the most penetrable channel for chronic disease medication management. Position through subscription-based refill compliance monitoring to bypass established clinic dispensing relationships. For Investors and Strategic Acquirers: Capital is best deployed toward biologics engineering platforms with monoclonal antibody capabilities that collapse historical gaps between human and veterinary pharmaceutical standards. Long-term viability over the projection horizon favors vertically integrated manufacturers with captive API supply and multi-species flexible production suites. Watch FDA oncology pilot program expansion beyond lymphoma indications as the signal for accelerated approval pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Monoclonal Antibody Pipeline Expansion | Captures premium positioning in canine atopic dermatitis as IL-31 pathway inhibitors displace corticosteroid protocols. |
| Zero-Liquid-Discharge Manufacturing Migration | Preempts EU Green Deal pharmaceutical discharge penalties through Portuguese and Irish facility consolidation. |
| Telemedicine Prescription Integration | Creates automated refill channels for chronic disease management beyond traditional veterinary clinic dispensing. |
| Feline Therapeutic Development Prioritization | Addresses chronic kidney disease and hyperthyroidism underserved relative to disease prevalence. |
| Regulatory Parallel Dossier Optimization | Reduces compliance overhead from FDA-EMA divergence in residue limit standards and approval timelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, EMA Committee for Medicinal Products for Veterinary Use submissions, and USDA biologics licensing data. Veterinary pharmaceutical executives, regulatory affairs specialists, specialty clinic formulary directors, and animal hospital procurement managers provided structured input. Secondary validation drew from ClinicalTrials.gov veterinary oncology entries, pet insurance claims databases, and customs records of API imports. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue segmentation.
Segmentation dimensions modeled include product type, administration route, therapy area, species, and regional regulatory cluster across the analysis window. CAGRs were derived from historical prescription volume trajectories, insurance penetration curves, and biologics adoption rates. Forecast inputs incorporated FDA oncology pilot program expansion scenarios and EU Green Deal manufacturing compliance cost projections.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine and EMA approval pathways; material policy shifts would require re-modeling. Specific risks include API export license volatility from Chinese chemical parks and post-Brexit UK regulatory divergence from EMA standards. Practitioners should keep alternative scenarios live as environmental compliance thresholds and telemedicine prescribing regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Porcine Vaccine Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Europe Veterinarians Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Animal Microchip Implant Market
Veterinary
Veterinary Lasers Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Animal Drug Compounding Market
Veterinary
Canine Arthritis Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Veterinary Parasiticides Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Canine Parvovirus Market