
 Belgium and Netherlands Advanced Wound Care Market | 2026-2036
Belgium and Netherlands Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium and Netherlands Advanced Wound Care Market Outlook
Silicone adhesives are restructuring the economics of advanced wound care by displacing traditional acrylic bonding layers in foam and hydrocolloid dressings. Mölnlycke Health Care leverages its silicone expertise to sustain premium positioning across Belgian hospital networks. Smith & Nephew anchors its competitive stance through integrated negative pressure wound therapy systems that pair with advanced dressings. Hartmann Group differentiates via antimicrobial portfolio depth, competing directly with Coloplast's chronic wound specialization in Dutch long-term care channels.
Advanced wound care comprises sterile, bioactive, and semi-occlusive dressing systems engineered from polymers, alginates, hydrocolloids, or antimicrobial agents to maintain moist healing environments, manage exudate, and prevent infection across acute and chronic tissue damage. These products serve primarily to accelerate re-epithelialization, reduce dressing change frequency, and lower complication rates in diabetic foot ulcers, pressure injuries, and post-surgical sites. Foam dressings capture substantial volume share due to their versatility across moderate-to-heavy exudate wounds, while antimicrobial dressings command margin premiums driven by hospital-acquired infection prevention mandates. Home care represents the fastest-expanding end-user channel as both countries shift post-acute monitoring outside institutional settings under cost-containment pressures.
EU MDR compliance requirements and CE marking protocols under the EU Medical Device Regulation reshape product registration timelines and clinical evidence standards for manufacturers serving Belgium and the Netherlands. The Dutch Health and Youth Care Inspectorate and Belgium's Federal Agency for Medicines and Health Products enforce vigilance reporting that elevates quality system investments for market participants. Stakeholders must monitor reimbursement harmonization negotiations between Belgian INAMI/RIZIV and Dutch Zorginstituut Nederland, as divergent tariff schedules for advanced dressings could fragment pricing and access across the neighboring markets.
Market Dynamics
EU MDR compliance deadlines are compressing product registration timelines while Belgian and Dutch hospitals accelerate procurement of antimicrobial dressings under tightened infection control protocols. This regulatory pressure is restructuring supplier relationships and evidence requirements across both markets.
Growth Catalysts
- EU MDR Alignment:Belgium's Federal Agency for Medicines and Health Products and the Dutch Health and Youth Care Inspectorate are enforcing stricter vigilance reporting, elevating demand for CE-marked advanced dressings with robust clinical evidence packages.
- Randstad Demographics:The metropolitan cluster encompassing Amsterdam, Rotterdam, The Hague and Utrecht concentrates aging populations with diabetes-related chronic wounds, driving specialized wound care network expansion.
- Silver-Ion Technology:PHMB-impregnated and silver-ion materials are displacing traditional gauze in Belgian tertiary centers and Dutch wound clinics as frontline infection prevention tools.
Market Restraints
- Polymer Feedstock Volatility:Hydrophilic polyurethane and silicone raw material costs fluctuate with petrochemical markets, compressing margins on foam and hydrocolloid dressing production.
- Supplier Concentration:Advanced antimicrobial substrate manufacturing concentrates among a limited set of European chemical suppliers, creating single-source vulnerability for dressing manufacturers.
- Substitution Pressure:Biosynthetic skin substitutes and cellular wound matrices threaten to displace advanced dressings in deep chronic wound applications where re-epithelialization acceleration is critical.
Strategic Opportunities
- Home Care Channel:Post-acute monitoring outside institutional settings is expanding fastest in Dutch long-term care channels, creating demand for patient-administered dressing systems with simplified application protocols.
- Reimbursement Harmonization:Ongoing negotiations between Belgian INAMI/RIZIV and Dutch Zorginstituut Nederland present white space for suppliers who can navigate divergent tariff schedules across the neighboring markets.
- Silicone-Foam Convergence:Soft silicone contact layers integrated with superabsorbent foam cores are enabling extended wear times and reduced dressing change frequency in moderate-to-heavy exudate wounds.
Industry Challenges
- Clinical Evidence Generation:EU MDR requires renewed clinical investigations for legacy products, stretching biostatistics and regulatory affairs capabilities at mid-tier manufacturers.
- Supply Chain Reconfiguration:Post-Brexit customs friction and MDR notified body capacity constraints are forcing inventory repositioning and dual-sourcing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium and Netherlands Advanced Wound Care Market |
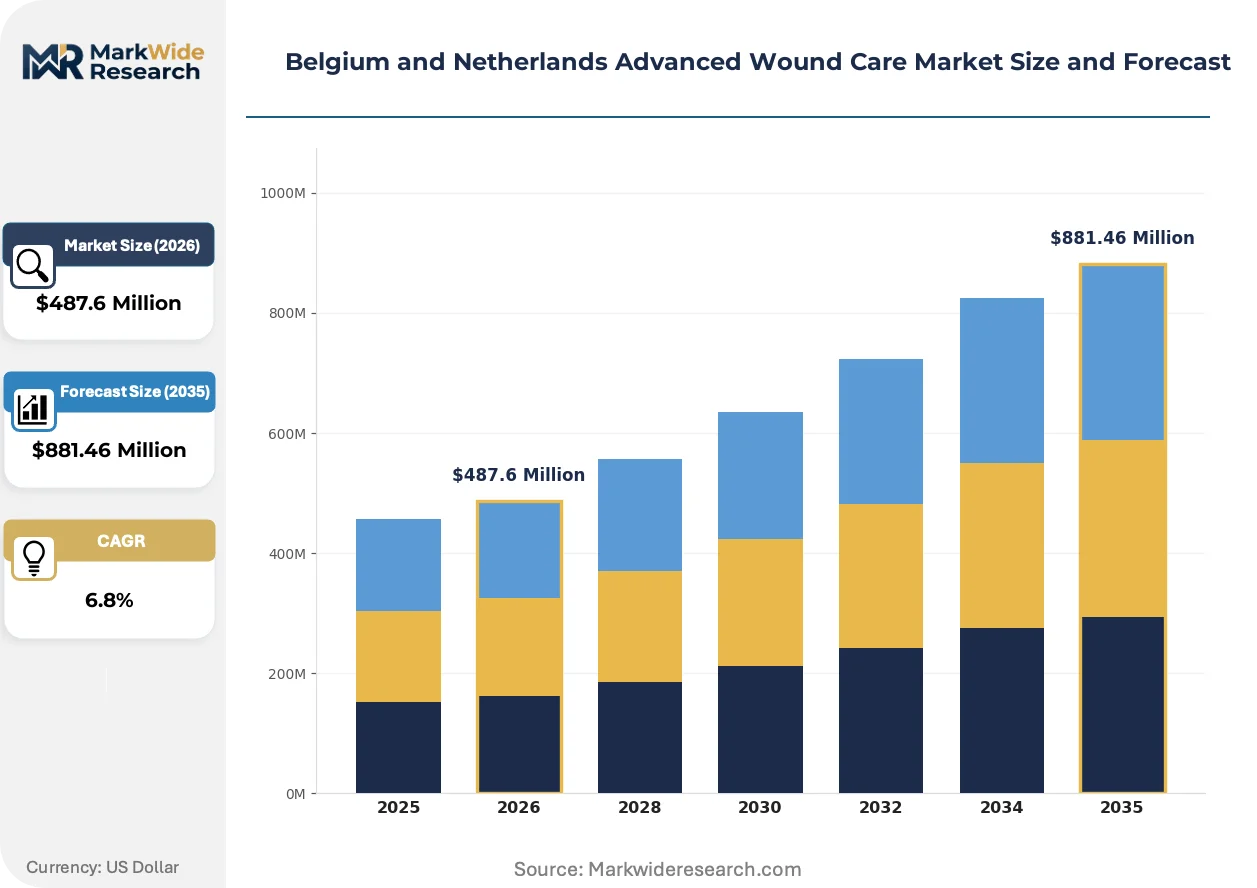
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Foam Dressings, Alginate Dressings, Antimicrobial Dressings End User: Home Care, Hospitals, Clinics, Long-term Care Facilities Application: Chronic Wounds, Surgical Wounds, Trauma Wounds, Burns Delivery Mode: Topical, Injectable, Oral, Others |
| Companies Covered | Smith & Nephew, ConvaTec, Mölnlycke Health Care, 3M, Coloplast, B. Braun, Johnson & Johnson Services, Medtronic, Hartmann Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium and Netherlands Advanced Wound Care Market Strategic Shifts
Silicone adhesive chemistry is restructuring dressing economics while regulatory evidence standards tighten and care delivery migrates toward decentralized settings. These forces are compressing traditional competitive advantages and opening new capability requirements.
Soft silicone interface layers are unifying patient comfort with clinical performance in foam and hydrocolloid dressings. Belgian tertiary centers are adopting these materials for fragile periwound skin applications where trauma minimization is paramount. The technology is unifying previously separate dressing categories into single-product solutions that reduce SKU complexity and inventory carrying costs.
EU MDR clinical evidence requirements are elevating post-market surveillance obligations for manufacturers serving Belgium and the Netherlands. The regulation mandates systematic literature reviews and PMCF studies that extend regulatory affairs timelines by 12-18 months for product line extensions. Antimicrobial dressing portfolios face the steepest compliance burden given their higher-risk classification under the updated rules.
Hospital purchasing consortia are consolidating procurement decisions across Belgian and Dutch networks, compressing supplier negotiation leverage. Academic medical centers in Leuven and Amsterdam are leading this concentration, replacing fragmented ward-level ordering with centralized tender processes. This shift is most visible in the Randstad and Flemish Diamond regions where integrated care networks span multiple treatment sites.
Belgium and Netherlands Advanced Wound Care Market Segmentation
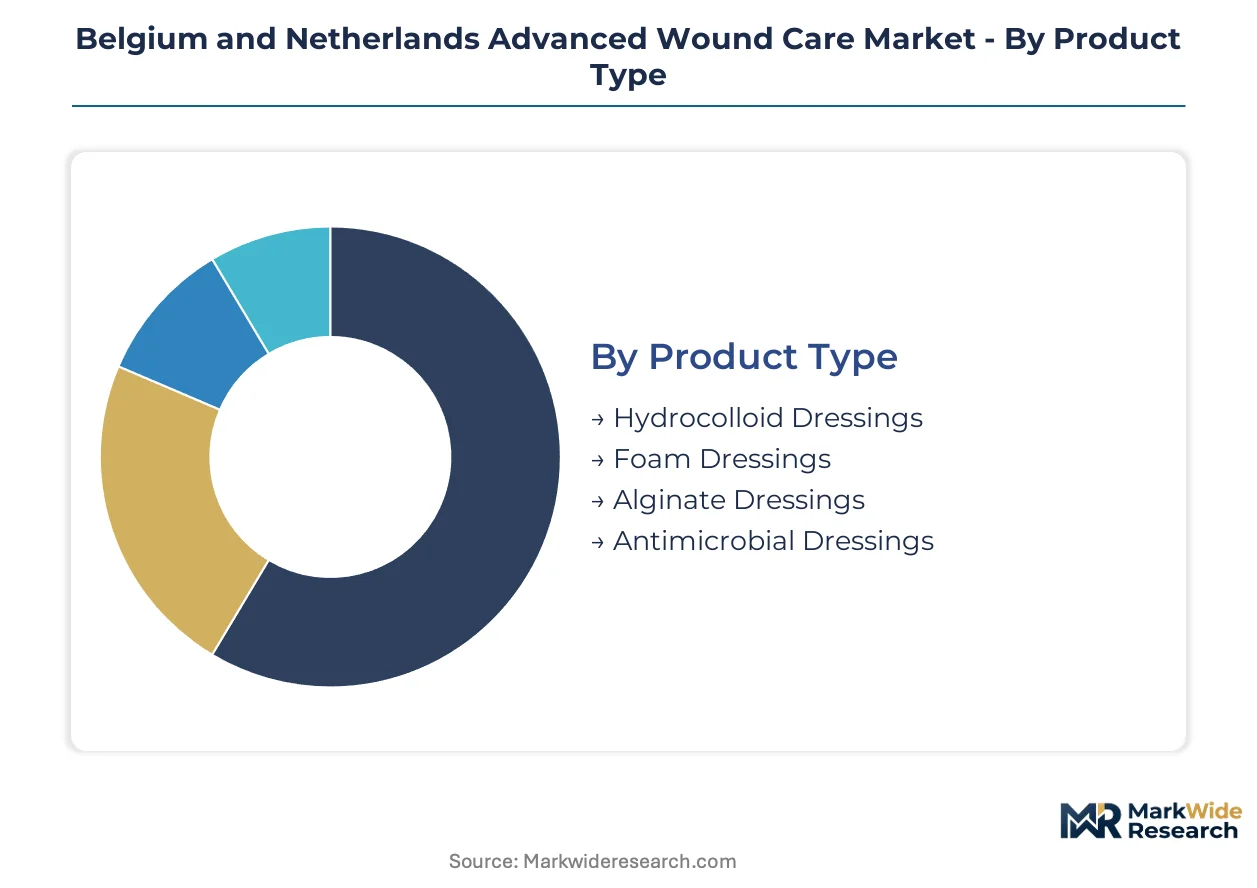
Advanced wound care purchasing decisions in Belgium and the Netherlands diver sharply across clinical settings and wound severity. Procurement managers prioritize infection control metrics in hospital tenders while home care channels demand simplified application protocols for patient self-administration.
Product Type:
Material selection hinges on exudate management requirements and reimbursement tier positioning within Belgian INAMI/RIZIV and Dutch Zorginstituut Nederland schedules.
- Foam Dressings:Hydrophilic polyurethane matrices with silicone contact layers manage moderate-to-heavy exudate across post-surgical sites and pressure injuries. Belgian tertiary centers in Leuven and Dutch academic hospitals in Amsterdam standardize these for extended wear protocols, reducing nursing labor costs.
- Antimicrobial Dressings:Silver-ion and PHMB-impregnated substrates deliver sustained release biocidal action against MRSA and Pseudomonas colonization. Frontline adoption concentrates in Dutch wound clinics and Belgian diabetes centers where infection-related amputation prevention drives procurement budgets.
- Hydrocolloid Dressings:Carboxymethylcellulose and gelatin-based occlusive systems autolytically debride necrotic tissue in low-exudate chronic wounds.
- Alginate Dressings:Calcium-sodium seaweed-derived fibers gel on contact with wound fluid, indicated for heavily exuding cavity wounds.
Volume sits with foam dressings; growth tilts toward antimicrobial variants.
End User:
Channel economics reshape product form factor requirements and regulatory evidence burdens across institutional and decentralized care models.
- Hospitals:Centralized procurement consortia in the Randstad and Flemish Diamond regions negotiate volume contracts for antimicrobial portfolios. EU MDR vigilance reporting obligations elevate supplier quality system investments for hospital tenders.
- Home Care:Patient-administered dressing systems with color-change indicators and simplified application mechanics expand fastest in Dutch long-term care channels. Reimbursement codes for post-acute monitoring outside institutional settings accelerate this shift.
- Long-term Care Facilities:Pressure injury prevention protocols in Belgian nursing homes drive scheduled dressing rotation programs.
- Clinics:Specialized wound care networks concentrate in Rotterdam and Antwerp, serving diabetic foot ulcer populations with ambulatory debridement services.
Procurement value concentrates in hospitals; patient volume expansion favors home care.
Application:
Wound etiology determines dressing performance specifications and clinical outcome measurement frameworks for reimbursement justification.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries require moisture-balanced environments over extended healing timelines. The Randstad aging demographic concentrates demand for neuropathic wound management in Dutch specialized networks.
- Surgical Wounds:Post-operative incision sites demand sterile barrier properties and absorbency matched to procedure type. Belgian tertiary centers prioritize antimicrobial dressings for contaminated surgical fields under tightened infection control mandates.
- Trauma Wounds:Acute mechanical injuries in emergency settings require rapid-application hemostatic and protective systems.
- Burns:Partial-thickness thermal injuries need conformable, non-adherent contact layers that permit joint mobility.
Clinical complexity peaks with chronic wounds; acute volume concentrates in surgical applications.
Delivery Mode:
Administration route selection reflects wound depth, tissue viability, and care setting capabilities for invasive versus non-invasive intervention.
- Topical:Direct wound bed application of dressings, gels, and ointments dominates across all care settings. Belgian and Dutch formularies prioritize topical advanced dressings for cost containment and patient safety profiles.
- Injectable:Platelet-rich plasma and cellular matrices deliver biologics to deep or avascular wound beds. Limited reimbursement coverage constrains uptake in both national markets.
- Oral:Nutritional supplements and pharmacological adjuvants support systemic wound healing processes.
- Others:Negative pressure wound therapy and hyperbaric oxygen represent device-based delivery modalities.
Topical administration captures volume share; device-integrated delivery climbs fastest in hospital settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Randstad metropolitan cluster, where aging demographics and diabetes prevalence drive specialized wound care network expansion across Dutch and Belgian border regions.
Netherlands
The Randstad region encompassing Amsterdam, Rotterdam, The Hague and Utrecht anchors Dutch demand through dense specialized wound care networks serving diabetic foot ulcer populations. Zorginstituut Nederland reimbursement protocols favor post-acute monitoring outside institutional settings, accelerating home care channel development. Dutch wound clinics in Rotterdam and Utrecht standardize silver-ion and PHMB-impregnated dressings as frontline infection prevention tools.
Belgium
Flemish Diamond cities including Leuven, Antwerp and Ghent concentrate Belgian procurement through academic medical centers and tertiary care networks. INAMI/RIZIV tariff schedules for advanced dressings diverge from Dutch equivalents, creating navigation complexity for cross-border suppliers. Belgian diabetes centers in Brussels and Antwerp prioritize antimicrobial dressing portfolios under tightened Federal Agency for Medicines and Health Products vigilance mandates.
Germany
Borderland demand from North Rhine-Westphalia and Rhineland-Palatinate influences Belgian logistics networks and supplier distribution strategies. German BfArM regulatory standards for CE-marked devices create reference points for Belgian and Dutch quality system investments. Aachen and Cologne medical technology clusters supply raw materials and polymer substrates to dressing manufacturers serving the Low Countries.
France
ANSM regulatory frameworks for advanced wound care products inform Belgian Federal Agency compliance strategies through shared linguistic and procedural heritage. Lille and French Flanders wound care networks create cross-border patient flows into Belgian specialized clinics. French hospital purchasing consortia benchmark pricing that Dutch and Belgian procurement managers reference in tender negotiations.
United Kingdom
Post-Brexit customs friction reshapes supply chain routing for dressing manufacturers serving Belgium and Netherlands through previously UK-based distribution hubs. MHRA regulatory divergence from EU MDR creates parallel evidence generation requirements for suppliers maintaining UK market access. London and Southeast England wound care research networks influence clinical protocol adoption in Dutch academic hospitals.
Belgium and Netherlands Advanced Wound Care Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers extend antimicrobial and silicone-foam convergence across hospital and home care channels. Market structure tilts toward consolidated procurement leverage, with hospital purchasing consortia in the Randstad and Flemish Diamond compressing supplier negotiation positions. Three archetypes define competitive positioning: integrated wound care system providers, specialized antimicrobial dressing developers, and silicone adhesive technology leaders. M&A activity and strategic partnerships represent the dominant competitive moves, with manufacturers acquiring complementary dressing technologies to fill portfolio gaps.
Within the integrated system provider tier, Smith & Nephew and Mölnlycke Health Care occupy positions that exemplify full-spectrum wound care capability. Hartmann Group anchors the antimicrobial specialization vector through portfolio depth in infection-prevention substrates. These three entities represent the competitive anchors against which mid-tier manufacturers and regional specialists benchmark quality system investments and clinical evidence generation.
| Leading Market Players |
|---|
| Smith & Nephew |
| ConvaTec |
| Mölnlycke Health Care |
| 3M |
| Coloplast |
| B. Braun |
| Johnson & Johnson Services |
| Medtronic |
| Hartmann Group |
| Others |
Value Chain & Pricing Dynamics
Silicone raw material costs cascade through hydrophilic polyurethane foam dressing production, compressing margins at mid-tier manufacturers while premium suppliers in Belgium and the Netherlands defend position through backward integration into polymer substrate manufacturing. Hospital purchasing consortia in the Randstad and Flemish Diamond exploit this supplier stratification to extract volume concessions on antimicrobial dressing contracts.
Pricing Analysis
Volume concentrates in standard-grade foam dressings while antimicrobial variants capture margin premiums through infection-prevention certification tiers. Three-tier pricing structure across premium silicone-adhesive, standard acrylic-bonded, and economy gauze-based levels reflects EU MDR compliance investment differentials. Cost compression in standard foam tiers is intensifying because petrochemical feedstock volatility feeds through polymer costs. Home care channels exhibit highest price sensitivity; hospital procurement committees prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Reverse logistics for expired antimicrobial dressings and recalled silicone-foam products flow through specialized medical waste processors in Germany and the Netherlands, with refurbishment limited to repackaging undamaged returns. Hydrophilic polyurethane raw materials draw from petrochemical complexes in Germany, Belgium, and the Netherlands; silver-ion substrates hinge on electroplating specialists in Switzerland and Germany. Single-source vulnerability concentrates in PHMB-impregnated nonwoven suppliers. Distribution runs through hospital purchasing consortia and wound clinic networks serving the Randstad metropolitan cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines are forcing consolidation as smaller manufacturers lack capital for renewed clinical investigations and quality system upgrades. Market structure favors integrated players with antimicrobial and silicone-foam capabilities.
For Market Incumbents: Anticipate biosynthetic skin substitute encroachment on deep chronic wound applications by accelerating silicone-foam convergence R&D and securing captive supply of silver-ion substrates through upstream partnerships. Defend hospital contract renewals in Leuven and Amsterdam academic centers by bundling negative pressure wound therapy systems with dressing portfolios. For New Entrants and Emerging Players: EU MDR in Belgium and the Netherlands opens a window for specialized home care dressing developers who can navigate Zorginstituut Nederland reimbursement codes for patient-administered systems. Target Dutch long-term care channels with simplified application mechanics and color-change indicators. Pursue white-label manufacturing partnerships with established CE-marked suppliers to bypass 12-18 month regulatory timelines. For Investors and Strategic Acquirers: Hospital purchasing consortia consolidation in the Randstad is the leading indicator that mid-tier antimicrobial dressing manufacturers face margin compression and become acquisition targets. Five-to-ten year viability rests on EU MDR compliance completion and silicone chemistry expertise. Monitor Belgian Federal Agency vigilance enforcement actions as early signals of quality system differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance separates viable suppliers from distressed assets in Belgian tenders. |
| Hospital System Partnership | Integrated care networks in Amsterdam and Rotterdam consolidate procurement leverage. |
| Backward Integration | Captive silicone substrate production defends margin against petrochemical volatility. |
| Reimbursement Strategy | INAMI/RIZIV and Zorginstituut Nederland tariff navigation unlocks cross-border pricing. |
| Software Companion Development | Digital wound monitoring platforms differentiate dressing portfolios in home care channels. |
Study Parameters
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare-equivalent data underwrites the qualitative findings on antimicrobial dressing adoption rates. Primary interviews with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from EU MDR filings, EMA vigilance reports, and hospital procurement tender records. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, application, and delivery mode dimensions.
Comparable-period anchoring to historical wound care expenditure patterns establishes baseline growth trajectories across the projection horizon. Segmentation modeling incorporates product material chemistry, care setting infrastructure, wound severity classification, and regional reimbursement framework. CAGRs derive from exponential smoothing of validated adoption curves, with inputs including diabetes prevalence projections for the Randstad, surgical procedure volumes at Belgian tertiary centers, and home care reimbursement policy trajectories.
The model assumes a particular technology adoption path; alternative pathways for biosynthetic skin substitutes displacing advanced dressings in deep chronic wounds would alter the outlook. Forecasts reflect assumptions regarding EU MDR notified body capacity, polymer feedstock price stability, and reimbursement harmonization progress. Practitioners should monitor Belgian Federal Agency enforcement intensity and Dutch Zorginstituut Nederland tariff revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Bioactive Wound Care Market
Wound Care
Europe Compression Bandages Market
Wound Care
Animal Wound Care Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Acute Wound Care Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
South Korea Wound Care Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Wound Care Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
US Wound Care Management Devices Market