
 Pharmaceutical Glass Ampoules Market | 2026-2036
Pharmaceutical Glass Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Glass Ampoules Market Outlook
Hospital and pharmacy procurement channels is reconfiguring around direct manufacturer partnerships to secure supply continuity for critical injectables. Gerresheimer AG leverages its integrated borosilicate glass furnace network to control upstream material quality. SCHOTT AG anchors European supply through its specialized FIOLAX tubing operations. Nipro Corporation competes across Asia-Pacific markets with standardized volume production lines.
Pharmaceutical glass ampoules are sealed cylindrical containers manufactured from borosilicate or soda-lime glass, typically ranging from 1 mL to 20 mL, designed for single-dose sterile liquid drug storage and administration. Type I borosilicate glass dominates biologics packaging due to its hydrolytic resistance and minimal alkali leaching. Standard Ampoules remain the volume base for generic injectables, while Specialty Ampoules command premium positioning for orphan drugs and temperature-sensitive formulations. Blow-Fill-Seal technology is displacing conventional filling in high-volume parenteral segments.
FDA enforces container closure integrity standards under 21 CFR 211.94, while the EU MDR mandates traceability and leachable testing for glass primary packaging in Class III devices. USP Chapter 660 and EP 3.2.1 define hydrolytic resistance grading, directly determining which glass types qualify for biologics versus small-molecule applications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as divergent testing protocols will reshape qualification timelines and regional sourcing decisions.
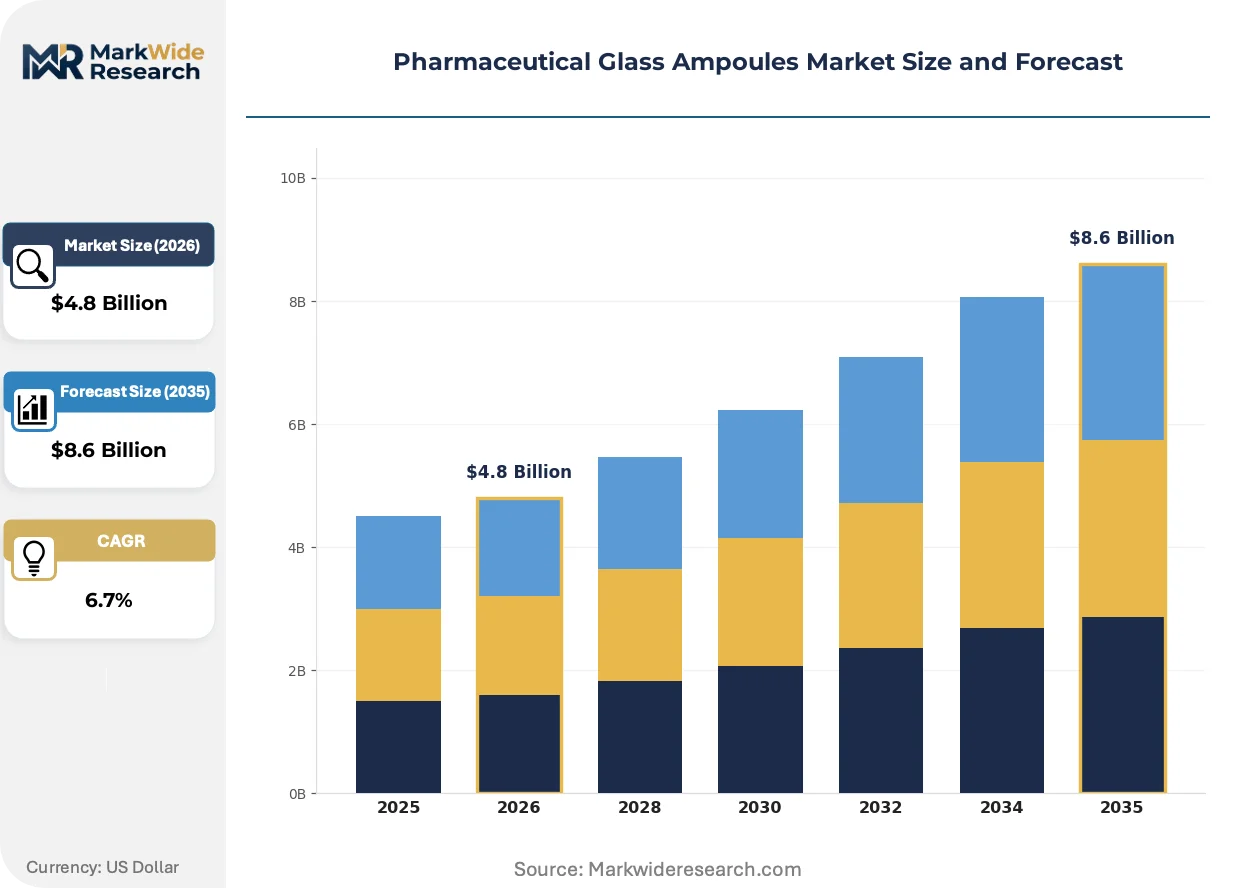
Market Dynamics
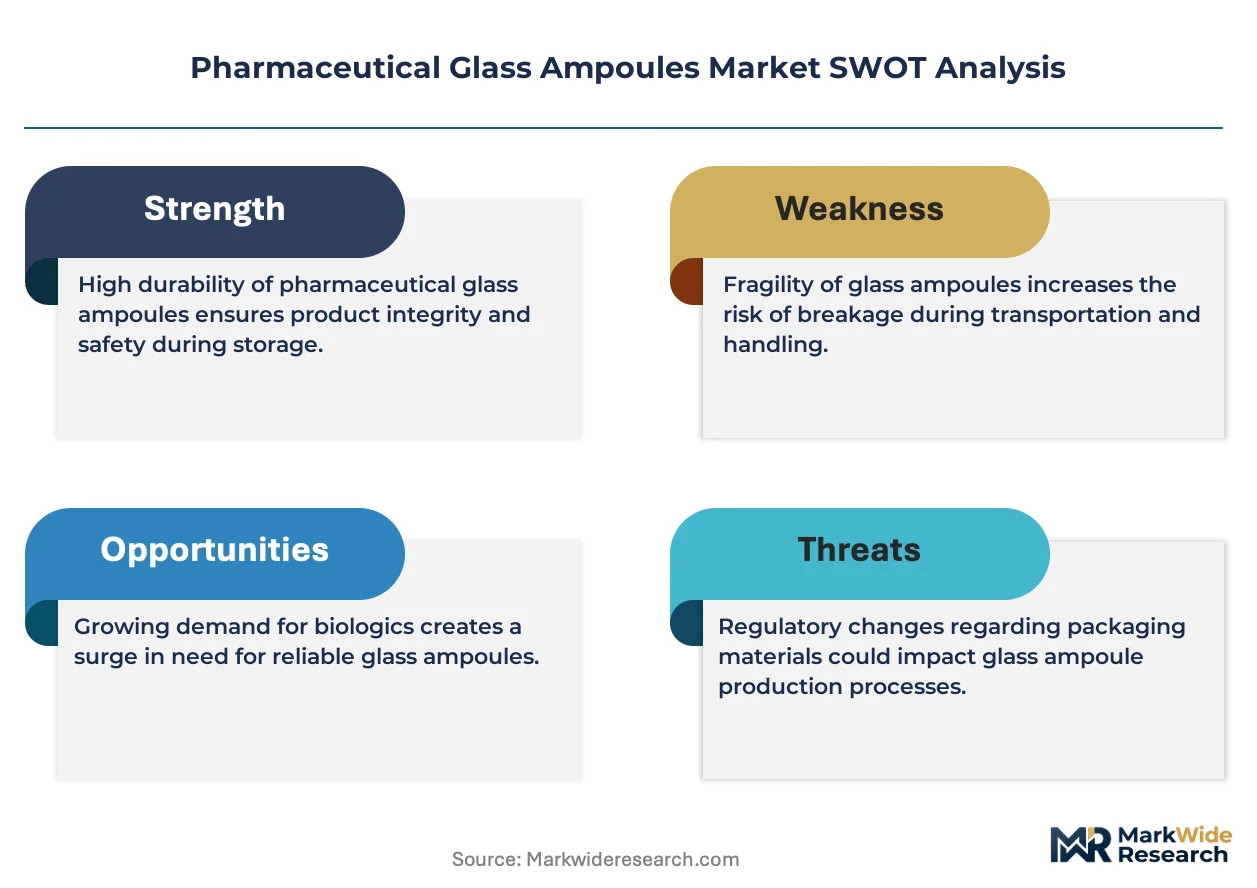
EU MDR and USP Chapter 660 revisions are forcing pharmaceutical glass ampoule manufacturers to requalify entire product lines, compressing timelines for biologics packaging certification.
Growth Catalysts
- Biologics expansion:Peptide and mRNA injectables require Type I borosilicate hydrolytic resistance, pulling demand from oncology and immunology pipelines.
- EU MDR traceability mandates:Class III device classification for glass primary packaging creates compliance-driven replacement cycles across European sterile fill-finish facilities.
- German production clustering:Specialized borosilicate furnace networks in Mainz and Mitterteich concentrate technical expertise for premium ampoule tubing supply.
Market Restraints
- Borosilicate raw material concentration:High-purity sand and alumina sourcing concentrates in limited geographies, exposing manufacturers to energy-cost volatility.
- Specialty glass furnace capex intensity:New borosilicate melting capacity requires nine-figure investments with decade-long depreciation horizons.
- Blow-Fill-Seal substitution:Plastic BFS technology captures high-volume parenteral segments where glass ampoule breakage rates prove economically prohibitive.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad seek qualified Type I ampoule supply for export-oriented biologics filling.
- Orphan drug packaging:Small-batch specialty ampoules for ultra-rare disease therapies command premium positioning outside commodity generic injectables.
- Cold-chain ampoule innovation:Thermal shock-resistant formulations enable direct-to-freezer storage for temperature-sensitive biologics, collapsing traditional secondary packaging layers.
Industry Challenges
- Pharmacopeial harmonization friction:Divergent USP, EP, and JP hydrolytic resistance testing protocols force redundant qualification studies for multi-regional product registrations.
- Container closure integrity validation:Vacuum decay and dye ingress method standardization across FDA and EMA expectations extends submission preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Glass Ampoules Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow-Fill-Seal, Standard Ampoules, Customized Ampoules, Specialty Ampoules Material: Type I Glass, Type II Glass, Type III Glass, Borosilicate Glass Closure Type: Snap-off, Screw Cap, Crimped, Open Vial End User: Pharmaceutical Companies, Biotechnology Firms, Contract Manufacturing Organizations, Research Laboratories |
| Companies Covered | SGD Pharma, Bormioli Pharma, Gerresheimer AG, Corning Incorporated, West Pharmaceutical Services, SCHOTT AG, Nipro Corporation, Piramal Glass, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Glass Ampoules Market Strategic Shifts
Glass ampoule manufacturing is converging with advanced inspection and forming technologies that compress defect rates while accommodating smaller batch sizes for personalized medicine.
Ready-to-use (RTU) pre-sterilized ampoules are collapsing traditional fill-finish workflows by eliminating upstream washing and depyrogenation steps. Biologics manufacturers in Germany and Switzerland are adopting RTU formats for clinical trial materials and commercial launch sequences. This shift compresses time-to-market for novel injectables while transferring sterilization liability to packaging suppliers.
EMA's tightened leachable and extractable testing guidelines under the EU MDR are forcing reformulation of glass surface treatments. Manufacturers must now document elemental impurity profiles across sulfur-treated, ammonium-treated, and untreated ampoule surfaces. Small-molecule injectable producers in Southern Europe are responding by consolidating suppliers to those with dedicated pharmacopeial testing laboratories.
Hospital procurement consortia are consolidating purchasing power through direct manufacturer partnerships that bypass traditional distribution intermediaries. German university hospital networks now negotiate multi-year ampoule supply agreements with volume commitments tied to fill-finish capacity expansion. This channel compression is most visible in Benelux and Nordic markets where public procurement centralization has advanced furthest.
Pharmaceutical Glass Ampoules Market Segmentation
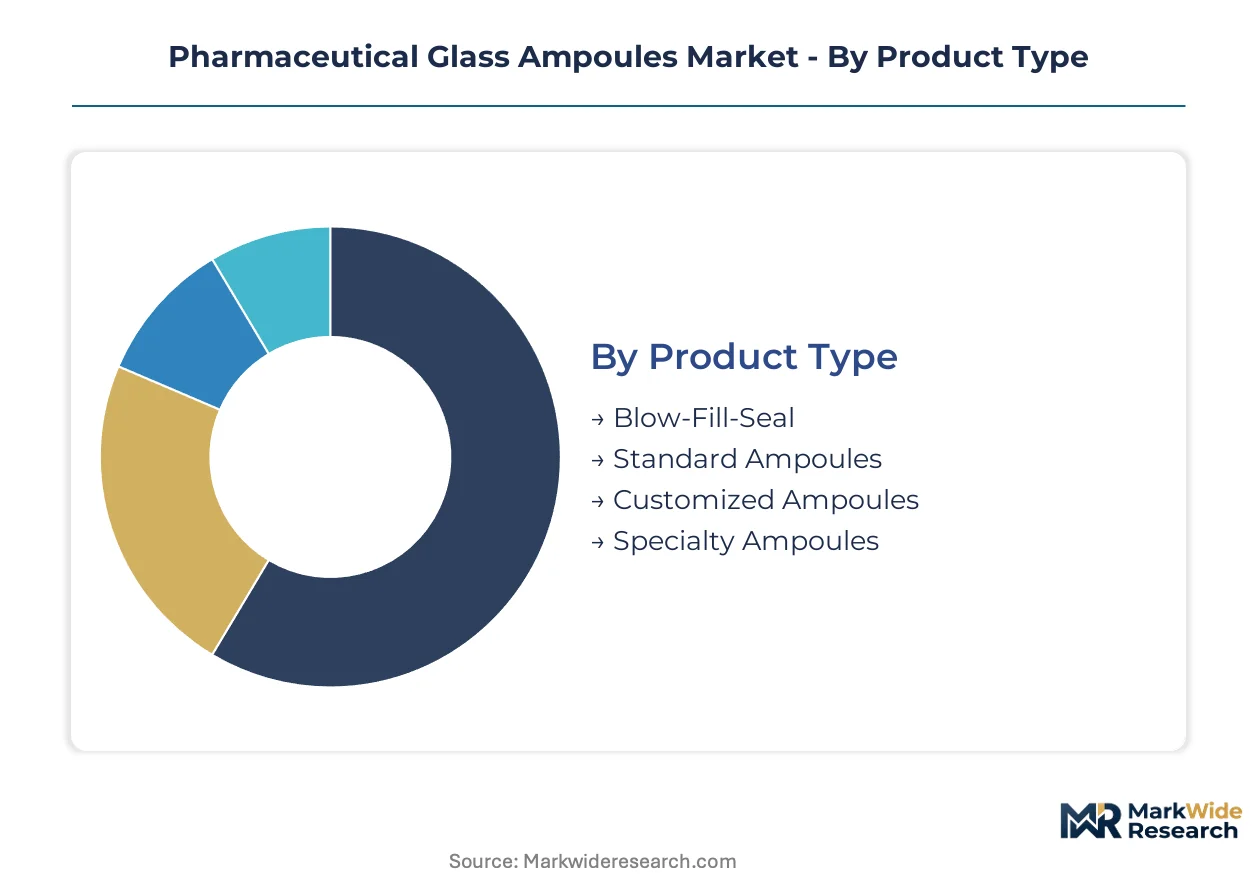
Glass ampoule segmentation determines qualification pathways for biologics versus small-molecule applications. Material classification and closure mechanics directly dictate regulatory acceptance under USP Chapter 660 and EU MDR traceability mandates.
Product Type:
After-sales service intensity varies sharply across forming technologies, with Blow-Fill-Seal demanding continuous technical support and Standard Ampoules requiring minimal field intervention.
- Standard Ampoules:Conventional flame-sealed cylindrical containers manufactured through ampoule-forming machines. Demand concentrates in Indian and Chinese generic injectable facilities where cost minimization governs procurement. These facilities prioritize volume supply security over customization services.
- Specialty Ampoules:Engineered for temperature-sensitive biologics with enhanced hydrolytic resistance and surface treatments. German and Swiss biologics manufacturers specify these for orphan drug launches requiring documented leachable profiles. Technical qualification support extends through product lifecycle.
- Blow-Fill-Seal:Integrated forming-filling-sealing technology displacing conventional ampoules in high-volume parenteral segments. Plastic polymer construction eliminates glass breakage risk in hospital settings.
- Customized Ampoules:Patient-specific volumes and printing for clinical trial materials and personalized medicine workflows. Contract development organizations in Hyderabad and Ahmedabad drive specification complexity.
Standard Ampoules holds the largest share; momentum sits with Specialty Ampoules.
Material:
Cost tier stratification separates premium borosilicate formulations from commodity soda-lime alternatives, with qualification expense determining accessible market segments.
- Type I Glass:Borosilicate composition with hydrolytic resistance meeting USP Chapter 660 and EP 3.2.1 standards for parenteral biologics. Peptide and mRNA injectable manufacturers in Germany and Switzerland mandate this grade for regulatory submissions. Alkali leaching minimization protects protein stability.
- Borosilicate Glass:High-purity silica-alumina-borax matrix providing thermal shock resistance for cold-chain distribution. Direct-to-freezer storage applications in Nordic hospital networks eliminate secondary packaging layers. Furnace capacity constraints in Mainz and Mitterteich limit supply expansion.
- Type II Glass:Surface-treated soda-lime glass with improved hydrolytic resistance for less sensitive small-molecule injectables. Southern European generic manufacturers specify this grade for cost containment.
- Type III Glass:Untreated soda-lime composition for non-parenteral or oral liquid applications where hydrolytic resistance requirements relax. Limited pharmaceutical adoption outside veterinary markets.
Type I Glass dominates biologics qualification; Borosilicate Glass is expanding most quickly through cold-chain innovation.
Closure Type:
Application context determines closure selection, with oncology emergency settings demanding instant access and multi-dose vials requiring resealability.
- Snap-off:Scored glass neck enabling single-motion opening without tools. Emergency medicine and anesthesia applications in German university hospital networks specify this format for rapid drug administration. Breakage risk necessitates protective packaging.
- Crimped:Aluminum seal over rubber stopper permitting needle penetration for multi-dose withdrawal. Hospital pharmacy compounding operations in Benelux markets favor this format for dose flexibility. Container closure integrity validation extends FDA submission timelines.
- Screw Cap:Threaded plastic or metal closure for non-sterile reconstitution workflows. Research laboratory applications predominate.
- Open Vial:Unsealed format for immediate filling in aseptic processing environments. Contract manufacturing organizations employ this for specialized batch production.
Snap-off holds the largest share; momentum sits with Crimped through multi-dose biologics expansion.
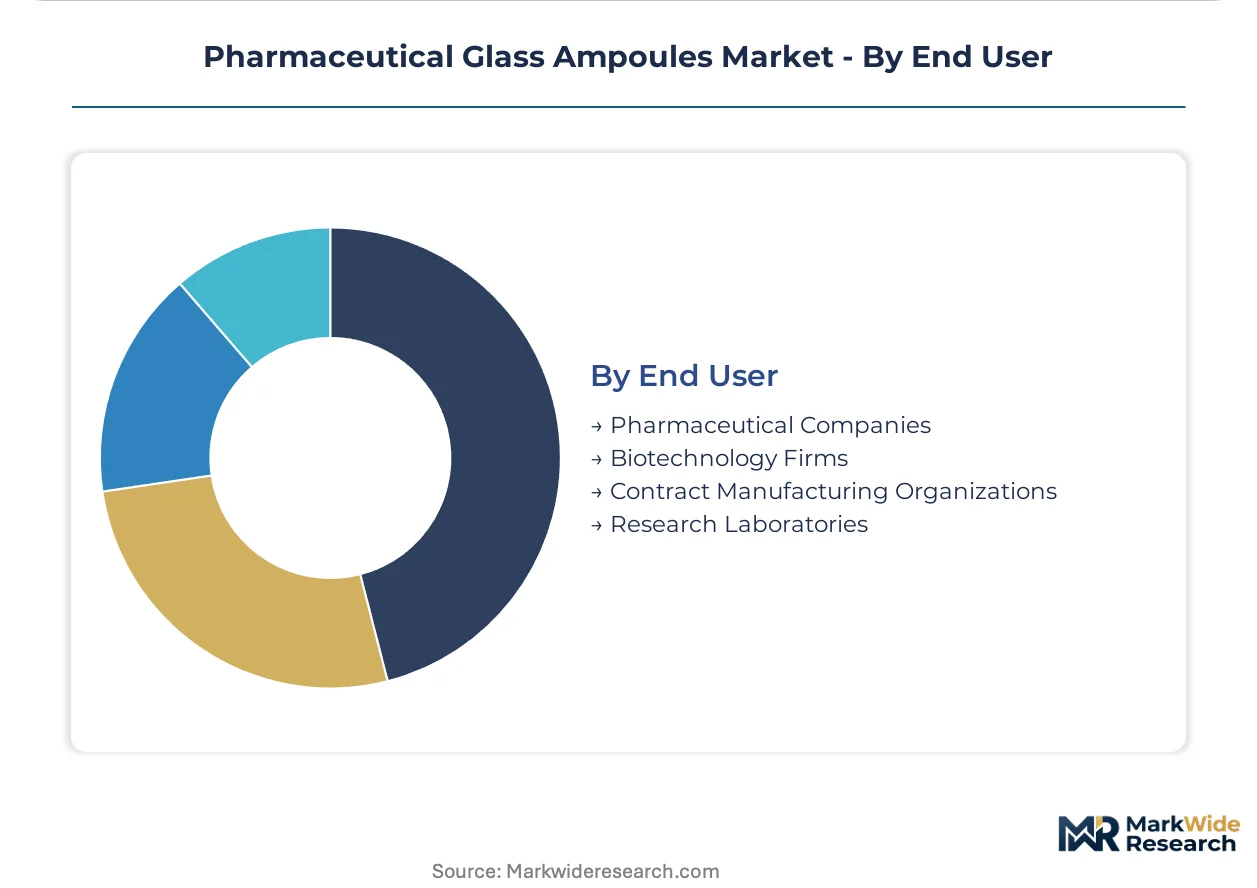
End User:
Customer type dictates procurement scale and technical service requirements, with biotechnology firms demanding extensive qualification support versus standardized pharmaceutical purchasing.
- Pharmaceutical Companies:Large-volume purchasers of standardized ampoules for established injectable portfolios. Direct manufacturer partnerships in German hospital procurement consortia bypass distribution intermediaries. Multi-year supply agreements tie volume commitments to fill-finish capacity expansion.
- Biotechnology Firms:Emerging biologics developers requiring Type I borosilicate ampoules with documented extractable profiles. Swiss and German clinical-stage companies specify ready-to-use formats to compress time-to-market. Pharmacopeial testing laboratory access determines supplier selection.
- Contract Manufacturing Organizations:Indian CDMOs in Hyderabad and Ahmedabad seek qualified Type I supply for export-oriented biologics filling. Regulatory divergence between FDA, EMA, and CDSCO forces redundant qualification studies.
- Research Laboratories:Small-batch purchasers for preclinical and clinical trial materials. Customized volume and printing specifications predominate.
Pharmaceutical Companies holds the largest share; momentum sits with Contract Manufacturing Organizations through Indian biologics export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main logistics corridor connects German glass manufacturing clusters to European pharmaceutical fill-finish networks. Container traffic through Rotterdam and Hamburg ports channels borosilicate raw materials to tubing furnaces in Mainz and Mitterteich.
Germany
Biologics manufacturers in Baden-Württemberg and Bavaria specify Type I borosilicate ampoules for peptide and mRNA injectable portfolios. The EU MDR Class III device classification for glass primary packaging forces requalification cycles across sterile fill-finish facilities. Gerresheimer AG and SCHOTT AG anchor specialized production clusters in Mainz and Mitterteich, controlling upstream furnace capacity for premium tubing supply.
United States
Oncology and immunology pipeline expansion drives Type I glass qualification for sensitive biologic formulations. FDA enforces container closure integrity standards under 21 CFR 211.94, extending submission preparation timelines for multi-regional registrations. The Boston-Cambridge biotechnology corridor concentrates demand for ready-to-use ampoule formats in clinical trial materials.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad seek qualified Type I ampoule supply for export-oriented biologics filling. CDSCO alignment with FDA and EMA standards forces redundant pharmacopeial testing for multi-regional product registrations. The Hyderabad-Pharma City cluster concentrates technical qualification capacity for international regulatory submissions.
Switzerland
Clinical-stage biologics developers mandate documented extractable profiles for orphan drug packaging specifications. Swissmedic pharmacopeial testing requirements align with EMA leachable guidelines under tightened EU MDR surface treatment documentation. The Basel biopharmaceutical corridor concentrates demand for small-batch specialty ampoules with thermal shock-resistant cold-chain formulations.
China
Domestic biologics manufacturers expand Type I borosilicate adoption for insulin and vaccine injectable portfolios. NMPA harmonization with USP Chapter 660 and EP 3.2.1 hydrolytic resistance grading determines glass qualification pathways. The Yangtze River Delta pharmaceutical manufacturing belt concentrates fill-finish capacity for both domestic consumption and export markets.
Pharmaceutical Glass Ampoules Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers anchored by specialized furnace operators, diversified packaging conglomerates, and regional volume producers. German and Japanese manufacturers concentrate premium borosilicate tubing capacity through captive furnace networks, while Indian and Chinese competitors scale standardized soda-lime production for cost-sensitive generic injectables. Strategic differentiation centers on backward integration into borosilicate raw material refining and pharmacopeial testing laboratory accreditation. Capacity expansion and direct procurement partnerships with hospital consortia represent the dominant competitive moves reshaping channel configuration.
Among European furnace-based specialists, Gerresheimer AG and SCHOTT AG occupy positions defining premium-tier supply for biologics qualification. SGD Pharma, Bormioli Pharma, and Piramal Glass represent the diversified packaging conglomerate archetype spanning multiple primary packaging categories beyond glass ampoules. Nipro Corporation anchors Asian volume production for standardized parenteral applications. These named entities exemplify how geographic concentration of technical expertise and regulatory qualification capacity determines accessible market segments.
| Leading Market Players |
|---|
| SGD Pharma |
| Bormioli Pharma |
| Gerresheimer AG |
| Corning Incorporated |
| West Pharmaceutical Services |
| SCHOTT AG |
| Nipro Corporation |
| Piramal Glass |
| Stevanato Group |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German borosilicate furnace networks concentrates pricing power among Gerresheimer AG and SCHOTT AG while forcing buyers into long-term offtake commitments with volume-discount tiering. This structural chokepoint determines both the premium spread for Type I glass qualification and the geographic shape of supply chain financing arrangements.
Pricing Analysis
Volume-discount tiering structures procurement across pharmaceutical glass ampoules, with three-tier pricing separating Type I borosilicate biologics grades from Type II surface-treated soda-lime and Type III untreated alternatives. Price differentiation hinges on hydrolytic resistance certification under USP Chapter 660 and furnace capacity scarcity in Mainz and Mitterteich. Pricing pressure stems from Blow-Fill-Seal plastic substitution capturing high-volume parenteral segments. Generic injectable manufacturers in India and China exhibit highest price sensitivity, while Swiss and German biologics firms prioritize qualification certainty over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for hospital procurement consortia negotiating multi-year ampoule agreements with furnace operators. Raw material sourcing draws from high-purity sand deposits in Germany and alumina refineries in China and Australia, with borax supply concentrating in Turkey and the United States. Single-source vulnerability pervades premium tubing supply given furnace capacity constraints and decade-long depreciation horizons. Distribution runs through Rotterdam and Hamburg port channels feeding Rhine-Main logistics corridors to sterile fill-finish networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as Blow-Fill-Seal technology erodes glass ampoule economics in high-volume hospital segments. Plastic polymer alternatives threaten commodity generic injectable volumes while biologics qualification requirements protect premium tiers.
For Market Incumbents: Entrench furnace capacity control through captive borosilicate tubing operations in Mainz and Mitterteich, locking in supply security for Type I glass qualification. Expand pharmacopeial testing laboratory accreditation to capture EU MDR traceability mandates and compress competitor certification timelines. Defensive consolidation around backward integration into high-purity sand refining protects margin structures against raw material volatility.
For New Entrants and Emerging Players: Indian CDMO corridors in Hyderabad and Ahmedabad represent the most penetrable entry point for qualified Type I ampoule supply serving export-oriented biologics filling. Orphan drug packaging for ultra-rare disease therapies offers white-space positioning outside commodity generic competition. Go-to-market execution should emphasize documented extractable profiles and ready-to-use format availability to compress pharmaceutical customer time-to-market.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors furnace-integrated specialists with pharmacopeial testing capabilities over diversified packaging conglomerates. Long-term viability across the next decade hinges on biologics pipeline expansion and cold-chain ampoule innovation. Acquisition targeting should prioritize German and Japanese borosilicate tubing operators with EMA and FDA qualification track records. Monitor Blow-Fill-Seal penetration rates in oncology and emergency medicine segments as inflection indicators for glass ampoule demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Furnace Capacity | Gerresheimer AG and SCHOTT AG control upstream material quality through captive Mainz and Mitterteich operations. |
| Pharmacopeial Testing Laboratory Accreditation | EMA leachable guidelines under EU MDR force documented elemental impurity profiles for glass surface treatments. |
| Ready-to-Use Pre-Sterilized Format Expansion | Swiss and German biologics manufacturers adopt RTU ampoules to eliminate upstream washing and depyrogenation steps. |
| Direct Hospital Consortium Partnerships | German university hospital networks negotiate multi-year supply agreements bypassing traditional distribution intermediaries. |
| Cold-Chain Thermal Shock-Resistant Formulation | Nordic hospital networks enable direct-to-freezer storage for temperature-sensitive biologics, collapsing secondary packaging layers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile fill-finish facility managers, pharmaceutical packaging procurement leads, regulatory affairs specialists, and borosilicate furnace operations directors. Secondary validation drew from FDA 21 CFR 211.94 filings, EMA MDR Class III device submissions, USP Chapter 660 and EP 3.2.1 pharmacopeial standards, and hospital procurement database records. Bottom-up volume modeling triangulated against top-down market sizing across material grade, closure type, and end-user segments.
Calibration approaches anchored volume and value outputs to observed furnace capacity utilization rates, fill-finish facility expansion announcements, and biologics pipeline advancement data across the analysis window. Segmentation dimensions modeled included product type, material classification, closure mechanics, end-user category, and regional regulatory cluster. CAGRs derived from regression analysis against biologics approval velocity and generic injectable volume trends, with cross-reference to borosilicate raw material cost indices and energy price volatility.
Practitioners should monitor EU MDR harmonization progress, Blow-Fill-Seal technology adoption curves, and borosilicate furnace capacity expansion announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market