
 Global Blood Pressure Cuffs Market | 2026-2036
Global Blood Pressure Cuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Pressure Cuffs Market Foresight
Hospital procurement channels in the United States and Western Europe is tilting toward integrated device vendors with captive supply chains. OMRON Corporation leverages its oscillometric technology leadership to dominate home monitoring segments across Asia. Baxter International sustains its clinical diagnostics presence through deep hospital relationships in North America. Cardinal Health competes on distribution scale, anchoring its position through GPO contracts that lock in multi-year cuff replenishment cycles.
Blood pressure cuffs are inflatable bladders encased in nylon or polyester fabric, designed to occlude arterial blood flow for systolic and diastolic pressure measurement, with bladder dimensions standardized to limb circumference ranges for accuracy. Digital cuffs represent the fastest-expanding product type as oscillometric algorithms replace manual auscultation in non-clinical settings, while ambulatory cuffs command premium positioning due to ABPM protocol requirements. Among end users, diagnostic centers concentrate volume demand through bulk replacement cycles, whereas home health monitoring generates the highest unit velocity through retail pharmacy and e-commerce channels.
FDA 510(k) clearance requirements and the EU MDR's tightened clinical evidence standards for Class IIa medical devices shape product development timelines and market access costs for cuff manufacturers. The EPA's mercury disposal regulations have accelerated phase-out of mercury-based systems, redirecting procurement toward aneroid and digital alternatives. Stakeholders must monitor how smartphone-integrated cuff platforms navigate emerging software-as-medical-device classifications in multiple jurisdictions.
Market Dynamics
Hospital procurement consolidation and home health monitoring adoption are compressing the traditional two-channel structure, forcing manufacturers to simultaneously serve high-volume institutional tenders and direct-to-consumer retail velocity.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for oscillometric digital cuffs are expanding eligible product submissions from Asian manufacturers seeking US market entry.
- Germany's ambulatory monitoring reimbursement:Expanded ABPM coverage under statutory health insurance is driving diagnostic center procurement of multi-day wearable cuff systems.
- Polyester-nylon fabric substitution:Advanced textile manufacturing in Vietnam and Bangladesh is reducing bladder encapsulation costs while maintaining inflation pressure tolerances.
Market Restraints
- EU MDR clinical evidence requirements:Tightened Class IIa device documentation is extending certification timelines and inflating regulatory consulting expenditures for smaller manufacturers.
- Semiconductor input concentration:Pressure sensor chip fabrication concentrates in Taiwan and South Korea, exposing digital cuff producers to single-source supply vulnerability.
- Mercury disposal compliance costs:EPA hazardous waste regulations impose ongoing liability for healthcare systems maintaining legacy sphygmomanometer fleets.
Strategic Opportunities
- India's diagnostic center networks:Tier-2 and Tier-3 city expansion creates unserved demand for mid-range aneroid and digital cuff systems outside metro hospital procurement.
- Smartphone-integrated cuff platforms:Bluetooth-enabled home monitoring devices are capturing pharmacy channel shelf space previously dominated by standalone digital units.
- Japan's Silver ICT promotion:METI subsidies for elderly health technology adoption are reducing consumer price sensitivity for premium home monitoring equipment.
Industry Challenges
- Biomedical calibration technician scarcity:Hospital biomedical engineering departments face hiring gaps for aneroid gauge verification and digital algorithm validation protocols.
- Multi-jurisdiction software-as-medical-device classification:Cuff manufacturers with app-connected products must navigate divergent FDA, EU MDR, and PMDA digital health frameworks simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Pressure Cuffs Market |
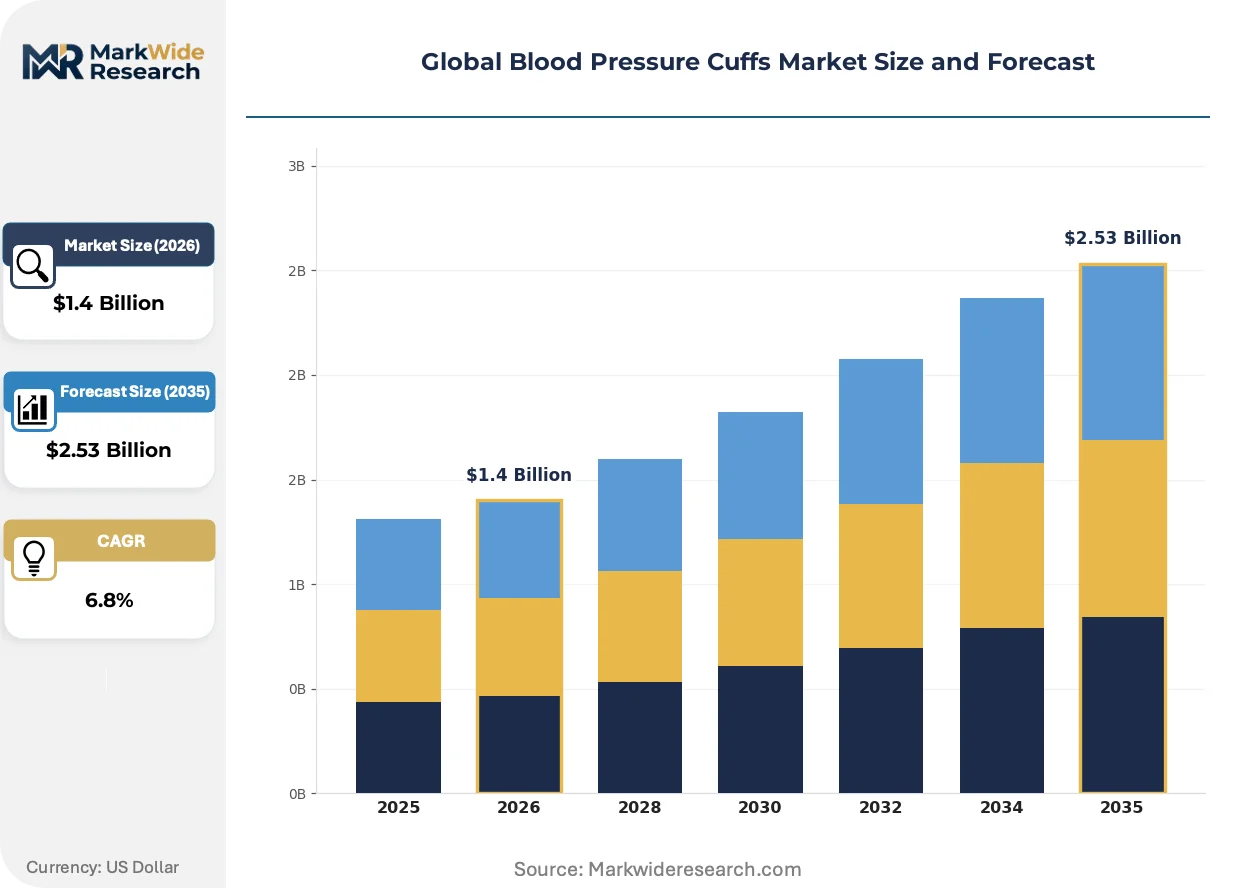
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cuffs, Digital Cuffs, Aneroid Cuffs, Ambulatory Cuffs, Neonatal Cuffs Application: Home Health Monitoring, Clinical Diagnostics, Sports Medicine, Emergency Response, Veterinary Care End User: Hospitals, Diagnostic Centers, Nursing Homes, Ambulance Services, Research Laboratories Technology: Cuff-Based Sphygmomanometers, Oscillometric Devices, Mercury-Based Systems, Wireless Bluetooth Cuffs, Smartphone-Integrated Cuffs |
| Companies Covered | OMRON Corporation, Baxter International, McKesson Corporation, Cardinal Health, GE Healthcare, Koninklijke Philips, SunTech Medical, American Diagnostic Corporation, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Pressure Cuffs Market Shifts & Advancements
Algorithmic measurement and connected health architectures are displacing mechanical precision as the primary value driver, redefining competitive advantage around data integration rather than hardware durability.
Photoplethysmography-based cuffless blood pressure estimation is rendering obsolete the inflatable bladder paradigm for continuous monitoring applications. Wearable technology developers in Silicon Valley and Shenzhen are integrating optical sensors into smartwatches and earphones for passive vascular assessment. This shift is rendering obsolete the traditional replacement cycle economics of disposable cuff procurement in employer wellness programs.
REACH regulation amendments restricting persistent organic pollutants in medical textiles are compelling fabric suppliers to reformulate nylon coating compounds. German and French notified bodies are enforcing expanded material safety testing for cuff bladders and Velcro fastening systems. Asian contract manufacturers are responding by shifting encapsulation material sourcing to EU-registered chemical suppliers, compressing margin structures for economy-tier product lines.
Direct-to-consumer subscription models for cuff replacement and calibration services are fragmenting the traditional hospital-centric revenue architecture. Pharmacy chains in the United States and United Kingdom are bundling digital cuffs with telehealth platform memberships, displacing standalone device margin with recurring software revenue. This pattern concentrates in markets with high smartphone penetration and established remote patient monitoring reimbursement codes.
Global Blood Pressure Cuffs Market Segmentation
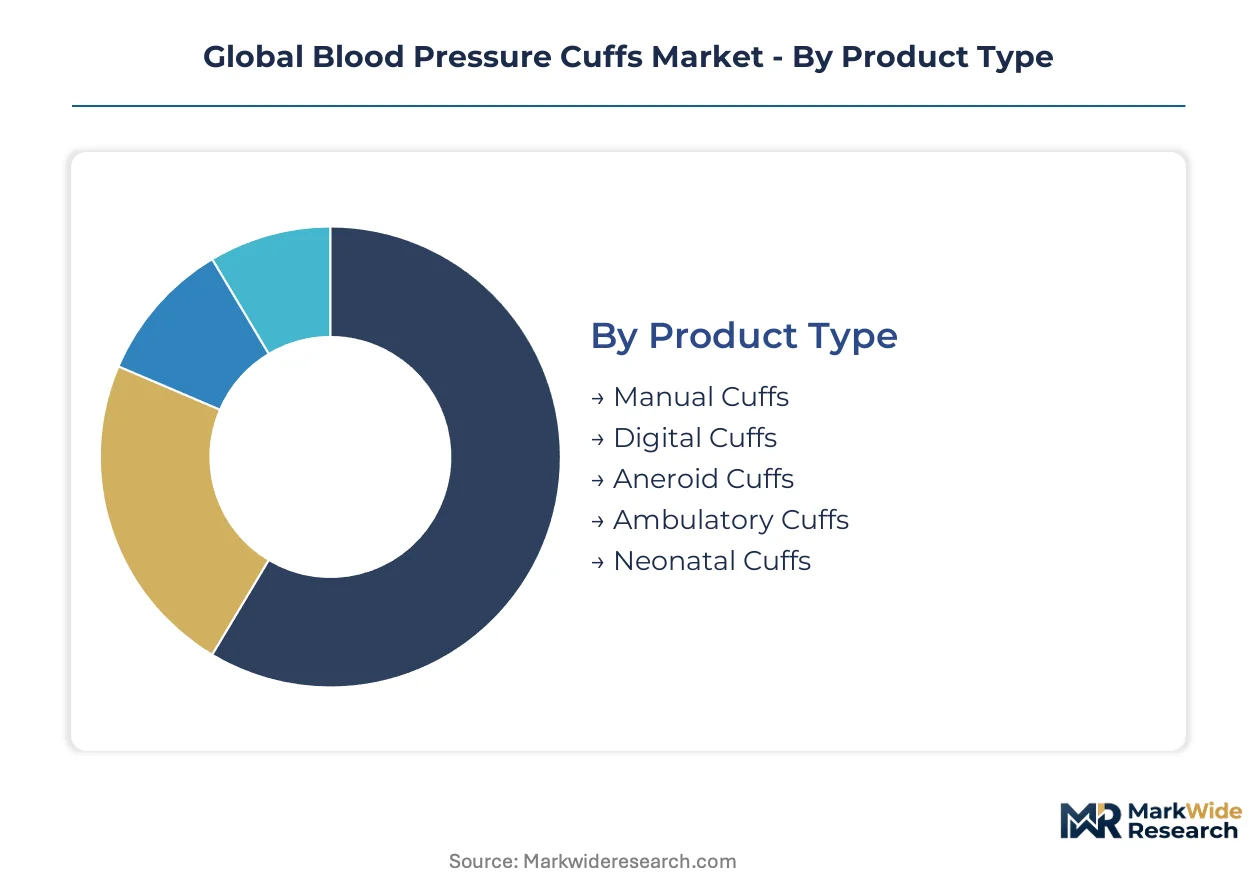
Segmentation reveals divergent replacement economics across the blood pressure cuffs landscape. Cycle times vary dramatically from daily-use home devices to decade-long hospital installations, reshaping manufacturer portfolio priorities and channel investments.
Product Type:
Replacement velocity separates commodity consumables from capital equipment, with calibration requirements and wear patterns dicting procurement frequency.
- Digital Cuffs:Oscillometric sensors embedded in nylon-encased bladders automate pressure detection without stethoscope dependency. Pharmacy chains in Germany and Japan are expanding retail shelf space for Bluetooth-enabled home units as aging populations adopt self-monitoring protocols.
- Ambulatory Cuffs:Multi-day wearable systems with programmable inflation schedules support ABPM diagnostic protocols. Diagnostic centers in Germany are procuring these systems under expanded statutory health insurance reimbursement for hypertension confirmation.
- Manual Cuffs:Traditional latex or PVC bladders requiring trained auscultation technique and stethoscope pairing.
- Aneroid Cuffs:Mechanical gauge systems with metal bellows and pinion mechanisms demanding biennial calibration verification.
- Neonatal Cuffs:Specialized low-pressure bladders sized for limb circumferences under 15 centimeters in NICU settings.
Aneroid cuffs dominate installed base in legacy hospital systems. Digital cuffs are where expansion concentrates fastest.
Application:
End-use setting determines accuracy requirements, portability needs, and regulatory scrutiny intensity.
- Home Health Monitoring:Consumer-grade oscillometric devices with simplified one-button operation and irregular heartbeat detection algorithms. E-commerce platforms in India and retail pharmacy networks in the United States are capturing highest unit velocity through direct-to-consumer channels.
- Clinical Diagnostics:Precision-calibrated systems meeting ISO 81060-2 accuracy protocols for hypertension diagnosis and medication titration.
- Emergency Response:Ruggedized rapid-inflation cuffs designed for pre-hospital trauma assessment and field durability.
- Sports Medicine:Portable units for athletic screening and exercise physiology monitoring in training facilities.
- Veterinary Care:Tail-cuff and limb-cuff adaptations sized for companion animal and livestock blood pressure assessment.
Clinical diagnostics commands premium pricing through certification requirements. Home health monitoring is climbing the fastest in absolute unit terms.
End User:
Procurement scale and decision authority concentrate differently across institutional hierarchies versus distributed care networks.
- Diagnostic Centers:High-throughput facilities executing bulk replacement cycles for standardized cuff inventories across multiple examination rooms. India's Tier-2 and Tier-3 city expansion is creating unserved demand for mid-range aneroid and digital systems outside metro hospital procurement channels.
- Hospitals:Integrated health systems leveraging GPO contracts for multi-year cuff replenishment tied to electronic health record implementations.
- Nursing Homes:Long-term care facilities prioritizing durability and infection-control compatible materials for resident monitoring.
- Ambulance Services:Mobile intensive care units requiring rapid-cycling cuffs with extended temperature operating ranges.
- Research Laboratories:Academic and pharmaceutical trial sites demanding NIST-traceable calibration documentation.
Hospitals anchor volume through centralized purchasing. Diagnostic centers are where geographic expansion concentrates.
Technology:
Underlying measurement principle determines regulatory classification, software liability exposure, and obsolescence risk.
- Oscillometric Devices:Algorithm-based systolic and diastolic estimation through cuff pressure oscillation analysis during deflation. FDA's streamlined 510(k) pathway for validated algorithms is accelerating Asian manufacturer submissions for US market entry.
- Smartphone-Integrated Cuffs:Bluetooth-enabled platforms transmitting measurement data to iOS and Android applications for trend visualization and physician sharing. Pharmacy chains in the United Kingdom are bundling these with telehealth memberships, displacing standalone device margins with recurring software revenue.
- Cuff-Based Sphygmomanometers:Traditional inflatable bladder systems encompassing manual, aneroid, and digital implementations.
- Wireless Bluetooth Cuffs:Intermediate connectivity tier enabling data transmission to dedicated receivers or tablet-based clinical workstations.
- Mercury-Based Systems:Gravity-dependent column manometers facing EPA hazardous waste disposal compliance costs and procurement phase-out.
Cuff-based sphygmomanometers retain largest installed base. Smartphone-integrated platforms are gaining share fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's statutory reimbursement corridors while Vietnam's textile manufacturing clusters compress encapsulation costs for economy-tier production. Japan's METI subsidies for elderly health technology create premium-tier demand elasticity unavailable in India's price-sensitive diagnostic networks.
United States
Hospital procurement consolidation through GPO contracts favors integrated device vendors with captive supply chains. FDA 510(k) pathway streamlining accelerates oscillometric digital cuff submissions from Asian manufacturers seeking market entry. The Minneapolis-St. Paul corridor anchors distribution scale for multi-year cuff replenishment tied to electronic health record implementations.
Germany
Expanded ABPM coverage under statutory health insurance drives diagnostic center procurement of multi-day wearable cuff systems. EU MDR clinical evidence requirements for Class IIa devices extend certification timelines for smaller manufacturers. The Baden-Württemberg medical technology cluster concentrates precision-calibrated system production for hypertension diagnosis protocols.
China
Hospital procurement systems concentrate volume demand through centralized tenders for standardized cuff inventories. NMPA device registration requirements shape product development timelines for oscillometric algorithm validation. Shenzhen's electronics manufacturing ecosystem supplies Bluetooth-enabled home monitoring platforms for domestic and export markets.
India
Tier-2 and Tier-3 city diagnostic center expansion creates unserved demand for mid-range aneroid and digital systems outside metro hospital channels. CDSCO medical device regulations tighten import documentation for foreign manufacturers. The Maharashtra-Gujarat pharmaceutical corridor anchors bulk replacement cycle fulfillment for high-throughput examination facilities.
Japan
METI's Silver ICT promotion reduces consumer price sensitivity for premium home monitoring equipment among aging populations. PMDA software-as-medical-device classifications complicate app-connected cuff platform approvals. The Kansai region's precision manufacturing base supplies oscillometric sensor modules for domestic and Asian export markets.
Global Blood Pressure Cuffs Market Competitive Landscape
Integrated healthcare conglomerates and specialized monitoring device manufacturers split the market along channel boundaries. Hospital procurement tilts toward vendors with deep institutional relationships and GPO contract anchoring, while retail pharmacy and e-commerce velocity favors technology specialists with consumer brand recognition. Two archetypes dominate: oscillometric technology leaders with algorithm validation capabilities, and distribution-scale operators with multi-year replenishment contract portfolios. Competitive moves concentrate on smartphone-integrated platform development and textile manufacturing cost optimization through Asian contract partnerships.
Among the named players, OMRON Corporation exemplifies the oscillometric technology archetype with established consumer health monitoring positioning, while Baxter International and Cardinal Health occupy institutional procurement roles through hospital system integration and GPO contract scale respectively. These three represent the strategic divergence between technology-driven home monitoring penetration and relationship-driven clinical supply chain anchoring.
| Leading Market Players |
|---|
| OMRON Corporation |
| Baxter International |
| McKesson Corporation |
| Cardinal Health |
| GE Healthcare |
| Koninklijke Philips |
| SunTech Medical |
| American Diagnostic Corporation |
| Medline Industries |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses margin structures for economy-tier digital cuff imports while amplifying price differentiation between standard pharmacy retail units and configured-to-order ambulatory systems for diagnostic centers.
Pricing Analysis
The customization-premium spread between configured-to-order ambulatory cuffs and standard retail digital units spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 81060-2 certification grade and after-sales calibration service bundling. Cost compression in economy-tier segments is intensifying because Vietnamese textile manufacturers are absorbing polyester-nylon fabric cost escalations. Diagnostic centers exhibit lowest price sensitivity due to statutory reimbursement coverage, while India's Tier-2 retail channels face acute margin pressure.
Supply Chain Analysis
Contract-manufacturing concentration in Vietnam, Bangladesh, and southern China's Pearl River Delta dominates bladder encapsulation and final assembly capacity for mid-range and economy-tier products. Raw material dependencies center on Taiwan and South Korea for pressure sensor chip fabrication, German precision gauge components for aneroid systems, and EU-registered chemical suppliers for REACH-compliant nylon coatings. Single-source vulnerability in semiconductor inputs exposes digital cuff producers to allocation risk. Distribution runs through hospital GPO contracts in North America, pharmacy chain direct procurement in Western Europe, and e-commerce platform fulfillment in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consolidation and pharmacy chain category management, fragmenting manufacturer pricing autonomy across institutional and retail channels.
For Market Incumbents: Insulate algorithm validation capabilities through backward integration into oscillometric sensor module production in the Kansai region, defending against cuffless photoplethysmography substitutes. Deepen GPO contract anchoring with multi-year replenishment clauses tied to EHR implementation timelines. Prioritize FDA 510(k) pathway pre-submission for smartphone-integrated platforms to preempt software-as-medical-device classification complexity. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 diagnostic center networks through mid-range aneroid and digital systems priced below metro hospital procurement thresholds. Target Germany's expanded ABPM reimbursement corridor with white-label ambulatory cuff platforms for statutory insurance coverage. Deploy telehealth platform bundling agreements with United Kingdom pharmacy chains to bypass standalone device margin compression. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core monitoring device divisions with stranded hospital relationships but intact oscillometric IP portfolios. Long-term viability hinges on algorithmic measurement differentiation as hardware commoditization accelerates. Watch for FDA software-as-medical-device guidance finalization as inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission | Accelerates oscillometric algorithm clearance timelines for Asian manufacturers seeking US market entry. |
| Hospital System Partnership | Locks in multi-year cuff replenishment cycles through EHR-integrated procurement workflows. |
| Software Companion Development | Navigates emerging FDA, EU MDR, and PMDA digital health classification frameworks for app-connected cuffs. |
| CE Marking Pathway | Addresses EU MDR's tightened Class IIa clinical evidence requirements for bladder encapsulation materials. |
| Reimbursement Strategy | Captures Germany's statutory health insurance ABPM expansion and Japan's METI Silver ICT subsidies. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and diagnostic center procurement leads, and refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and hospital procurement system records. Bottom-up demand modeling across product type, application, end user, and technology segments was triangulated with top-down macroeconomic anchoring.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with oscillometric device adoption curves, ambulatory monitoring reimbursement expansion, and textile manufacturing cost trajectories serving as core segmentation dimensions. CAGRs were derived from replacement cycle velocity differentials between home health monitoring and clinical diagnostic settings, calibrated against semiconductor input availability and regulatory pathway timelines.
Macroeconomic conditions sit as an overlay; deviation in freight rates, semiconductor allocation, or statutory reimbursement coverage would shift the trajectory. Forecasts reflect documented assumptions regarding FDA pathway streamlining persistence and EU MDR enforcement intensity. Quarterly review of GPO contract renewal patterns, CDSCO import documentation changes, and REACH amendment implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market