
 Animal Nutrition Chemicals Market | 2026-2036
Animal Nutrition Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Nutrition Chemicals Market Intelligence
Precision fermentation and cell-culture-derived nutrient synthesis is fragmenting traditional extraction-based supply chains for amino acids and vitamins. BASF SE leverages its biotechnology platforms to sustain cost leadership in lysine and methionine production. Evonik Industries AG anchors its position through backward integration into fermentation feedstocks and dedicated bioreactor capacity. Kemin Industries Inc. differentiates via specialized natural antioxidant formulations that command premium positioning in poultry and aquaculture channels.
Animal nutrition chemicals comprise synthetically or biologically produced compounds including vitamins, minerals, amino acids, and enzymes formulated to optimize feed conversion ratios, reproductive performance, and disease resistance in livestock; lysine specification typically requires minimum 98.5% purity with granular flowability below 5% dust fraction for automated feed mill integration. Amino acids capture the dominant margin pool as methionine and lysine remain indispensable for monogastric diets where soybean meal protein quality falls short of nutritional requirements. Enzyme applications in swine and poultry expand fastest as phytase and non-starch polysaccharide enzymes unlock phosphorus and energy from lower-cost plant-based feedstuffs. Aquaculture nutrition chemicals remain structurally undersupplied relative to projected farmed seafood volume trajectories, creating concentrated investment interest in species-specific premix formulations.
The European Commission's Farm to Fork strategy under the EU Green Deal mandates 50% reduction in antimicrobial sales for farmed animals, redirecting formulation R&D toward enzymatic and organic acid alternatives. FDA's Veterinary Feed Directive in the United States restricts medically important antibiotics to veterinary prescription, while China's Ministry of Agriculture and Rural Affairs enforces feed antibiotic bans that accelerate domestic enzyme capacity expansion. Stakeholders must monitor regulatory divergence between jurisdictions that reward early biocertification investments versus those that maintain transitional compliance windows.
Market Dynamics
Precision fermentation platforms are fragmenting traditional amino acid extraction chains, forcing incumbents to retool bioreactor capacity or cede margin to cell-culture specialists with superior carbon efficiency.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The 50% antimicrobial reduction mandate redirects formulation R&D budgets toward enzymatic alternatives, expanding addressable market for phytase and protease suppliers.
- China's Feed Antibiotic Ban:Ministry of Agriculture and Rural Affairs enforcement accelerates domestic enzyme capacity buildout, creating pull-through demand for fermentation-derived premix formulations.
- Precision Fermentation:Cell-culture nutrient synthesis achieves cost parity with soybean meal protein in lysine and methionine, unlocking substitution economics for monogastric feed mills.
Market Restraints
- Fermentation Feedstock Volatility:Corn dextrose and molasses input costs swing with Brazilian sugarcane harvests and US ethanol policy, compressing margin predictability for amino acid producers.
- Bioreactor Supply Concentration:Stainless steel vessel fabrication concentrates among German and South Korean specialized fabricators, creating 18-24 month equipment lead times that throttle capacity expansion.
- Phytase Thermal Stability Limits:Pelleting temperatures above 85°C degrade enzyme activity, forcing feed mills to choose between nutrient loss or capital-intensive post-pelleting liquid application systems.
Strategic Opportunities
- Aquaculture Premix Undersupply:Farmed shrimp and salmon volume trajectories outpace species-specific formulation development, creating white space for astaxanthin and taurine specialists in Norway and Vietnam.
- US Veterinary Feed Directive Compliance Services:FDA prescription requirements for medically important antibiotics generate recurring revenue streams for diagnostic and veterinary consultation platforms integrated with feed formulation.
- Blockchain-Enabled Provenance:Distributed ledger verification of antibiotic-free and organic certification claims commands premium positioning in German and Dutch retail protein channels.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Bioprocess engineering expertise for industrial amino acid production concentrates among legacy Cargill and ADM alumni, constraining specialist hiring pools for emerging cell-culture ventures.
- Multi-Jurisdiction Certification Timelines:EU organic, US NOP, and China Green Food standards diverge on synthetic vitamin permissibility, forcing parallel documentation systems that extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Nutrition Chemicals Market |
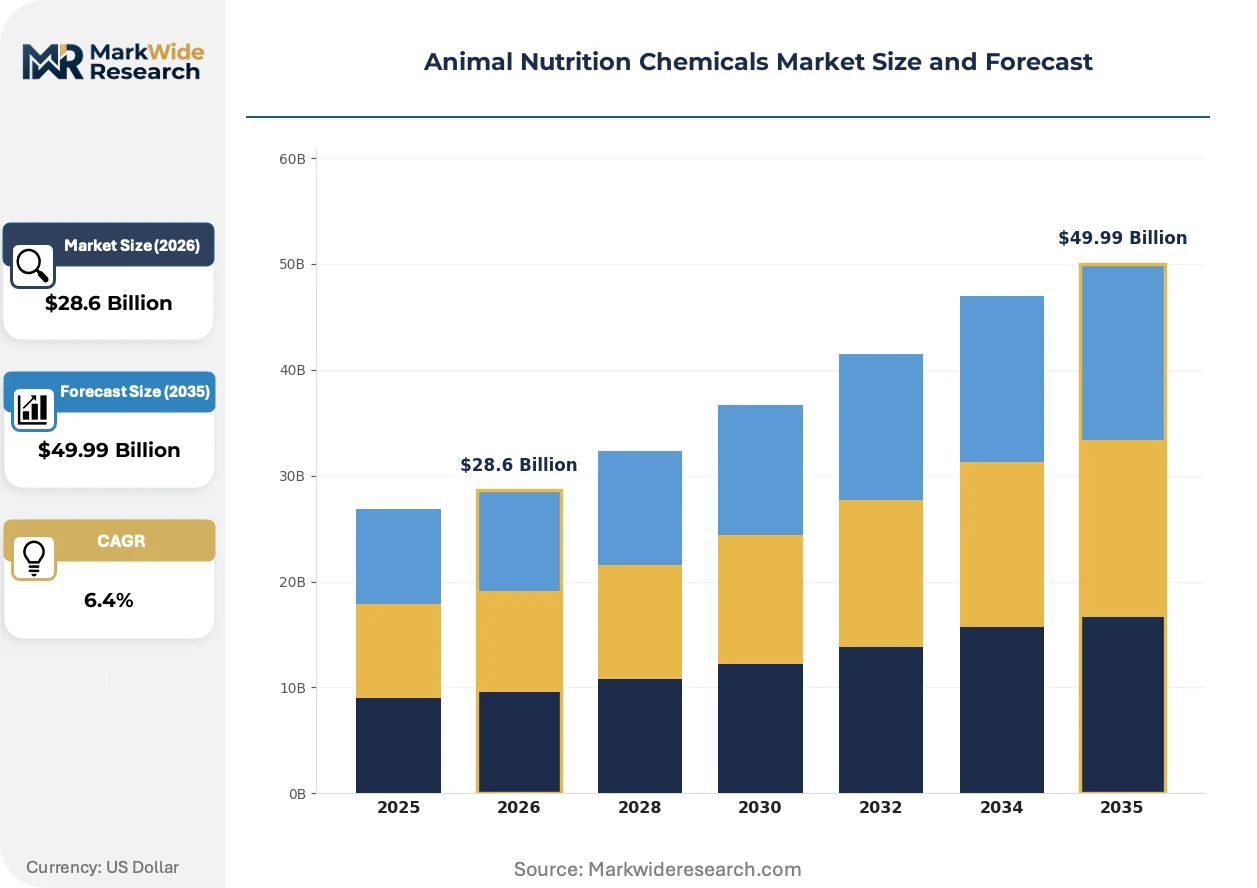
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes Application: Ruminants, Poultry, Swine, Aquaculture Form: Powder, Liquid, Granular, Pelleted Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Cargill Incorporated, BASF SE, Evonik Industries AG, Koninklijke DSM NV, Balchem Corporation, Kemin Industries Inc., Archer-Daniels-Midland Company, Novozymes A/S, Aumgene Biosciences Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Nutrition Chemicals Market Strategic Shifts & Innovations
Biotechnology convergence with digital process control is compressing development cycles for novel feed additives while regulatory fragmentation forces parallel compliance architectures.
Sensor-integrated bioreactor arrays is digitizing real-time metabolite monitoring in amino acid fermentation, enabling predictive nutrient feeding that lifts yields 12-18% over batch protocols. Large-scale lysine producers in Iowa and Jiangsu province are retrofitting legacy tanks with dissolved oxygen and pH probe networks. The structural consequence is compressing R&D-to-commercial timelines for novel strains from 36 months toward 18 months.
REACH biocide authorization reviews are reclassifying organic acid preservatives used in feed hygiene, forcing reformulation toward GRAS-listed alternatives ahead of 2026 sunset dates. ECHA's cumulative assessment of formic and propionic acid mixtures is tightening maximum residue limits in swine finishing diets. Northern European compound feed manufacturers are accelerating enzyme-based preservation validation to preempt supply disruption.
Integrated feed-to-farm data platforms are consolidating procurement decisions among 500+ sow unit operations in the US Corn Belt and Denmark, displacing independent nutritionist relationships. Smithfield and Danish Crown contract growers now specify premix suppliers through mandated enterprise software, compressing spot-market participation. This concentration is most visible in Iowa and Jutland Peninsula sow operations where vertical coordination exceeds 60% of feed volume.
Animal Nutrition Chemicals Market Segmentation
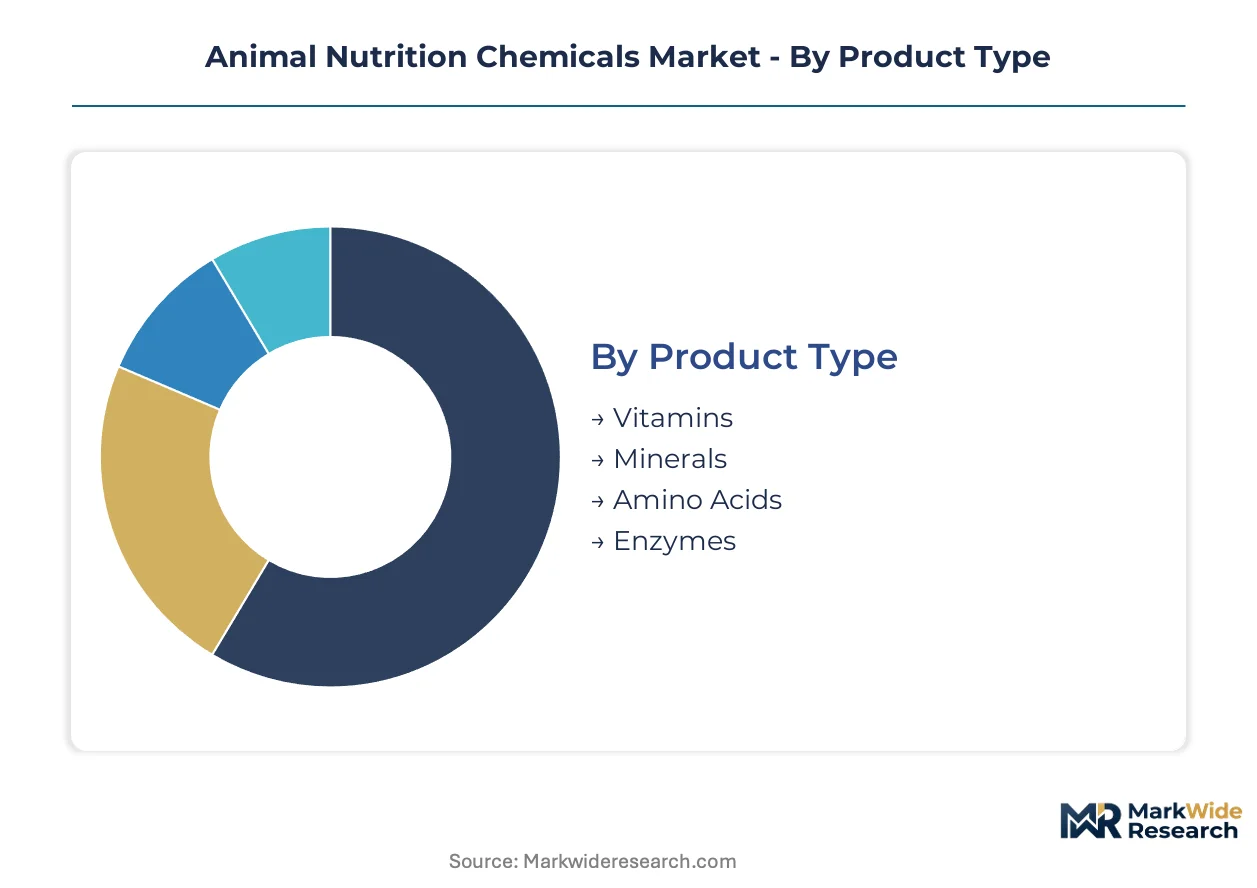
Segmentation in animal nutrition chemicals reveals how formulation requirements diverge across species physiology, processing constraints, and procurement channels. Each dimension shapes margin structures and competitive positioning differently.
Product Type:
Mature commodity categories dominate volume, while biotechnology-enabled segments accelerate fastest.
- Amino Acids:Lysine and methionine specifications demand minimum 98.5% purity with granular flowability below 5% dust fraction for automated feed mill integration. Monogastric diets in Iowa and Jiangsu province concentrate demand as soybean meal protein quality falls short of nutritional requirements.
- Enzymes:Phytase and non-starch polysaccharide enzymes unlock phosphorus and energy from lower-cost plant-based feedstuffs. Swine and poultry operations in Denmark and Vietnam drive fastest adoption as phytase thermal stability limits force capital investment in post-pelleting liquid application systems.
- Vitamins:Synthetic and natural vitamin formulations span fat-soluble and water-soluble categories for metabolic function support.
- Minerals:Macro and trace mineral premixes address bone development, enzyme cofactor, and immune function requirements.
Amino Acids retains volume leadership; Enzymes holds the steepest expansion curve.
Application:
Species-specific digestive physiology dictates formulation complexity and pricing power.
- Poultry:Rapid growth genetics and high feed conversion ratios necessitate precise amino acid balancing and enzyme supplementation. Broiler operations in the US Southeast and Brazil's São Paulo state concentrate demand for cost-optimized premix formulations.
- Swine:Phytase inclusion rates exceed poultry due to lower endogenous phosphorus utilization, driving enzyme volume per ton of feed.
- Ruminants:Microbial protein synthesis in the rumen reduces direct amino acid supplementation needs compared to monogastrics.
- Aquaculture:Farmed shrimp and salmon volume trajectories outpace species-specific formulation development, creating supply constraints for astaxanthin and taurine specialists.
Poultry commands the largest absolute tonnage; Aquaculture posts the most aggressive volume gains.
Form:
Processing compatibility and handling economics segment the market by feed manufacturing infrastructure.
- Powder:Fine particle size enables homogeneous mixing in small-batch operations but generates dust exposure and flowability challenges.
- Granular:Low-dust flowability suits automated bulk handling systems in 10,000+ ton feed mills.
- Liquid:Post-pelleting application preserves heat-sensitive enzyme activity, commanding premium positioning for phytase and protease delivery.
- Pelleted:Co-extruded nutrient matrices protect vitamins from oxidation but require specialized extrusion capacity.
Granular forms dominate high-volume compound feed; Liquid application expands most quickly for enzyme preservation.
Distribution Channel:
Procurement consolidation is reshaping channel economics across integrated and independent operations.
- Direct Sales:Enterprise contracts with Smithfield, Tyson, and Danish Crown specify premix suppliers through mandated feed-to-farm data platforms, displacing spot-market participation.
- Distributors:Regional stocking points serve mid-scale independent feed mills with technical service support and inventory financing.
- Retail:Farm supply cooperatives and veterinary clinics cater to smallholder livestock producers with bagged premix and supplement offerings.
- Online:E-procurement platforms aggregate price transparency for generic vitamin and mineral formulations among price-sensitive buyers.
Direct Sales captures the largest contract value; Online channels gain share fastest among cost-focused independents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian lysine and methionine exports flow primarily to European Union compound feed mills and Southeast Asian aquaculture operations, creating price-discovery linkages between São Paulo state fermentation clusters and Rotterdam port logistics.
United States
Iowa and Illinois concentrate amino acid fermentation capacity serving domestic swine and poultry integrators. FDA's Veterinary Feed Directive restricts medically important antibiotics to veterinary prescription, redirecting formulation budgets toward enzyme alternatives. Smithfield and Tyson contract growers in the Corn Belt now specify premix suppliers through mandated enterprise software platforms.
China
Jiangsu and Shandong provinces house the largest lysine fermentation complexes supplying domestic feed mills and export markets. Ministry of Agriculture and Rural Affairs enforcement of feed antibiotic bans accelerates domestic phytase and protease capacity expansion. Qingdao and Dalian port clusters handle bulk amino acid shipments to Vietnam and Indonesia.
Germany
North Rhine-Westphalia and Lower Saxony concentrate precision fermentation R&D serving EU compound feed manufacturers. ECHA's REACH biocide authorization reviews reclassify organic acid preservatives, forcing reformulation toward enzyme-based alternatives ahead of 2026 sunset dates. BASF SE and Evonik Industries AG anchor bioreactor capacity in Ludwigshafen and Marl chemical parks.
Brazil
São Paulo state and Mato Grosso integrate soybean crushing with amino acid premix production for domestic broiler and swine operations. Export flows to Portugal and Spain leverage preferential trade terms under the EU-Mercosur agreement. Campinas and Ribeirão Preto host formulation facilities supplying independent feed mills in the Center-West agricultural frontier.
India
Maharashtra and Gujarat concentrate enzyme manufacturing serving domestic dairy cooperatives and Southeast Asian aquaculture exporters. FSSAI feed additive regulations tighten maximum residue limits for synthetic preservatives, accelerating natural antioxidant validation. Pune and Ahmedabad house formulation specialists supplying shrimp feed mills in Andhra Pradesh and Odisha.
Animal Nutrition Chemicals Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Consolidation concentrates among fermentation-scale incumbents with captive bioreactor networks, while mid-scale premix formulators serve regional independents. Three archetypes dominate: biotechnology platforms with backward integration into fermentation feedstocks, natural-extraction specialists commanding premium positioning, and distributor-anchored regional blenders. Competitive moves center on M&A for bioprocess engineering talent and strategic partnerships for species-specific formulation development.
Within the biotechnology platform tier, BASF SE and Evonik Industries AG exemplify fermentation-scale leadership through Ludwigshafen and Marl chemical park infrastructure. Kemin Industries Inc. occupies a natural-extraction specialist position, while Cargill Incorporated and Archer-Daniels-Midland Company represent agribusiness-integrated feed additive channels. Novozymes A/S anchors enzyme technology licensing relationships across multiple geographies. Koninklijke DSM NV, Balchem Corporation, and Aumgene Biosciences Pvt. Ltd. sit within diversified nutrition and regional formulation archetypes respectively.
| Leading Market Players |
|---|
| Cargill Incorporated |
| BASF SE |
| Evonik Industries AG |
| Koninklijke DSM NV |
| Balchem Corporation |
| Kemin Industries Inc. |
| Archer-Daniels-Midland Company |
| Novozymes A/S |
| Aumgene Biosciences Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp barge freight corridors transmit Brazilian lysine export cost volatility directly into EU compound feed mill procurement budgets, concentrating pricing power among Ludwigshafen and Marl chemical park operators while fragmenting margin capture across independent distributors serving spot-market buyers.
Pricing Analysis
Cell-culture lysine and methionine production achieves cost parity with fermentation-derived grades, compressing premiums for precision-formulated amino acids while standard-grade products face downward pressure from Chinese capacity expansion. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade vitamin formulations from feed-grade commodities and generic mineral blends. Pricing pressure stems from Jiangsu province lysine oversupply and Brazilian real currency depreciation against contract currencies. Spot-market buyers in Vietnam and Indonesia exhibit highest price sensitivity; integrated Tyson and Smithfield contract operations absorb premiums for supply security.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain working capital for mid-scale premix formulators, forcing reliance on supply-chain finance facilities anchored by Cargill and ADM trade credit programs. Feedstock concentration in Iowa and Jiangsu province creates single-source vulnerability for corn dextrose and molasses inputs. Bioreactor fabrication dependence on German and South Korean specialized fabricators extends equipment lead times. Distribution runs through enterprise software-mandated direct sales for integrated operations, with regional distributors serving independent feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed-to-farm data platform consolidation creates platform-economics inflection as Smithfield and Danish Crown enterprise software mandates displace independent nutritionist procurement relationships.
For Market Incumbents: Pre-empt enzyme supplier consolidation by acquiring Vietnam and Norway aquaculture premix specialists before species-specific formulation scarcity drives valuation premiums. BASF SE and Evonik Industries AG should accelerate bioreactor capacity in Ludwigshafen and Marl to capture Chinese export displacement from domestic antibiotic ban compliance. Backward integration into Brazilian sugarcane fermentation feedstocks defends margin position against corn dextrose price volatility. For New Entrants and Emerging Players: Species-specific shrimp and salmon premix formulations in Vietnam and Norway represent the most penetrable entry point given supply constraints for astaxanthin and taurine against farmed seafood volume trajectories. Blockchain-enabled antibiotic-free certification verification for German and Dutch retail channels offers differentiated positioning. Partner with Qingdao and Dalian port logistics operators to bypass established distributor relationships in Southeast Asian aquaculture feed markets. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core feed additive divisions as parent companies refocus on grain trading and protein processing. Mid-scale premix formulators with captive aquaculture or organic certification capabilities offer 5-10 year viability as channel consolidation proceeds. Monitor EU Green Deal Farm to Fork implementation timelines as inflection signal for enzyme and probiotic substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Corn dextrose and molasses supply control in Iowa and Brazil insulates margin from Brazilian sugarcane harvest volatility. |
| Bioreactor Capacity Expansion | Ludwigshafen and Marl chemical park additions capture enzyme demand surge from China's Ministry of Agriculture antibiotic enforcement. |
| Species-Specific Premix Development | Shrimp and salmon formulation capabilities in Vietnam and Norway address structural undersupply against aquaculture volume trajectories. |
| Blockchain Certification Integration | Distributed ledger verification commands premium positioning in German and Dutch antibiotic-free retail protein channels. |
| Enterprise Software Platform Partnership | Smithfield and Danish Crown feed-to-farm data integration secures mandated supplier status across 500+ sow unit operations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and EU ECHA REACH biocide authorization records. Plant managers at Iowa and Jiangsu province fermentation facilities, procurement leads at Tyson and Smithfield integrators, distribution channel partners serving independent feed mills, and technical R&D directors at BASF SE and Evonik Industries AG provided operational validation. Bottom-up volume modeling from species-specific feed consumption rates triangulates against top-down amino acid and enzyme production capacity assessments.
Forecast inputs span product type segmentation across amino acids, enzymes, vitamins, and minerals; application dimensions covering poultry, swine, ruminant, and aquaculture species; and form factors including powder, granular, liquid, and pelleted delivery systems. CAGRs derive from regression analysis of historical production capacity expansion correlated with regulatory enforcement timelines and protein consumption elasticity across middle-income demographics. Feed conversion ratio improvement trajectories and antibiotic substitution elasticity inform substitution modeling for enzyme and probiotic segments.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, US ethanol policy, and EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and fermentation technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Feed Carotenoids Market