
 Feed Electrolytes Market | 2026-2036
Feed Electrolytes Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Electrolytes Market Foresight
A capital-intensity divergence between integrated nutrition conglomerates and specialized electrolyte formulators is reorganizing competitive boundaries in feed additives. Cargill Inc leverages its captive mineral sourcing and premix manufacturing footprint across multiple continents to sustain cost-advantaged electrolyte blends. Alltech Inc anchors its position through yeast-based electrolyte synergies that differentiate its portfolio from commodity salt formulations. Zinpro competes on organic trace mineral integration, occupying a technical niche where chelated mineral-electrolyte combinations command premium positioning in ruminant nutrition programs.
Feed electrolytes comprise water-soluble mineral salts—primarily sodium, potassium, chloride, magnesium, and calcium compounds—formulated to restore ionic balance and maintain cellular osmotic pressure in animals under thermal, metabolic, or transport stress. These formulations typically achieve optimal absorption at specified osmolality ranges and are manufactured through spray-drying, crystallization, or liquid blending processes to ensure homogeneity in final feed or drinking water applications. Mineral Blends dominate volume flows due to their compatibility with standard feed milling equipment and cost efficiency in bulk livestock operations, while Liquid Electrolytes capture faster growth in automated drinking water systems where precision dosing replaces manual feed-top dressing. The Poultry application segment channels significant demand as broiler operations in climate-controlled housing still encounter periodic heat events that trigger mortality and condemnations without electrolyte intervention.
The EU Feed Additives Regulation and FDA's Center for Veterinary Medicine oversight jointly elevate compliance burdens for novel electrolyte formulations seeking cross-border market access. BIS certification requirements in India add another layer of mineral purity standards that suppliers must navigate for export eligibility. Stakeholders must monitor evolving antibiotic-reduction mandates, as these regulatory trajectories directly expand the addressable space for electrolyte-based performance solutions in livestock production systems.
Market Dynamics
The EU Feed Additives Regulation is compressing product registration timelines while simultaneously expanding the addressable market for electrolyte-based performance solutions as antibiotic reduction mandates accelerate across livestock sectors.
Growth Catalysts
- Heat stress protocols:Dairy operations in the United States are institutionalizing electrolyte supplementation as standard operating procedure during thermal events to protect milk yield retention.
- REACH compliance expansion:European formulators are redesigning mineral salt matrices to satisfy ECHA substance evaluation requirements, creating technical differentiation from commodity imports.
- Ionophore-free finishing:Brazilian beef feedlots are elevating electrolyte inclusion rates to compensate for removed growth promoters in ruminant nutrition programs.
Market Restraints
- Mineral input volatility:Magnesium chloride and potassium carbonate spot markets exhibit price swings that compress blending margins for independent formulators.
- Supply concentration risk:High-purity sodium sources concentrate among a limited set of Chilean and Israeli solar evaporation producers, creating geographic vulnerability.
- Technical limitation:Spray-dried formulations face hygroscopic stability constraints in tropical storage environments, limiting shelf-life in certain distribution channels.
Strategic Opportunities
- Automated drinking water systems:Precision dosing infrastructure in Netherlands poultry houses creates demand for liquid electrolyte concentrates that bypass manual feed-top dressing.
- Organic trace mineral convergence:Chelated zinc-electrolyte combinations command premium positioning in technical ruminant nutrition programs.
- Indian export eligibility:BIS certification pathways for mineral purity standards open formal market access for compliant suppliers.
Industry Challenges
- Formulation chemistry expertise:The intersection of osmolality optimization and species-specific absorption kinetics requires specialized veterinary nutritionists that remain scarce in emerging production regions.
- Multi-jurisdiction dossier preparation:Simultaneous FDA Center for Veterinary Medicine and EU Feed Additives Regulation compliance timelines extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Electrolytes Market |
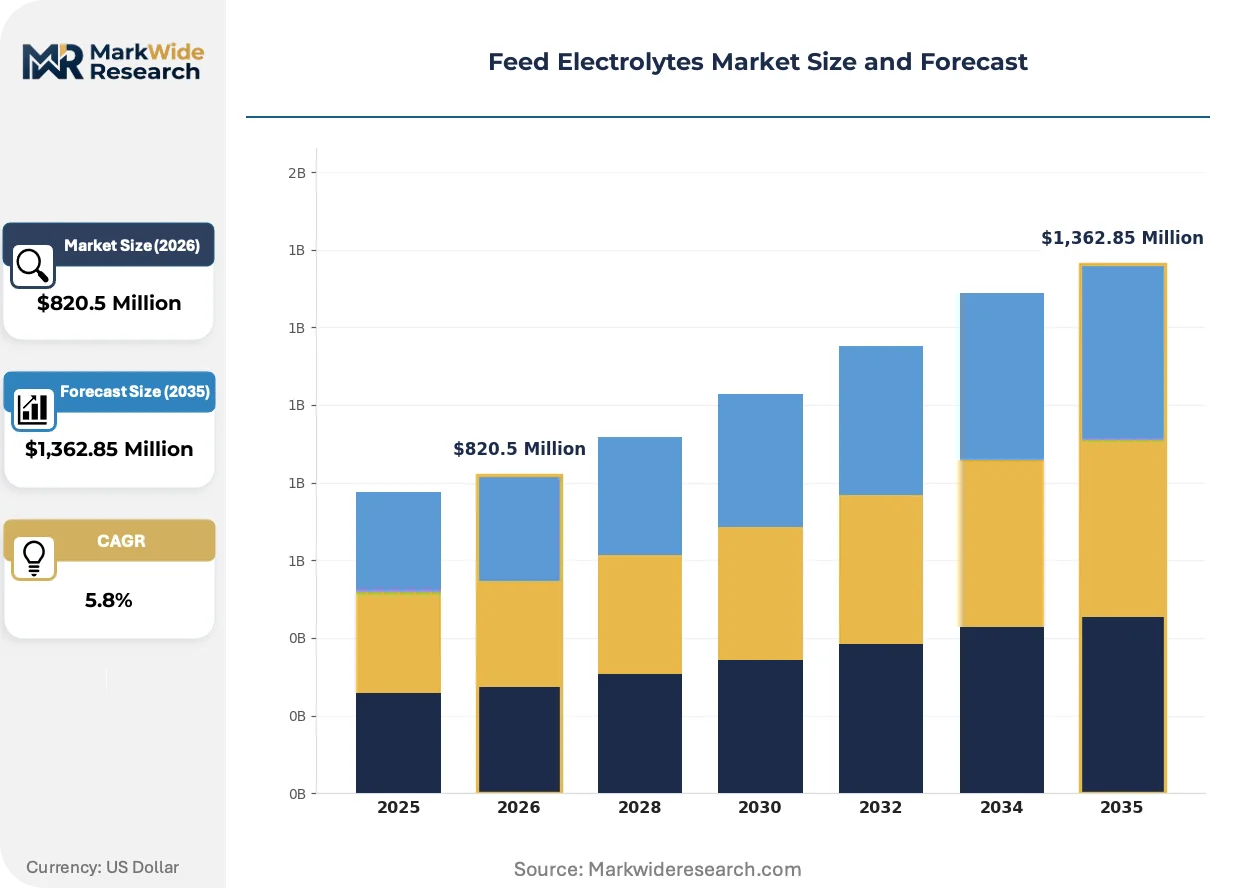
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,362.85 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Blends, Liquid Electrolytes, Powdered Electrolytes, Electrolyte Solutions Application: Livestock, Poultry, Aquaculture, Pets Distribution Channel: Direct Sales, E-commerce, Retail Stores, Veterinary Clinics End User: Farmers, Feed Manufacturers, Pet Owners, Aquaculture Producers |
| Companies Covered | Royal DSM, Tanke Biosciences Corp, Archer Daniels Midland Co, Cargill Inc, Alltech Inc, Kemin, Zinpro, Nutrena, Purina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Electrolytes Market Shifts & Advancements
Formulation science is pivoting toward bioavailable mineral matrices while regulatory pressure and precision livestock infrastructure reshape how electrolyte solutions reach end-users.
Yeast-based electrolyte synergies are supplanting commodity salt formulations in premium ruminant applications. Large-scale dairy cooperatives in the Upper Midwest are adopting these integrated solutions at accelerating rates. The technology is supplanting standalone mineral premixes by delivering osmotic balance alongside gut health modulation in single-dose protocols.
EU Feed Additives Regulation reauthorization requirements are forcing systematic toxicological dossier updates for existing electrolyte products. European manufacturers must resubmit safety data packages that now include environmental fate assessments. Poultry electrolyte suppliers serving the Benelux region are consolidating formulation lines to reduce compliance fragmentation costs.
Buyer concentration among integrated protein companies is compressing supplier negotiation leverage and unbundling technical advisory services from product supply. Traditional distributor networks in the US Corn Belt are losing share to direct procurement relationships with nutrition staff at major packer-affiliated feedyards. This pattern is most visible in Nebraska and Kansas cattle feeding regions where three operators control substantial finishing capacity.
Feed Electrolytes Market Segmentation
Feed electrolytes serve heterogeneous production systems where formulation chemistry, delivery mechanism, and species physiology create distinct commercial requirements. Segmentation reveals how regulatory thresholds, infrastructure maturity, and buyer procurement patterns fragment addressable demand across product types, applications, and channel structures.
Product Type:
REACH substance evaluation requirements in Europe and FDA Center for Veterinary Medicine oversight in the United States create divergent compliance burdens that reshape competitive positioning across formulation categories.
- Mineral Blends:Dry-mix formulations of sodium, potassium, chloride, magnesium, and calcium salts achieve optimal compatibility with standard feed milling equipment. Dairy operations in the United States institutionalize these blends as standard operating procedure during thermal events to protect milk yield retention.
- Liquid Electrolytes:Concentrated aqueous solutions enable precision dosing through automated drinking water systems. Netherlands poultry houses deploy these formulations to bypass manual feed-top dressing, with demand climbing fastest where precision livestock infrastructure penetrates.
- Powdered Electrolytes:Spray-dried crystalline matrices face hygroscopic stability constraints in tropical storage environments, limiting shelf-life in certain distribution channels.
- Electrolyte Solutions:Ready-to-use dilutions target small-scale operations lacking mixing infrastructure, with BIS certification requirements in India filtering export eligibility.
Established volume favors Mineral Blends; emerging adoption favors Liquid Electrolytes.
Application:
Species-specific metabolic stress patterns and production intensity gradients concentrate demand unevenly across livestock categories.
- Livestock:Ruminant and swine operations drive bulk consumption where heat stress protocols and ionophore-free finishing elevate supplementation rates. Brazilian beef feedlots compensate for removed growth promoters through elevated electrolyte inclusion.
- Poultry:Broiler operations in climate-controlled housing encounter periodic heat events triggering mortality and condemnations without electrolyte intervention. EU Feed Additives Regulation reauthorization requirements force systematic toxicological dossier updates for suppliers serving this segment.
- Aquaculture:Intensive finfish and shrimp systems deploy electrolytes to manage osmotic stress during transport and handling, with formulation expertise scarce in emerging production regions.
- Pets:Companion animal applications concentrate in veterinary-directed recovery protocols and premium hydration products, with margin structures diverging sharply from agricultural commodities.
Livestock anchors current volume; Poultry represents the fastest-growing trajectory as climate volatility intensifies.
Distribution Channel:
Buyer concentration among integrated protein companies compresses supplier negotiation leverage and unbundles technical advisory services from product supply.
- Direct Sales:Nutrition staff at major packer-affiliated feedyards in Nebraska and Kansas cattle feeding regions procure directly, bypassing traditional distributor networks.
- E-commerce:Digital platforms capture share in smallholder and pet owner segments where technical consultation requirements remain minimal.
- Retail Stores:Agricultural supply cooperatives in the US Corn Belt maintain relevance for mid-scale independent producers.
- Veterinary Clinics:Prescription-adjacent channels dominate pet applications and livestock therapeutic use cases requiring professional oversight.
Direct Sales concentrates large-account volume; E-commerce gains share fastest among fragmented buyer bases.
End User:
Scale asymmetries and technical capability gaps fragment procurement behavior across producer categories.
- Farmers:Individual producers prioritize cost efficiency and equipment compatibility, with spray-dried formulations dominating where tropical storage conditions permit.
- Feed Manufacturers:Integrated premix operations demand mineral input stability and homogeneity guarantees, with magnesium chloride and potassium carbonate spot market volatility compressing blending margins.
- Pet Owners:Premium positioning tolerance supports yeast-based electrolyte synergies that differentiate from commodity salt formulations.
- Aquaculture Producers:Intensive operators in climate-controlled systems generate concentrated demand spikes during seasonal stress periods.
Feed Manufacturers dominate commercial volume; Pet Owners sustain premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Brazilian feedlot operators while European formulators absorb compliance premiums, creating a trans-Atlantic margin asymmetry that reshapes supplier investment priorities.
United States
Dairy cooperatives in Wisconsin and California institutionalize electrolyte protocols during thermal events to protect milk yield retention. FDA Center for Veterinary Medicine oversight elevates dossier requirements for novel formulations seeking market entry. Nebraska and Kansas cattle feeding regions concentrate procurement leverage among packer-affiliated feedyards that bypass traditional distributor networks.
Brazil
Beef feedlots in Mato Grosso and São Paulo states elevate electrolyte inclusion rates to compensate for removed ionophore growth promoters. ANVISA alignment with international residue standards filters import eligibility for mineral premix suppliers. The São Paulo-Belo Horizonte corridor anchors formulation demand from integrated protein companies consolidating finishing capacity.
Germany
Poultry integrators in Lower Saxony deploy precision dosing infrastructure that accelerates liquid electrolyte adoption over manual feed-top dressing. ECHA substance evaluation requirements under REACH force systematic toxicological updates for existing mineral salt matrices. The Münsterland cluster concentrates technical ruminant nutrition programs where chelated mineral-electrolyte combinations command premium positioning.
India
Poultry and dairy operations in Maharashtra and Gujarat generate concentrated demand for BIS-certified mineral purity standards that filter export eligibility. The country's national feed regulator maintains stringent additive registration pathways that extend product launch timelines. The Pune-Nashik industrial corridor attracts formulation investment from suppliers targeting domestic livestock intensification.
Netherlands
Climate-controlled broiler houses in Gelderland and North Brabant integrate automated drinking water systems that bypass traditional feed milling channels. EU Feed Additives Regulation reauthorization requirements compress supplier margins through consolidated formulation lines. The Food Valley cluster around Wageningen anchors veterinary nutrition expertise that remains scarce in emerging production regions.
Feed Electrolytes Market Competitive Landscape
Concentration sits with integrated nutrition conglomerates that leverage captive mineral sourcing and multi-continent premix manufacturing footprints. The supplier base fragments between these scale players and specialized electrolyte formulators competing on technical differentiation. Three archetypes dominate: diversified agribusiness conglomerates with backward integration into mineral supply, yeast-based synergy specialists, and organic trace mineral integrators. Competitive moves center on portfolio diversification into chelated mineral-electrolyte combinations and geographic expansion through direct procurement relationships with integrated protein companies.
Among diversified agribusiness conglomerates, Cargill Inc and Archer Daniels Midland Co exemplify scale-driven positioning through captive supply chains and global premix infrastructure. Royal DSM anchors the premium tier through integrated nutritional solutions that bundle electrolytes with broader feed additive portfolios. Specialized players including Alltech Inc and Zinpro occupy technical niches where formulation chemistry expertise creates differentiation from commodity salt alternatives.
| Leading Market Players |
|---|
| Royal DSM |
| Tanke Biosciences Corp |
| Archer Daniels Midland Co |
| Cargill Inc |
| Alltech Inc |
| Kemin |
| Zinpro |
| Nutrena |
| Purina |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Brazilian feedlot operators and Chilean solar evaporation producers lock in sodium chloride supply access while providing twelve-to-eighteen-month price visibility against magnesium chloride spot volatility. These arrangements concentrate procurement leverage among integrated protein companies that bypass distributor markups, compressing margin capture for independent formulators dependent on open-market mineral sourcing.
Pricing Analysis
Configured-to-order pricing for chelated mineral-electrolyte combinations commands substantial premiums over standard salt-matrix formulations, with differentiation resting on organic trace mineral certification tiers and species-specific osmolality optimization. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and veterinary nutritionist advisory bundling. Pricing pressure stems from potassium carbonate spot market swings that compress blending margins for non-integrated suppliers. Mid-scale independent producers in the US Corn Belt exhibit highest price sensitivity, while Upper Midwest dairy cooperatives tolerate premium positioning for yeast-based synergies.
Supply Chain Analysis
Inbound logistics costs through the Santos port corridor fluctuate with container availability on the Asia-South America trade lane, elevating landed costs for Indian BIS-certified mineral imports. High-purity sodium sources concentrate among Chilean and Israeli solar evaporation producers, while magnesium chloride feedstock draws from Chinese and Turkish chemical processing hubs. Single-source vulnerability concentrates in Chilean Atacama-derived sodium where drought risk threatens evaporation yields. Distribution runs through direct procurement relationships with packer-affiliated feedyards that displace traditional agricultural supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three operators controlling substantial finishing capacity in Nebraska and Kansas cattle feeding regions, fragmenting supplier negotiation leverage and unbundling technical advisory services from product supply.
For Market Incumbents: Shield margin position through backward integration into captive mineral sourcing and multi-continent premix manufacturing footprints that neutralize potassium carbonate spot volatility. Deepen formulation chemistry expertise in osmolality optimization to defend against yeast-based synergy specialists encroaching on premium ruminant applications. Prioritize EU Feed Additives Regulation dossier resubmission timelines to maintain market access against compliance-fragmented competitors. For New Entrants and Emerging Players: Differentiate on precision dosing infrastructure compatibility for automated drinking water systems in Netherlands poultry houses and climate-controlled broiler operations. Target white-space demand in Indian BIS-certified mineral purity standards where domestic livestock intensification outpaces compliant supplier capacity. Penetrate through veterinary-directed recovery protocols in companion animal segments where premium positioning tolerance exceeds agricultural commodity margins. For Investors and Strategic Acquirers: Capital is best deployed toward specialized electrolyte formulators with proven organic trace mineral integration capabilities and established toxicological dossier libraries for multi-jurisdiction compliance. Long-term viability hinges on regulatory trajectory alignment as antibiotic-reduction mandates expand addressable space for electrolyte-based performance solutions. Monitor ionophore-free finishing protocol adoption rates in Brazilian beef feedlots as inflection indicator for electrolyte inclusion rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Cargill's captive supply chains neutralize magnesium chloride spot price volatility for cost-advantaged blending. |
| Multi-Jurisdiction Dossier Preparation | Simultaneous FDA and EU Feed Additives Regulation compliance extends product launch cycles but locks out fragmented competitors. |
| Precision Dosing Infrastructure Partnership | Liquid electrolyte concentrates bypass manual feed-top dressing in Netherlands climate-controlled poultry houses. |
| Organic Trace Mineral Convergence | Chelated zinc-electrolyte combinations command premium positioning in Münsterland technical ruminant nutrition programs. |
| BIS Certification Pathway Investment | Mineral purity standards filter export eligibility for suppliers targeting Maharashtra and Gujarat livestock intensification. |
Research Methodology
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings on supply concentration and compliance burden distribution. Primary interviews with veterinary nutritionists, feed mill procurement managers, premix manufacturing directors, and integrated protein company nutrition staff combined with secondary validation through FDA Center for Veterinary Medicine dossier records, ECHA substance evaluation documentation, ANVISA alignment filings, and BIS certification registries. Bottom-up demand modeling across species-specific application segments triangulates against top-down mineral consumption estimates.
Sensitivity analysis around heat stress protocol adoption rates and ionophore-free finishing penetration shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, species application, distribution channel structure, and end-user scale category, with regional regulatory cluster differentiation for multi-jurisdiction suppliers. CAGRs derive from mineral inclusion rate trajectories correlated with livestock inventory forecasts and climate volatility indices.
Material uncertainties — regulatory timeline slippage, drought-induced sodium evaporation yield compression, and precision livestock infrastructure deployment delays — sit outside the modeled envelope. Forecasts reflect documented assumptions on antibiotic-reduction mandate acceleration and automated drinking water system penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market