
 Global Animal Feed Amino Acids Market | 2026-2036
Global Animal Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Feed Amino Acids Market Foresight
Market Dynamics
Aftermarket nutritional consulting and feed formulation services is tilting margin pools away from commodity amino acid sales toward value-added technical partnerships. Evonik Industries AG leverages its MetAMINO methionine platform to anchor premium positioning in poultry and swine applications across Europe and Asia. Cargill Inc. competes through backward integration into corn and soybean processing, sustaining cost advantages in lysine production. Adisseo differentiates via its liquid methionine expertise and rumen-protected product lines, dominating specialty ruminant formulations.
Product and Segment Landscape
Animal feed amino acids are essential nitrogenous compounds—predominantly lysine, methionine, threonine, tryptophan, and valine—produced through fermentation of carbohydrate feedstocks or chemical synthesis, formulated into premixes to optimize protein deposition and minimize environmental nitrogen loss in livestock. Lysine and methionine collectively occupy the dominant value share, with threonine and tryptophan recording faster growth as swine and aquaculture diets advance toward ideal protein formulations. Fermentation-derived sources lead volume supply, though enzymatic and hydrolyzed protein alternatives are gaining traction as sustainability metrics tighten across European and North American procurement standards.
Regulatory Environment and Outlook
The European Food Safety Authority and REACH frameworks govern amino acid purity thresholds and manufacturing emissions, while the FDA and USDA oversee feed additive safety and labeling in the United States, collectively elevating compliance costs for new market entrants. China's Ministry of Agriculture and Rural Affairs enforces GB standards on feed-grade amino acid specifications, shaping export qualification requirements for international suppliers. Stakeholders must monitor evolving carbon border adjustments and precision livestock farming mandates that will redefine competitive advantage around verified low-carbon production credentials.
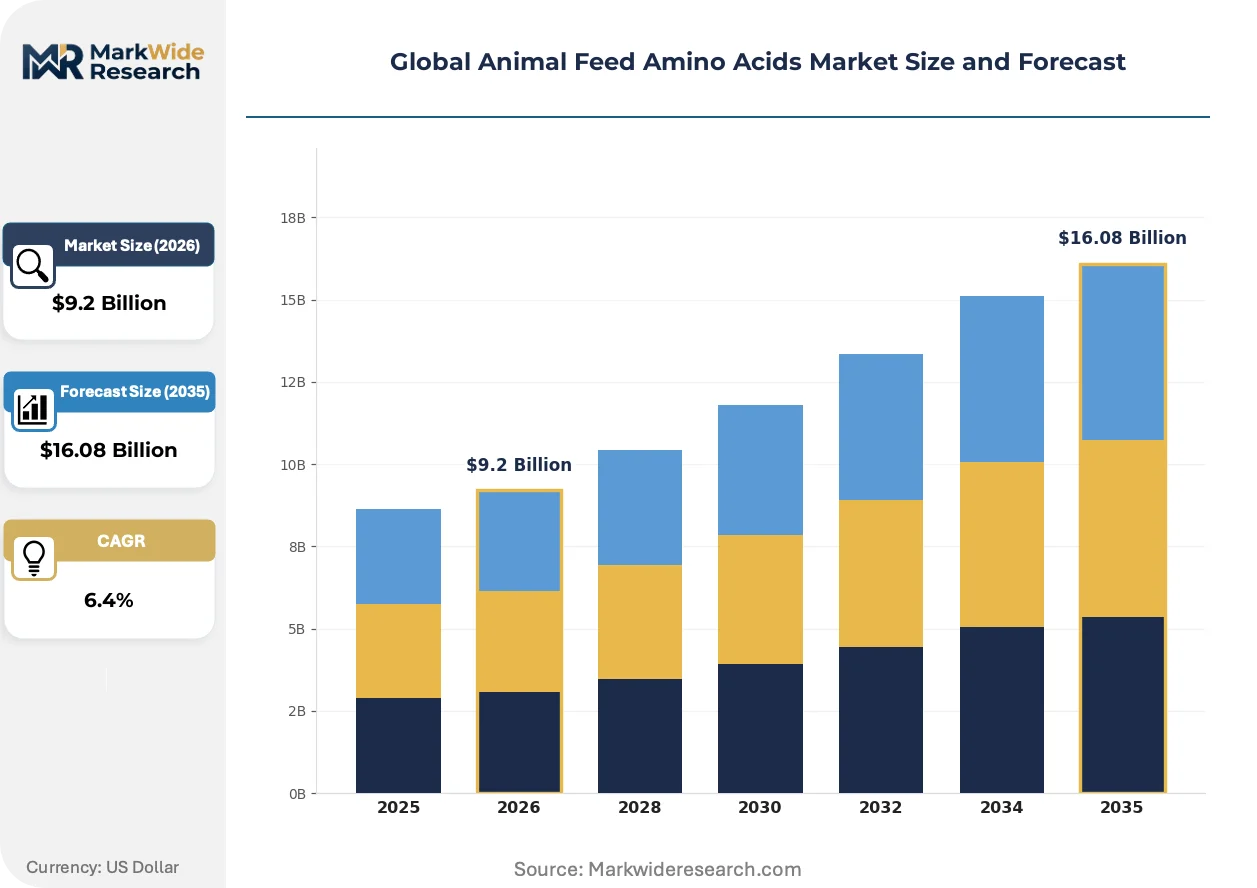
Market Dynamics
Precision livestock farming mandates and carbon border adjustments are compressing margins for commodity amino acid producers while rewarding verified low-carbon production credentials and technical formulation partnerships.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Nitrogen excretion limits are forcing European compound feed manufacturers to reformulate with precision amino acid dosing, creating sustained demand for lysine and methionine optimization services.
- Poultry feed conversion pressure:Southeast Asian broiler operations are expanding lysine and methionine supplementation as margin survival depends on extracting maximum protein deposition from every kilogram of feed.
- Fermentation technology maturation:Advanced carbohydrate-to-amino-acid bioconversion processes are lowering production costs for threonine and tryptophan, accelerating adoption in swine ideal protein formulations.
Market Restraints
- Raw material cost volatility:Corn and soybean meal price swings directly compress lysine production economics, particularly for non-integrated manufacturers lacking captive carbohydrate feedstock supply.
- Supply concentration in China:GB standards enforcement and export qualification requirements concentrate bulk amino acid production in state-supported fermentation facilities, creating single-source vulnerability for international buyers.
- Enzymatic hydrolysis substitution:Sustainability-driven European and North American procurement standards are elevating plant-derived and enzymatic protein alternatives as acceptable amino acid sources in premium feed segments.
Strategic Opportunities
- Brazilian captive blending capacity:Integrated pork and broiler producers in São Paulo and Paraná states are building in-house amino acid premix operations to control input costs and secure supply chain autonomy.
- Rumen-protected methionine expansion:Dairy and beef operations across Germany, France, and the Netherlands are adopting specialty ruminant formulations that bypass rumen degradation and deliver metabolizable protein directly to the small intestine.
- Carbon border adjustment readiness:Verified low-carbon production credentials under emerging EU CBAM frameworks will differentiate European-manufactured amino acids from import-dependent competitors in high-value sustainability markets.
Industry Challenges
- Formulation biochemistry expertise scarcity:Compound feed manufacturers struggle to recruit nutritionists capable of balancing ideal protein ratios across species-specific metabolizable energy requirements.
- REACH and EFSA compliance timelines:New amino acid purity thresholds and manufacturing emissions standards extend product registration cycles, delaying market entry for novel fermentation-derived variants.
- Precision dosing equipment integration:Retrofitting existing feed mills with automated amino acid micro-dosing systems requires capital outlays that mid-scale operations struggle to justify without guaranteed volume contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Feed Amino Acids Market |
| Market Size in 2026 | $9.2 Billion |
| Market Size in 2035 | $16.08 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan, Valine Source: Fermentation Derived, Synthetic, Enzymatic, Hydrolyzed Protein, Extracted Animal Type: Swine, Poultry, Aquaculture, Ruminants, Equine Form: Powder, Granules, Liquid, Pellets, Crystals |
| Companies Covered | Archer Daniels Midland Co, Kemin Industries, Evonik Industries AG, Nutreco N.V., Adisseo, Ajinomoto Co Inc, Novus International Inc, CJ CheilJedang Corp., Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Feed Amino Acids Market Shifts & Advancements
Digital formulation platforms and real-time nutritional analytics are displacing static feed tables, enabling dynamic amino acid dosing that responds to daily livestock performance data rather than periodic batch testing.
Sensor-enabled feed intake monitoring systems are digitizing the relationship between amino acid supplementation and individual animal protein deposition rates. Large integrated poultry and swine operations in Denmark and the Netherlands are deploying these systems at barn level. This technology is digitizing margin capture by allowing producers to adjust lysine and methionine inclusion within 24-hour cycles rather than standard 14-day formulation reviews.
REACH framework amendments on manufacturing emissions and EFSA purity thresholds are elevating compliance costs for amino acid producers serving European markets. The regulatory burden falls disproportionately on fermentation facilities lacking carbon capture or wastewater treatment upgrades. Specialty premix manufacturers are responding by consolidating supplier relationships around verified low-carbon credential holders and demanding third-party lifecycle assessments.
Buyer concentration among mega-scale integrators is compressing amino acid procurement into direct technical partnerships rather than spot commodity purchases. Brazilian and Thai poultry conglomerates now contract directly with fermentation houses for multi-year lysine supply with embedded formulation consulting. This shift is most visible in Southeast Asia, where feed mill consolidation has reduced the number of independent compounders by half over the past decade, concentrating volume with vertically integrated protein producers.
Global Animal Feed Amino Acids Market Segmentation
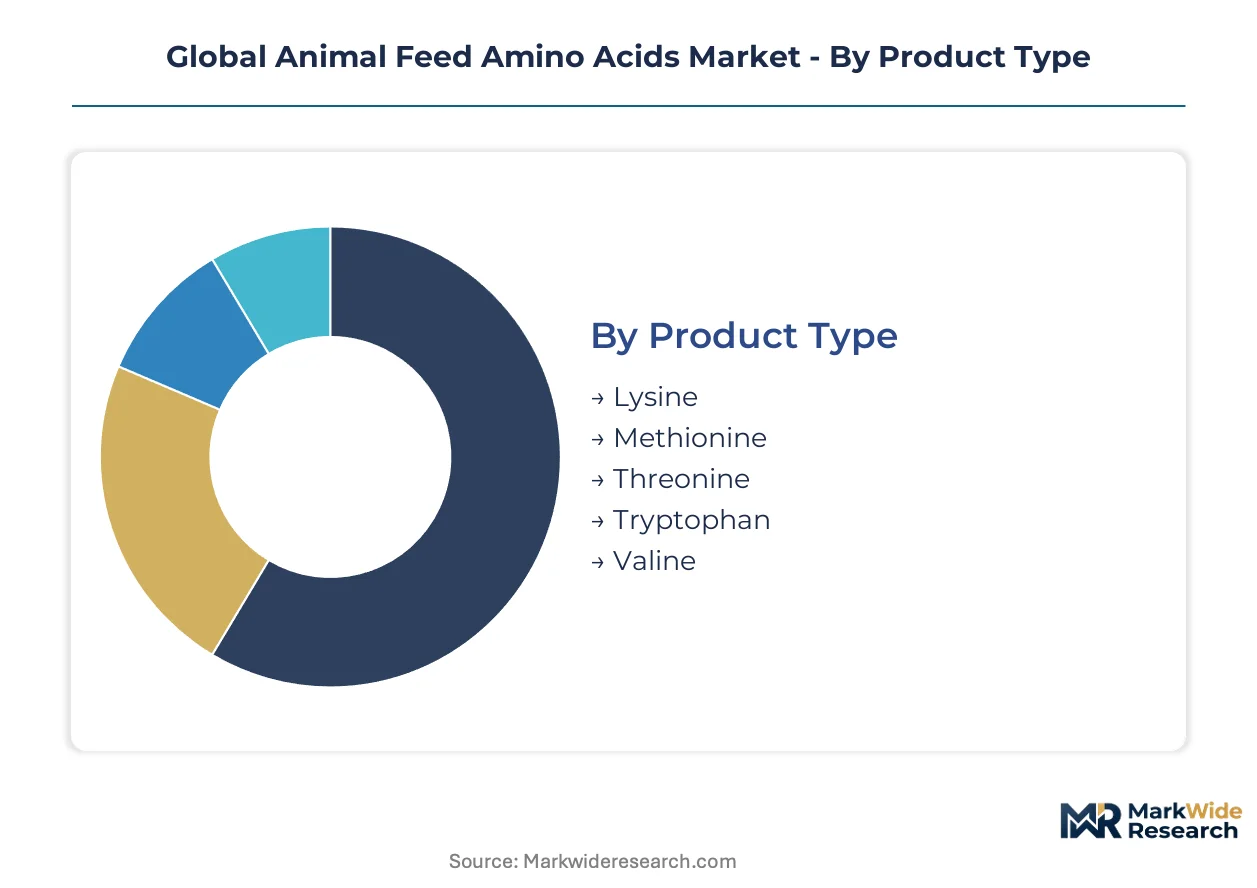
Segmentation in animal feed amino acids reveals distinct margin pools across production methods and species applications. Manufacturers align capacity investments with the technical requirements of each slice rather than pursuing undifferentiated volume.
Product Type:
Mature lysine and methionine platforms dominate commercial volumes while threonine and tryptophan emerge from specialty formulation demand.
- Lysine:The most widely supplemented essential amino acid in monogastric diets, typically supplied as L-lysine HCl or sulfate salts. Poultry integrators in Thailand and Vietnam are expanding lysine inclusion rates as feed conversion ratios tighten under margin pressure. This segment retains volume leadership; tryptophan holds the steepest expansion curve.
- Methionine:Available as DL-methionine solid or liquid hydroxy analogues, critical for poultry feathering and swine muscle synthesis. Evonik's MetAMINO platform anchors European supply while Chinese fermentation houses compete on DL-variants for Asian broiler operations.
- Threonine:Second-limiting amino acid in swine diets, increasingly formulated into ideal protein ratios for reduced nitrogen excretion under EU Green Deal compliance.
- Tryptophan:Precision dosing in high-performance swine and aquaculture feeds supports serotonin regulation and feed intake optimization.
- Valine:Branched-chain amino acid gaining inclusion in low-protein swine diets to maintain lean tissue deposition when soybean meal rates are reduced.
Lysine and methionine together capture the bulk of amino acid procurement spend; valine and tryptophan are climbing fastest as precision nutrition advances.
Source:
Cost tiers separate fermentation-derived bulk supply from premium enzymatic and hydrolyzed alternatives serving sustainability-certified procurement channels.
- Fermentation Derived:Microbial conversion of carbohydrate feedstocks—primarily corn-derived glucose—dominates lysine, threonine, and tryptophan supply. Chinese state-supported fermentation facilities concentrate global bulk production under GB standards enforcement.
- Synthetic:Chemical synthesis via the hydantoin process produces DL-methionine at scale, with European and Asian petrochemical complexes supplying integrated poultry and swine operations.
- Enzymatic:Protein hydrolysis using protease cocktails generates amino acid mixtures from plant substrates, qualifying for organic and non-GMO feed certifications in German and Dutch markets.
- Hydrolyzed Protein:Acid or enzymatic treatment of animal byproducts and oilseed meals creates complex amino acid profiles for specialty aquaculture and pet food applications.
- Extracted:Isolation from protein-rich biomass including algae and single-cell proteins, emerging as a carbon-accounting-compliant source for EU CBAM-aligned supply chains.
Fermentation-derived sources command volume leadership; enzymatic extraction posts the steepest expansion curve as sustainability procurement standards tighten.
Animal Type:
Application intensity varies sharply—poultry and swine drive lysine-methionine throughput while ruminant and aquaculture formulations command premium pricing for protected and marine-adapted products.
- Poultry:Broiler and layer operations consume the largest lysine and methionine volumes, with Southeast Asian integrators optimizing feed conversion ratios through precision amino acid dosing. Thai and Vietnamese conglomerates now contract directly with fermentation houses for multi-year supply with embedded formulation consulting.
- Swine:Ideal protein formulation—balancing lysine, threonine, methionine, and tryptophan—reduces crude protein levels and nitrogen excretion. Danish and Dutch producers deploy sensor-enabled feed intake monitoring to adjust amino acid inclusion within 24-hour cycles.
- Aquaculture:Marine and freshwater species require species-specific amino acid profiles, with methionine particularly critical for shrimp and salmonid growth performance.
- Ruminants:Rumen-protected methionine and lysine bypass microbial degradation in the rumen, delivering metabolizable protein to the small intestine. Dairy operations across Germany, France, and the Netherlands are expanding adoption of these specialty formulations.
- Equine:Limited but growing supplementation in performance horse feeds, particularly branched-chain amino acids for muscle recovery in racing and competition applications.
Poultry retains volume leadership; aquaculture holds the steepest expansion curve as marine protein substitution accelerates.
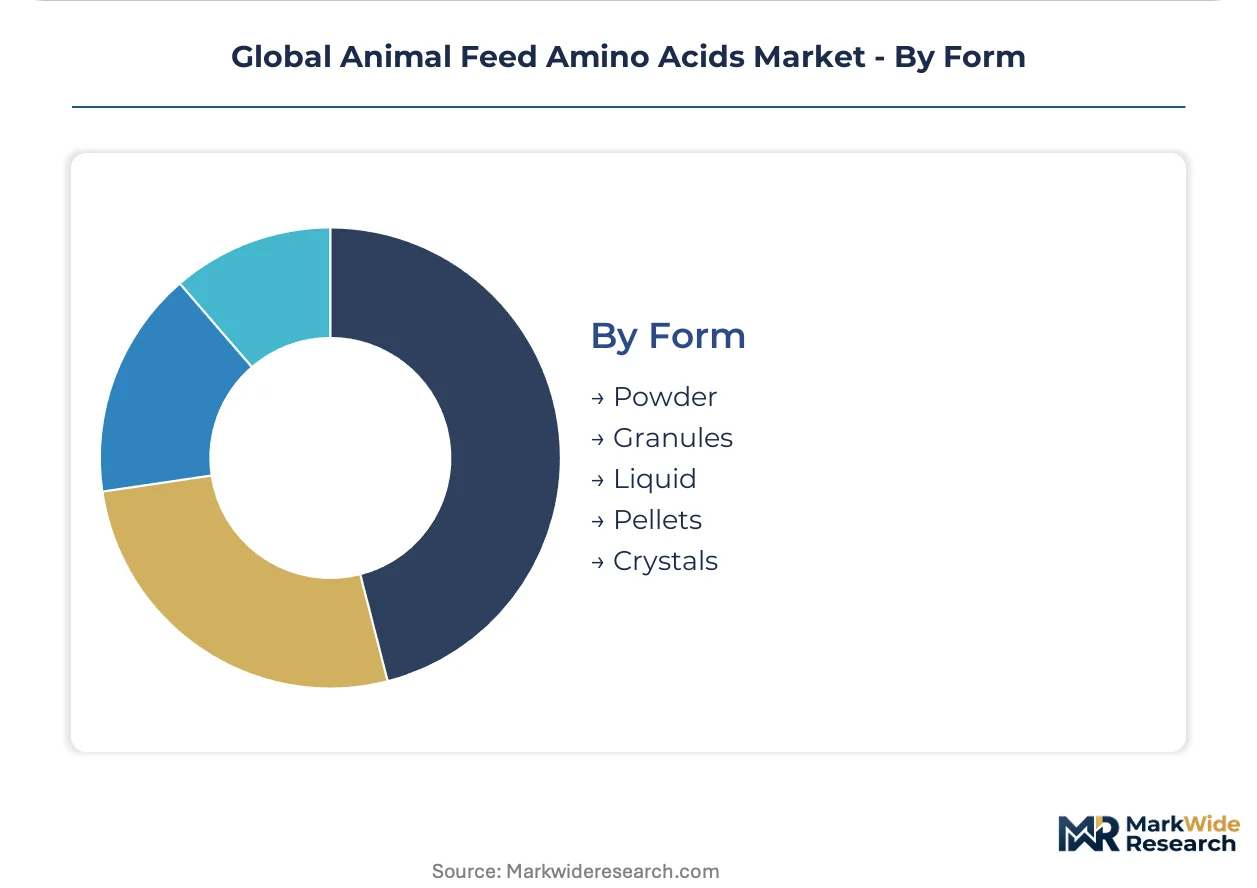
Form:
Customer type dictates form selection—powder and granules serve compound feed mills while liquid and specialized pellets target integrated operations with automated dosing infrastructure.
- Powder:Standardized particle size for uniform premix distribution, dominating independent compound feed manufacturing across Brazil and Southeast Asia.
- Granules:Dust-free handling characteristics suit automated batching systems in large-scale European and North American feed mills.
- Liquid:Hydroxy analogue methionine and certain lysine solutions enable post-pelleting application and precise micro-dosing in integrated poultry operations. Adisseo's liquid methionine expertise dominates this specialty segment.
- Pellets:Coated or extruded amino acids for rumen protection in dairy and beef applications, with pH-sensitive coatings releasing in the abomasum.
- Crystals:High-purity solid forms for research, specialty aquaculture, and pharmaceutical-grade applications requiring precise assay verification.
Powder and granules retain volume leadership; liquid forms gain share fastest as precision dosing equipment penetrates integrated operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major markets. Southeast Asian poultry integrators squeeze every basis point from feed conversion ratios, while European compounders absorb premium costs for carbon-verified amino acids to satisfy EU Green Deal procurement mandates.
China
State-supported fermentation facilities concentrate global bulk lysine and threonine supply under GB standards enforcement. The Ministry of Agriculture and Rural Affairs shapes export qualification requirements that international buyers must navigate. Shandong and Jiangsu provinces host the dominant amino acid production clusters, with integrated carbohydrate-to-amino-acid bioconversion complexes supplying Brazilian and Southeast Asian integrators.
Brazil
São Paulo and Paraná states drive captive premix capacity expansion as integrated pork and broiler producers seek supply chain autonomy. ANVISA oversees feed additive safety frameworks while state-level agricultural departments promote domestic blending infrastructure. The Sorocaba and Londrina industrial corridors anchor new amino acid distribution hubs serving the southern livestock belt.
Germany
Dairy operations across Lower Saxony and Bavaria expand rumen-protected methionine adoption to optimize metabolizable protein delivery. EFSA purity thresholds and REACH manufacturing emissions standards elevate compliance costs for fermentation-derived imports. The Münsterland and Allgäu dairy clusters contract directly with specialty premix manufacturers for verified low-carbon credential supply.
United States
Midwestern swine and poultry operations deploy precision dosing equipment to optimize lysine inclusion within shortened formulation cycles. FDA and USDA oversight governs feed additive safety and labeling requirements across state lines. Iowa and North Carolina livestock belts concentrate demand for automated amino acid micro-dosing systems integrated with sensor-enabled feed intake monitoring.
Thailand
Broiler integrators in the Central Plains and Eastern Economic Corridor contract directly with fermentation houses for multi-year lysine supply with embedded formulation consulting. The country's national agricultural regulator enforces feed-grade specifications aligned with export market access requirements. Rayong and Chonburi provinces concentrate vertically integrated poultry operations driving Southeast Asia's fastest amino acid throughput expansion.
Global Animal Feed Amino Acids Market Competitive Landscape
Capability concentration sits with specialty premix and rumen-protection formulators; scale advantage sits with integrated fermentation houses and petrochemical-derived methionine producers. The market structures around three tiers: global amino acid majors with captive carbohydrate feedstock supply, regional premix specialists with formulation biochemistry expertise, and emerging enzymatic hydrolysis players targeting sustainability-certified procurement channels. Dominant competitive moves include backward integration into corn and soybean processing, and multi-year technical partnerships that embed amino acid supply within consulting relationships.
Within the global fermentation tier, Evonik Industries AG anchors European methionine positioning through its MetAMINO platform, while Cargill Inc. exemplifies backward integration advantages from corn and soybean processing into lysine production. Adisseo occupies a specialist position in liquid methionine and rumen-protected formulations. These three represent distinct archetypes: petrochemical-derived methionine scale, agricultural commodity integration, and precision ruminant nutrition specialization.
| Leading Market Players |
|---|
| Archer Daniels Midland Co |
| Kemin Industries |
| Evonik Industries AG |
| Nutreco N.V. |
| Adisseo |
| Ajinomoto Co Inc |
| Novus International Inc |
| CJ CheilJedang Corp. |
| Cargill Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese lysine fermentation facilities is compressing spot-market pricing while forcing integrated European producers toward long-term technical partnerships that bundle formulation consulting with amino acid supply. This utilization asymmetry between state-supported bulk production and specialty capacity shapes how buyers negotiate contracts across poultry, swine, and ruminant segments.
Pricing Analysis
After-sales formulation consulting and multi-year technical service contracts now generate higher lifetime value than commodity amino acid transactions. Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon European production from Chinese bulk supply and regional enzymatic alternatives. Pricing pressure stems from raw material cost volatility in corn and soybean meal feedstocks, with non-integrated manufacturers absorbing margin compression. Spot-market buyers in Southeast Asia exhibit acute price sensitivity, while European compounders under EU Green Deal mandates accept premium pricing for verified carbon credentials.
Supply Chain Analysis
Upstream carbohydrate feedstock availability centers on corn belt regions in the United States, Brazil, and China, with glucose conversion economics determining regional production competitiveness. Fermentation-derived lysine and threonine concentrate in Shandong and Jiangsu provinces, while petrochemical-derived methionine clusters in Germany and Belgium. Single-source vulnerability runs through Chinese state-supported facilities controlling bulk amino acid export volumes. Distribution runs through integrated poultry and swine operations building captive premix capacity in São Paulo, Paraná, and Thailand's Eastern Economic Corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation biochemistry expertise and embedded consulting services represent the fastest-expanding revenue layer, outpacing commodity amino acid sales as precision livestock farming mandates deepen technical dependencies between suppliers and compound feed manufacturers.
For Market Incumbents: Harden supply chain autonomy through backward integration into corn and soybean processing, mirroring Cargill's captive carbohydrate-to-amino-acid bioconversion model. Secure multi-year formulation partnerships with Brazilian and Thai integrators to lock in volume commitments before captive blending capacity saturates regional demand. Invest in rumen-protection coating technologies to defend premium positioning against enzymatic hydrolysis substitutes gaining traction in European sustainability-certified procurement channels. For New Entrants and Emerging Players: Geographic underpenetration in African poultry and aquaculture feed markets offers white-space expansion with limited incumbent technical service presence. Target East African broiler operations seeking lysine optimization without legacy supplier entanglements. Enter through enzymatic protein hydrolysis platforms qualifying for organic and non-GMO certifications in German and Dutch markets, leveraging sustainability procurement standards tightening across European compound feed manufacturers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation facility carbon capture and wastewater treatment upgrades required for EU CBAM compliance. Long-term viability favors specialty premix formulators with rumen-protection expertise and verified low-carbon production credentials over undifferentiated bulk amino acid producers. Watch for consolidation signals when Chinese state-supported facilities begin acquiring European enzymatic technology to bridge sustainability certification gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Cargill's captive glucose supply secures cost advantages in lysine production against Chinese fermentation competitors. |
| Rumen-Protected Methionine Capacity Expansion | Adisseo's pH-sensitive coating technology captures premium pricing from German and Dutch dairy operations optimizing metabolizable protein. |
| Carbon Border Adjustment Certification Program | Verified low-carbon credentials under EU CBAM frameworks differentiate European-manufactured amino acids from import-dependent competitors. |
| Long-term Technical Partnership Agreements | Evonik's MetAMINO platform embeds multi-year supply contracts with embedded formulation consulting across Asian poultry integrators. |
| Enzymatic Hydrolysis Technology Licensing | Plant-derived protein alternatives qualify for organic feed certifications in sustainability-driven German and Dutch procurement channels. |
Research Methodology
Desk research of customs and trade flow databases, SEC and ECHA regulatory filings, and industry association reports preceded structured interviews with fermentation plant managers, compound feed procurement leads, poultry integrator nutritionists, and specialty premix technical directors. Primary fieldwork validated production capacity estimates, pricing benchmarks, and formulation adoption patterns across European, Brazilian, and Southeast Asian markets. Secondary sources included GB standards documentation, EU Green Deal implementation guidance, and bottom-up volume triangulation against top-down market sizing.
Assumptions around EU carbon border adjustment implementation timelines, precision livestock farming mandate adoption rates, and fermentation technology cost curves were held fixed across baseline scenarios while varying Chinese export policy shifts and enzymatic substitution penetration rates in sensitivity analysis. Segmentation modeling incorporated product type, source technology, animal application, and geographic production hub dimensions. CAGRs were derived from installed capacity expansion announcements, feed conversion ratio improvement targets, and regulatory compliance-driven reformulation cycles.
Practitioners should monitor Chinese GB standards enforcement intensity, Brazilian captive blending capacity buildout announcements, and EU CBAM carbon accounting methodology refinements for early signals requiring forecast revision. Cross-checking against FEFAC compound feed production statistics and national agricultural ministry amino acid import disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Animal Nutrition Market