
 South America Eubiotics Market | 2026-2036
South America Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Eubiotics Market Analytics
Multi-source procurement for fermentation-derived actives is decoupling from the traditional single-feed-mill supply contracts that once dominated Brazilian poultry operations. DSM-Firmenich leverages its Swiss-Brazilian technical service infrastructure to sustain formulation partnerships with large integrators. Cargill Inc anchors downstream distribution through its captive feed manufacturing network across São Paulo and Paraná. Novus International, Inc. competes on methionine-eubiotic bundling, a combination few regional distributors replicate.
Eubiotics comprise live microbial cultures, non-digestible oligosaccharides, short-chain organic acids, and targeted enzymes added to animal feed to modulate gut microbiota, enhance nutrient absorption, and suppress pathogenic colonization without antibiotics; typical probiotic formulations contain 10^9 to 10^11 CFU per gram and require microencapsulation to survive pelleting temperatures above 80°C. Probiotics command the largest revenue share among product types due to established efficacy data in broiler weight-gain trials, while organic acids capture expanding margin pools as Brazilian exporters face EU-aligned residue scrutiny. Poultry dominates animal type consumption, though aquaculture applications in Chilean salmon farming represent the fastest-growing demand segment as seawater-adapted Bacillus strains reach commercial scale.
ANVISA coordinates with MAPA on veterinary product registration timelines, while MERCOSUR's harmonized feed additive standards reduce cross-border formulation barriers between Brazil, Argentina, and Paraguay. REACH-aligned contaminant thresholds from European import buyers indirectly force Brazilian exporters toward third-party certified eubiotic programs. Stakeholders must track how Chile's new aquaculture environmental impact assessments reshape enzyme and probiotic deployment rules in Patagonian farming zones.
Market Dynamics
Brazilian poultry integrators are consolidating eubiotic procurement away from single-feed-mill contracts toward multi-source fermentation-derived active sourcing, compressing traditional distributor margins while elevating technical service requirements.
Growth Catalysts
- ANVISA residue standard tightening:Brazil's pharmaceutical regulator is accelerating veterinary drug residue limits, forcing exporters toward third-party certified eubiotic programs to maintain EU market access.
- Poultry gut health protocols:Brazilian and Argentine broiler operations are expanding probiotic and organic acid feed additive programs to reduce antibiotic dependency without sacrificing weight-gain performance.
- MERCOSUR harmonization:Cross-border feed additive standards between Brazil, Argentina, and Paraguay are reducing formulation barriers and enabling centralized manufacturing for regional distribution.
Market Restraints
- Fermentation input cost volatility:Glucose and nitrogen substrate prices for probiotic cultivation fluctuate with Brazilian sugarcane harvest cycles, squeezing contract manufacturing margins.
- Heat-stable encapsulation technical ceiling:Microencapsulation technologies struggle to consistently protect 10^9 to 10^11 CFU per gram through pelleting temperatures exceeding 85°C, limiting formulation flexibility.
- Chilean aquaculture regulatory friction:New environmental impact assessments in Patagonian farming zones are delaying enzyme and probiotic deployment permits for salmon operations.
Strategic Opportunities
- Chilean salmon aquaculture expansion:Seawater-adapted Bacillus strains are reaching commercial scale, opening the fastest-growing demand segment for specialized eubiotic formulations.
- Organic acid premium positioning:Brazilian exporters facing EU-aligned residue scrutiny can capture expanding margin pools through certified organic acid programs differentiated from commodity alternatives.
- Technical service bundling:Swiss-Brazilian formulation partnerships demonstrate how on-site microbiota monitoring and diet optimization can lock in multi-year integrator contracts.
Industry Challenges
- Microbiologist talent scarcity:Brazilian universities produce insufficient gut microbiome specialists for feed mill technical service teams, forcing reliance on European expatriate consultants.
- Third-party certification timeline compression:EU import buyer REACH-aligned contaminant thresholds require faster third-party validation cycles than local laboratories can currently deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Eubiotics Market |
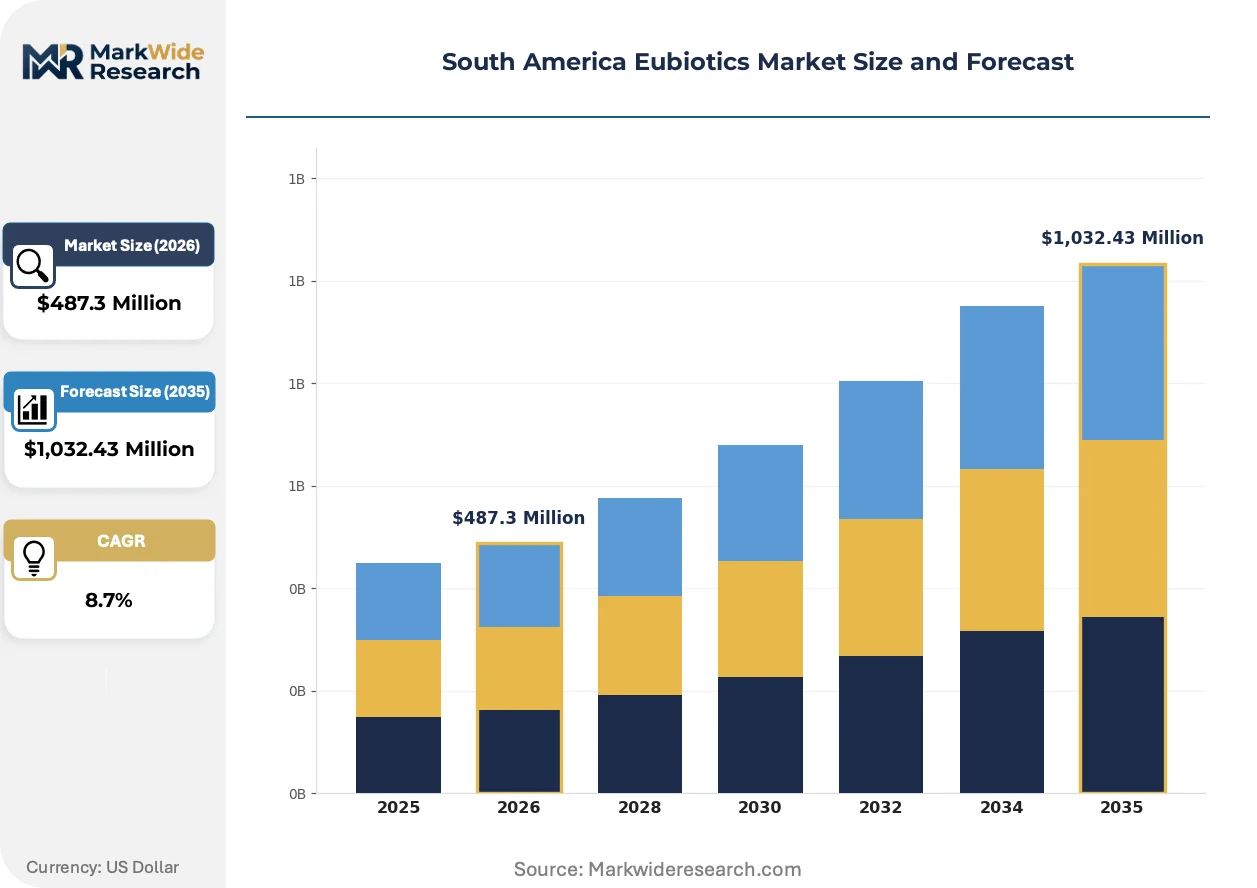
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Organic Acids, Enzymes Animal Type: Poultry, Swine, Ruminants, Aquaculture Formulation: Liquid, Powder, Granules, Tablets Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Alltech Inc, Kemin Industries Inc, BASF SE, Addcon, Chr. Hansen A/S, DSM-Firmenich, Cargill Inc, Novus International, Inc., Archer Daniels Midland Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Eubiotics Market Evolving Landscape
Live microbial delivery systems and regulatory compliance architectures are converging to reshape competitive positioning across Brazilian poultry and Chilean aquaculture supply chains.
Microencapsulation technology is unifying thermal protection with targeted intestinal release in next-generation probiotic formulations. Brazilian integrators adopting these systems report improved CFU survival through pelleting. The technology is unifying previously separate feed processing and additive manufacturing workflows, compressing supplier tiers.
ANVISA's coordination with MAPA on veterinary product registration timelines is accelerating formulation upgrade cycles. Manufacturers must now synchronize registration dossiers across both agencies simultaneously. Poultry feed mills in São Paulo and Paraná states are most affected, deploying dedicated regulatory affairs staff to manage parallel submissions.
Multi-source procurement for fermentation-derived actives is displacing traditional single-feed-mill supply contracts that dominated Brazilian poultry operations for decades. Large integrators now qualify three to five active suppliers per probiotic strain category. This pattern is most visible in vertically integrated operations across Brazil's southeastern production belt.
South America Eubiotics Market Segmentation
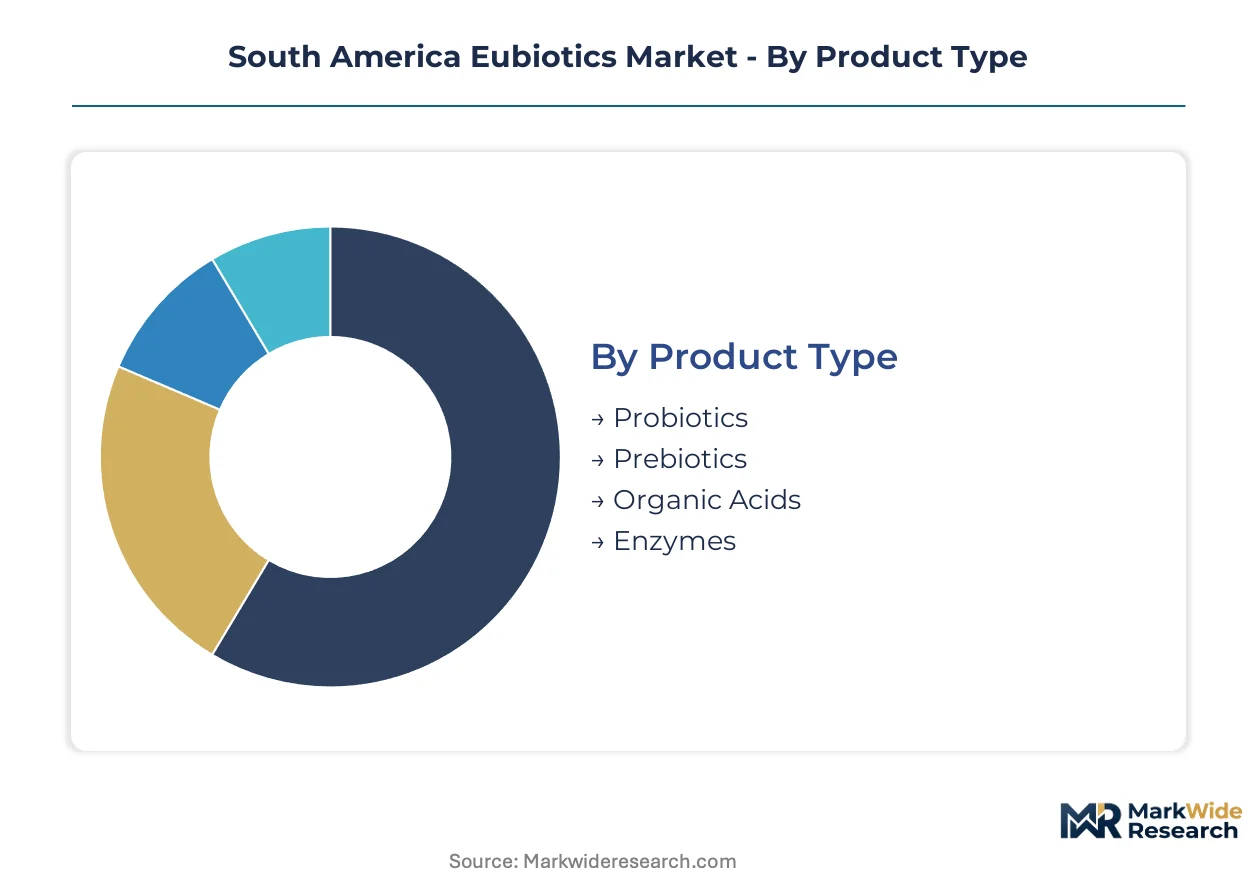
Eubiotic suppliers in South America must align formulation portfolios with distinct animal physiology requirements and feed processing constraints. Segmentation reveals where technical service investments yield contract stickiness versus commodity margin compression.
Product Type:
Volume concentrates in live microbial cultures, while premium margin pools accrue to residue-compliant acidifiers facing EU export scrutiny.
- Probiotics:Live microbial cultures containing 10^9 to 10^11 CFU per gram require microencapsulation to survive pelleting temperatures above 80°C. Brazilian poultry integrators in São Paulo and Paraná states concentrate demand here, driven by ANVISA's tightening veterinary drug residue standards that force antibiotic reduction without performance sacrifice.
- Organic Acids:Short-chain fatty acid formulations including formic, propionic, and butyric acids suppress pathogenic colonization while enhancing nutrient absorption. Exporters facing REACH-aligned contaminant thresholds from European buyers capture expanding margin pools through third-party certified programs differentiated from commodity alternatives.
- Prebiotics:Non-digestible oligosaccharides selectively stimulate beneficial gut microbiota proliferation.
- Enzymes:Targeted proteins breaking down anti-nutritional factors in feed substrates.
Today's leader: Probiotics. Tomorrow's challenger: Organic Acids.
Animal Type:
Application intensity varies sharply across species physiology and regulatory exposure.
- Poultry:Broiler and layer operations in Brazil's southeastern production belt generate the region's largest demand pull, with integrated operations consolidating procurement toward multi-source fermentation-derived active sourcing. Weight-gain trial data establishes probiotic efficacy benchmarks that lock in technical service relationships.
- Aquaculture:Chilean salmon farming in Patagonian zones represents the steepest expansion trajectory as seawater-adapted Bacillus strains reach commercial scale. New environmental impact assessments delay deployment permits but create first-mover advantages for compliant suppliers.
- Swine:Nursery and grower phase applications focus on post-weaning diarrhea prevention.
- Ruminants:Beef and dairy operations in Argentine Pampas deploy eubiotics for rumen fermentation modulation.
Poultry commands current volume. Aquaculture claims the fastest growth trajectory.
Formulation:
Physical form determines supply chain touchpoints and technical service requirements.
- Powder:Standardized particle size distributions compatible with existing feed mill mixing equipment dominate Brazilian distribution. São Paulo-based integrators prefer this format for seamless integration into pelleting workflows without process reconfiguration.
- Liquid:Post-pelleting spray applications preserve heat-sensitive actives, commanding premium positioning in specialized aquaculture and young animal nutrition segments where CFU survival rates dictate performance outcomes.
- Granules:Intermediate particle size for controlled release characteristics.
- Tablets:Compressed formats for on-farm water medication systems.
Powder leads in volume penetration. Liquid gains in premium applications.
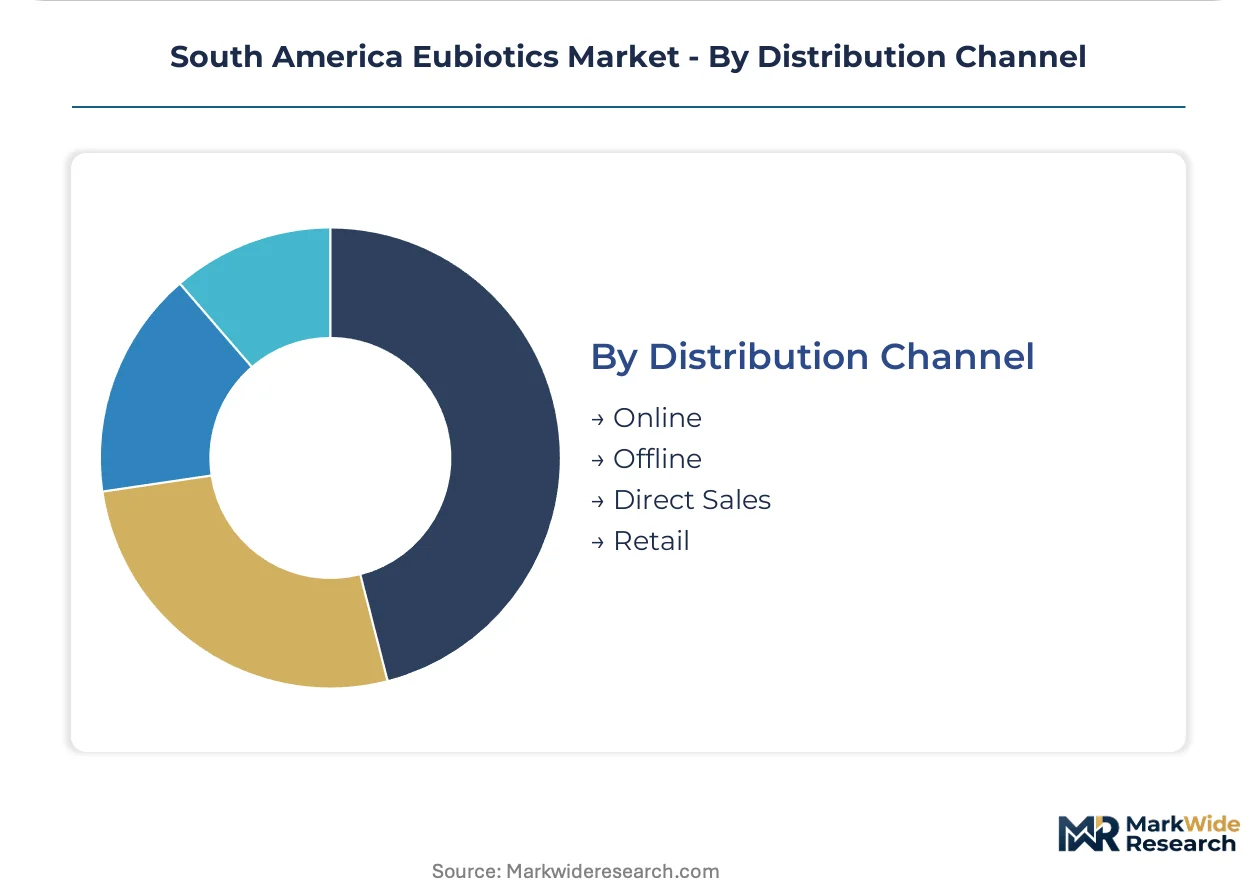
Distribution Channel:
Channel selection reflects customer scale and formulation complexity.
- Direct Sales:Large Brazilian poultry integrators negotiate multi-year contracts with embedded technical service components including on-site microbiota monitoring. DSM-Firmenich and Cargill anchor relationships through Swiss-Brazilian formulation partnerships and captive feed manufacturing networks respectively.
- Offline:Traditional distributor networks serving mid-scale operations across Argentina and Paraguay face margin compression as procurement consolidates toward multi-source qualification models.
- Online:Digital procurement platforms emerging for standardized commodity formulations.
- Retail:Farm supply stores targeting smallholder livestock producers.
Direct sales lock in strategic accounts. Offline channels defend regional coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography across South America as Brazilian cost-of-compliance advantages attract multinational formulation investments away from stricter European jurisdictions. ANVISA's accelerating registration timelines, though tightening residue standards, still outpace EMA procedural delays.
Brazil
Poultry integrators in São Paulo and Paraná states concentrate regional demand for heat-stable probiotic formulations. ANVISA coordinates veterinary product registrations with MAPA, compressing approval cycles for fermentation-derived actives. São Paulo-based feed manufacturing clusters are consolidating multi-source procurement contracts away from traditional single-mill dependencies.
Argentina
Beef and dairy operations in the Pampas region deploy rumen-modulating eubiotics to enhance feed conversion efficiency. The national agricultural secretariat enforces MERCOSUR-aligned feed additive standards that reduce cross-border formulation barriers with Brazil. Rosario and Buenos Aires provinces host the densest concentration of distributor networks serving mid-scale livestock producers.
Chile
Salmon aquaculture in Patagonian farming zones represents the steepest demand trajectory for seawater-adapted Bacillus strains. New environmental impact assessments delay enzyme and probiotic deployment permits but create first-mover advantages for compliant suppliers. Puerto Montt and Aysén regions anchor commercial-scale trials of specialized marine formulations.
Paraguay
Cattle finishing operations along the Brazilian border generate growing demand for organic acid programs. MERCOSUR harmonization enables Brazilian manufacturers to distribute certified formulations without redundant national registration. Ciudad del Este and Encarnación serve as logistics hubs for cross-border feed additive trade.
South America Eubiotics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aquaculture-specialized formulations and microencapsulation technology licensing. The vendor base stratifies across three archetypes: integrated nutrition conglomerates with captive feed manufacturing, dedicated fermentation specialists with strain-banking capabilities, and regional distributors pivoting toward technical service bundling. Dominant competitive moves include backward integration into fermentation capacity and multi-year formulation partnerships embedding on-site microbiota monitoring.
Among European-headquartered nutrition specialists, DSM-Firmenich and BASF SE exemplify the technical service-intensive archetype, leveraging Swiss-German formulation expertise to sustain integrator relationships. Cargill Inc anchors the integrated conglomerate tier through captive feed manufacturing networks across São Paulo and Paraná. These three occupy distinct competitive positions without overlapping core value propositions.
| Leading Market Players |
|---|
| Alltech Inc |
| Kemin Industries Inc |
| BASF SE |
| Addcon |
| Chr. Hansen A/S |
| DSM-Firmenich |
| Cargill Inc |
| Novus International, Inc. |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EU-aligned third-party validated eubiotics and commodity feed additives manifests in both margin structures and procurement configurations across Brazilian poultry operations. Premium organic acid programs command sustained price premiums through REACH-compliant residue documentation, while commodity probiotic formulations face margin compression as multi-source qualification displaces single-mill contracts.
Pricing Analysis
Distributor margin layers compress as large Brazilian integrators negotiate direct contracts with fermentation specialists, bypassing traditional 15-20 point markups. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ANVISA-MAPA dual-registered formulations capturing mid-tier positioning. Pricing pressure stems from glucose substrate cost volatility tied to Brazilian sugarcane harvest cycles, squeezing contract manufacturers. Mid-scale Argentine distributors exhibit highest price sensitivity, while Chilean salmon exporters show lowest sensitivity given performance-linked outcomes.
Supply Chain Analysis
Freight cost differentials between São Paulo-Paraná manufacturing clusters and Patagonian aquaculture zones distort regional formulation economics, favoring liquid post-pelleting applications over heat-stable powders for long-haul Chilean deliveries. Supply concentrates in Brazil, Argentina, and Switzerland, with DSM-Firmenich leveraging Swiss technical infrastructure for Brazilian integrator support. Raw material dependencies include fermentation-grade glucose, nitrogen substrates, and microencapsulation polymers. Single-source vulnerability persists for seawater-adapted Bacillus strains, where Chilean environmental permits delay qualified supplier expansion. Distribution runs through captive feed manufacturing networks for large integrators, with traditional distributors defending mid-scale coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ANVISA's faster registration timelines versus EMA procedural delays attract multinational formulation investments toward Brazilian cost-of-compliance advantages.
For Market Incumbents: Lock in multi-year technical service contracts embedding on-site microbiota monitoring before emerging fermentation specialists achieve strain-banking scale. Backward integration into captive glucose supply from Brazilian sugarcane processors defends margin position against substrate cost volatility threatening contract manufacturing economics. For New Entrants and Emerging Players: Begin with Chilean salmon aquaculture applications where environmental impact assessment delays have created qualified-supplier scarcity for seawater-adapted Bacillus formulations. Target Patagonian farming zones in Puerto Montt and Aysén regions, deploying liquid post-pelleting delivery systems that bypass heat-stability technical ceilings constraining powder competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where microbiologist talent scarcity meets expanding technical service requirements across Brazilian feed mill operations. Long-term viability favors acquisition targets with dual ANVISA-MAPA registration capabilities and existing Swiss-Brazilian formulation partnerships. Watch Chilean environmental permit issuance velocity as inflection indicator for aquaculture-specialized valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive glucose supply from Brazilian sugarcane processors insulates margin structures from harvest-cycle volatility. |
| Multi-Year Technical Service Partnerships | On-site microbiota monitoring contracts with São Paulo integrators create switching costs that lock out competitors. |
| Seawater-Adapted Strain Development | Patagonian aquaculture deployment permits for Bacillus formulations open fastest-growing demand segment in the region. |
| Dual Agency Registration Synchronization | Parallel ANVISA-MAPA submission capabilities accelerate market access versus competitors managing sequential approvals. |
| Microencapsulation Technology Licensing | Heat-stable delivery systems protecting 10^9 CFU through 85°C pelleting command formulation premiums from Brazilian integrators. |
Research Methodology
Bottom-up poultry and aquaculture feed additive modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with feed mill technical directors, regulatory affairs managers at ANVISA-registered manufacturers, procurement leads at Brazilian integrated poultry operations, and Chilean aquaculture environmental compliance officers combined with secondary validation from MAPA veterinary product registries, MERCOSUR trade harmonization documentation, and EU REACH contaminant threshold notifications. Triangulation across stakeholder inputs and documentary sources ensures cross-verified demand and supply estimates.
Historical probiotic and organic acid adoption trendlines across Brazilian broiler operations and Chilean salmon farming zones inform projection frameworks. Segmentation dimensions modeled include product type, animal species, physical formulation, and distribution channel complexity, with regulatory compliance tier as an industry-specific overlay. CAGRs derive from fitted growth curves reconciled against capacity expansion announcements and input cost trajectory assumptions. Forecast inputs incorporate ANVISA registration velocity indices and Patagonian environmental permit issuance patterns.
Caveats apply where ANVISA residue standard acceleration or Chilean aquaculture regulatory friction could materially shift the outlook for premium formulation demand. Forecasts reflect assumptions about MERCOSUR harmonization continuity and EU import buyer certification requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Cattle Nutrition Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Natural Feed Additive Market