
 Nutritional Ingredients in Animal Feed Market | 2026-2036
Nutritional Ingredients in Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Ingredients in Animal Feed Market Outlook
Plant-based protein concentrates are pivoting toward soybean meal alternatives as insect meal and single-cell proteins gain commercial traction. Cargill leverages its oilseed processing network to secure consistent supply chains for amino acid precursors. BASF SE anchors European production of synthetic vitamins through its Ludwigshafen complex. DSM differentiates via its precision nutrition platforms targeting monogastric species.
Nutritional ingredients in animal feed comprise vitamins, amino acids, minerals, and enzymes formulated to meet species-specific dietary requirements, typically specified by crude protein percentage, metabolizable energy content, and digestible lysine levels. These inputs optimize growth rates, reproductive performance, and disease resistance across livestock and aquaculture operations. Amino acids command the largest value share within ingredient types due to their irreplaceable role in protein synthesis and the cost efficiency of industrial fermentation production. Aquaculture represents the fastest-expanding animal type segment as salmon and shrimp producers intensify stocking densities. Feed manufacturers consolidate procurement of vitamin premixes to secure volume discounts and technical support services.
The EU Green Deal's Farm to Fork strategy, enforced by EFSA and national veterinary authorities, mandates reduced antibiotic use and drives demand for gut health additives. FDA's Veterinary Feed Directive in the United States requires veterinary oversight for medically important antimicrobials, reshaping formulation strategies for medicated feeds. China's Ministry of Agriculture and Rural Affairs enforces feed quality standards through GB specifications and promotes domestic amino acid capacity under food security directives. Stakeholders must track regulatory divergence between jurisdictions to align product portfolios with compliance timelines and certification requirements.
Market Dynamics
Antibiotic phase-out mandates across major livestock-producing jurisdictions are forcing feed manufacturers to reformulate around gut health additives and functional amino acids, compressing formulation timelines and supplier qualification windows.
Growth Catalysts
- EU Green Deal enforcement:EFSA and national veterinary authorities are tightening residue limits on antibiotic growth promoters, accelerating demand for enzyme-based digestibility enhancers in swine and poultry operations.
- Aquaculture intensification:Salmon and shrimp producers in Vietnam and Norway are expanding recirculating aquaculture systems that require precision-formulated micronutrient premixes to maintain health at high stocking densities.
- Fermentation capacity expansion:Industrial amino acid production via microbial fermentation is achieving cost parity with extraction-based methods, pulling substitution demand from soybean meal in monogastric feeds.
Market Restraints
- Feed-grade vitamin concentration:Three chemical conglomerates control over 70% of global synthetic vitamin A and E capacity, creating supply vulnerability when any single Ludwigshafen or Shanghai complex experiences outage.
- Trace mineral price volatility:Zinc and copper sulfate prices fluctuate with smelter output from Peruvian and Chilean mining operations, squeezing premix margin predictability.
- Regulatory divergence friction:FDA's Veterinary Feed Directive imposes veterinary oversight requirements that lack equivalence with EU medicated feed prescriptions, complicating multinational formulation portfolios.
Strategic Opportunities
- Insect protein regulatory opening:EFSA novel food approvals for black soldier fly meal in poultry and aquaculture feeds create first-mover positioning for defatted larvae processors targeting premium pet food and salmonid sectors.
- Precision nutrition platforms:Real-time feed intake monitoring combined with NIR spectroscopy enables dynamic ration adjustment, opening subscription-based nutrition advisory services for integrated pork producers.
- Brazilian southern poultry belt consolidation:Santa Catarina and Rio Grande do Sul integrators are centralizing amino acid premix procurement, creating volume aggregation points for suppliers with technical service capabilities.
Industry Challenges
- Formulation talent scarcity:Veterinary nutritionists with species-specific digestibility modeling expertise command premium compensation, constraining mid-tier feed compounder expansion.
- Multi-jurisdiction certification complexity:Organic feed additive producers must maintain separate FAMI-QS, GMP+, and regional organic accreditations, extending product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Ingredients in Animal Feed Market |
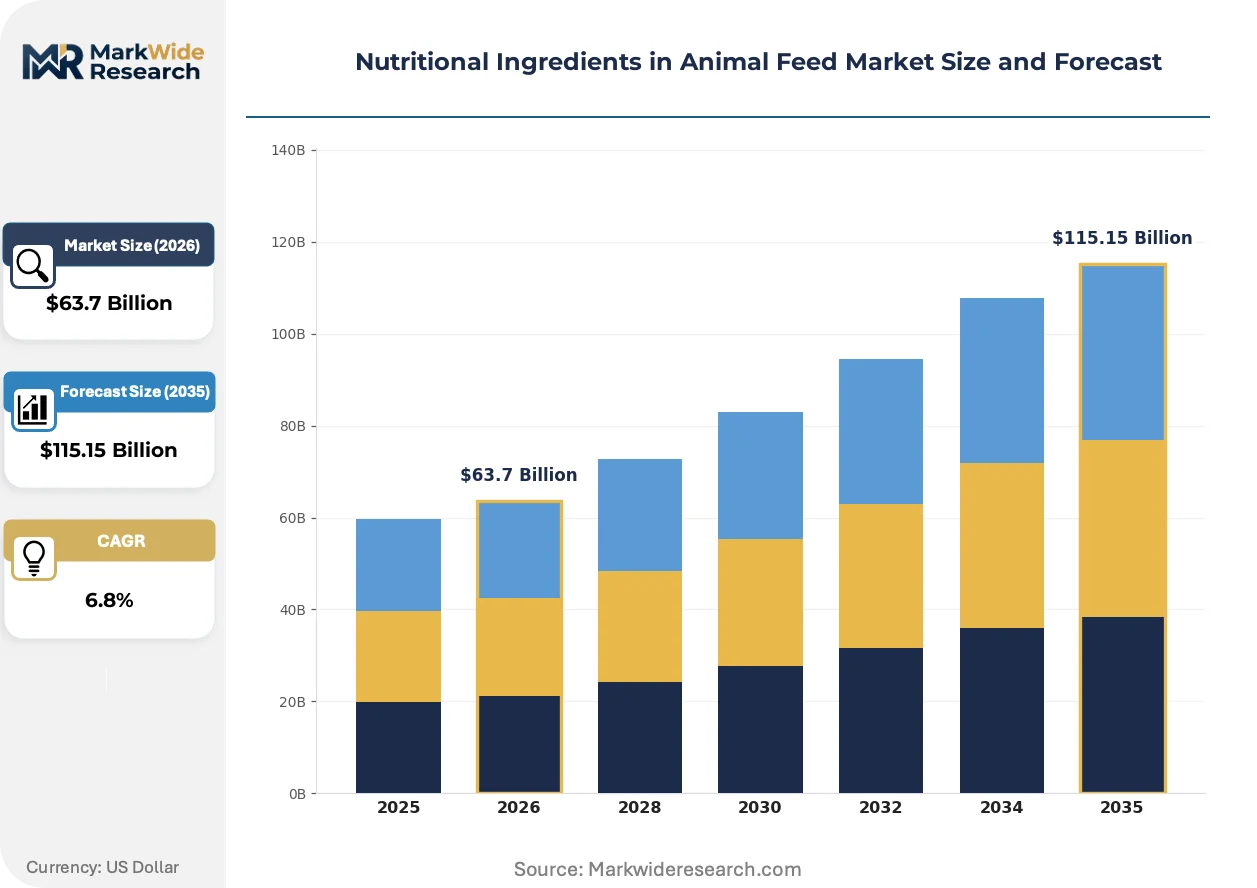
| Market Size in 2026 | $63.7 Billion |
| Market Size in 2035 | $115.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Vitamins, Amino Acids, Minerals, Enzymes Animal Type: Cattle, Poultry, Swine, Aquaculture Formulation Type: Complete Feed, Concentrates, Supplements, Medicated Feed End User: Commercial Farms, Feed Manufacturers, Poultry Farms, Livestock Producers |
| Companies Covered | Cargill, BASF SE, DSM, Archer Daniels Midland, Evonik Industries, Ingredion Inc, Barentz, Nutreco, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Ingredients in Animal Feed Market Strategic Shifts
Bioprocessing advances and digitized ration formulation are compressing the gap between research-scale nutritional discovery and commercial feed mill deployment, reshaping how ingredient suppliers demonstrate value beyond commodity pricing.
Single-cell protein production from methanotrophic bacteria is modularizing the upstream supply of high-quality protein concentrate for aquaculture and pet food applications. Norwegian salmon feed manufacturers are piloting 10,000-tonne annual capacity facilities that co-locate with industrial CO2 emitters. This distributed production model is modularizing what has historically been a centralized soybean crushing infrastructure, reducing transoceanic shipping exposure for protein sourcing.
China's GB standards for feed quality and safety are tightening maximum allowable limits for mycotoxins and heavy metals in mineral premixes. The Ministry of Agriculture and Rural Affairs is conducting unannounced inspections of amino acid fermentation facilities, disqualifying non-compliant producers from government procurement programs. Domestic compounders are responding by consolidating supplier relationships with state-affiliated chemical groups that maintain dedicated regulatory compliance teams.
Integrated poultry and pork producers are unbundling nutrition advisory from ingredient supply, contracting independent consulting veterinarians to design phase-feeding programs while sourcing amino acids and enzymes through spot-market tenders. This separation of technical specification from procurement execution is most visible in Brazil's southern belt, where large integrators maintain in-house formulation laboratories while disintermediating traditional premix distributors for base ingredient purchasing.
Nutritional Ingredients in Animal Feed Market Segmentation
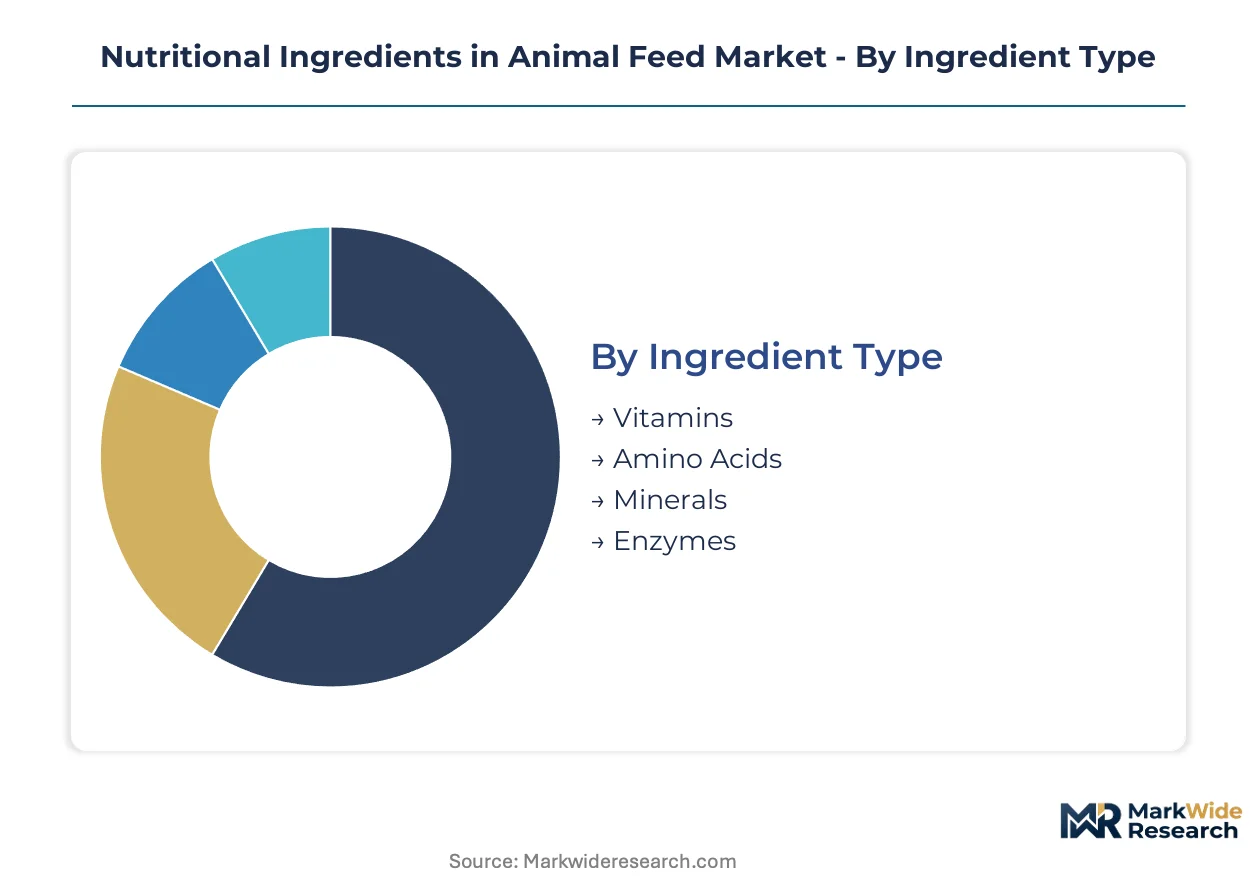
Ingredient suppliers configure product portfolios around species-specific metabolic requirements and regulatory constraints on antibiotic use. Segmentation reveals where formulation complexity concentrates and which customer channels command technical service investment.
Ingredient Type:
Specification hierarchies differentiate commodity inputs from precision-formulated additives requiring fermentation or synthetic chemistry capabilities.
- Amino Acids:Industrial fermentation produces lysine, methionine, and threonine with standardized purity grades for protein synthesis optimization. Demand concentrates in Brazil's southern poultry belt around Santa Catarina, driven by integrators consolidating premix procurement for phase-feeding programs.
- Enzymes:Phytases and carbohydrases enhance digestibility in monogastric species, reducing phosphorus excretion and feed conversion ratios. Vietnam's expanding aquaculture operations are accelerating enzyme-enhanced feed adoption to maintain health at intensified stocking densities.
- Vitamins:Synthetic fat-soluble and water-soluble micronutrients formulated to prevent deficiency disorders in high-production livestock systems.
- Minerals:Inorganic and organic trace element complexes supporting bone development, enzyme cofactor function, and reproductive performance.
Mature deployment sits with vitamins and minerals. Newer deployment is concentrated in enzymes and crystalline amino acids.
Animal Type:
Volume concentration and margin structure vary sharply across species based on production intensity and regulatory scrutiny of growth promoters.
- Poultry:Broiler and layer operations consume the largest amino acid volumes due to rapid protein deposition requirements and short production cycles. Santa Catarina and Rio Grande do Sul integrators centralize premix procurement, creating aggregation points for suppliers with technical service capabilities.
- Aquaculture:Salmon and shrimp producers require precision-formulated micronutrient premixes for recirculating systems. Norway and Vietnam are expanding recirculating aquaculture capacity, pulling demand for species-specific vitamin and mineral formulations.
- Swine:Phase-feeding programs optimize lysine-to-energy ratios across growth stages, with EU antibiotic restrictions driving gut health additive incorporation.
- Cattle:Ruminant formulations emphasize bypass protein and rumen-protected amino acids for dairy and beef finishing operations.
Volume leadership remains with poultry. Steepest expansion trajectory belongs to aquaculture.
Formulation Type:
Customer integration level determines whether suppliers deliver bulk commodities, concentrated intermediates, or finished medicated products requiring regulatory compliance infrastructure.
- Complete Feed:Fully formulated rations ready for direct consumption, manufactured by integrated producers and commercial mills with in-house formulation laboratories.
- Concentrates:Protein, vitamin, and mineral premixes requiring dilution with local grain sources, favored by mid-sized livestock operations.
- Supplements:Targeted additives addressing specific deficiencies or performance optimization, often procured through spot-market tenders separate from nutrition advisory services.
- Medicated Feed:Veterinary-supervised formulations incorporating approved therapeutics, subject to FDA Veterinary Feed Directive oversight in the United States and EFSA residue limits in Europe.
Procurement consolidation favors complete feed among large integrators. Concentrates and supplements retain relevance for independent producers seeking flexibility.
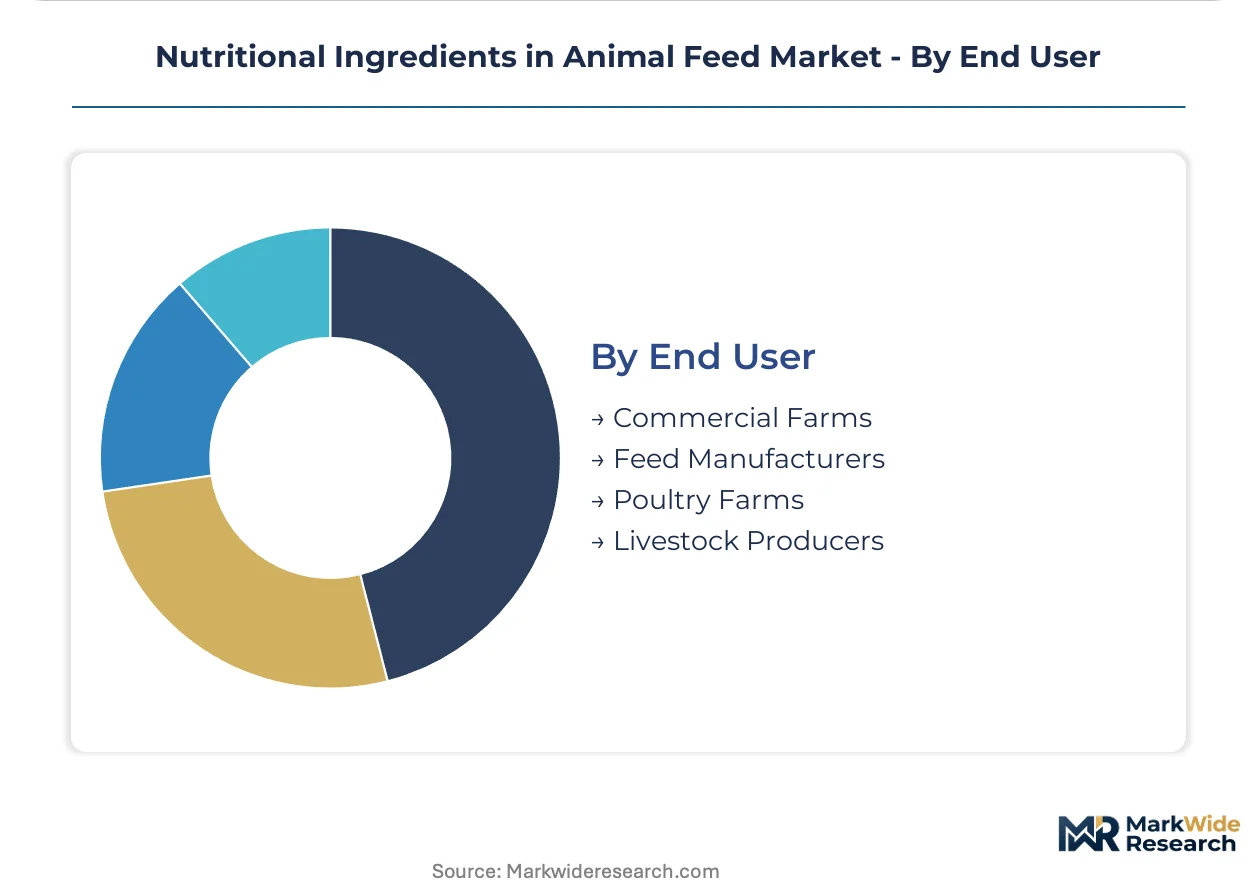
End User:
Channel structure separates vertically integrated operations with captive formulation expertise from external compounders dependent on supplier technical support.
- Feed Manufacturers:Commercial mills producing branded and private-label feeds for distribution to independent livestock operations, consolidating vitamin premix procurement for volume discounts.
- Commercial Farms:Large-scale poultry, pork, and dairy operations with in-house nutritionists designing phase-feeding programs while sourcing base ingredients through competitive tenders.
- Livestock Producers:Cattle ranchers and smaller swine operations relying on dealer networks for complete feed and nutritional advisory services.
- Poultry Farms:Layer and broiler operations with species-specific requirements for calcium, phosphorus, and amino acid density across production cycles.
Technical specification authority concentrates with commercial farms and feed manufacturers. Smaller livestock producers and poultry farms depend on distributor-led advisory models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Dinh Vu Economic Zone and adjacent industrial parks are attracting amino acid fermentation facilities seeking proximity to Mekong Delta aquaculture operations and preferential corporate tax rates.
United States
Poultry integrators in the Southeast are consolidating vitamin premix procurement under long-term supply agreements. FDA's Veterinary Feed Directive mandates veterinary oversight for medically important antimicrobials, reshaping formulation strategies for medicated feeds. Iowa and North Carolina feed mills are expanding in-house formulation laboratories to bypass traditional premix distributors.
China
State-affiliated chemical groups are consolidating amino acid fermentation capacity under food security directives. The Ministry of Agriculture and Rural Affairs enforces GB standards for mycotoxin limits through unannounced facility inspections. Shandong Province and Jiangsu Province house the dominant lysine and threonine production clusters serving domestic compounders.
Brazil
Santa Catarina and Rio Grande do Sul integrators are centralizing amino acid premix procurement for phase-feeding programs. ANVISA maintains residue monitoring protocols aligned with EU export requirements. The southern poultry belt is disintermediating traditional distributors through direct spot-market tenders for base ingredients.
Germany
Industrial biotechnology specialists are expanding precision nutrition platforms targeting monogastric species. EFSA novel food approvals under EU Green Deal enforcement are accelerating gut health additive adoption. The Ludwigshafen chemical complex anchors European synthetic vitamin production for feed-grade applications.
Vietnam
Mekong Delta aquaculture operations are intensifying stocking densities in recirculating systems. The Ministry of Agriculture and Rural Development promotes enzyme-enhanced feeds through technical extension programs. Can Tho and An Giang provinces are emerging as concentration points for shrimp feed micronutrient formulation.
Nutritional Ingredients in Animal Feed Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fermentation-based amino acid producers commanding pricing power in concentrated supply chains. Three chemical conglomerates control the majority of global synthetic vitamin capacity, creating tiered supply security premiums. Strategic archetypes include integrated oilseed processors with captive amino acid precursor networks, precision nutrition platform developers, and regional premix formulators with technical service capabilities. Dominant competitive moves involve backward integration into fermentation capacity and geographic expansion through distributor acquisition.
Among diversified agribusiness conglomerates, Cargill leverages its oilseed processing infrastructure to secure amino acid precursor supply chains. BASF SE anchors European production through its Ludwigshafen manufacturing complex. DSM occupies a position within the precision nutrition tier through species-specific formulation platforms. These three exemplify how scale and integration depth determine competitive positioning in ingredient supply.
| Leading Market Players |
|---|
| Cargill |
| BASF SE |
| DSM |
| Archer Daniels Midland |
| Evonik Industries |
| Ingredion Inc |
| Barentz |
| Nutreco |
| Kemin Industries |
| Others |
Value Chain & Pricing Dynamics
Fermentation-grade corn and natural gas feedstock costs cascade through amino acid pricing tiers, with Brazilian integrators in Santa Catarina and Rio Grande do Sul capturing volume discounts through consolidated procurement while smaller Vietnamese aquaculture operators absorb spot-market premiums for enzyme-enhanced formulations.
Pricing Analysis
Short lead-time premiums concentrate with spot-market buyers in Vietnam's Mekong Delta shrimp operations, while contract-based long-term offtake agreements dominate Brazil's southern poultry belt procurement. Three-tier pricing structure across premium, standard, and economy levels separates FAMI-QS certified organic additives from conventional mineral premixes and unbranded commodity imports. Cost compression in synthetic vitamin A and E is intensifying because three chemical conglomerates control Ludwigshafen and Shanghai production complexes. Mid-tier feed compounders exhibit highest price sensitivity, lacking volume scale to secure technical service bundles.
Supply Chain Analysis
Direct-to-feed-manufacturer channels handle large integrator demand in Brazil and the United States, while distributor-led networks serve smaller livestock producers across Vietnam and Germany. Supply concentrates in China for amino acid fermentation, Germany for synthetic vitamin synthesis, and Vietnam for aquaculture micronutrient formulation. Raw material dependencies include Peruvian copper sulfate, Brazilian soybean meal, and natural gas feedstock for methanotrophic protein production. Single-source vulnerability sits with Ludwigshafen vitamin A capacity. Distribution runs through regional premix formulators with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision nutrition platforms are displacing static formulation models, with real-time feed intake monitoring and NIR spectroscopy enabling dynamic ration adjustment that legacy premix distributors cannot replicate.
For Market Incumbents: Anchor fermentation capacity expansion in Vietnam's Dinh Vu Economic Zone to secure proximity to Mekong Delta aquaculture demand and preferential tax treatment. Defend margin position by backward integration into oilseed processing networks for amino acid precursor security, while investing in FAMI-QS and GMP+ certification infrastructure to extend product launch timelines for organic feed additive competitors.
For New Entrants and Emerging Players: Capture EFSA novel food approval positioning for black soldier fly meal in poultry and aquaculture feeds, where regulatory opening creates first-mover advantage before established vitamin producers pivot. Target Norway's salmon recirculating aquaculture systems with species-specific micronutrient premixes, leveraging technical extension partnerships with the Ministry of Agriculture and Rural Development as the primary go-to-market channel.
For Investors and Strategic Acquirers: EFSA enforcement of reduced antibiotic residue limits under EU Green Deal implementation is the leading indicator that gut health additive demand will structurally displace traditional growth promoter formulations. Long-term viability over the next decade rests on precision nutrition platform developers with captive fermentation capacity and regulatory compliance infrastructure. Acquisition focus should center on regional premix formulators with technical service capabilities in Brazil's southern belt. The signal to monitor is unannounced GB standard inspections by China's Ministry of Agriculture and Rural Affairs disqualifying non-compliant amino acid producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Industrial amino acid production via microbial fermentation achieves cost parity with extraction methods, pulling substitution from soybean meal. |
| Backward Integration into Oilseed Processing | Cargill leverages captive precursor networks to secure consistent supply chains for lysine and methionine production. |
| Precision Nutrition Platform Development | DSM differentiates through species-specific formulation targeting monogastric digestibility modeling for integrated pork producers. |
| Regulatory Certification Investment | FAMI-QS and GMP+ accreditation extends organic feed additive launch timelines by 8-14 months, creating defensive moats. |
| Geographic Distributor Acquisition | Consolidation of technical service capabilities in Santa Catarina and Rio Grande do Sul captures volume aggregation points. |
Study Parameters
Document review covered EFSA residue limit enforcement records, FDA Veterinary Feed Directive implementation guidance, and China's GB standard inspection reports, complemented by interviews with feed mill procurement directors, veterinary nutritionists at integrated poultry operations, amino acid fermentation plant managers, and aquaculture extension officers. Secondary validation drew from customs trade data, SEC filings of diversified agribusiness conglomerates, and Ministry of Agriculture and Rural Affairs procurement program disclosures. Bottom-up volume aggregation across ingredient types, animal species, and formulation tiers was cross-referenced with top-down market sizing from production capacity analysis.
Historical growth trajectories were benchmarked against panel input from industry stakeholders to derive expansion rates across the projection horizon. Segmentation dimensions modeled include ingredient type hierarchy, animal species metabolic requirements, formulation integration level, and end-user channel structure. CAGRs were computed from annualized growth patterns adjusted for regulatory phase-out timelines and technology substitution curves. Industry-specific forecast inputs incorporated antibiotic restriction enforcement schedules and recirculating aquaculture system deployment rates in Vietnam and Norway.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel food approval timelines for insect protein, trace mineral price volatility from Peruvian smelter output, and divergence between FDA Veterinary Feed Directive and EU medicated feed prescription requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Feed Supplements Market